
 Plastic Stabilizer Market | 2026-2036
Plastic Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Stabilizer Market Outlook
Specialized polymer chemist availability is redrawing competitive boundaries in plastic stabilizer development. BASF leverages its integrated antioxidants portfolio to anchor supply relationships with European automotive tier ones. SONGWON Industrial Group dominates Asian UV stabilizer production through captive intermediate supply. Baerlocher GmbH specializes in calcium-zinc heat stabilizer systems, positioning its portfolio for regulatory transitions away from lead and cadmium formulations.
Plastic stabilizers are chemical additives—typically organometallic compounds, hindered amine light stabilizers (HALS), or phenolic antioxidants—blended at 0.1% to 3.0% loadings to inhibit thermal oxidation, UV degradation, or chain scission in thermoplastics and thermosets. Their primary purpose is extending service life and maintaining mechanical properties in polymers exposed to heat, light, or shear during processing. Heat stabilizers lead volume demand due to PVC's inherent thermal sensitivity during extrusion and injection molding, while UV stabilizers represent the fastest-expanding margin pool as outdoor construction and agricultural film applications intensify. Antioxidants command stable positions in polyolefin packaging where melt-processing protection determines recyclate quality.
REACH restrictions on cadmium and lead compounds, RoHS substance limits, and EPA chemical risk evaluations under TSCA are reshaping formulation roadmaps and raw material qualification timelines across the value chain. ECHA's SVHC candidate list expansions are forcing additive suppliers to document substitution pathways for legacy metal soaps. Stakeholders must monitor regulatory divergence between European hazard-based approaches and China's GB standard harmonization to anticipate reformulation costs and regional product registration requirements.
Market Dynamics
Regulatory phase-outs of heavy-metal heat stabilizers are forcing simultaneous reformulation across PVC extrusion, wire coating, and pipe manufacturing lines. REACH SVHC expansions and China's GB standard tightening have compressed qualification timelines from 18 months to under 9 months.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany and Japan specify high-performance stabilizer packages for under-hood thermoplastics, pulling demand for calcium-zinc and organotin systems.
- REACH substitution deadlines:ECHA's cadmium and lead compound restrictions accelerate migration to metal-free heat stabilizers across European PVC processors.
- Agricultural film intensity:China's greenhouse sector expands UV stabilizer consumption for 3-5 season mulch films, outpacing construction film demand growth.
Market Restraints
- Epichlorohydrin cost volatility:Epoxy-based stabilizer intermediates face feedstock price swings tied to propylene and chlorine supply tightness.
- Asian intermediate concentration:Captive production of hindered amine light stabilizer precursors concentrates in Zhejiang and Jiangsu provinces, creating single-source vulnerability.
- Metal soap performance ceiling:Calcium-zinc systems struggle to match lead-based thermal stability in high-shear PVC pipe extrusion above 200°C.
Strategic Opportunities
- Indian compounding scale-up:Gujarat and Maharashtra polymer hubs lack qualified local stabilizer blending, creating import substitution openings.
- Recyclate quality premiums:Polyolefin packaging recyclers pay stabilizer cost-plus for antioxidant packages that protect melt-index through multiple reprocessing cycles.
- EU Green Deal chemistry incentives:Horizon Europe funding streams favor bio-based stabilizer backbone development from tall oil fatty acids.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise spanning organometallic synthesis and polymer rheology concentrates among retiring technical staff at European and Japanese suppliers.
- Multi-jurisdiction registration burden:Simultaneous EPA PMN filings, REACH dossier updates, and China MEE new chemical notifications stretch regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Stabilizer Market |
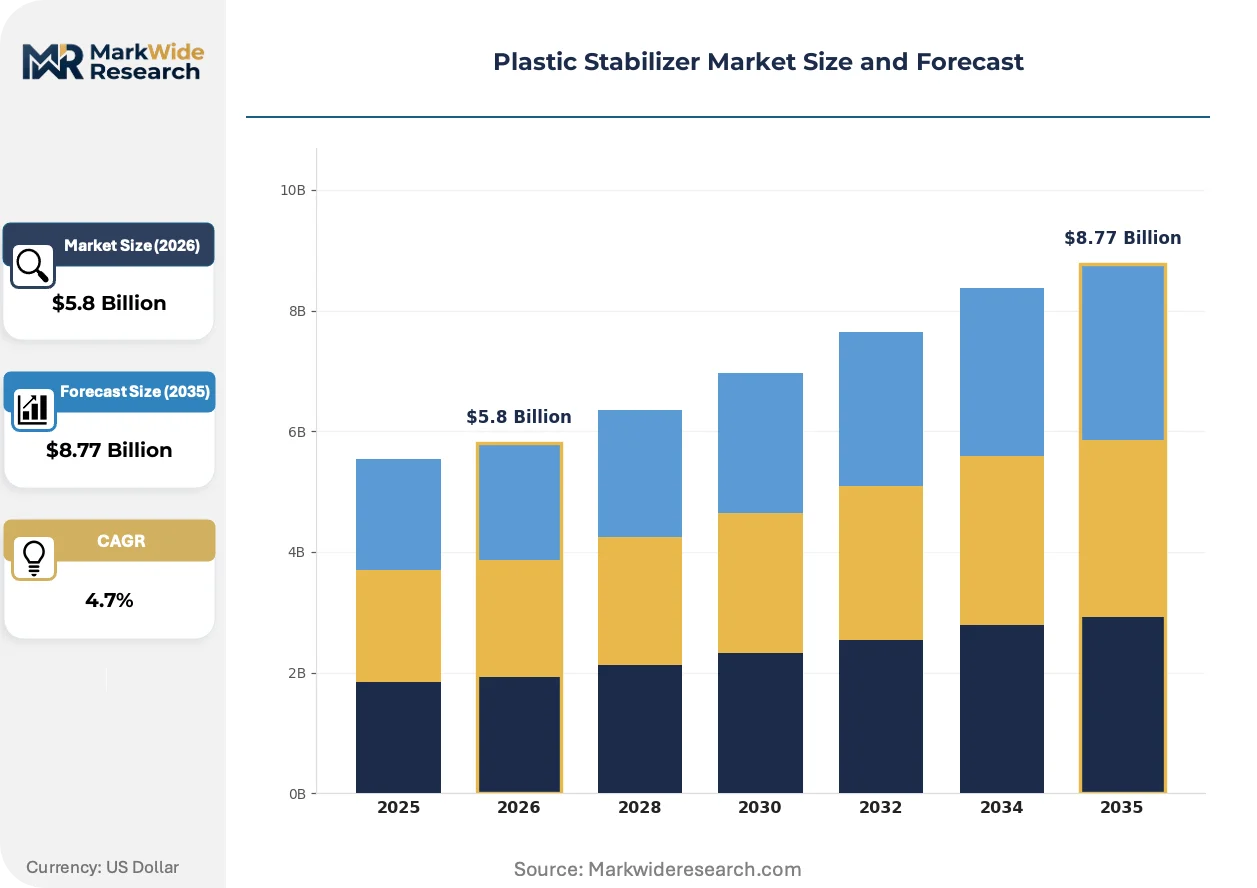
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Stabilizers, UV Stabilizers, Antioxidants, Light Stabilizers Application: Packaging, Automotive, Construction, Consumer Goods Form: Granules, Liquid, Powder, Masterbatch End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | SONGWON Industrial Group, Baerlocher GmbH, BASF, Solvay, LANXESS, Clariant, Adeka Corporation, ALTANA, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Stabilizer Market Strategic Shifts
Stabilizer technology development is splitting along performance-versus-sustainability axes. Suppliers now maintain parallel formulation tracks: one optimizing for extreme processing conditions, another eliminating residual metal content entirely.
Hybrid calcium-zinc/organophosphite heat stabilizer systems are bifurcating the PVC pipe sector. Tier one extruders in Germany and the US specify these packages for potable water pressure pipe, while commodity processors in Turkey and Egypt retain legacy lead systems. The technology is compressing margin pools for mid-tier metal soap suppliers unable to fund dual-track R&D.
EU F-Gas Regulation amendments and REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of fluoropolymer processing aids co-packed with stabilizers. Wire and cable compounders face 12-18 month requalification cycles for insulation grades. The medical device segment accelerates adoption of documented metal-free stabilizer certificates to preempt MDR substance disclosure requirements.
Long-term supply agreements are displacing spot purchasing in polyolefin antioxidant procurement. Large European packaging converters now contract 3-5 year antioxidant volumes with price collars tied to propylene indices. The shift concentrates purchasing leverage among top five film producers, squeezing regional compounders in Poland and Spain into distributor-tier supply relationships.
Plastic Stabilizer Market Segmentation
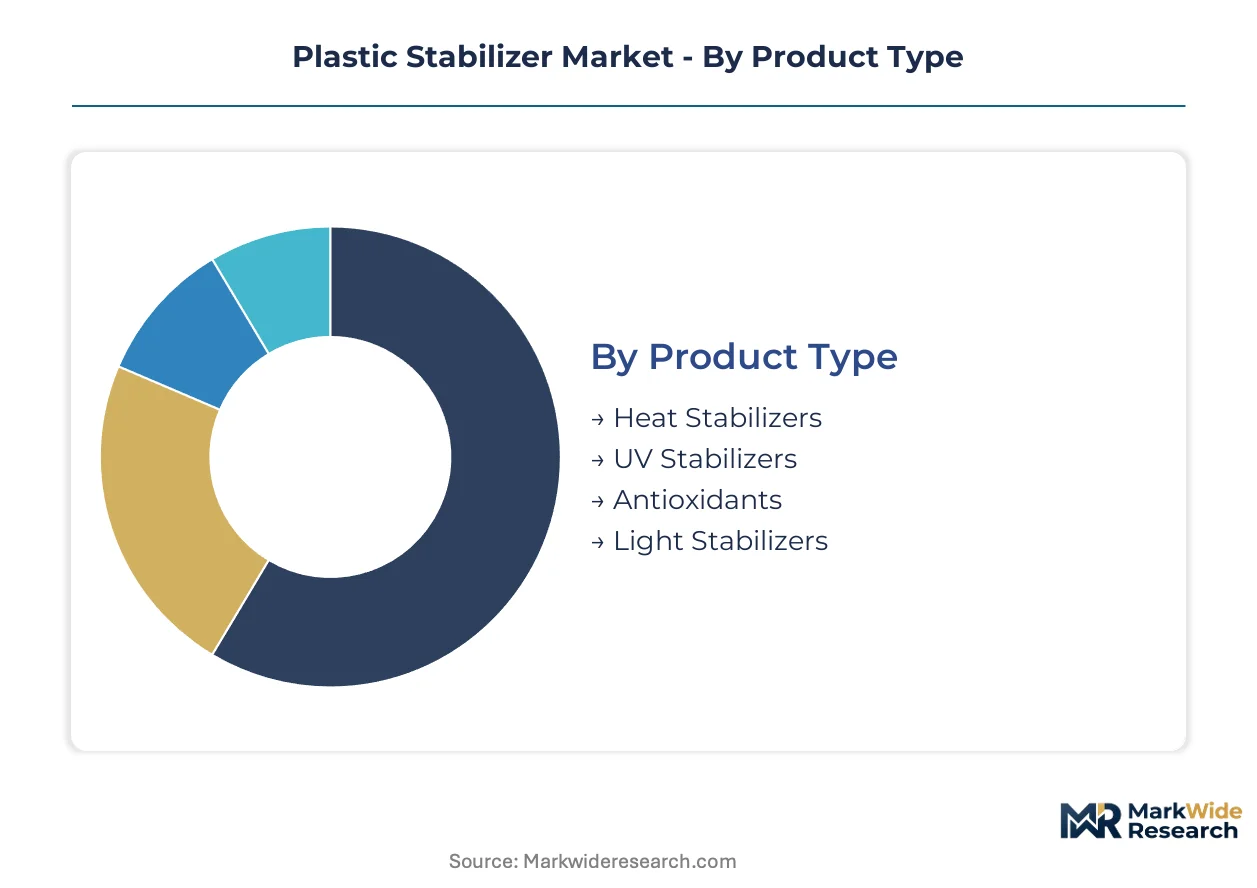
Plastic stabilizer procurement channels diverge sharply by segment. Heat stabilizers move through direct mill supply agreements, while UV stabilizers and antioxidants distribute through regional compounder networks. Understanding these channel dynamics reveals where pricing power concentrates and where substitution threats emerge.
Product Type:
Channel mix varies dramatically across stabilizer chemistries. Heat stabilizers flow primarily through direct technical sales to PVC processors, while UV stabilizers and antioxidants reach end-users via distributor and masterbatch compounder networks.
- Heat Stabilizers:Organometallic compounds—calcium-zinc, organotin, and barium-zinc systems—protect PVC during high-temperature extrusion and injection molding. Demand concentrates in China and Germany, where pipe and profile extruders face compressed qualification timelines under REACH SVHC expansions and tightening GB standards.
- UV Stabilizers:Hindered amine light stabilizers (HALS) and benzotriazole absorbers prevent photodegradation in outdoor applications. China's greenhouse agriculture sector pulls disproportionate volume for multi-season mulch films, outpacing construction film demand expansion.
- Antioxidants:Phenolic and phosphite variants shield polyolefins from thermal oxidation during melt processing. European packaging converters now contract 3-5 year volumes directly with additive suppliers, bypassing traditional distributor tiers.
- Light Stabilizers:UV absorbers and quenchers extend service life in transparent and colored thermoplastics. Automotive glazing and polycarbonate sheet applications in Japan and South Korea drive specification-grade demand.
By volume, heat stabilizers lead. By growth pace, UV stabilizers are expanding most quickly.
Application:
Cost tier segmentation separates specification-grade automotive and medical applications from commodity packaging and construction volumes. Premium tiers demand documented regulatory compliance and long-term supply assurance.
- Packaging:Polyolefin film and rigid container processors consume antioxidant packages to protect recyclate quality through multiple reprocessing cycles. European converters pay stabilizer cost-plus for melt-index preservation.
- Automotive:Under-hood thermoplastics require high-performance stabilizer systems meeting OEM thermal aging specifications. German and Japanese tier ones specify calcium-zinc and organotin packages for lightweighting programs.
- Construction:PVC pipe, siding, and window profiles drive heat stabilizer consumption. German and US potable water pressure pipe extruders specify hybrid calcium-zinc/organophosphite systems, while Turkish and Egyptian commodity processors retain legacy lead formulations.
- Consumer Goods:Durable appliances and electronics housings need balanced thermal and UV protection. Medical device manufacturers accelerate metal-free stabilizer adoption to preempt EU MDR substance disclosure requirements.
Construction generates the largest absolute volume. Automotive commands the steepest price premiums and tightest qualification standards.
Form:
Supply concentration shapes form selection. Captive granule and masterbatch production at large compounders displaces powder and liquid purchases among scaled processors.
- Granules:Dust-free handling and precise dosing favor automated extrusion lines. Major PVC pipe producers in China and Germany specify granule delivery to minimize workplace exposure compliance costs.
- Liquid:Pumpable systems suit continuous compounding operations and liquid color concentrate integration. Flexible PVC calendering operations in Italy and Spain prefer liquid stabilizer delivery.
- Powder:Lowest unit cost form serves small-batch compounders and developing market processors. Indian PVC profile manufacturers in Gujarat and Maharashtra rely on powder imports due to limited local blending capacity.
- Masterbatch:Pre-dispersed concentrates reduce processor capital equipment needs. European automotive tier ones specify masterbatch supply to ensure lot-to-lot consistency in critical under-hood components.
Granules dominate volume in regulated markets. Masterbatch claims the fastest share gains in automotive specification channels.
End User:
Customer type determines contract structure. Manufacturers secure long-term supply agreements, while distributors and wholesalers carry inventory risk for spot purchasers.
- Manufacturers:PVC processors, polymer compounders, and film extruders purchase direct at volume. Large European packaging producers now contract 3-5 year antioxidant volumes with price collars tied to propylene indices.
- Retailers:Limited role in stabilizer distribution due to technical specification requirements. Specialty chemical retailers in India serve small-scale processors lacking direct supplier relationships.
- Wholesalers:Regional inventory holders buffer supply volatility for mid-tier compounders. Polish and Spanish film producers increasingly rely on distributor-tier supply as large converters concentrate purchasing leverage.
- Distributors:Technical service and just-in-time delivery differentiate value-added distributors. Asian UV stabilizer precursors concentrate in Zhejiang and Jiangsu provinces, creating single-source vulnerability that distributors attempt to mitigate through safety stock positioning.
Manufacturers transact the largest volumes. Distributors are gaining share fastest among mid-tier processors seeking technical support and inventory flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards and MEE notifications anchor China as the dominant geography, where domestic PVC processing capacity and polymer compounding infrastructure continue scaling. ECHA's REACH SVHC expansions and RoHS compliance deadlines compress reformulation timelines across European processors. Regional demand patterns diverge sharply between specification-grade automotive channels and commodity construction volumes.
China
Greenhouse agriculture and PVC pipe extrusion drive stabilizer consumption in Zhejiang and Jiangsu provinces. MEE new chemical notification requirements and tightening GB standards on heavy-metal content force 9-month qualification cycles for imported additive packages. Yangtze River Delta chemical parks concentrate captive production of hindered amine light stabilizer precursors, creating single-source supply vulnerability for UV stabilizer formulators.
Germany
Automotive lightweighting mandates from BMW and Volkswagen pull high-performance calcium-zinc and organotin stabilizer packages for under-hood thermoplastics. ECHA cadmium and lead compound restrictions under REACH accelerate migration to metal-free heat stabilizers across PVC processors. Industrial clusters in North Rhine-Westphalia and Bavaria host tier one extruders specifying hybrid calcium-zinc/organophosphite systems for potable water pressure pipe.
United States
Wire and cable compounders face 12-18 month requalification cycles for insulation grades under EPA chemical risk evaluations through TSCA. EPA PMN filing requirements stretch regulatory affairs capacity for additive suppliers seeking to introduce reformulated metal-free stabilizers. Gulf Coast petrochemical corridors concentrate polyolefin production, driving antioxidant demand from packaging converters contracting 3-5 year volumes with price collars tied to propylene indices.
India
Gujarat and Maharashtra polymer hubs lack qualified local stabilizer blending capacity, creating import substitution openings for heat stabilizer suppliers. BIS standards alignment with REACH principles accelerates documentation requirements for legacy metal soap formulations. PVC profile manufacturers in Ahmedabad and Pune rely on powder stabilizer imports due to limited domestic compounding infrastructure, while distributors buffer supply volatility through safety stock positioning.
Japan
Automotive OEM thermal aging specifications from Toyota and Honda drive specification-grade stabilizer demand for engineering thermoplastics. METI chemical substance regulations and JIS standards harmonization with EU approaches compress reformulation timelines for export-oriented compounders. Kansai and Chubu industrial regions concentrate polycarbonate sheet and automotive glazing applications requiring documented metal-free stabilizer certificates.
Plastic Stabilizer Market Competitive Environment
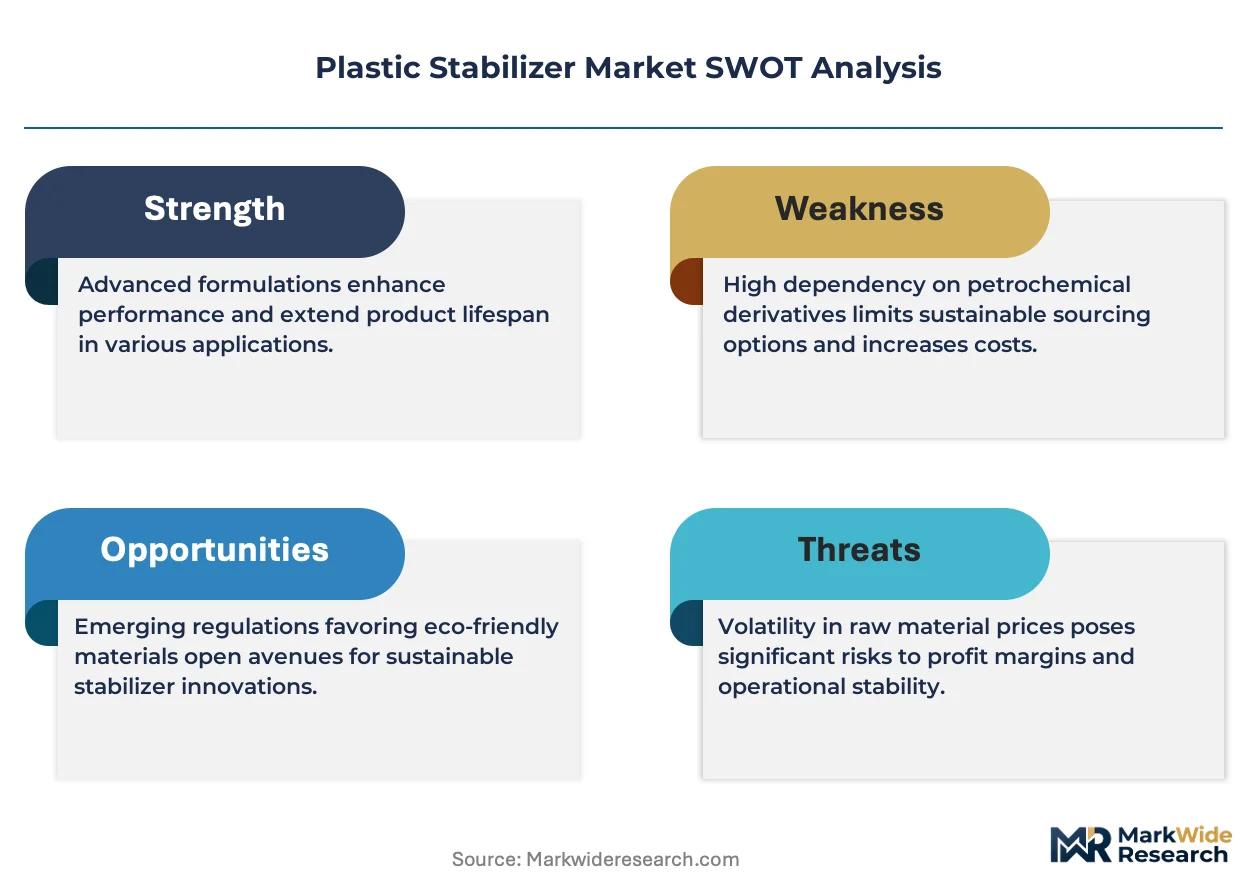
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around backward integration into hindered amine intermediates and captive antioxidant production. The competitive landscape splits between diversified chemical conglomerates leveraging portfolio breadth and focused additive specialists commanding technical formulation expertise. Three archetypes dominate: integrated polymer science leaders, metal soap specialists pivoting toward regulatory-compliant systems, and UV stabilizer intermediates producers. Capacity expansion in Zhejiang province and strategic partnerships for bio-based backbone development represent the dominant competitive moves.
Within the integrated polymer science tier, BASF anchors supply relationships through portfolio breadth spanning antioxidants and light stabilizers. SONGWON Industrial Group exemplifies the Asian UV stabilizer archetype through captive intermediate production. Baerlocher GmbH occupies a specialist position in calcium-zinc heat stabilizer systems, positioning for regulatory transitions away from lead and cadmium formulations.
| Leading Market Players |
|---|
| SONGWON Industrial Group |
| Baerlocher GmbH |
| BASF |
| Solvay |
| LANXESS |
| Clariant |
| Adeka Corporation |
| ALTANA |
| Evonik Industries |
| Others |
Value Chain & Pricing Dynamics
Calcium-zinc heat stabilizer substitution for legacy lead systems redraws procurement geography and pricing power simultaneously. German and US pipe extruders absorb 15-20% cost premiums for REACH-compliant hybrid packages, while Turkish and Egyptian processors retain lead-based economics through distributor-tier spot purchasing.
Pricing Analysis
Geographic price spreads between European specification-grade stabilizers and Asian commodity volumes exceed 30% at equivalent loadings. Three-tier pricing structure across premium automotive certification, standard industrial compliance, and economy construction grades separates contract-based long-term offtake from spot powder transactions. Pricing pressure stems from propylene index volatility feeding epoxy-based intermediate costs. Small-batch compounders in India and Southeast Asia exhibit highest price sensitivity, while German automotive tier ones prioritize thermal aging documentation over unit economics.
Supply Chain Analysis
Inventory strategy bifurcates between just-in-time masterbatch delivery for automotive tier ones and strategic stockpiling of hindered amine precursors by UV stabilizer formulators. Supply concentrates in China, Germany, and Belgium, with Zhejiang province hosting captive HALS intermediate production. Raw material flows draw from epichlorohydrin, propylene derivatives, and tall oil fatty acid bio-based feedstocks. Single-source vulnerability pervades Zhejiang-Jiangsu precursor corridors. Distribution runs through direct mill supply for heat stabilizers and regional compounder networks for UV grades and antioxidants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic stabilizer demand sits in early-cycle expansion as automotive lightweighting and agricultural film intensity accelerate specification-grade adoption ahead of regulatory deadlines.
For Market Incumbents: Compound defensive positioning through backward integration into hindered amine intermediates and captive antioxidant production in Yangtze River Delta chemical parks. Secure 3-5 year supply agreements with European packaging converters before distributor-tier consolidation squeezes regional compounders. Threat: Asian intermediate concentration creates single-source vulnerability that specialized polymer chemist scarcity exacerbates. For New Entrants and Emerging Players: Differentiate on metal-free heat stabilizer certification for medical device and potable water pipe channels where MDR and REACH documentation requirements outpace incumbent reformulation capacity. Target Gujarat and Maharashtra polymer hubs lacking qualified local blending infrastructure. Go-to-market: technical service partnerships with Indian distributors holding safety stock positions. For Investors and Strategic Acquirers: The market sits at a substitution-driven phase that favors integrated additive specialists with captive intermediate supply and documented regulatory compliance pathways. Long-term viability hinges on dual-track R&D funding for extreme-performance and sustainability-optimized formulation tracks. Acquisition archetype: calcium-zinc system specialists pivoting from metal soaps with existing automotive tier one qualifications. Signal to watch: ECHA SVHC expansion velocity compressing qualification timelines below 6 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HALS Precursors | Captive supply of hindered amine intermediates insulates SONGWON and Asian UV specialists from Zhejiang-Jiangsu single-source vulnerability. |
| Long-term Supply Agreement with Price Collars | European packaging converters at BASF and LANXESS lock propylene-indexed antioxidant volumes to secure recyclate quality through multiple reprocessing cycles. |
| Green Manufacturing Transition | EU Green Deal chemistry incentives favor bio-based stabilizer backbone development from tall oil fatty acids for Horizon Europe funding eligibility. |
| Joint Venture for Indian Compounding Scale-up | Local blending capacity in Gujarat addresses import substitution openings as BIS standards alignment accelerates documentation requirements. |
| Regulatory Certification Investment | Documented metal-free stabilizer certificates preempt EU MDR substance disclosure requirements for medical device manufacturers accelerating adoption. |
Study Parameters
Desk research of trade flow databases, ECHA REACH dossier filings, and GB standard harmonization documents preceded structured interviews with PVC pipe extrusion plant managers, automotive tier one procurement leads, polymer compounding technical directors, and regional distributor inventory planners. Primary fieldwork across North Rhine-Westphalia, Zhejiang province, and Gujarat polymer hubs combined with secondary validation from customs records and SEC additive supplier filings. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Variance decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions span stabilizer chemistry type, application end-use, physical form, and customer procurement channel. CAGRs derive from elasticity-adjusted demand curves tied to PVC processing capacity expansion and automotive lightweighting content-per-vehicle trajectories. Industry-specific forecast inputs include epichlorohydrin feedstock cost indices and REACH SVHC candidate list expansion velocity.
Material uncertainties — regulatory divergence between European hazard-based approaches and China's GB standard harmonization, plus specialized polymer chemist retirement waves — sit outside the modeled envelope. Forecasts reflect assumptions about qualification timeline compression and substitution elasticity for metal-free systems. Revision becomes warranted when ECHA cadmium and lead compound restriction enforcement crosses thresholds that trigger simultaneous multi-jurisdiction reformulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
Global Metal Chelates Market