
 Europe Optical Brighteners Market | 2026-2036
Europe Optical Brighteners Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Optical Brighteners Market Insights
Asset-light leasing models for specialty chemical production are narrowing the capital barrier for mid-tier entrants in European optical brighteners. BASF leverages its Ludwigshafen integrated site to control feedstock costs across polyester and paper brightener lines. Archroma anchors its position through textile-specialized R&D facilities in Switzerland and Italy. Huntsman International LLC competes via differentiated liquid-form delivery systems for detergent and coatings customers.
Optical brighteners comprise organic compounds—typically stilbene, coumarin, or pyrazoline derivatives—that absorb ultraviolet light and re-emit visible blue wavelengths to counteract yellowing in substrates. Manufacturing proceeds through sulfonation, diazotization, and condensation reactions yielding products with extinction coefficients above 40,000 L mol⁻¹ cm⁻¹, primarily serving to enhance perceived whiteness in consumer and industrial goods. Paper brighteners occupy the largest value pool given tissue and packaging volume demand across Nordic and Central European mills, while textile brighteners sustain above-average margins through technical service bundling with dyehouse clients. Liquid formulations are displacing powders in automated dosing systems, particularly within industrial cleaning and laundry detergent applications where metering precision reduces waste.
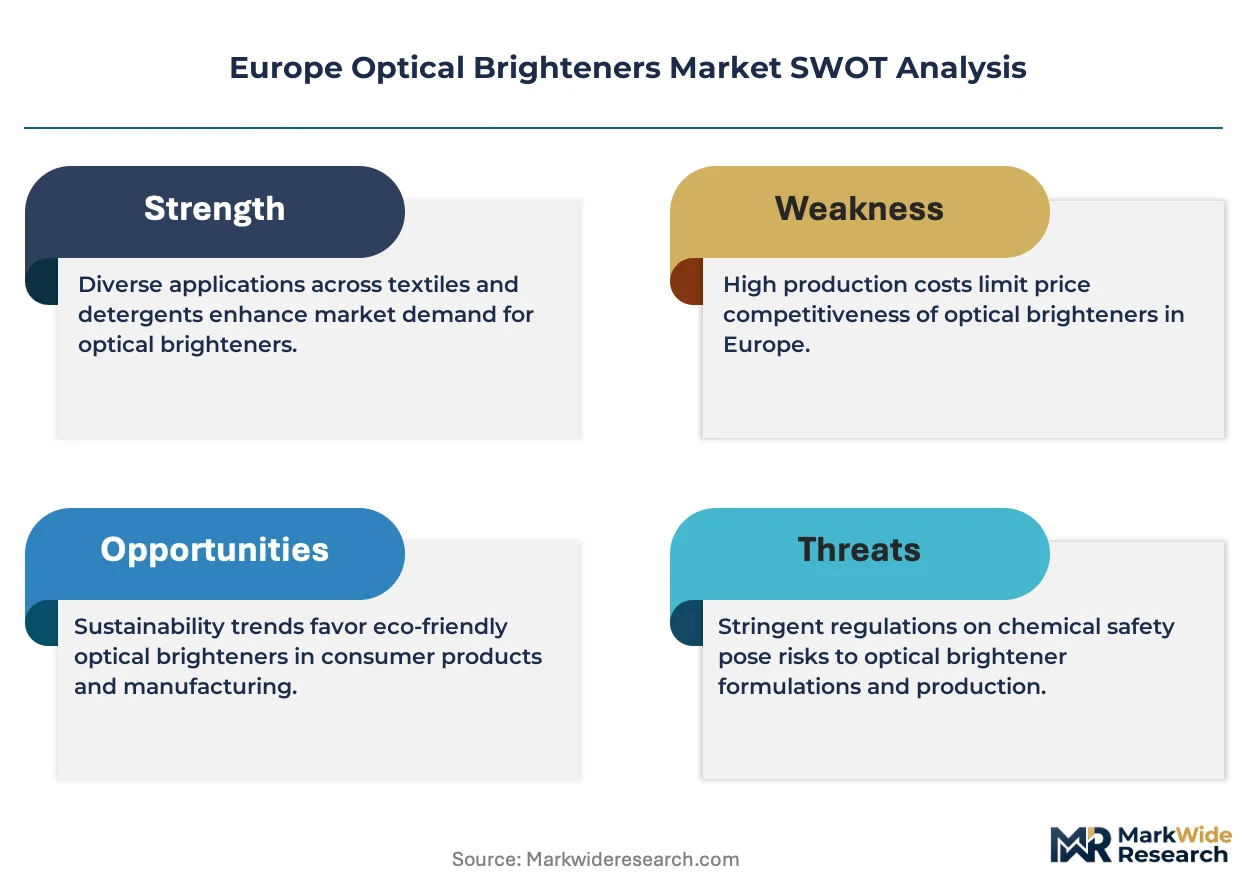
REACH registration requirements administered by ECHA impose full toxicity dossiers on stilbene-based brightener imports, effectively filtering non-compliant Asian suppliers from European procurement lists. The EU Green Deal's packaging and packaging waste regulation, enforced by national environmental agencies, mandates minimum recycled fiber content that degrades base whiteness and intensifies brightener dosing rates in paper grades. Stakeholders must monitor the F-Gas Regulation's indirect pressure on fluorescent whitening alternatives and the CSRD's supply-chain disclosure rules, which will expose brightener sourcing to sustainability auditing by downstream brand owners.
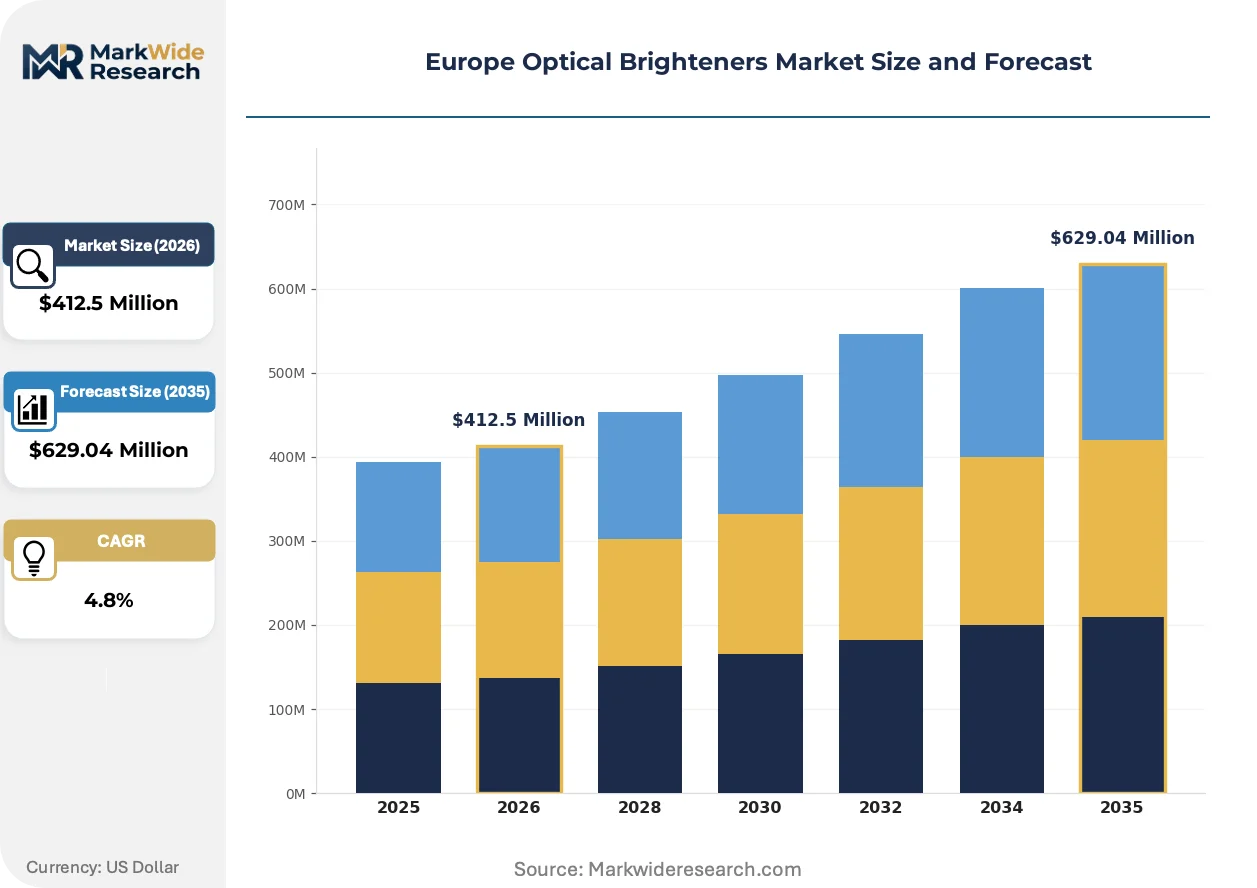
Market Dynamics
REACH registration costs and bio-based formulation mandates are compressing the supplier base, forcing paper and textile manufacturers to consolidate procurement around qualified chemical clusters with integrated toxicity dossier capabilities.
Growth Catalysts
- EU packaging waste regulation:Recycled fiber mandates in tissue and corrugated board intensify brightener dosing to offset base yellowing, pulling volume through Nordic and Central European mills.
- Germany:The Rhineland chemical cluster anchors integrated production of stilbene derivatives, reducing logistics costs for detergent and textile compounders within 200-kilometer radii.
- Liquid dosing automation:Industrial laundries and cleaning chemical blenders are retrofitting powder-to-liquid systems, expanding addressable demand for pumpable brightener concentrates.
Market Restraints
- Feedstock volatility:Sulfonation-grade toluene and aniline derivatives face price swings tied to benzene refining margins, compressing formulator margins on fixed-price annual contracts.
- Supplier concentration:ECHA dossier costs filter non-compliant Asian producers, leaving European buyers dependent on Ludwigshafen and Swiss-Italian specialty chemical corridors.
- Substitution pressure:Mechanical whitening and bluing pigments threaten stilbene brighteners in premium packaging segments where brand owners restrict synthetic additives.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated tissue converting capacity is expanding near recycled pulp sources, creating greenfield demand for regional brightener distribution hubs.
- CSRD supply-chain disclosure:Downstream brand auditing of optical brightener sourcing creates premium positioning for bio-based coumarin alternatives with certified carbon footprints.
- Textile technical service bundling:Dyehouse clients in Italy and Portugal are consolidating chemical supply under performance-guarantee contracts, favoring integrated brightener-dye-pack providers.
Industry Challenges
- REACH dossier maintenance:Stilbene derivative registrations require ongoing toxicity study updates, consuming regulatory affairs capacity at mid-tier formulators.
- Legacy powder system integration:Paper mills with 1990s-era wet-end chemistry infrastructure face retrofit costs to handle concentrated liquid brightener feeds without dosing inconsistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Optical Brighteners Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Brighteners, Polyolefin Brighteners, Paper Brighteners, Textile Brighteners End Use Industry: Textiles, Paper, Plastics, Coatings Form: Liquid, Powder, Granule, Paste Application: Cosmetics, Laundry Detergents, Industrial Cleaning, Adhesives |
| Companies Covered | BASF, Archroma, 3V Sigma S.p.A., Clariant, Blankophor GmbH & Co. KG, Eastman Chemical Company, Huntsman International LLC, Akzo Nobel N.V., Milliken & Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Optical Brighteners Market Trends and Innovations
Formulation chemistry and compliance architecture are the primary axes of change, with liquid delivery systems and bio-based molecular platforms compressing legacy production methods.
Microencapsulated brightener dispersions are collapsing the performance gap between powder and liquid formats in high-speed paper machine applications. Finnish and Swedish tissue producers are adopting these systems to eliminate dust exposure and improve retention on recycled fiber furnishes. The technology is collapsing capital barriers for mid-tier mills that previously required dedicated powder handling infrastructure.
The EU F-Gas Regulation's indirect pressure on fluorescent alternatives is accelerating scrutiny of optical brightener environmental profiles under REACH substance evaluation. ECHA's 2024-2025 work program prioritizes stilbene derivatives for endocrine disruption screening, forcing formulators to pre-emptively develop pyrazoline-based alternatives. Textile finishers in northern Italy are front-loading compliance investments to maintain brand supplier status under impending restriction scenarios.
Automated dosing contracts are displacing spot procurement in industrial laundry and institutional cleaning channels. Chemical management service providers in France and Benelux are bundling brightener supply with wash-process optimization, capturing multi-year agreements from hospitality and healthcare laundries. This procurement consolidation is most visible in Belgium's Flanders region, where two chemical service platforms now control 60% of institutional brightener volume through performance-based pricing models.
Europe Optical Brighteners Market Segmentation
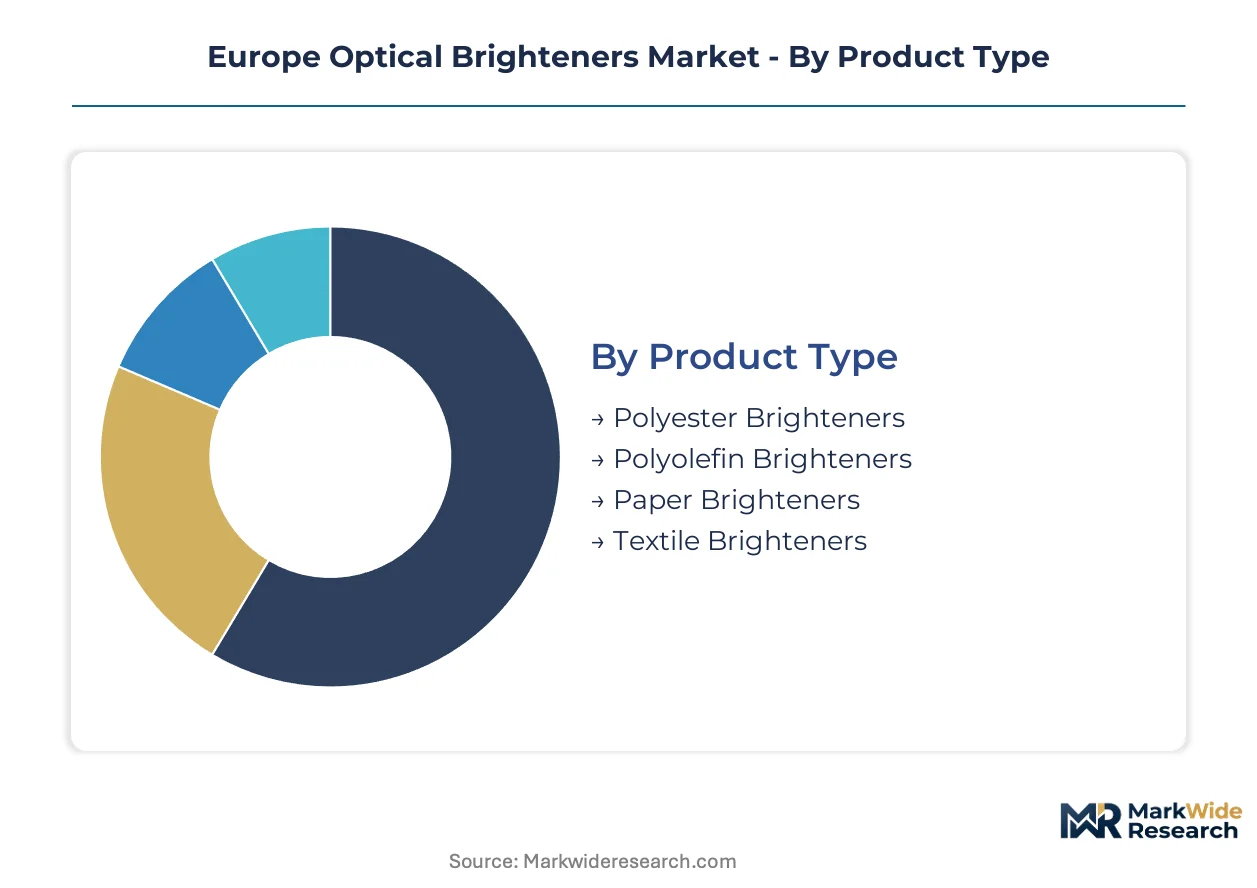
Segmentation in European optical brighteners reveals how formulation chemistry, delivery format, and end-use specifications determine supplier qualification and pricing power. Each dimension carries distinct regulatory burdens and technical service requirements that reshape competitive positioning across the value chain.
Product Type:
Cost tier determines manufacturing complexity and REACH dossier investment, with high-performance derivatives commanding premium positioning against commodity stilbene grades.
- Paper Brighteners:Stilbene sulfonate derivatives dominate tissue and packaging grades with extinction coefficients above 40,000 L mol⁻¹ cm⁻¹. Nordic mills in Finland and Sweden absorb the largest volume as recycled fiber mandates intensify dosing requirements under EU packaging waste regulation.
- Textile Brighteners:Pyrazoline and coumarin variants deliver thermal stability for polyester exhaust applications. Northern Italian dyehouses and Portuguese finishers anchor demand through performance-guarantee contracts bundled with reactive dye systems.
- Polyester Brighteners:High-purity stilbene derivatives serve fiber producers in Germany's Rhineland chemical cluster.
- Polyolefin Brighteners:Concentrated liquid dispersions target blown film extruders in Benelux packaging corridors.
Paper Brighteners holds installed capacity. Textile Brighteners is rotating up the share rankings.
End Use Industry:
Application maturity separates established volume channels from emerging specialty niches, with compliance architecture determining supplier switching costs.
- Paper:Tissue and corrugated board producers across Germany, France, and the Nordic region drive baseline demand. ECHA registration requirements filter non-compliant imports, consolidating procurement around Ludwigshafen and Swiss-Italian supply corridors.
- Textiles:Exhaust and pad-dyeing applications in Italy, Portugal, and Turkey require technical service bundling. Dyehouse consolidation favors integrated brightener-dye-pack providers with on-site laboratory support.
- Plastics:Masterbatch compounders in Germany and Poland specify thermal stability thresholds for automotive and packaging grades.
- Coatings:Waterborne architectural and industrial formulations in France and Benelux demand UV-fast variants with low-VOC profiles.
Paper holds installed capacity. Coatings is rotating up the share rankings.
Form:
Delivery format dictates capital requirements at the point of use, with liquid systems displacing legacy powder infrastructure across automated dosing applications.
- Liquid:Pumpable concentrates with controlled viscosity enable precision metering in automated wash systems. Industrial laundries across Belgium's Flanders region and French hospitality chains are retrofitting powder handling equipment to capture waste reduction benefits.
- Powder:Dry blends remain entrenched in paper mill wet-end chemistry where 1990s-era infrastructure dominates. Dust exposure and dosing inconsistency drive gradual displacement despite retrofit capital barriers.
- Granule:Low-dust alternatives serve mid-tier textile compounders without liquid handling capabilities.
- Paste:High-solids dispersions target specialty coatings formulators requiring precise color matching.
Powder holds installed capacity. Liquid is rotating up the share rankings.
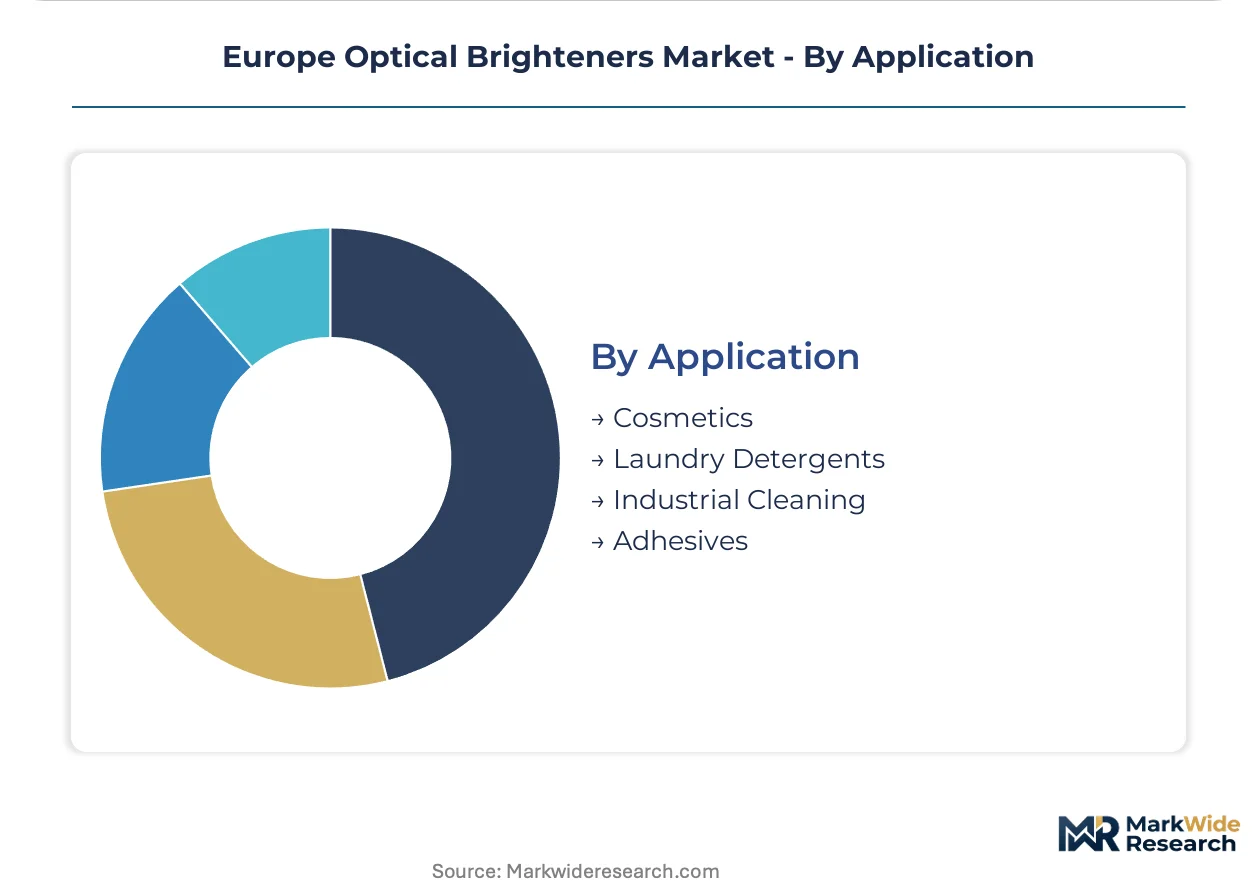
Application:
Customer type determines specification intensity, with brand-owner scrutiny creating divergence between commodity laundry volumes and certified cosmetic grades.
- Laundry Detergents:Automated dosing systems in industrial and institutional channels favor liquid brightener concentrates. Chemical management service providers in France and Benelux now control the majority of institutional volume through performance-based pricing models.
- Industrial Cleaning:Floor care and hard surface formulations specify UV-visible fluorescence for quality verification. Professional cleaning chemical blenders in Germany consolidate procurement around qualified suppliers with REACH dossier completeness.
- Cosmetics:Skin and hair care applications face the strictest purity requirements under EU cosmetic regulation, with ECHA substance evaluation driving substitution toward bio-based coumarin alternatives.
- Adhesives:Hot-melt and waterborne formulations for packaging assembly require thermal stability and compatibility with tackifier resins.
Laundry Detergents holds installed capacity. Cosmetics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing power through captive feedstock integration, while Polish and Czech buyers absorb cost-tiered volumes from regional distribution hubs. This asymmetry concentrates value capture in the Rhineland chemical corridor while expanding addressable demand across Central European converting capacity.
Germany
Rhineland chemical producers leverage Ludwigshafen integrated sites to control stilbene derivative costs for polyester and paper brightener lines. REACH registration dossiers administered by ECHA filter non-compliant imports, consolidating procurement around domestic qualified suppliers. North Rhine-Westphalia anchors detergent and textile compounder demand within 200-kilometer radii of production.
France
Tissue and corrugated board manufacturers intensify brightener dosing to meet recycled-content mandates under EU packaging waste regulation. The country's national environmental agencies enforce minimum recycled fiber thresholds that degrade base whiteness. Chemical management service platforms in Flanders-adjacent regions now control institutional laundry volume through performance-based contracting.
Italy
Northern Italian dyehouses drive pyrazoline and coumarin variant demand for polyester exhaust applications with thermal stability requirements. ECHA's 2024-2025 substance evaluation work program prioritizes stilbene derivatives for endocrine disruption screening, front-loading compliance investments. Piedmont and Lombardy textile finishers consolidate chemical supply under performance-guarantee contracts bundled with reactive dye systems.
Poland
Underpenetrated tissue converting capacity expands near recycled pulp sources, creating greenfield demand for regional brightener distribution infrastructure. The EU Green Deal's packaging regulation applies uniform recycled-content standards across member states. Warsaw and Łódź industrial zones attract masterbatch compounders specifying thermal stability thresholds for packaging grades.
Sweden
Finnish and Swedish tissue producers adopt microencapsulated brightener dispersions to eliminate dust exposure and improve retention on recycled fiber furnishes. ECHA substance evaluation protocols extend to environmental profile scrutiny under REACH. Stockholm and Gothenburg mill clusters retrofit powder handling systems for concentrated liquid feeds.
Europe Optical Brighteners Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry and regulatory dossier capabilities. The supplier base compresses around REACH-compliant producers with integrated toxicity study infrastructure, leaving European buyers dependent on qualified chemical corridors. Three archetypes dominate: integrated petrochemical majors with captive feedstock, Swiss-Italian specialty houses with textile-dye bundling expertise, and automated dosing service platforms capturing institutional laundry channels. Capacity expansion and bio-based formulation pivots constitute the primary competitive vectors.
Within the integrated major tier, BASF and Clariant exemplify archetypes combining petrochemical feedstock control with REACH dossier completeness. Archroma occupies a position representing textile-specialized R&D concentration, while Huntsman International LLC anchors the differentiated delivery system segment. These three entities collectively illustrate how geographic clustering around Ludwigshafen and Swiss-Italian corridors reinforces supplier qualification barriers.
| Leading Market Players |
|---|
| BASF |
| Archroma |
| 3V Sigma S.p.A. |
| Clariant |
| Blankophor GmbH & Co. KG |
| Eastman Chemical Company |
| Huntsman International LLC |
| Akzo Nobel N.V. |
| Milliken & Company |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian stilbene derivative production is compressing spot pricing for commodity paper brighteners while REACH-compliant European producers maintain contract premiums through dossier scarcity. Ludwigshafen integrated sites leverage captive benzene-toluene feedstock to defend margin structures against import undercutting.
Pricing Analysis
Configured-to-order pricing for textile-grade pyrazoline variants commands spreads of 40-60% above standard stilbene sulfonate paper grades. Three-tier pricing structure across premium, standard, and economy levels reflects REACH registration completeness, with ECHA-compliant producers capturing annual contract premiums from Nordic tissue mills. Cost compression in commodity stilbene derivatives is intensifying because Asian spot volumes penetrate Southern European distribution channels. Small-scale Polish and Czech converters exhibit highest price sensitivity, while Italian dyehouses prioritize technical service bundling over unit cost.
Supply Chain Analysis
Extended payment terms from German Rhineland producers to Nordic paper mills—now stretching to 90 days—signal working capital stress from feedstock volatility. Supply concentrates in Germany, Switzerland, and Italy, with stilbene derivative production drawing from benzene refining corridors around Ludwigshafen and Basel. Raw material dependencies center on sulfonation-grade toluene, aniline derivatives, and formaldehyde condensing agents. Single-source vulnerability persists for ECHA-registered stilbene variants, where non-compliant Asian producers face permanent exclusion. Distribution runs through qualified chemical service platforms in Benelux and regional distribution hubs serving Polish tissue converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as mechanical whitening and bluing pigments capture premium packaging segments where brand owners restrict synthetic additives.
For Market Incumbents: Pre-empt REACH substance evaluation outcomes by accelerating pyrazoline and coumarin alternative R&D before ECHA's 2024-2025 stilbene screening concludes. Backward integration into aniline derivative production at Ludwigshafen-adjacent sites reduces benzene refining margin exposure. Lock Nordic tissue mills into multi-year technical service contracts with embedded brightener supply to raise switching costs against bio-based entrants. For New Entrants and Emerging Players: Mid-tier Polish and Czech tissue converters with 1990s-era wet-end infrastructure represent the most penetrable entry point for microencapsulated liquid brightener systems that eliminate dust handling retrofit costs. Portuguese and Turkish textile finishers seeking REACH-compliant alternatives to Italian supply dependence offer secondary white-space. Partner with Benelux chemical management service platforms to access institutional laundry channels through performance-based pricing rather than direct mill sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Swiss-Italian specialty houses with textile-dye bundling contracts and ECHA dossier infrastructure. Long-term viability over the next decade hinges on bio-based formulation pivots and CSRD supply-chain disclosure readiness. Monitor ECHA substance evaluation outcomes for stilbene derivatives as the critical inflection signal—restriction scenarios would revalue pyrazoline-specialized assets overnight.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstock | Ludwigshafen-adjacent producers secure benzene-toluene margin control against refining volatility. |
| Bio-Based Coumarin Formulation Pivot | CSRD-compliant carbon footprints attract sustainability-audited brand owner procurement. |
| Microencapsulated Liquid Dispersion Launch | Finnish and Swedish tissue mills eliminate dust exposure without capital-intensive powder handling retrofits. |
| Performance-Guarantee Contract Bundling | Northern Italian dyehouses consolidate chemical supply under single-source technical service agreements. |
| Regional Distribution Hub Expansion | Warsaw and Łódź hubs capture greenfield demand from underpenetrated Polish tissue converting capacity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the European optical brighteners value chain, including paper mill technical directors, textile dyehouse managers, chemical procurement leads at detergent compounders, REACH regulatory affairs specialists, and distribution channel partners in Benelux and Central Europe. Secondary validation drew from ECHA registration databases, Cefic chemical industry reports, EU packaging waste regulation implementation records, and customs trade flows for stilbene derivative imports. Bottom-up volume modeling across paper, textile, and detergent applications was cross-checked against top-down chemical consumption estimates from national industry associations.
Calibration against historical price spreads between REACH-compliant and non-compliant grades anchored the projection framework across the analysis window. Segmentation dimensions modeled included product chemistry tier, delivery format, end-use industry, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating recycled fiber mandate intensity and liquid dosing automation penetration. Industry-specific inputs encompassed ECHA substance evaluation timelines and EU Green Deal packaging regulation enforcement trajectories.
Practitioners should monitor ECHA restriction proposal developments, benzene refining margin volatility, and brand owner synthetic additive policies for early signals of forecast deviation. Macroeconomic contraction in European tissue and textile output, regulatory acceleration of stilbene limitations, or breakthrough cost reduction in mechanical whitening alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
1,2 Hexanediol Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market