
 Skin Hyperpigmentation Treatment Market | 2026-2036
Skin Hyperpigmentation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Hyperpigmentation Treatment Market Insights
South Korean pharmaceutical manufacturers is shifting capacity toward tyrosinase-inhibitor R&D complexes. Galderma S.A. leverages its dermatology-focused pipeline to anchor prescription-grade topical portfolios across North America and Europe. L'Oréal S.A. sustains consumer-facing innovation through mass-market brightening lines that compete with clinic-grade alternatives. Pierre Fabre S.A. specializes in botanical-derived actives that differentiate its offerings from synthetic competitors.
Skin hyperpigmentation treatment encompasses pharmacological and procedural interventions designed to reduce melanin concentration in epidermal or dermal tissue, typically employing agents such as hydroquinone, azelaic acid, kojic acid, or laser wavelengths between 532 nm and 1064 nm that selectively target melanin chromophores. These treatments serve both therapeutic purposes for melasma and post-inflammatory hyperpigmentation and cosmetic objectives for photodamage and uneven tone. Topical agents command the largest revenue share due to accessibility and daily-use recurrence, while laser therapies represent the fastest-expanding margin pool as device manufacturers improve safety profiles for darker skin phototypes. Professional procedures draw disproportionate profitability from dermatology clinics where physician oversight justifies premium pricing, whereas over-the-counter options face margin compression from private-label competition.
FDA oversight of hydroquinone concentration limits and EMA restrictions on corticosteroid combinations in topical formulations compel reformulation investments across manufacturers. The EU Green Deal chemical sustainability criteria and REACH registration requirements for novel active ingredients extend development timelines but create barriers against commoditized entrants. Stakeholders must monitor evolving pigmentation biology research, regulatory divergence between FDA and EMA on ingredient safety thresholds, and the competitive threat from energy-based device manufacturers expanding into home-use formats.
Market Dynamics
Tyrosinase-inhibitor formulation chemistry is compressing development timelines while FDA and EMA divergence on hydroquinone safety thresholds forces parallel regulatory track investments from every multinational manufacturer.
Growth Catalysts
- Photodamage awareness campaigns:Dermatology clinics in the United States and Germany report patient volume expansion for elective pigmentation correction. Aesthetic medicine infrastructure investments accelerate procedure accessibility.
- REACH registration pathways:Novel botanical actives gain formal approval status under EU chemical sustainability criteria. This creates defensible market positions against commoditized synthetic competitors.
- 532 nm laser platform improvements:Device manufacturers achieve safer melanin-selective energy delivery for Fitzpatrick skin types IV-VI. Darker phototype treatment volumes expand beyond traditional limitations.
Market Restraints
- Active ingredient concentration caps:FDA-mandated hydroquinone limits restrict prescription-grade efficacy thresholds. Formulators sacrifice clinical performance for regulatory compliance.
- Raw material supplier concentration:Kojic acid and azelaic acid precursor supply clusters in Chinese chemical manufacturing zones. Geopolitical friction threatens input cost stability.
- Post-inflammatory hyperpigmentation recurrence rates:Topical monotherapy demonstrates incomplete durable response in melasma subtypes. Patient discontinuation elevates customer acquisition costs for repeat procedures.
Strategic Opportunities
- Home-use energy device penetration:LED and low-level laser formats migrate from clinic to consumer channels. Device manufacturers capture recurring revenue through consumable attachment models.
- PLI scheme alignment:Indian domestic pharmaceutical production incentives support local tyrosinase-inhibitor manufacturing scale. Export competitiveness improves against European incumbents.
- AI-assisted diagnostic integration:Melanin depth imaging converges with treatment parameter selection algorithms. Personalized protocol software differentiates premium clinic offerings.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in melanin biology and dermal penetration science commands premium compensation. Talent competition intensifies between dermatology device and topical pharmaceutical divisions.
- Clinical trial endpoint standardization:Lack of harmonized MASI scoring protocols across FDA and EMA submissions extends validation timelines. Regulatory consultants absorb disproportionate program budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Hyperpigmentation Treatment Market |
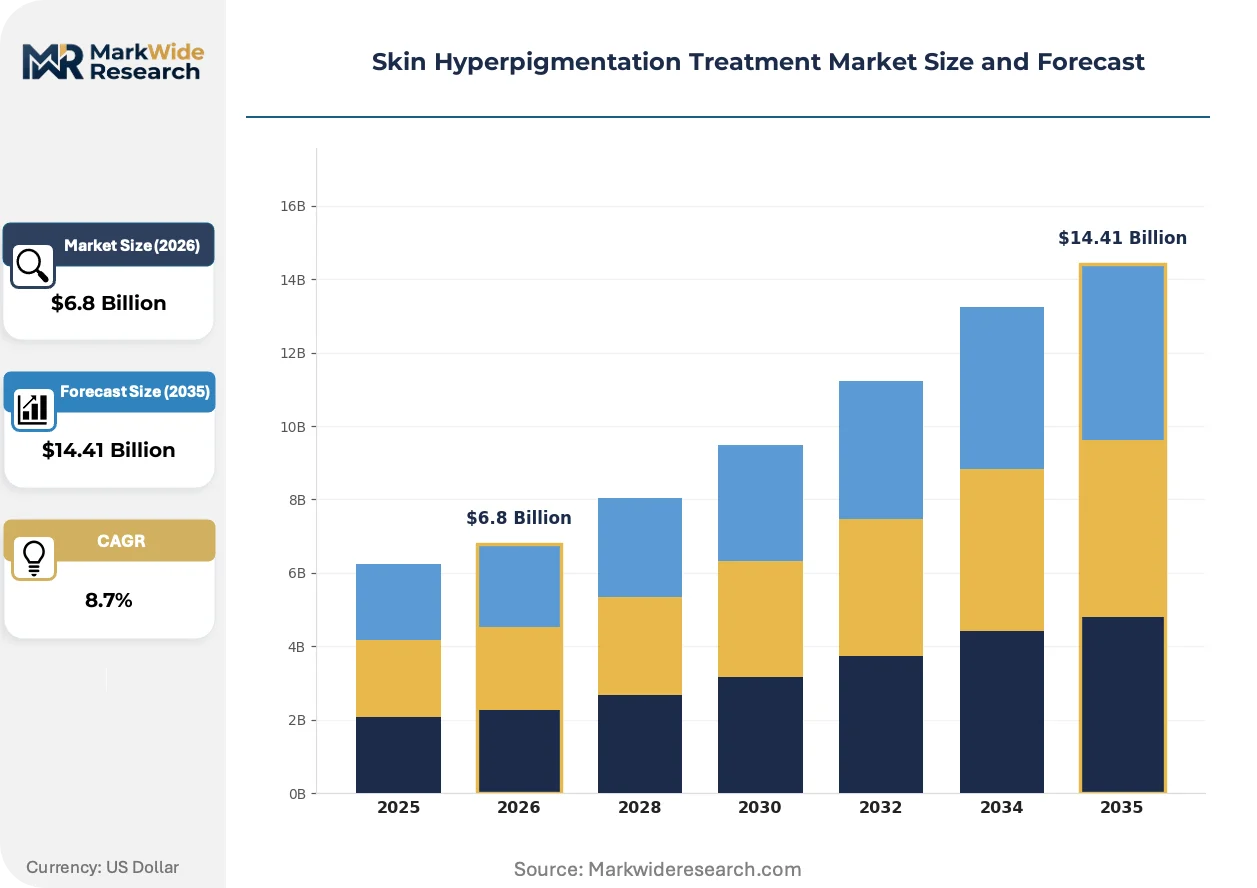
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Laser Therapies, Chemical Peels, Microdermabrasion Treatment Method: Prescription Treatments, Over-the-Counter Options, Professional Procedures, Home Remedies End User: Dermatology Clinics, Beauty Salons, Home Users, Hospitals Skin Type: Oily Skin, Dry Skin, Combination Skin, Sensitive Skin |
| Companies Covered | Galderma S.A., L'Oréal S.A., Pierre Fabre S.A., Vivier Pharma, Candela Medical, AbbVie Inc., Obagi Cosmeceuticals LLC, Bayer AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Hyperpigmentation Treatment Market Trends and Innovations
Convergence between prescription-grade actives and consumer device formats is dissolving traditional channel boundaries. Biology-driven personalization and sustainability-mandated chemistry reformulation dominate capital allocation decisions.
Picosecond laser technology is rewriting treatment safety profiles across darker skin phototypes. Dermatology clinics in Seoul and Los Angeles adopt 755 nm and 1064 nm platforms for post-inflammatory hyperpigmentation with reduced thermal collateral damage. Device manufacturers compress pulse durations below 450 picoseconds to achieve selective photothermolysis without surrounding tissue injury.
EU Green Deal chemical sustainability criteria are mandating biodegradable active ingredient alternatives. REACH registration requirements for novel tyrosinase inhibitors extend development timelines by 18-24 months. European manufacturers reformulate around botanical-derived actives to preempt registration denial risks for synthetic molecules.
Subscription-based topical regimen delivery is replacing single-purchase pharmacy models. Direct-to-consumer platforms in the United States bundle prescription-grade hydroquinone alternatives with teledermatology oversight. Patient adherence monitoring through mobile applications reduces treatment discontinuation rates compared to traditional retail dispensing.
Skin Hyperpigmentation Treatment Market Segmentation
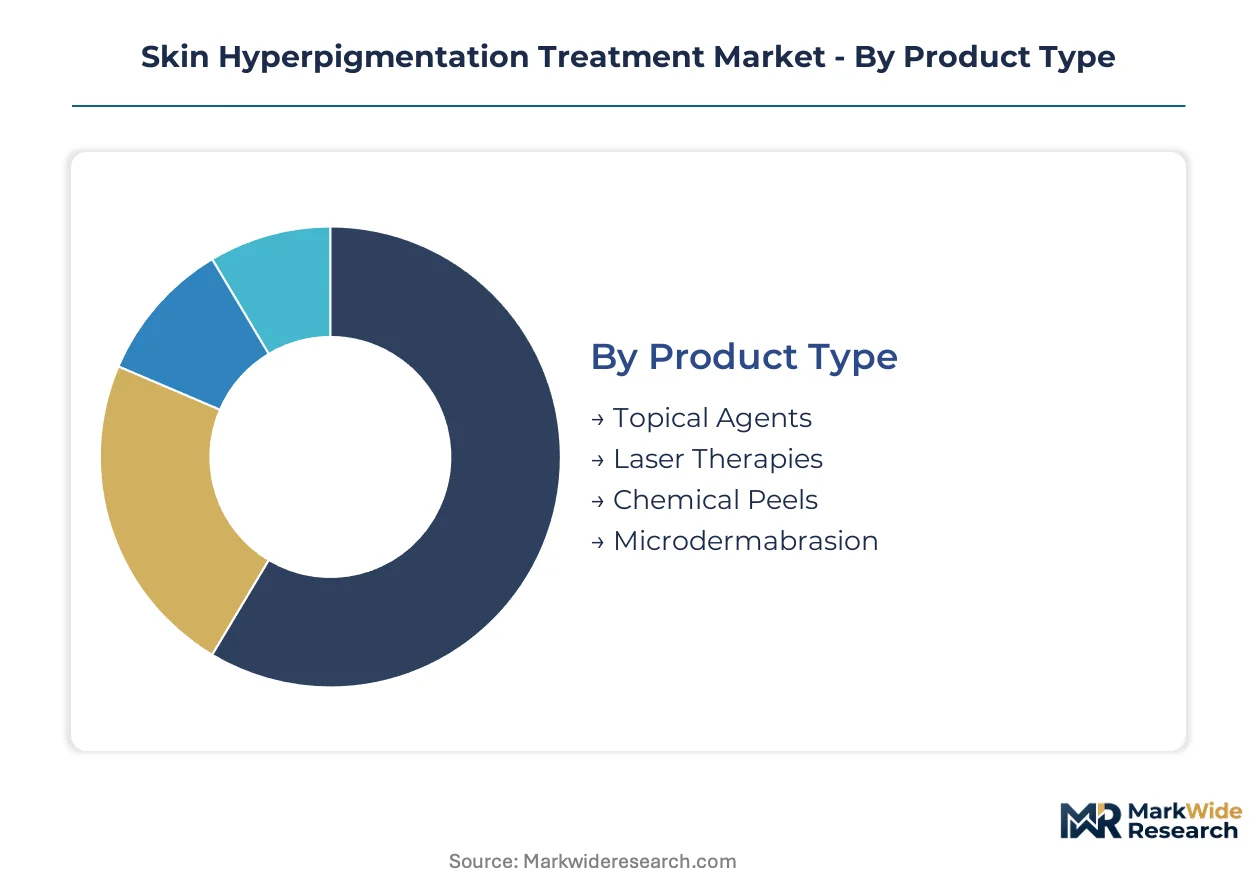
Product differentiation in hyperpigmentation treatment follows distinct efficacy-accessibility trade-offs. Channel boundaries between prescription-grade and consumer formats are dissolving as teledermatology platforms expand. Segmentation choices directly determine margin capture, regulatory pathway complexity, and patient adherence economics.
Product Type:
Volume concentration favors daily-use formats while premium pools cluster around device-based interventions requiring clinical infrastructure.
- Topical Agents:Hydroquinone, azelaic acid, and kojic acid formulations dominate pharmacy and direct-to-consumer channels. Daily application protocols generate recurring revenue streams, though FDA concentration limits constrain efficacy ceilings for prescription variants.
- Laser Therapies:Picosecond and Q-switched platforms deliver selective photothermolysis at 532 nm, 755 nm, and 1064 nm wavelengths. Seoul and Los Angeles clinics report expanding adoption for Fitzpatrick types IV-VI as pulse duration improvements reduce thermal collateral damage.
- Chemical Peels:Glycolic acid and trichloroacetic acid concentrations stratify between superficial home-use and medium-depth clinical application.
- Microdermabrasion:Crystal and diamond-tip systems serve as entry-level procedural options in beauty salons and dermatology clinics.
Mature deployment sits with Topical Agents. Newer deployment is concentrated in Laser Therapies.
Treatment Method:
Regulatory oversight intensity separates prescription pathways from consumer autonomy, with teledermatology platforms bridging this divide.
- Prescription Treatments:FDA-mandated hydroquinone limits and EMA corticosteroid combination restrictions define formulation boundaries. Physician oversight justifies premium pricing while compliance costs absorb disproportionate R&D budgets.
- Over-the-Counter Options:Niacinamide and vitamin C derivatives compete on accessibility. Private-label compression erodes branded margins in mass retail channels.
- Professional Procedures:Dermatology clinics in the United States and Germany anchor demand. Energy-based device manufacturers capture recurring revenue through maintenance contracts and consumable attachment models.
- Home Remedies:Botanical extracts and unregulated actives occupy regulatory gray zones with minimal clinical validation requirements.
Revenue concentration clusters in Professional Procedures. Volume expansion is climbing fastest in Over-the-Counter Options.
End User:
Channel selection determines pricing power, with clinical settings commanding premiums through liability insulation and outcome accountability.
- Dermatology Clinics:Physician-directed protocols combine prescription actives with energy-based devices. Malpractice coverage and outcome liability justify 3-5x pricing multiples over consumer channels.
- Beauty Salons:Microdermabrasion and superficial chemical peels dominate service menus. Regulatory enforcement gaps permit procedure expansion beyond traditional scope-of-practice boundaries.
- Home Users:Subscription-based topical delivery and LED devices displace single-purchase pharmacy models. Mobile adherence monitoring reduces discontinuation rates versus traditional retail dispensing.
- Hospitals:Post-inflammatory hyperpigmentation following burn or surgical intervention drives institutional procurement. Reimbursement coding limitations constrain market penetration.
Margin capture concentrates with Dermatology Clinics. Addressable population expansion is steepest among Home Users.
Skin Type:
Formulation tolerability and device safety profiles segment addressable markets, with darker phototypes historically underserved by legacy technologies.
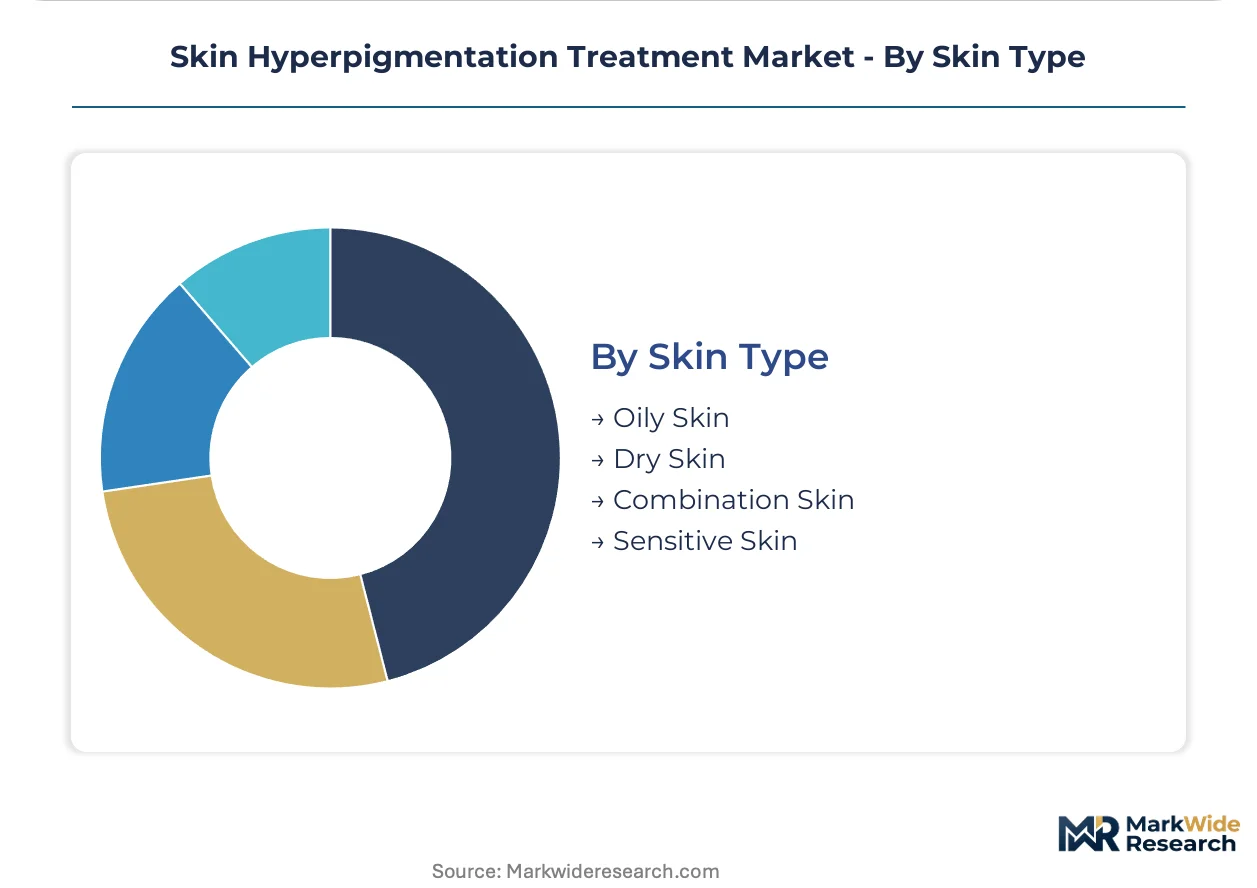
- Oily Skin:Non-comedogenic vehicle formulations and oil-control adjuncts dominate product development. Salicylic acid combinations address concurrent acne and hyperpigmentation presentations.
- Dry Skin:Emollient-rich bases and ceramide co-formulations mitigate barrier disruption from active ingredients. Hydration-focused marketing differentiates premium positioning.
- Combination Skin:Zone-specific treatment protocols complicate formulation standardization. Multi-product regimens elevate customer lifetime value through regimen bundling.
- Sensitive Skin:Fragrance-free and hypoallergenic certifications command price premiums. Botanical-derived actives from Pierre Fabre S.A. and competitors target this intolerance-prone segment.
Established formulation libraries serve Oily Skin. Product development investment is concentrating fastest in Sensitive Skin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kojic acid and azelaic acid precursor supply clusters in Chinese chemical manufacturing zones. Geopolitical friction threatens input cost stability. Patient awareness campaigns in developed aesthetic medicine infrastructure drive procedural volume expansion.
United States
Dermatology clinics in Los Angeles and New York Metro report patient volume expansion for elective pigmentation correction. FDA-mandated hydroquinone concentration limits restrict prescription-grade efficacy thresholds. Aesthetic medicine infrastructure investments accelerate procedure accessibility across the Sun Belt corridor.
Germany
Beauty salons and dermatology clinics in Bavaria and North Rhine-Westphalia anchor European procedural demand. EMA restrictions on corticosteroid combinations in topical formulations compel reformulation investments. REACH registration requirements for novel active ingredients extend development timelines for Frankfurt-based pharmaceutical manufacturers.
China
Raw material supplier concentration for tyrosinase-inhibitor precursors sits in Jiangsu and Zhejiang chemical manufacturing zones. NMPA oversight of active pharmaceutical ingredients in topical agents shapes product development pathways. Yangtze River Delta pharmaceutical manufacturers shift capacity toward tyrosinase-inhibitor R&D complexes.
South Korea
Seoul Capital Area dermatology clinics adopt picosecond laser platforms for post-inflammatory hyperpigmentation with reduced thermal collateral damage. MFDS regulates medical device safety profiles for darker skin phototypes. Busan-Ulsan device manufacturers achieve safer melanin-selective energy delivery for Fitzpatrick skin types IV-VI.
India
Maharashtra and Gujarat pharmaceutical production scales under PLI scheme alignment for domestic tyrosinase-inhibitor manufacturing. CDSCO oversight of topical formulation imports creates compliance barriers for European incumbents. Mumbai-based exporters improve competitiveness against established Western manufacturers.
Skin Hyperpigmentation Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in home-use energy devices and subscription-based topical delivery. The market structures around three tiers: multinational dermatology specialists with prescription-grade portfolios, consumer-facing beauty conglomerates with mass-market brightening lines, and device manufacturers with clinic-to-consumer format migration. Strategic archetypes include biology-driven formulators, energy-based platform developers, and botanical-active specialists. Competitive moves concentrate on M&A for teledermatology capabilities and capacity expansion in Indian pharmaceutical zones.
Within the dermatology specialist tier, Galderma S.A. and Pierre Fabre S.A. represent distinct positioning archetypes. Galderma S.A., a Swiss S.A., anchors prescription-grade topical portfolios across North American and European clinical channels. Pierre Fabre S.A., a French S.A., exemplifies botanical-derived active differentiation from synthetic competitors. L'Oréal S.A. occupies the consumer-facing tier as a French S.A. sustaining mass-market innovation that competes with clinic-grade alternatives.
| Leading Market Players |
|---|
| Galderma S.A. |
| L'Oréal S.A. |
| Pierre Fabre S.A. |
| Vivier Pharma |
| Candela Medical |
| AbbVie Inc. |
| Obagi Cosmeceuticals LLC |
| Bayer AG |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Prescription-grade efficacy divergence from mass-market accessibility manifests in both pricing power concentration and supply chain configuration complexity. FDA-mandated hydroquinone limits and EMA corticosteroid restrictions create certification-ladder pricing tiers that reward compliant manufacturers with premium positioning while forcing reformulation investments that reshape upstream chemical sourcing patterns.
Pricing Analysis
Warranty and service bundling separates clinic-grade device contracts from unbundled consumer-format sales. Professional procedures command three-tier pricing structure across premium, standard, and economy levels based on physician oversight intensity and liability coverage depth. Brand premium and certification level—FDA 510(k) versus CE marking tiers—drive price differentiation between multinational dermatology specialists and emerging device manufacturers. Pricing pressure stems from private-label compression in over-the-counter channels as subscription-based topical delivery models displace traditional pharmacy dispensing. Home users exhibit highest price sensitivity; dermatology clinics demonstrate lowest sensitivity due to outcome accountability requirements.
Supply Chain Analysis
Freight cost volatility from Jiangsu and Zhejiang chemical manufacturing zones to European and North American formulation facilities compresses margin structures for tyrosinase-inhibitor precursors. Kojic acid and azelaic acid supply concentrates in China, India, and South Korea, with botanical active sourcing drawing from France and Brazil. Raw material dependencies rest on tyrosinase-inhibitor chemistry, picosecond laser componentry, and REACH-registered active ingredients. Single-source vulnerability from Chinese precursor concentration threatens input cost stability. Distribution runs through dermatology clinic procurement networks, direct-to-consumer subscription platforms, and mass retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration timelines and FDA hydroquinone concentration enforcement erect cost-of-compliance barriers that protect incumbent positions while filtering out undercapitalized entrants lacking regulatory affairs infrastructure.
For Market Incumbents: Lock in formulation chemist talent through specialized compensation structures targeting melanin biology expertise. Acquire teledermatology platform capabilities to defend against direct-to-consumer subscription erosion. Capacity addition in Indian pharmaceutical zones under PLI scheme alignment captures export competitiveness against European supply chain cost structures.
For New Entrants and Emerging Players: AI-assisted diagnostic integration offers technology-first wedge positioning against established clinic workflows. Target home-use energy device penetration as the most penetrable segment, exploiting LED and low-level laser format migration from professional to consumer channels. Deploy mobile adherence monitoring as the primary go-to-market angle to reduce treatment discontinuation rates.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational dermatology specialists seeking teledermatology capabilities and Indian manufacturing scale. Long-term viability favors biology-driven formulators with REACH-registered active ingredient portfolios and energy-based platform developers with darker phototype safety profiles. Watch NMPA and MFDS regulatory harmonization progress as the inflection indicator for Asia-Pacific market expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Standardized MASI scoring protocols reduce FDA and EMA validation timeline divergence for topical submissions. |
| Regulatory Approval Pathway | REACH registration for novel tyrosinase inhibitors creates defensible positions against commoditized synthetic competitors. |
| Manufacturing Scale-Up | PLI scheme alignment in Maharashtra and Gujarat improves export competitiveness against European incumbents. |
| Strategic Partnership | Device manufacturers partnering with teledermatology platforms capture recurring revenue through consumable attachment models. |
| Geographic Expansion | Seoul and Los Angeles clinic networks anchor picosecond laser adoption for Fitzpatrick skin types IV-VI. |
Research Methodology
Independent corroboration across dermatology clinic operators, formulation chemists, and device manufacturer product managers underwrites the qualitative findings. Primary interviews with regulatory affairs leads at multinational pharmaceutical divisions, procurement directors at hospital system dermatology departments, and R&D heads at tyrosinase-inhibitor development facilities combined with secondary validation from FDA 510(k) filings, EMA marketing authorization submissions, ClinicalTrials.gov registries, and REACH registration databases. Bottom-up patient volume modeling and top-down market sizing triangulation anchored the value estimates.
Comparable-period anchoring to historical procedural volume and topical agent dispensing patterns established the forecast baseline across the analysis window. Segmentation dimensions modeled include product type, treatment method, end user channel, and skin phototype compatibility. CAGRs derived from procedure adoption curves, subscription service growth trajectories, and regulatory approval pipeline velocity. Forecast inputs incorporated picosecond laser platform improvement rates and EU Green Deal chemical sustainability compliance timelines.
Several conditions sit outside the modeled scope, including geopolitical friction effects on Chinese precursor supply chains and unforeseen FDA hydroquinone safety threshold revisions. Forecasts reflect assumptions about patient awareness campaign effectiveness and teledermatology platform regulatory acceptance. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Microneedling Market
Dermatology
Darier Disease Drugs Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Scar Treatment Oils Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Rosacea Treatment Market
Dermatology
Dermatological Products Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
UK Scar Treatment Market
Dermatology
Acne Vulgaris Market
Dermatology
Acne Scar Treatment Market