
 Microbiome Sequencing Outsourcing Services Market | 2026-2036
Microbiome Sequencing Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Microbiome Sequencing Outsourcing Services Market Intelligence
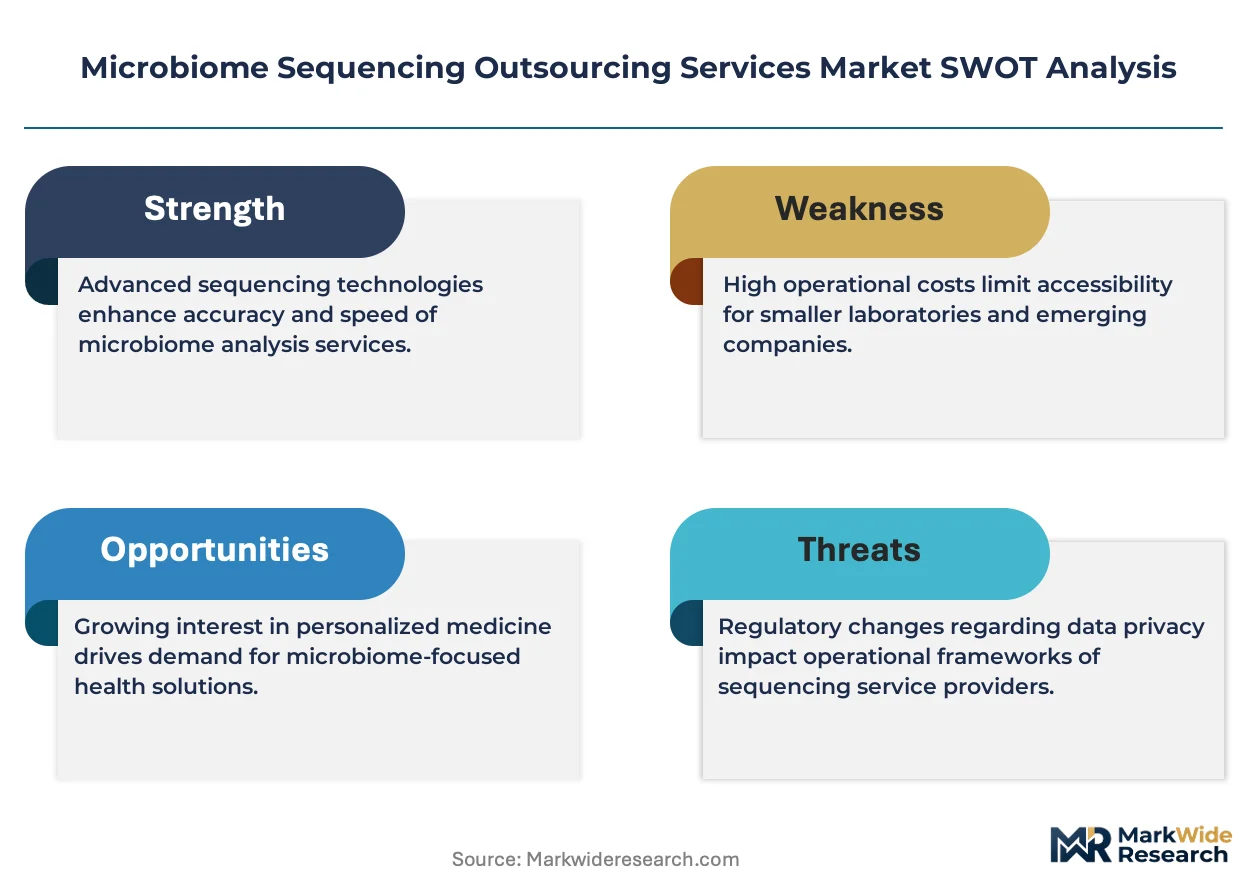
Long-read sequencing chemistry is recalibrating cost structures across microbiome analysis workflows. Illumina leverages its installed base of short-read platforms to sustain dominance in high-throughput 16S rRNA projects. Thermo Fisher Scientific anchors its position through integrated sample-to-data workflows that span extraction through bioinformatics. Eurofins Scientific differentiates by operating accredited labs across multiple European jurisdictions, reducing cross-border shipping burdens for clients.
Microbiome sequencing outsourcing services encompass contract-based DNA extraction, library preparation, sequencing, and bioinformatic analysis of microbial communities from human, animal, or environmental samples, typically targeting the 16S ribosomal RNA gene or entire metagenomes at depths exceeding 10 million reads per sample to characterize taxonomic composition and functional potential. These services enable pharmaceutical firms and research institutions to access advanced sequencing infrastructure without capital investment in instruments or specialized personnel. Next Generation Sequencing occupies the largest revenue share due to its throughput advantages, while Nanopore Sequencing is gaining traction for real-time pathogen surveillance applications where rapid turnaround outweighs per-base accuracy. Among end users, pharmaceutical companies represent the fastest-growing segment as microbiome-targeted drug programs multiply, though research institutions still dominate absolute project volume.
The FDA's evolving framework for live biotherapeutic products shapes quality expectations that sequencing providers must document, while the EMA's guidelines on microbiome-based medicinal products create parallel compliance obligations for European contract labs. ISO 15189 accreditation and CLIA certification function as gatekeeping credentials that determine which outsourcing firms can support regulated clinical trials. Stakeholders must weigh platform flexibility against regulatory documentation depth when selecting sequencing partners for programs advancing toward therapeutic approval.
Market Dynamics
Long-read sequencing chemistry is compressing turnaround times for microbiome characterization, forcing contract labs to reconfigure instrument fleets and bioinformatics pipelines to retain pharmaceutical clients advancing live biotherapeutic programs toward FDA submission.
Growth Catalysts
- Live Biotherapeutic Product Guidance:The FDA's evolving framework for microbiome-based therapeutics mandates rigorous genomic documentation, expanding sequencing demand from drug developers seeking compliant contract partners.
- Pharmaceutical Pipeline Expansion:Biotechnology firms are outsourcing end-to-end microbiome analysis for candidate strain identification and mechanistic validation without capitalizing in-house sequencing infrastructure.
- 16S rRNA Standardization:Consensus protocols for taxonomic profiling are reducing data variability, enabling multi-site clinical trials to aggregate sequencing results across accredited contract laboratories.
Market Restraints
- Reagent Supply Concentration:Library preparation kits and sequencing consumables depend on a limited set of certified suppliers, creating vulnerability to batch discontinuations or geographic trade restrictions.
- CLIA Certification Barriers:The multi-year accreditation timeline for clinical-grade microbiome testing locks smaller sequencing providers out of regulated pharmaceutical contracts.
- Short-Read Platform Lock-In:Extensive historical 16S rRNA databases bias comparative studies toward Illumina chemistry, slowing adoption of long-read alternatives despite superior resolution.
Strategic Opportunities
- Veterinary Microbiome Services:Companion animal pharmaceutical developers represent an underpenetrated client segment with comparable sequencing depth requirements and lighter regulatory documentation burdens.
- Real-Time Pathogen Surveillance:Nanopore sequencing enables same-day microbial identification for hospital infection control programs, opening service contracts outside traditional research channels.
- EMA Microbiome Guidelines:The European Medicines Agency's emerging quality standards for microbiome medicinal products create first-mover advantage for contract labs achieving dual FDA-EMA compliance.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of computational biologists proficient in metagenomic assembly and functional annotation constrains service expansion regardless of instrument capacity.
- Sample Integrity Logistics:Cold-chain maintenance for fecal and tissue specimens across international shipping routes degrades DNA quality, complicating multi-site clinical trial execution.
- Data Harmonization Complexity:Diverse bioinformatics pipelines across contract labs produce non-comparable outputs, forcing sponsors to lock into single providers for longitudinal studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbiome Sequencing Outsourcing Services Market |
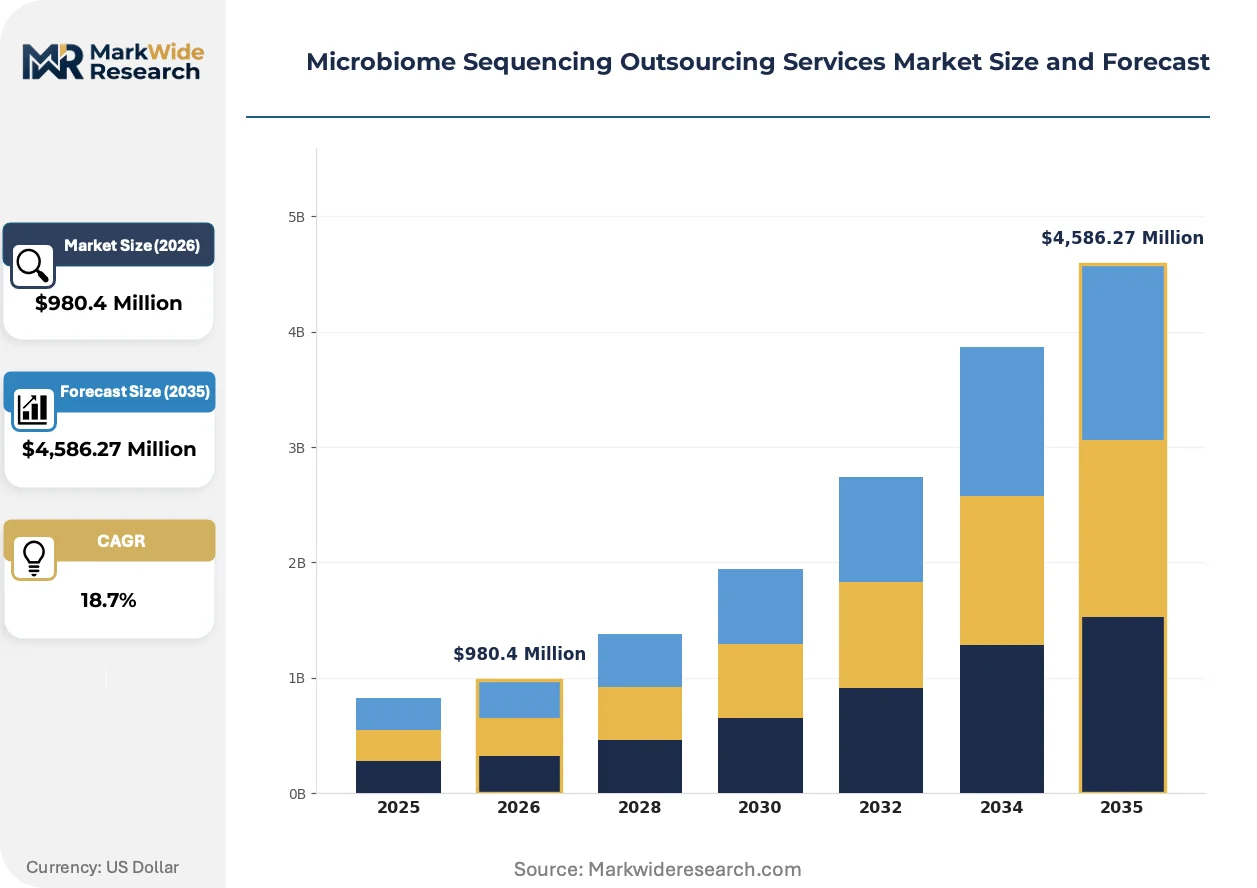
| Market Size in 2026 | $980.4 Million |
| Market Size in 2035 | $4,586.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Whole Genome Sequencing, 16S rRNA Sequencing, Metagenomic Sequencing, Shotgun Sequencing End User: Research Institutions, Pharmaceutical Companies, Healthcare Providers, Diagnostic Labs Technology: Sanger Sequencing, Next Generation Sequencing, PCR-based Sequencing, Nanopore Sequencing Application: Clinical Diagnostics, Agricultural Research, Environmental Monitoring, Personalized Medicine |
| Companies Covered | Zymo Research, Clinical Microbiomics, Illumina, Merieux Nutrisciences, Microbiome Insights, Thermo Fisher Scientific, Baseclear, Eurofins Scientific, BGI Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbiome Sequencing Outsourcing Services Market Strategic Shifts & Innovations
Sequencing providers are racing to integrate multi-omics capabilities as pharmaceutical sponsors demand unified microbiome, metabolite, and immune profiling from single contract relationships.
Third-generation long-read platforms are consolidating market share among microbiome specialists requiring strain-level resolution for mechanistic studies. Pharmaceutical toxicology groups are adopting these systems to trace engineered bacterial persistence in host tissues. The technology is consolidating previously fragmented analytical steps—amplification, sequencing, and preliminary assembly—into single-workflow offerings that compress project timelines by weeks.
The FDA's guidance on live biotherapeutic products is elevating documentation requirements for strain identity and purity verification. Contract labs must now implement redundant sequencing chemistries and validated bioinformatics pipelines to support regulatory submissions. European service providers are responding by pursuing parallel EMA qualification to capture transatlantic drug development programs seeking unified analytical standards.
Consolidated procurement models are displacing project-by-project sequencing contracts as pharmaceutical firms negotiate master service agreements with preferred providers. Large biotechnology sponsors are bundling discovery-phase 16S screening with later-stage metagenomic characterization under multi-year commitments. This concentration is most visible in the Boston and San Diego clusters, where dense sponsor populations enable contract labs to dedicate captive sequencing capacity.
Microbiome Sequencing Outsourcing Services Market Segmentation
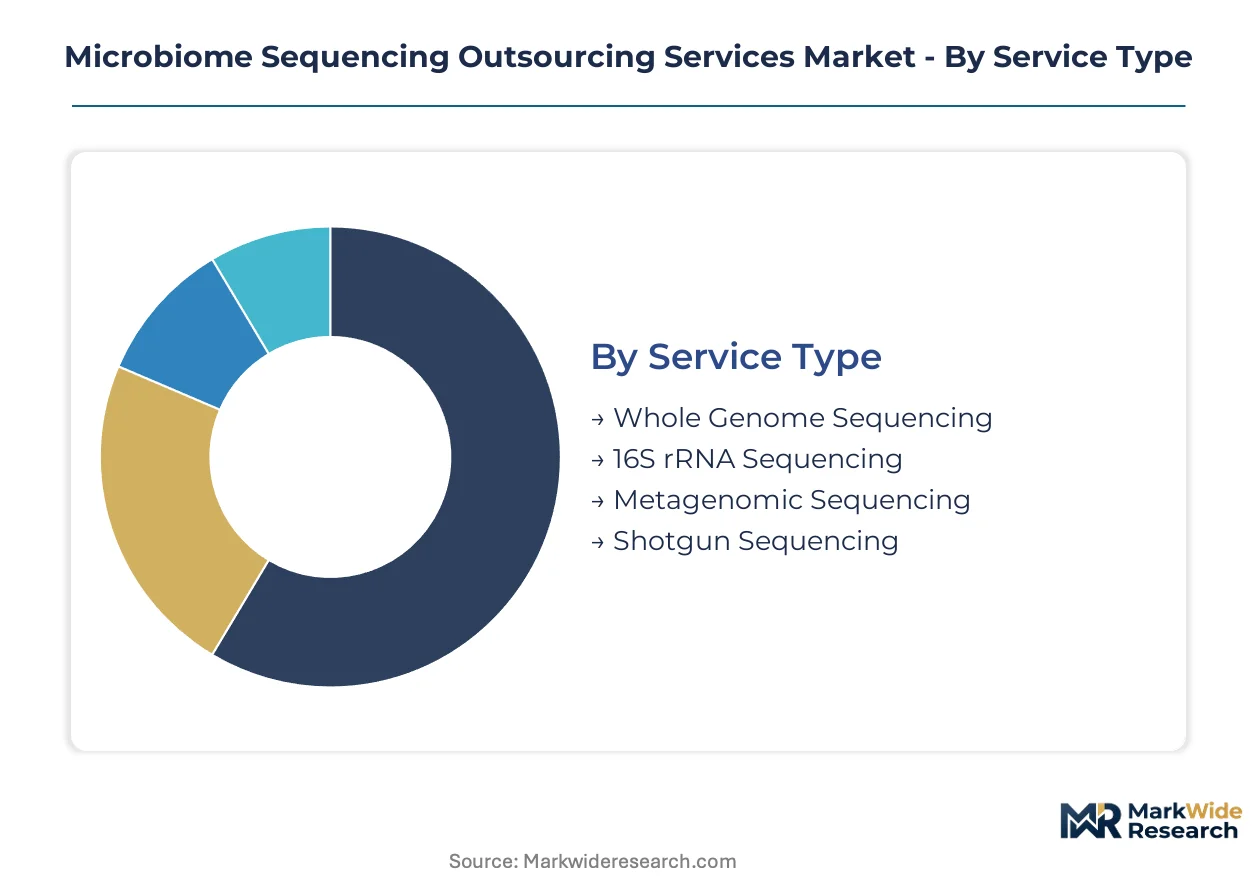
Microbiome sequencing outsourcing services fragment across four analytical dimensions that determine pricing tiers, regulatory compliance burdens, and client retention strategies. Contract laboratories configure platform investments and certification pathways differently for each segment intersection.
Service Type:
Standardized 16S rRNA protocols contrast with bespoke whole-genome workflows that demand customized bioinformatics pipelines and strain-level resolution.
- Whole Genome Sequencing:Complete chromosomal mapping of individual microbial isolates enables strain authentication for live biotherapeutic submissions. Pharmaceutical developers in Massachusetts and California concentrate demand here as FDA documentation requirements intensify for purity verification.
- 16S rRNA Sequencing:Targeted amplification of conserved ribosomal regions delivers cost-effective taxonomic profiling at genus and species resolution. Research institutions across the United States dominate project volume for ecological and clinical cohort studies where throughput outweighs strain-level precision.
- Metagenomic Sequencing:Untargeted recovery of all genetic material from complex communities enables functional gene annotation.
- Shotgun Sequencing:Random fragmentation approach captures both taxonomic and functional information without PCR bias.
Leading the category by volume: 16S rRNA Sequencing. Growing fastest: Whole Genome Sequencing.
End User:
Academic budget constraints diverge sharply from pharmaceutical procurement cycles that prioritize regulatory documentation over per-sample economics.
- Research Institutions:Universities and government laboratories drive absolute project volume through investigator-initiated grants requiring 16S screening and ecological monitoring. Funding volatility across NIH and NSF cycles compresses pricing tolerance, favoring established providers with high-throughput infrastructure.
- Pharmaceutical Companies:Biotechnology sponsors advancing microbiome therapeutics outsource mechanistic validation and strain tracking for IND-enabling studies. Boston and San Diego clusters concentrate demand for CLIA-compliant workflows supporting FDA live biotherapeutic guidance.
- Healthcare Providers:Hospital systems and integrated delivery networks pursue infection surveillance and dysbiosis profiling.
- Diagnostic Labs:Clinical reference laboratories seek accredited partnerships for microbiome-based test development.
Research Institutions command the largest share by project count. Pharmaceutical Companies are expanding most quickly as therapeutic pipelines mature.
Technology:
Platform selection trades historical database compatibility against emerging resolution capabilities that pharmaceutical toxicology groups now require.
- Next Generation Sequencing:Illumina short-read chemistry sustains dominance through installed base advantages and extensive 16S reference databases. High-throughput contract labs in Research Triangle Park and San Diego leverage this infrastructure for multi-site clinical trial aggregation.
- Nanopore Sequencing:Oxford Nanopore's long-read platforms enable real-time pathogen identification and complete plasmid tracking in engineered strains. Hospital infection control programs and veterinary surveillance networks are adopting these workflows where turnaround speed outweighs per-base error rates.
- Sanger Sequencing:First-generation capillary electrophoresis retains niche applications for targeted validation.
- PCR-based Sequencing:Amplicon-focused approaches persist in resource-constrained settings.
Next Generation Sequencing leads by revenue. Nanopore Sequencing shows the steepest expansion trajectory among emerging platforms.
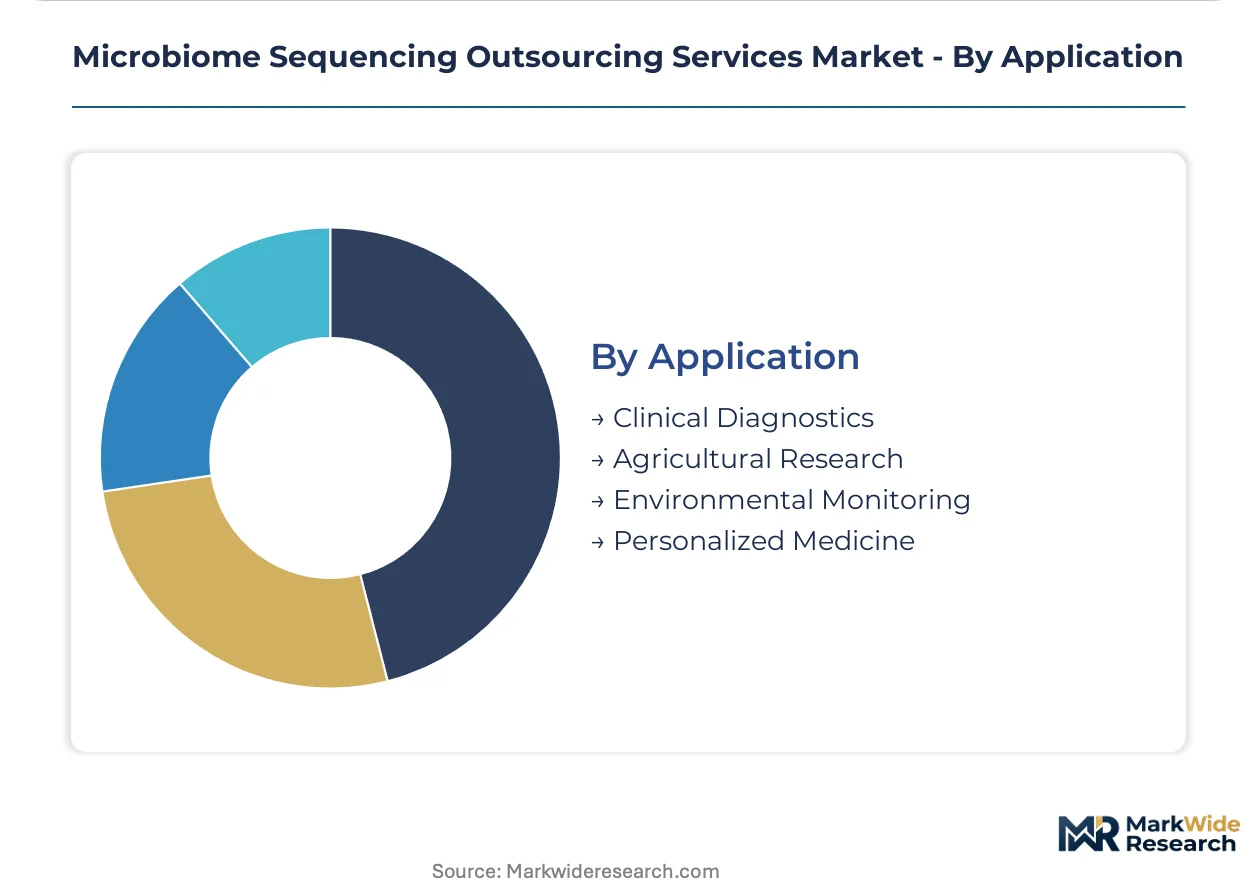
Application:
Regulatory intensity varies dramatically from unregulated agricultural field trials to FDA-scrutinized therapeutic development programs.
- Clinical Diagnostics:Microbiome profiling for disease stratification and treatment response prediction demands CLIA-certified workflows with validated bioinformatics. Diagnostic developers in California and Massachusetts pursue outsourcing partnerships for assay commercialization.
- Personalized Medicine:Patient-specific microbial characterization guides dietary intervention and probiotic selection in functional medicine practices. Direct-to-consumer testing channels and concierge medicine networks concentrate demand in metropolitan markets with disposable income concentration.
- Agricultural Research:Crop microbiome and livestock gut health studies operate with lighter documentation burdens.
- Environmental Monitoring:Soil and water microbial surveillance supports bioremediation and ecosystem health assessment.
Clinical Diagnostics leads by contract value. Personalized Medicine is gaining share fastest as consumer-facing testing platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts biotechnology tax incentives and California's life sciences R&D credits concentrate microbiome sequencing demand along both coasts of the United States. These fiscal mechanisms accelerate contract laboratory expansion near pharmaceutical clusters.
United States
FDA live biotherapeutic product guidance drives pharmaceutical sponsors toward CLIA-certified sequencing partners. Boston and San Diego biotechnology clusters outsource mechanistic validation and strain tracking for IND-enabling studies. The National Institutes of Health maintains funding pipelines for academic 16S rRNA screening projects.
Germany
EMA microbiome-based medicinal product guidelines create parallel compliance obligations for contract laboratories serving European drug developers. Munich and Heidelberg host sequencing providers pursuing dual FDA-EMA accreditation. The country's federal research ministry funds metagenomic infrastructure through national excellence initiatives.
China
NMPA regulatory pathways for microbiome therapeutics expand sequencing demand from domestic pharmaceutical firms. Beijing and Shanghai biotechnology parks attract outsourced metagenomic characterization for strain identification. Government precision medicine initiatives channel public funding toward microbial community profiling.
United Kingdom
MHRA post-Brexit regulatory frameworks reshape quality documentation requirements for sequencing providers. London and Cambridge life sciences corridors concentrate demand from academic medical centers and emerging biotechnology firms. NHS England pilot programs explore microbiome profiling for personalized intervention.
Switzerland
Swissmedic therapeutic product regulations elevate documentation standards for contract sequencing supporting clinical trials. Basel pharmaceutical headquarters outsource strain authentication and purity verification to regional providers. Federal innovation grants sustain academic-industry microbiome research partnerships.
Microbiome Sequencing Outsourcing Services Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with platform-integrated conglomerates commanding pharmaceutical contracts while boutique laboratories retain academic relationships. The vendor base organizes around three strategic archetypes: sequencing instrument manufacturers extending into services, pure-play contract research organizations with regulatory accreditation, and academic spin-outs with specialized bioinformatics capabilities. Consolidation proceeds through instrument manufacturer acquisition of regional sequencing labs and pharmaceutical sponsors negotiating multi-year master service agreements that lock in capacity.
Within the platform-integrated tier, Illumina and Thermo Fisher Scientific exemplify instrument-to-service vertical strategies that leverage installed base advantages for recurring revenue. Eurofins Scientific occupies a position among accredited contract research networks spanning multiple regulatory jurisdictions. BGI Genomics anchors the scale-driven archetype with sequencing throughput that supports population-scale microbiome projects. These three company types represent distinct competitive vectors: technology lock-in, regulatory geographic coverage, and cost-per-sample minimization.
| Leading Market Players |
|---|
| Zymo Research |
| Clinical Microbiomics |
| Illumina |
| Merieux Nutrisciences |
| Microbiome Insights |
| Thermo Fisher Scientific |
| Baseclear |
| Eurofins Scientific |
| BGI Genomics |
| Others |
Cost & Logistics Intelligence
Illumina sequencing reagent index movements cascade through contract laboratory pricing tiers, compressing margins on high-throughput 16S rRNA projects while amplifying premiums for CLIA-certified whole-genome workflows serving FDA-tracked live biotherapeutic programs.
Pricing Analysis
Expedited turnaround pricing commands substantial premiums over standard queue positioning, with pharmaceutical sponsors paying differential rates for IND-enabling strain verification timelines. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and bioinformatics depth. Cost compression in economy-tier academic screening reflects NIH funding volatility and capacity oversupply in Research Triangle Park. Research institutions exhibit highest price sensitivity, while Massachusetts biotechnology clusters prioritize documentation depth over per-sample economics.
Supply Chain Analysis
CLIA certification and ISO 15189 accreditation function as gating mechanisms that filter supplier eligibility for regulated pharmaceutical contracts. Sequencing consumable manufacturing concentrates in the United States, China, and Germany, with library preparation kit assembly anchored in San Diego and Shanghai hubs. Raw material flows draw from semiconductor-grade reagent suppliers, synthetic oligonucleotide foundries, and cold-chain logistics providers. Single-source vulnerability pervades certified sequencing chemistry supply, particularly for FDA-validated strain-tracking protocols. Distribution runs through dedicated pharmaceutical courier networks with temperature-validated chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-read sequencing platforms are displacing legacy short-read infrastructure for strain-level resolution requirements in toxicology and mechanistic validation studies.
For Market Incumbents: Anticipate margin erosion in standardized 16S rRNA screening as Nanopore sequencing captures real-time surveillance contracts. Defensive consolidation through captive bioinformatics talent acquisition in Boston and San Diego clusters addresses computational biologist scarcity. Backward integration into validated reagent manufacturing secures supply continuity against batch discontinuation risks from certified suppliers. For New Entrants and Emerging Players: Nanopore sequencing specialization offers entry leverage into veterinary pharmaceutical and hospital infection control segments with lighter regulatory documentation burdens than human therapeutic pathways. Companion animal microbiome services represent the most penetrable white-space target, with comparable sequencing depth requirements and abbreviated approval timelines. Direct-to-consumer testing platform partnerships provide channel access without proprietary sales infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor dual FDA-EMA accredited contract laboratories in Germany and Switzerland with established pharmaceutical sponsor relationships. Long-term viability hinges on multi-omics integration capabilities spanning microbiome, metabolite, and immune profiling from unified workflows. The signal to watch is EMA microbiome-based medicinal product guideline finalization, which will trigger consolidation demand for transatlantic compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Omics Platform Integration | Unified microbiome-metabolite-immune profiling from single contract relationships captures pharmaceutical bundling demand. |
| Dual FDA-EMA Accreditation | Parallel regulatory qualification opens transatlantic live biotherapeutic programs to unified analytical standards. |
| Long-Read Sequencing Fleet Expansion | Oxford Nanopore infrastructure addresses strain-level resolution requirements in toxicology persistence studies. |
| Master Service Agreement Concentration | Multi-year capacity commitments from Boston and San Diego biotechnology clusters lock in recurring revenue. |
| Bioinformatics Pipeline Validation | FDA-compliant strain identity documentation supports IND submissions for microbiome therapeutic developers. |
Research Approach
Document review covered FDA live biotherapeutic product guidance, EMA microbiome-based medicinal product draft guidelines, and ClinicalTrials.gov protocol registrations, complemented by interviews with contract laboratory operations directors, pharmaceutical regulatory affairs leads, academic principal investigators, and sequencing platform vendor account managers. Secondary validation drew from SEC filings of instrument manufacturers, NIH funding database extractions, and ISO 15189 accreditation registries. Bottom-up project volume aggregation across 50-plus service providers was cross-referenced with top-down pharmaceutical R&D spending allocation estimates.
Historical revenue trajectories were cross-referenced against expert panel input from sequencing facility directors and biotechnology sponsor procurement executives. Segmentation modeling spanned service type, end user, technology platform, and application across the projection horizon. CAGRs were derived from instrument placement forecasts, pharmaceutical pipeline progression rates, and regulatory documentation requirement evolution. Industry-specific inputs included live biotherapeutic IND submission velocity and CLIA certification timeline compression.
Several conditions sit outside the modeled scope, including abrupt reagent supply disruptions, novel sequencing chemistry breakthroughs, and regulatory framework revisions beyond current FDA and EMA draft guidance. Forecasts reflect documented assumptions regarding pharmaceutical outsourcing penetration rates and academic funding stability. A model refresh is warranted upon material change in EMA microbiome guideline finalization or NMPA regulatory pathway clarity for domestic Chinese therapeutics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Forensic Genomics Market
Genomics
Genome Sequencing Market
Genomics
UAE Genetic Testing Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Europe Epigenetics Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
Agrigenomics Market
Genomics
US Direct-To-Consumer Genetic Testing Market
Genomics
APO E Gene Test Kit Market
Genomics
Global Metagenomic Sequencing Market
Genomics
DNA Microarray Market
Genomics
Global Genotyping Assay Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Global NGS Sample Preparation Market