
 Global NGS Sample Preparation Market | 2026-2036
Global NGS Sample Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Global NGS Sample Preparation Market Foresight
Multi-source procurement of NGS sample preparation consumables is broadening as large sequencing centers diversify supplier relationships to mitigate batch-to-batch variability risks. Thermo Fisher Scientific leverages its integrated reagent-to-instrument portfolio to anchor high-throughput clinical contracts. QIAGEN differentiates through silica-membrane extraction chemistry leadership in forensic and diagnostic workflows. Illumina sustains proprietary library preparation ecosystem lock-in through its patterned flowcell sequencing architecture.
NGS sample preparation encompasses the enzymatic and mechanical processing of nucleic acids into sequencer-compatible libraries, typically involving fragmentation, adapter ligation, and amplification steps with defined insert sizes of 150–500 base pairs for short-read platforms. Library preparation reagents and kits represent the largest product category by revenue, though target enrichment technologies for oncology panel applications command premium pricing due to complex probe design requirements. Research institutions and academic centers constitute the deepest installed base, while clinical laboratories represent the fastest-growing end user segment driven by reimbursement expansion for somatic tumor profiling.
The FDA's oversight of NGS-based in vitro diagnostics under the Class II medical device framework elevates validation requirements for sample preparation kit manufacturers seeking clinical market access. The EMA's In Vitro Diagnostic Regulation and Japan's PMDA quality management standards for companion diagnostics create parallel compliance pathways that shape regional product registration strategies. Stakeholders must monitor evolving reimbursement codes for liquid biopsy applications and preemptive harmonization of analytical validation standards across notified bodies.
Market Dynamics
Automated liquid handling platforms are compressing manual protocol steps from hours to minutes, forcing reagent suppliers to redesign kit chemistries for compatibility with robotic deck layouts rather than benchtop pipetting.
Growth Catalysts
- Liquid biopsy reimbursement expansion:Medicare coverage determinations for circulating tumor DNA analysis in solid tumors are pulling clinical laboratories toward standardized, high-throughput preparation workflows.
- EMA In Vitro Diagnostic Regulation:The 2022 IVDR implementation is accelerating CE-IVD certification investments among kit manufacturers seeking European clinical market access.
- CRISPR-based enrichment:Cas9-mediated target capture is displacing hybridization probe panels in hereditary disease testing, reducing DNA input requirements and protocol duration.
Market Restraints
- Enzyme supply concentration:High-fidelity polymerase production concentrates among three contract manufacturers in the United States, creating batch consistency vulnerabilities during demand surges.
- FDA Class II device pathway:Analytical validation requirements for NGS-based companion diagnostics extend kit development timelines by 18–24 months versus research-use-only products.
- Magnetic bead cost volatility:Carboxyl-coated paramagnetic particles face price pressure from rare earth element sourcing constraints in China's processing facilities.
Strategic Opportunities
- India's CDSCO streamlined pathways:The 2023 Medical Device Rules amendments create accelerated registration for IVDs with prior US FDA or EU CE approvals, opening clinical laboratory expansion.
- Single-cell multi-omics convergence:Simultaneous DNA and RNA library preparation from individual cells is enabling new immuno-oncology biomarker discovery contracts.
- Cloud-based protocol marketplaces:Sequencing instrument vendors are launching digital repositories where laboratories download validated automated methods, creating embedded reagent subscription models.
Industry Challenges
- Bioinformatics pipeline integration:Sample preparation metadata standardization remains incomplete across LIMS platforms, forcing custom API development for automated quality control handoffs.
- Cross-platform certification burden:Clinical laboratories running both Illumina and Thermo Fisher sequencers must maintain dual validated workflows, doubling compliance documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global NGS Sample Preparation Market |
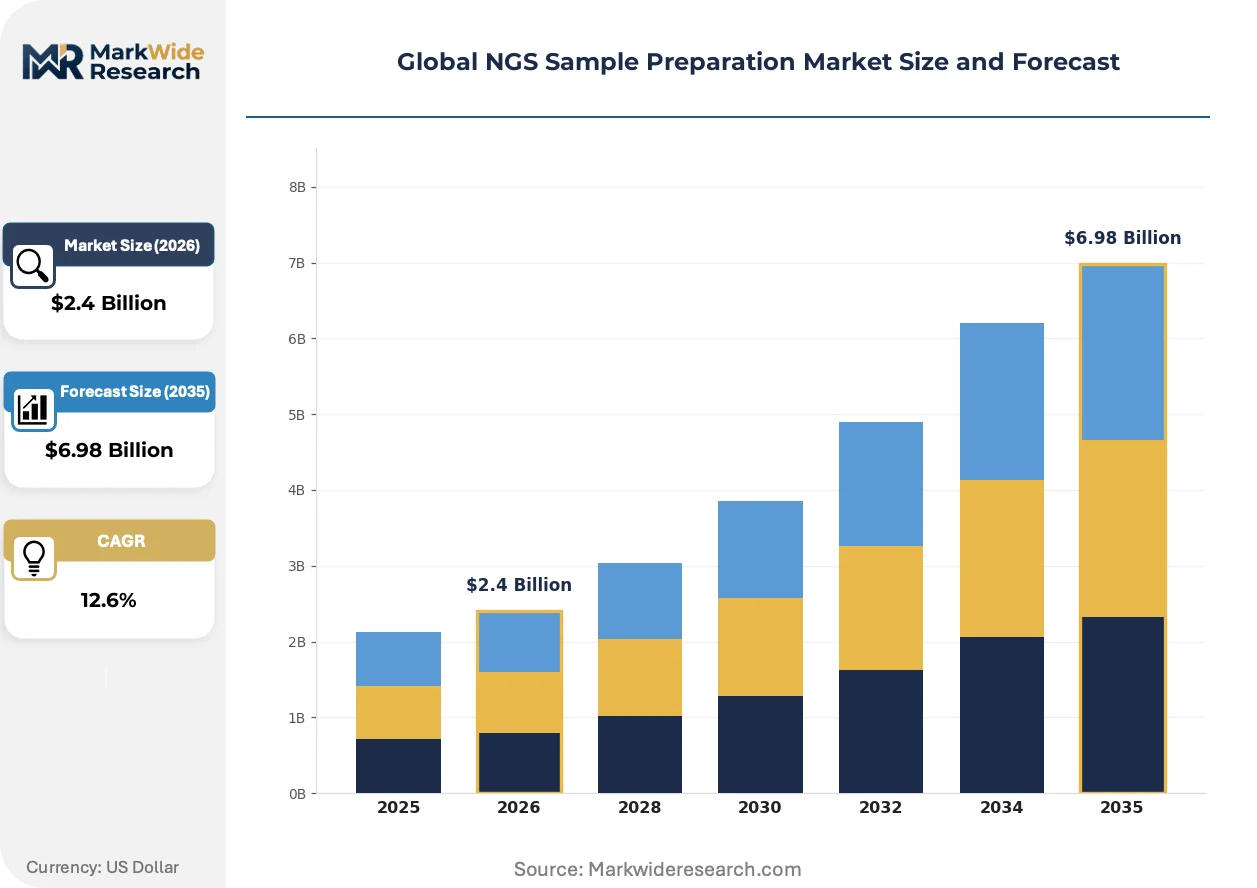
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Consumables, Instruments End User: Research Institutions, Academic Centers, Clinical Laboratories, Biotechnology Companies Technology: Library Preparation, Target Enrichment, PCR Amplification, Fragmentation Application: Oncology, Infectious Disease, Genetic Disorders, Prenatal Screening |
| Companies Covered | Agilent Technologies, PerkinElmer, Illumina, Bio-Rad Laboratories, Danaher Corporation, Thermo Fisher Scientific, Roche, Eurofins Scientific, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global NGS Sample Preparation Market Shifts & Advancements
Enzymatic fragmentation is displacing mechanical shearing as the dominant DNA preparation method, compressing instrument capital requirements while elevating reagent chemistry sophistication.
Transposase-based tagmentation is rewriting library preparation economics by combining fragmentation and adapter ligation into a single 10-minute incubation. Mid-sized clinical laboratories in the United States are adopting this chemistry fastest, drawn by reduced hands-on time and minimized sample transfer steps. The technology is compressing the addressable market for dedicated sonication equipment while expanding consumable pull-through per sequencing run.
Japan's PMDA quality management standards for companion diagnostics now mandate traceable reagent lot records across the entire preparation workflow. Kit manufacturers must implement serialized component tracking from raw enzyme batches through final packaged products. Oncology panel suppliers serving Japanese pharmaceutical partners are restructuring supply chain documentation systems to satisfy audit requirements.
Consolidated procurement through group purchasing organizations is concentrating contract negotiation power among multi-hospital networks in the United States. Independent clinical laboratories are losing price leverage as preferred vendor agreements lock sequencing centers into multi-year reagent commitments. This concentration is most visible in Texas and California, where consolidated health systems operate centralized genomics core facilities serving dozens of satellite hospitals.
Global NGS Sample Preparation Market Segmentation
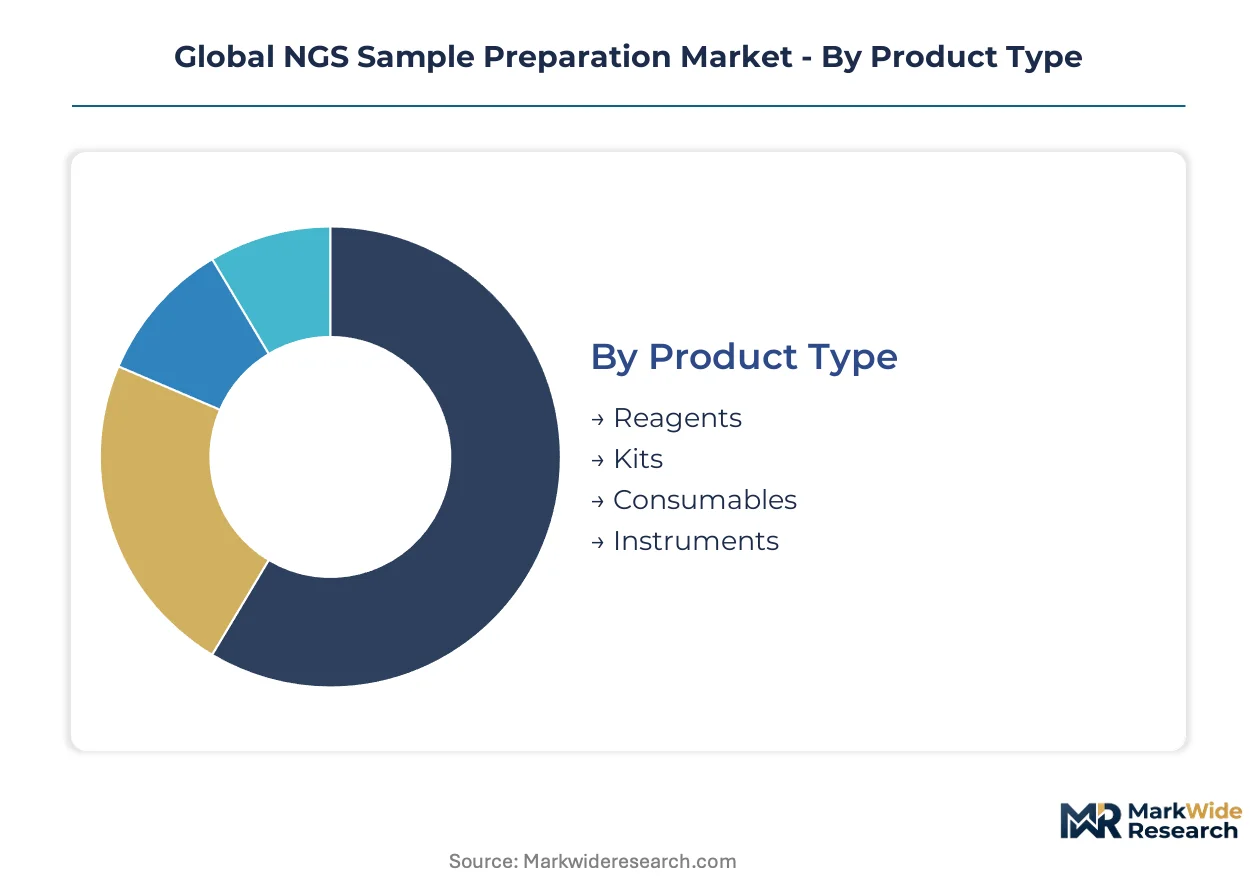
Segmentation in NGS sample preparation reveals distinct technology maturity curves and regulatory exposure profiles. Product architecture choices determine capital intensity, while end-user concentration shapes procurement contract structures across clinical and research channels.
Product Type:
Technology sophistication separates reagent chemistry from hardware automation, with margin structures diverging sharply between consumables and capital equipment.
- Reagents:Enzymatic formulations including high-fidelity polymerases, ligases, and fragmentation enzymes constitute the highest-margin consumable layer. Thermo Fisher and QIAGEN supply contracts with major sequencing centers in the United States concentrate procurement leverage for these inputs.
- Kits:Pre-formulated library preparation workflows bundle reagents with validated protocols, commanding premium pricing in clinical settings where FDA Class II compliance documentation adds regulatory value. Demand clusters in oncology reference laboratories seeking standardized turnaround times.
- Consumables:Adapter oligonucleotides, magnetic beads, and spin columns represent high-volume, lower-margin flow-through products. Magnetic bead supply from Chinese rare earth processing facilities introduces cost volatility that kit manufacturers hedge through multi-year supplier agreements.
- Instruments:Automated liquid handling platforms and integrated library preparation systems require substantial capital outlay. Academic core facilities in Germany and Japan delay replacement cycles amid budget constraints, extending installed base amortization periods.
Reagents lead on scale; kits lead on momentum.
End User:
Customer type determines validation burden and pricing elasticity, with clinical adopters accepting substantial premiums for regulatory-compliant workflows.
- Research Institutions:Academic genomics cores operate diverse sequencing platforms, demanding flexible kit chemistries compatible with multiple instrument vendors. Budget fragmentation across principal investigator grants complicates volume-based procurement negotiations.
- Academic Centers:University-affiliated facilities balance research flexibility with emerging clinical translation requirements. CDSCO streamlined pathways in India attract academic-industry partnership investments for companion diagnostic development.
- Clinical Laboratories:CAP-accredited and CLIA-certified facilities require end-to-end traceability and lot-specific performance data. Medicare reimbursement expansion for liquid biopsy applications in the United States accelerates high-throughput automation adoption.
- Biotechnology Companies:Pharmaceutical and diagnostic developers prioritize scalable, GMP-compatible preparation workflows for biomarker discovery and clinical trial support. EMA IVDR implementation drives CE-IVD certification investments among European biotech partners.
Clinical laboratories expand most quickly; biotechnology companies concentrate highest-value contracts.
Technology:
Workflow integration depth separates discrete processing steps from consolidated chemistries, with protocol duration and hands-on time as critical selection criteria.
- Library Preparation:The foundational enzymatic workflow encompassing fragmentation, end-repair, A-tailing, and adapter ligation. Transposase-based tagmentation is compressing protocol duration from hours to minutes in mid-sized United States clinical laboratories.
- Target Enrichment:Hybridization capture and CRISPR-Cas9-mediated selection isolate genomic regions of interest. Complex probe design requirements for oncology panels sustain premium pricing despite CRISPR-based alternatives displacing hybridization in hereditary disease testing.
- PCR Amplification:Post-ligation library amplification balances yield against amplification bias. High-fidelity polymerase supply concentration among three United States contract manufacturers creates batch consistency vulnerabilities.
- Fragmentation:Mechanical shearing and enzymatic methods reduce DNA to defined insert sizes. Enzymatic approaches displace sonication equipment, eliminating capital expenditure for dedicated instrumentation.
Library preparation dominates installed base; target enrichment captures steepest expansion trajectory.
Application:
Disease area selection determines panel complexity, sample type, and reimbursement environment, with oncology commanding disproportionate R&D investment.
- Oncology:Somatic tumor profiling and liquid biopsy applications drive highest kit consumption per test. Companion diagnostic development for targeted therapies mandates rigorous analytical validation under FDA and PMDA oversight.
- Infectious Disease:Pathogen genomic surveillance and antimicrobial resistance profiling expanded during pandemic response infrastructure buildout. Wastewater surveillance programs in Singapore and the Netherlands sustain demand for high-throughput preparation workflows.
- Genetic Disorders:Rare disease diagnosis and carrier screening utilize exome and genome sequencing approaches. Cas9-mediated target capture reduces DNA input requirements for pediatric and prenatal samples with limited material availability.
- Prenatal Screening:Non-invasive prenatal testing for fetal aneuploidy represents a maturing application with consolidated vendor relationships. Reimbursement pressure in the United States compresses margins despite stable test volumes.
Oncology leads on revenue concentration; infectious disease shows strongest post-pandemic infrastructure leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as kit producers seek jurisdictions with streamlined clinical validation pathways. Cost-of-compliance gaps between the FDA's Class II framework and emerging alternatives are redirecting investment toward markets offering accelerated device registration.
United States
Concentrated biopharma R&D spending and major reference laboratory networks drive kit consumption. The FDA's classification of certain NGS-based tests as Class II medical devices tightens quality benchmarks for domestic suppliers. Texas and California host consolidated health systems operating centralized genomics core facilities serving dozens of satellite hospitals.
Germany
Academic core facilities operate diverse sequencing platforms amid budget constraints extending instrument replacement cycles. The EMA's In Vitro Diagnostic Regulation accelerates CE-IVD certification investments among European kit manufacturers. Bavaria's research clusters maintain deep installed bases of flexible chemistries compatible with multiple instrument vendors.
China
Rare earth element processing facilities supply carboxyl-coated paramagnetic particles facing cost volatility from sourcing constraints. The NMPA's quality management standards for companion diagnostics mandate traceable reagent lot records across preparation workflows. Yangtze River Delta sequencing centers diversify supplier relationships to mitigate batch-to-batch variability risks.
Japan
PMDA quality management standards now require serialized component tracking from raw enzyme batches through final packaged products. Pharmaceutical partners restructure supply chain documentation systems to satisfy audit requirements. Kanto region oncology panel suppliers implement end-to-end traceability systems for companion diagnostic development.
India
CDSCO streamlined pathways create accelerated registration for IVDs with prior US FDA or EU CE approvals. Academic-industry partnerships expand for companion diagnostic development targeting clinical laboratory growth. Maharashtra's emerging genomics infrastructure attracts contract manufacturing investments from multinational kit producers.
Global NGS Sample Preparation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automated workflow integration and cloud-based protocol distribution. The market structure concentrates around integrated reagent-to-instrument portfolios, silica-membrane extraction specialists, and proprietary sequencing ecosystem providers. Three archetypes dominate: full-stack platform vendors, chemistry-focused consumable suppliers, and sequencing instrument-anchored ecosystem players. Competitive moves center on multi-year reagent commitment contracts through group purchasing organizations and CE-IVD certification investments for European clinical market access.
Among diversified life science conglomerates, Thermo Fisher Scientific, Danaher Corporation, and Agilent Technologies represent the integrated platform archetype. These entities anchor high-throughput clinical contracts through bundled instrument and consumable offerings. QIAGEN and Bio-Rad Laboratories exemplify chemistry-specialist positioning, with the former leveraging membrane-based extraction leadership. Illumina occupies a distinct ecosystem-anchored position through proprietary library preparation compatibility with its patterned flowcell architecture.
| Leading Market Players |
|---|
| Agilent Technologies |
| PerkinElmer |
| Illumina |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Roche |
| Eurofins Scientific |
| QIAGEN |
| Others |
Supply & Pricing Matrix
Enzyme biochemist concentrations in the Boston-Cambridge corridor and San Diego biotech clusters feed directly into kit manufacturing labor-cost differentials, widening spreads between FDA-validated premium tiers and research-use-only economy positioning.
Pricing Analysis
Distributor margins on library preparation kits typically capture 15-25% before reaching clinical laboratories, though direct-to-OEM contracts for high-throughput sequencing centers compress this layer substantially. Pricing stratifies across CE-IVD certified premium tiers, research-grade standard tiers, and unvalidated economy chemistries, with FDA Class II compliance documentation commanding the steepest premiums. Cost compression in the economy tier intensifies as Chinese magnetic bead suppliers extend volume discounts to Asian kit assemblers. Biotechnology companies show least price sensitivity due to GMP workflow requirements, while academic cores exhibit highest elasticity and multi-vendor quote comparison behavior.
Supply Chain Analysis
Dual-sourcing requirements from CAP-accredited clinical laboratories mandate qualified backup suppliers for high-fidelity polymerases, forcing kit manufacturers to maintain validated relationships with at least two of the three dominant United States contract enzyme producers. Manufacturing concentrates in the United States, Germany, and China, with the latter controlling carboxyl-coated paramagnetic particle output through rare earth processing facilities. Raw material dependencies center on recombinant enzyme fermentation, synthetic oligonucleotide synthesis, and magnetic bead coatings. Single-source vulnerability in thermostable polymerase supply creates acute disruption risk during demand surges. Distribution runs through specialized life science distributors and direct field service teams for automated platform placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in NGS sample preparation rests on transposase-based chemistry cost-down trajectories and the premium-tier shift toward companion diagnostic-validated workflows.
For Market Incumbents: Anchor high-throughput clinical contracts through multi-year reagent subscription models tied to automated liquid handling platforms, insulating against CRISPR-based enrichment displacement in hereditary disease testing. Deepen backward integration into high-fidelity polymerase production to reduce batch consistency vulnerabilities from concentrated contract manufacturing. Prioritize CE-IVD certification investments ahead of EMA IVDR enforcement waves. For New Entrants and Emerging Players: Begin with cloud-based protocol marketplace partnerships that embed reagent pull-through through sequencer vendor digital repositories, targeting mid-sized United States clinical laboratories adopting tagmentation fastest. Penetrate India's CDSCO streamlined pathway segment by leveraging prior FDA or EU CE approvals for accelerated registration. Pursue academic-industry partnership structures for companion diagnostic development contracts. For Investors and Strategic Acquirers: Sequencing instrument vendors are the most active acquirer in this space, seeking captive reagent ecosystems to match Illumina's patterned flowcell architecture lock-in. Long-term viability favors targets with validated automated workflow integration and serialized component tracking systems for PMDA compliance. Watch liquid biopsy reimbursement expansion velocity as the signal for high-throughput automation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Certification Investment | EMA IVDR compliance opens European clinical laboratory access and premium pricing tiers. |
| Automated Liquid Handling Integration | Robotic deck compatibility compresses protocol duration and locks reagent subscription revenue. |
| Cloud-Based Protocol Marketplace Launch | Sequencer vendor digital repositories embed validated methods and consumable pull-through. |
| Serialized Component Tracking Implementation | PMDA quality standards mandate lot traceability from enzyme batches through final packaging. |
| Transposase-Based Tagmentation Scale-Up | Single-step chemistry reduces hands-on time and displaces dedicated sonication equipment capital. |
Research Methodology
Direct dialogue with sequencing core directors, clinical laboratory quality managers, reagent kit product managers, and GPO contracts specialists grounded the qualitative foundation, cross-referenced against FDA 510(k) filings, EMA IVDR technical documentation, CDSCO registration databases, and Medicare coverage determination records. Secondary validation drew from CAP proficiency testing reports, NMPA quality management bulletins, and PMDA audit inspection summaries. Bottom-up installed base estimates and top-down biopharma R&D spending trajectories were reconciled through iterative triangulation.
Segment-level revenue projections across reagents, kits, consumables, and instruments were generated through the analytical framework, with oncology panel demand, liquid biopsy reimbursement velocity, and CRISPR enrichment adoption curves as primary demand drivers. CAGRs were derived from regression-weighted scenario outputs. Modeled dimensions spanned product architecture, end-user certification tier, workflow integration depth, and regional regulatory pathway complexity.
Several conditions sit outside the modeled scope, including unforeseen FDA reclassification of additional NGS-based tests, sudden rare earth export restrictions from Chinese magnetic bead suppliers, and disruptive single-molecule sequencing platform commercialization. Deviation in Medicare liquid biopsy reimbursement expansion velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Plant Genomics Market
Genomics
Genomic Biomarkers Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Multiomics Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
UAE Genetic Testing Market
Genomics
Forensic Genomics Market
Genomics
Genetic Testing Panels Market
Genomics
Omics Lab Services Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Personal Genome Testing Market
Genomics
China Genetic Testing Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
DNA Sequencing Services Market