
 Global Microbiome Therapeutics Market | 2026-2036
Global Microbiome Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbiome Therapeutics Market Foresight
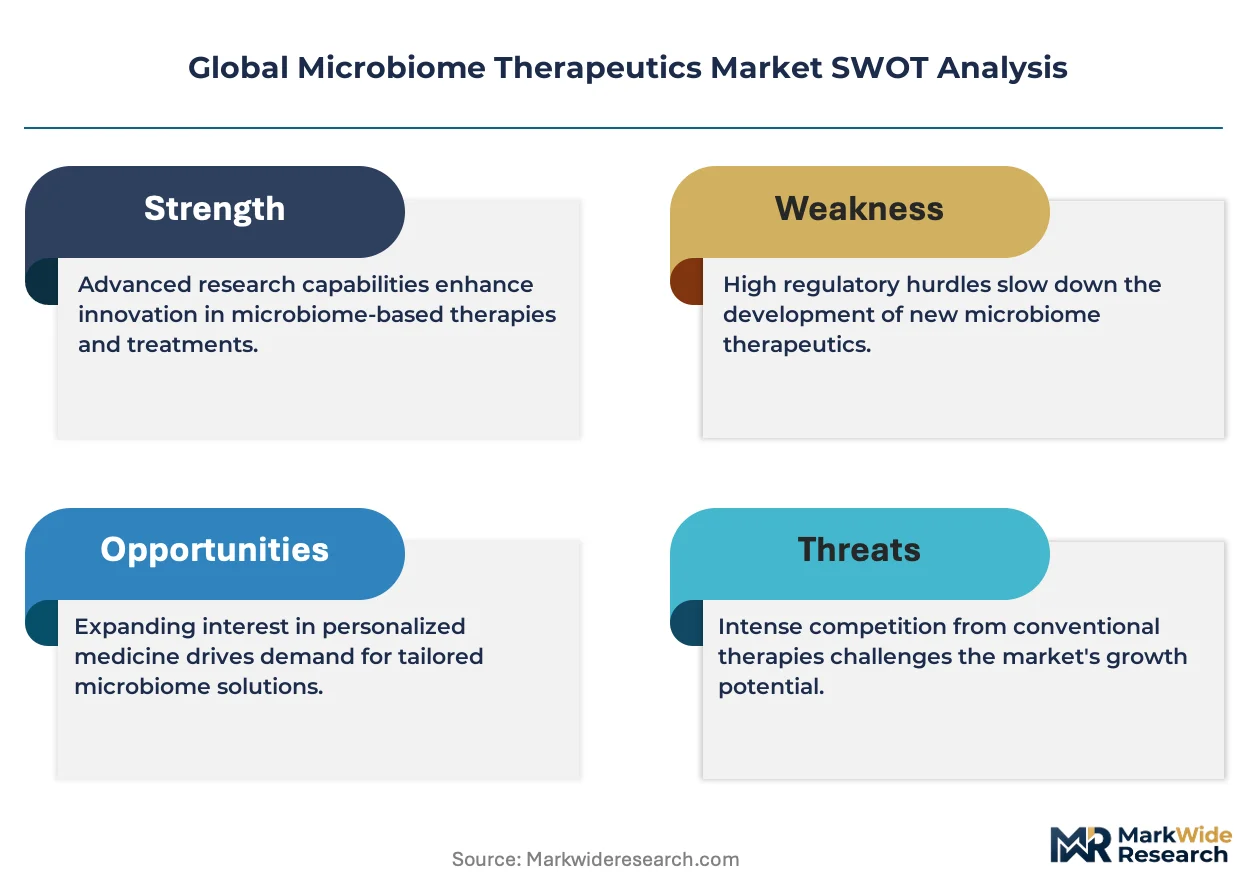
FDA's 2023 guidance on live biotherapeutic products is restructuring the cost-of-entry calculus for microbiome drug developers, forcing candidates into rigorous quality-attribute frameworks before Phase II. Seres Therapeutics leverages its end-to-end manufacturing infrastructure to sustain commercial supply of its approved C. difficile therapy. Vedanta Biosciences anchors its position through defined bacterial consortia designed for reproducible colonization kinetics. Ferring competes via established gastroenterology channels that accelerate physician adoption of microbiome interventions.
Microbiome therapeutics comprise live, attenuated, or inactivated microorganisms, their cellular components, or metabolites formulated to modulate host microbial ecology and restore homeostatic immune and metabolic function; these products typically require cryopreservation or specialized encapsulation to maintain viability through gastric transit. Oral capsules dominate current delivery mode revenue due to patient compliance advantages and scalable fill-finish manufacturing, while liquid suspension formats are gaining fastest in pediatric and nasogastric tube populations. Gastrointestinal disorders occupy the largest therapy area share with established payer pathways, though neurological conditions represent the emerging margin pool as gut-brain axis mechanisms attract neurodegenerative drug development funding.
FDA, EMA, and Japan's PMDA collectively shape microbiome therapeutic standards through divergent live-product classification schemes that fragment global development strategies and force region-specific CMC packages. The EU AI Act and GDPR impose additional constraints on computational microbiome analysis pipelines used for patient stratification. Stakeholders must monitor how rapidly national health technology assessment bodies construct reimbursement categories for live biotherapeutics versus traditional small molecules.
Market Dynamics
The microbiome therapeutics sector pivots on accelerated regulatory clarification from FDA, EMA, and PMDA, which is compressing development timelines while simultaneously elevating chemistry, manufacturing, and controls standards that favor vertically integrated manufacturers over asset-light developers.
Growth Catalysts
- Live Biotherapeutic Product Guidance:FDA's 2023 framework provides definitive quality-attribute benchmarks that reduce regulatory uncertainty and accelerate Investigational New Drug application approvals for defined consortia.
- Japan's PMDA Fast-Track Designation:Japan's regulator offers priority review pathways for microbiome-based drugs targeting unmet gastrointestinal needs, channeling clinical trial investment toward Tokyo and Osaka research clusters.
- CRISPR-Engineered Consortia:Precision genome editing enables rational design of bacterial communities with predictable colonization kinetics, replacing empirical strain selection and shortening preclinical phases.
Market Restraints
- Cryopreservation Infrastructure Concentration:Viable cell maintenance requires liquid nitrogen cold chain networks concentrated in the United States and Germany, limiting trial site expansion in emerging markets.
- EU AI Act Constraints:The European Union's artificial intelligence regulation imposes validation requirements on computational microbiome analysis pipelines used for patient stratification, increasing algorithm development costs.
- Small-Molecule Substitution:Traditional antibiotics and immunosuppressants retain entrenched reimbursement codes and physician familiarity for C. difficile and inflammatory bowel disease, slowing live biotherapeutic adoption.
Strategic Opportunities
- Pediatric Liquid Formulations:Nasogastric tube-compatible suspensions address an underserved population in pediatric hospitals across France and the United Kingdom, opening volume pools beyond oral capsule dominance.
- Gut-Brain Axis Applications:Neurodegenerative drug development funding is redirecting toward microbiome modulation for Parkinson's and Alzheimer's, creating margin expansion beyond gastrointestinal disorders.
- Outcome-Based Reimbursement Pilots:Germany's health technology assessment bodies are constructing novel payment categories for live biotherapeutics that reward durable remission rather than treatment administration.
Industry Challenges
- Microbial Strain Banking Complexity:Master cell bank qualification and working cell bank maintenance require specialized facilities with biosafety level containment that few contract manufacturers possess.
- Cross-Jurisdictional CMC Divergence:FDA, EMA, and PMDA employ divergent live-product classification schemes that force developers to construct region-specific regulatory packages, fragmenting global launch strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbiome Therapeutics Market |
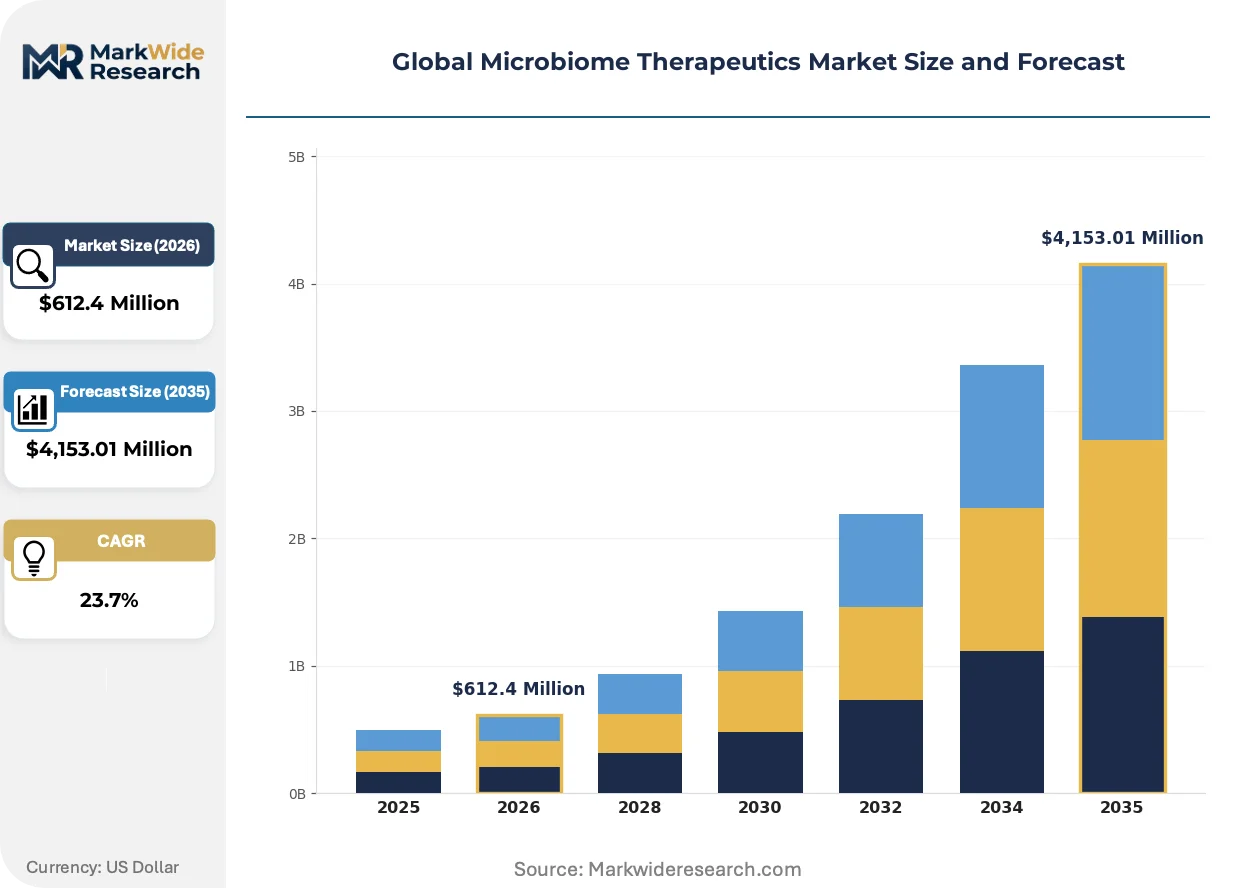
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $4,153.01 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Synbiotics, Fecal Microbiota Transplantation, Postbiotics Therapy Area: Gastrointestinal Disorders, Metabolic Diseases, Neurological Conditions, Immunological Disorders, Dermatological Conditions Delivery Mode: Oral Capsules, Liquid Suspension, Rectal Enema, Topical Formulations, Injectable Solutions End User: Hospitals, Specialty Clinics, Research Institutes, Biopharmaceutical Firms, Contract Research Organizations |
| Companies Covered | Seres Therapeutics, Ferring, Vedanta Biosciences, MaaT Pharma, Finch Therapeutics Group, Enterome, Nestlé Health Science, Evelo Biosciences, 4D Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbiome Therapeutics Market Shifts & Advancements
Synthetic ecology platforms and advanced encapsulation technologies are restructuring how live biotherapeutics achieve gastric transit survival, with computational design tools now enabling rational consortium assembly rather than empirical screening.
Synthetic ecology design platforms is overtaking traditional fecal microbiota transplantation as the dominant preclinical approach. Large pharmaceutical sponsors and specialized biotechs in Boston and Basel are adopting these tools to engineer defined bacterial consortia with reproducible pharmacokinetic profiles. The technology is compressing strain selection timelines from years to months while eliminating donor variability risks that plagued earlier-generation products.
EMA's evolving stance on live biotherapeutic classification is forcing developers to navigate between medicinal product and tissue framework designations. This regulatory ambiguity is creating strategic positioning battles as sponsors seek optimal approval pathways before centralized marketing authorization applications. German and Dutch regulatory consultants report accelerating demand for classification determination procedures as pipelines mature toward Phase II.
Hospital pharmacy committees are consolidating microbiome therapeutic procurement under centralized formularies rather than individual physician prescribing. Gastroenterology departments in United States academic medical centers now route live biotherapeutic requests through infectious disease stewardship programs that evaluate cost-per-remission against standard-of-care antibiotics. This behavioral shift elevates the importance of health-economic evidence packages and real-world colonization durability data in competitive positioning.
Global Microbiome Therapeutics Market Segmentation
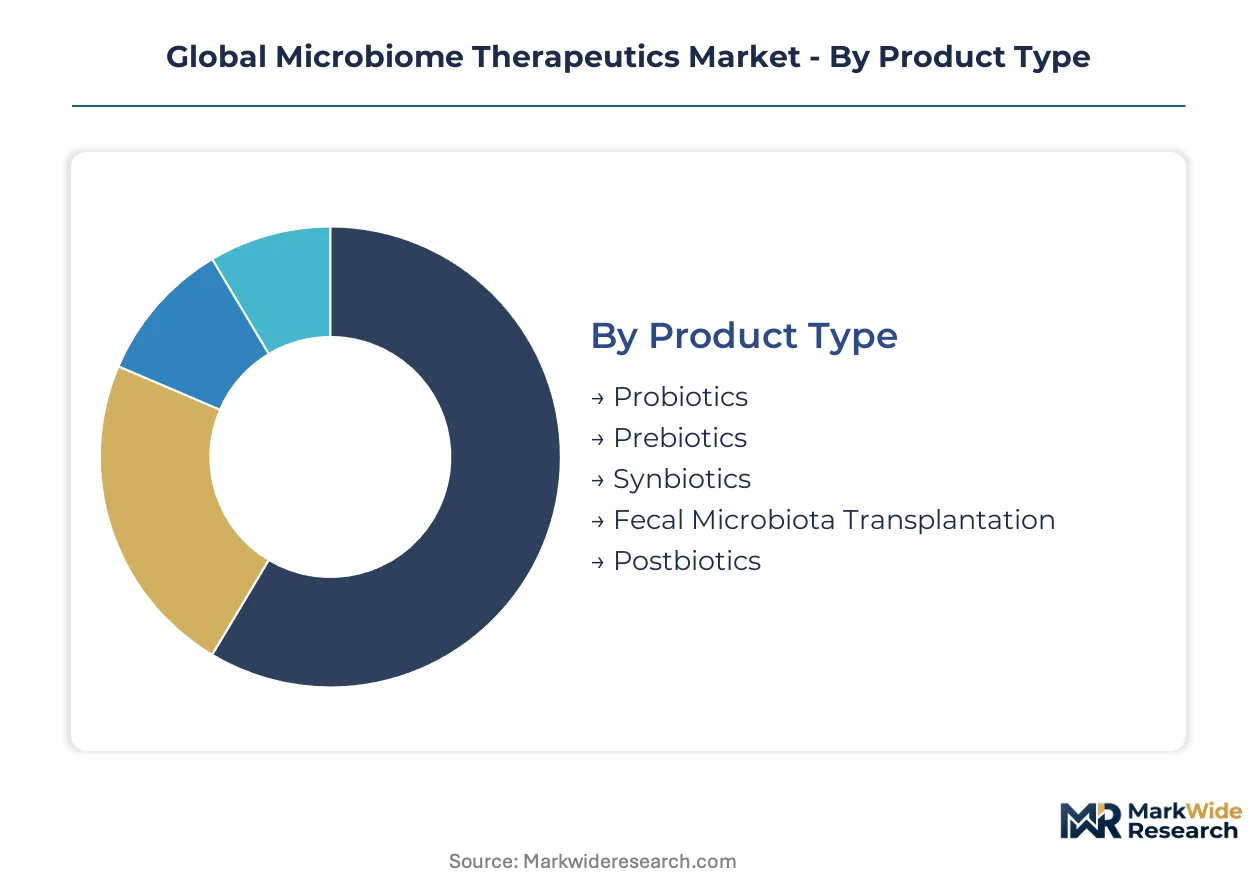
Microbiome therapeutic segmentation reflects competing technical philosophies on microbial viability maintenance and target site delivery. Product format decisions cascade through manufacturing infrastructure requirements, cold chain logistics, and regulatory classification pathways.
Product Type:
Formulation chemistry determines stability windows, colonization kinetics, and intellectual property defensibility across development pipelines.
- Probiotics:Live microorganisms formulated in cryopreserved or lyophilized states to survive gastric transit and establish colonization in target niches. Demand concentrates in United States hospital networks where FDA's live biotherapeutic guidance provides definitive quality benchmarks for Investigational New Drug submissions.
- Fecal Microbiota Transplantation:Whole-community preparations derived from screened donor material, requiring specialized biosafety containment and rigorous donor qualification protocols. Germany's hospital procurement committees route these through infectious disease stewardship programs that evaluate cost-per-remission against standard antibiotics.
- Prebiotics:Non-digestible substrates that selectively nourish beneficial commensal populations.
- Synbiotics:Combined formulations pairing live organisms with targeted nutrient substrates.
- Postbiotics:Inactivated microbial components or metabolites offering immunomodulatory function without viability maintenance requirements.
Probiotics lead on scale; postbiotics gain share fastest as cold chain constraints limit live-product distribution.
Therapy Area:
Clinical indication selection shapes reimbursement pathway construction and health-economic evidence requirements for market access.
- Gastrointestinal Disorders:C. difficile infection, inflammatory bowel disease, and irritable bowel syndrome constitute the established revenue base with defined payer categories. Japan's PMDA fast-track designation channels trial investment toward Tokyo and Osaka research clusters for unmet gastrointestinal needs.
- Neurological Conditions:Parkinson's disease and Alzheimer's disease applications target gut-brain axis mechanisms with neurodegenerative drug development funding redirecting toward microbiome modulation. Boston and Basel biotechs are engineering defined consortia for blood-brain barrier penetration studies.
- Metabolic Diseases:Type 2 diabetes and non-alcoholic steatohepatitis interventions.
- Immunological Disorders:Autoimmune and allergic condition applications.
- Dermatological Conditions:Atopic dermatitis and psoriasis topical or systemic microbiome modulation.
Gastrointestinal disorders anchor current revenue; neurological conditions climb the fastest as mechanistic understanding deepens.
Delivery Mode:
Route of administration determines encapsulation technology requirements, patient compliance profiles, and manufacturing scale-up complexity.
- Oral Capsules:Enteric-coated or cryoprotected formats dominating current revenue due to patient compliance advantages and scalable fill-finish manufacturing. United States and German production facilities concentrate oral dose form capacity.
- Liquid Suspension:Nasogastric tube-compatible formats gaining traction in pediatric hospitals across France and the United Kingdom where swallowing difficulties prevent capsule administration.
- Rectal Enema:Lower gastrointestinal delivery for ulcerative colitis and pouchitis applications.
- Topical Formulations:Cutaneous microbiome modulation for dermatological conditions.
- Injectable Solutions:Parenteral routes for systemic immunomodulation requiring sterile manufacturing.
Oral capsules dominate volume; liquid suspension expands most quickly in pediatric and enteral feeding populations.
End User:
Customer type dictates sales force structure, evidence package design, and procurement decision-making authority.
- Hospitals:Academic medical centers and community hospital networks consolidating microbiome therapeutic procurement under centralized formularies. United States gastroenterology departments now route requests through infectious disease stewardship programs.
- Biopharmaceutical Firms:Large pharmaceutical sponsors in Boston and Basel adopting synthetic ecology platforms for rational consortium design, compressing strain selection timelines.
- Specialty Clinics:Gastroenterology and functional medicine focused outpatient facilities.
- Research Institutes:Academic and government laboratories conducting mechanistic microbiome studies.
- Contract Research Organizations:Service providers supporting clinical trial execution and regulatory submission preparation.
Hospitals lead on procurement scale; biopharmaceutical firms lead on R&D investment momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized microbiome research talent concentrates in Boston, Basel, and Tokyo, anchoring global clinical trial execution and regulatory strategy for live biotherapeutic developers.
United States
FDA's 2023 live biotherapeutic product guidance attracts Investigational New Drug submissions from developers seeking definitive quality-attribute benchmarks. Hospital networks in Massachusetts and California expand centralized formulary procurement of microbiome therapies through infectious disease stewardship programs. The Greater Boston biotech corridor houses synthetic ecology platform companies engineering CRISPR-modified bacterial consortia.
Germany
Health technology assessment bodies in Berlin construct novel reimbursement categories for live biotherapeutics that reward durable remission outcomes. EMA's evolving classification frameworks between medicinal product and tissue designations create strategic positioning battles for sponsors filing centralized marketing authorization applications. Hospital procurement committees in Munich and Heidelberg route fecal microbiota transplantation through cost-per-remission evaluations against standard antibiotics.
Japan
PMDA fast-track designation channels clinical trial investment toward Tokyo and Osaka research clusters addressing unmet gastrointestinal needs. Cryopreservation infrastructure for viable cell maintenance concentrates in Kanto region facilities serving Phase II and Phase III microbiome studies. Japanese pharmaceutical sponsors partner with domestic biotechs to access priority review pathways for defined bacterial consortia.
United Kingdom
Pediatric hospitals in London and Manchester drive nasogastric tube-compatible liquid suspension demand for populations unable to swallow oral capsules. The Medicines and Healthcare products Regulatory Agency aligns with EMA frameworks while maintaining distinct national marketing authorization procedures for live biotherapeutics. Oxford and Cambridge research institutes attract neurodegenerative drug development funding targeting gut-brain axis mechanisms.
Switzerland
Swissmedic's regulatory clarity on live biotherapeutic classification attracts development-stage companies seeking predictable approval timelines. Basel-based pharmaceutical sponsors adopt synthetic ecology platforms for rational consortium design, compressing strain selection timelines from years to months. The country's specialized biosafety containment facilities support master cell bank qualification for advanced therapy medicinal products.
Global Microbiome Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the microbiome therapeutics sector, creating a tiered structure where manufacturing scale and regulatory expertise determine competitive position. Large pharmaceutical sponsors leverage established gastroenterology channels and end-to-end manufacturing infrastructure to accelerate physician adoption. Three archetypes dominate: vertically integrated biotechs with captive production capabilities, synthetic ecology platform companies offering rational consortium design services, and diversified nutrition-pharma hybrids extending into live biotherapeutics. Competitive moves concentrate on strategic partnerships for cryopreservation infrastructure access and technology licensing agreements for CRISPR-engineered strain libraries.
Among United States-based developers, Seres Therapeutics and Vedanta Biosciences exemplify contrasting strategic positions within the pure-play specialist tier. Seres occupies a position representing vertically integrated manufacturing archetypes with end-to-end infrastructure for commercial supply sustainability. Vedanta sits within the defined consortia design segment, anchoring reproducible colonization kinetics capabilities. Ferring, a European pharmaceutical sponsor, represents the diversified incumbent archetype competing through established physician relationships and gastroenterology channel access rather than platform technology differentiation.
| Leading Market Players |
|---|
| Seres Therapeutics |
| Ferring |
| Vedanta Biosciences |
| MaaT Pharma |
| Finch Therapeutics Group |
| Enterome |
| Nestlé Health Science |
| Evelo Biosciences |
| 4D Pharma |
| Others |
Supply & Pricing Matrix
Specialized cryopreservation technicians in Massachusetts and Basel command wage premiums that compress margin spreads between premium live biotherapeutic consortia and standard probiotic formulations, forcing manufacturers to tier pricing by viability maintenance complexity rather than strain count alone.
Pricing Analysis
Bundled service contracts encompassing master cell bank qualification, cold chain logistics, and real-time colonization monitoring command price premiums over unbundled per-dose transactions. Pricing stratifies across premium, standard, and economy tiers based on CRISPR-engineered strain specificity and FDA live biotherapeutic guidance compliance level. Cost compression in standard-tier probiotics is intensifying because hospital procurement committees route requests through infectious disease stewardship programs that evaluate cost-per-remission metrics. Pediatric liquid suspension formats exhibit highest price sensitivity due to nasogastric tube administration constraints limiting reimbursement flexibility, while CRISPR-engineered consortia for neurological applications show lowest sensitivity given neurodegenerative drug development funding abundance.
Supply Chain Analysis
Dual-sourcing requirements from hospital pharmacy committees mandate multi-supplier qualification for live biotherapeutic procurement, forcing developers to maintain redundant master cell bank relationships. Geographic supply concentration centers on United States, Germany, and Japan where liquid nitrogen cold chain networks and biosafety level containment facilities cluster. Raw material dependencies rest on donor screening protocols, cryoprotectant formulations, and enteric coating polymers. Single-source vulnerability in qualified donor strain collections poses structural risk as EMA and FDA employ divergent live-product classification schemes. Distribution runs through centralized hospital formularies and infectious disease stewardship programs rather than direct physician prescribing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement pilot programs in Germany and Japan are redirecting demand toward premium specifications that reward durable remission outcomes over treatment administration volume.
For Market Incumbents: Lock in cryopreservation infrastructure access through long-term facility leases in Kanto and Massachusetts regions before capacity scarcity intensifies. Secure exclusive master cell bank qualification relationships with biosafety level containment specialists to defend against synthetic ecology platform companies entering from Boston and Basel. Prioritize health-economic evidence packages demonstrating cost-per-remission superiority against standard antibiotics to satisfy infectious disease stewardship program evaluation criteria. For New Entrants and Emerging Players: Capture pediatric liquid formulation white space in French and British hospitals where nasogastric tube-compatible suspensions address swallowing difficulties in underserved populations. Target gut-brain axis applications for Parkinson's and Alzheimer's where neurodegenerative drug development funding is redirecting toward microbiome modulation with limited incumbent penetration. Pursue outcome-based reimbursement pilot participation in Germany as the primary go-to-market angle rather than traditional per-dose contracting. For Investors and Strategic Acquirers: Large pharmaceutical sponsors with established gastroenterology channels are the most active acquirer in this space, seeking synthetic ecology platform capabilities and defined bacterial consortia libraries. Over a five-to-ten year horizon, vertically integrated manufacturing archetypes with end-to-end infrastructure will outlast asset-light developers dependent on contract manufacturers. Monitor EMA classification determination procedures as the critical inflection signal—regulatory clarity between medicinal product and tissue designations will trigger consolidation among development-stage companies.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA classification determination procedures in Germany and the Netherlands are accelerating as pipelines mature toward Phase II. |
| Manufacturing Scale-Up | End-to-end infrastructure investments in Massachusetts and California sustain commercial supply of approved live biotherapeutics. |
| Pipeline Diversification | Gut-brain axis applications for Parkinson's and Alzheimer's attract neurodegenerative drug development funding from Boston and Basel sponsors. |
| Strategic Partnership | Japanese pharmaceutical sponsors partner with domestic biotechs to access PMDA priority review pathways for defined bacterial consortia. |
| Reimbursement Strategy | Germany's health technology assessment bodies construct novel payment categories rewarding durable remission rather than treatment administration. |
Research Methodology
Multiple input streams—regulatory filing databases, hospital procurement records, and clinical trial registries—were reconciled through structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from FDA live biotherapeutic product guidance documents, EMA centralized marketing authorization application records, PMDA fast-track designation filings, and ClinicalTrials.gov protocol repositories. Bottom-up strain-level demand estimates and top-down therapy area expenditure analyses were triangulated to cross-verify market sizing.
Data-stream reconciliation across product type, therapy area, delivery mode, and regional regulatory cluster dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating live biotherapeutic procurement expansion in hospital networks, CRISPR-engineered consortia development timelines, and reimbursement pilot program adoption curves. Forecast inputs included synthetic ecology platform technology maturation rates and cryopreservation infrastructure capacity constraints.
Regulatory reclassification by EMA, PMDA approval pathway delays, and cryopreservation cold chain disruptions are the dominant revision risks to modeled assumptions. Deviation in live biotherapeutic classification clarity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Ripening Cultures Market