
 Global Single Nucleotide Polymorphism (SNP) Genotyping Market | 2026-2036
Global Single Nucleotide Polymorphism (SNP) Genotyping Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single Nucleotide Polymorphism (SNP) Genotyping Market Foresight
Modular SNP panel configurations is broadening buyer choice across research and clinical segments. Illumina leverages its sequencing platform ecosystem to anchor high-throughput genotyping workflows in academic institutions. Thermo Fisher Scientific competes through integrated PCR-based assay systems that sustain repeat purchase revenue from biopharmaceutical quality control labs.
Single nucleotide polymorphism genotyping identifies DNA sequence variations at single base-pair positions using allele-specific hybridization, primer extension, or ligation-based detection methods with throughput ranging from tens to millions of variants per run. Its primary commercial purpose spans trait mapping, disease association studies, and personalized medicine dosing optimization. Pharmacogenomics applications command premium positioning due to direct clinical revenue linkage, while plant breeding demand accelerates in agricultural biotechnology corridors. Real-Time PCR technology dominates routine screening volumes, though Next-Generation Sequencing captures complex trait analysis where multiplex density requirements exceed array capacities.
FDA companion diagnostic guidelines and EMA pharmacogenomic biomarker qualification pathways shape product development priorities and market access timelines for assay manufacturers. ISO 15189 medical laboratory accreditation requirements in multiple jurisdictions determine platform eligibility for reimbursed clinical testing. Stakeholders must monitor evolving payer coverage decisions for pharmacogenomic panels as these determine the addressable clinical market beyond research budgets.
Market Dynamics
Pharmacogenomic integration into clinical workflows is compressing platform procurement cycles as hospitals and health systems prioritize FDA-cleared companion diagnostic compatibility over research-grade flexibility.
Growth Catalysts
- FDA Companion Diagnostic Guidance:Accelerated biomarker qualification pathways are streamlining assay validation timelines and expanding reimbursable test menus in US academic medical centers.
- Real-Time PCR:Sustained instrument placement in biopharmaceutical quality control labs generates recurring consumable revenue and locks in platform loyalty.
- Agricultural Biotechnology:Marker-assisted selection programs in Brazil and Argentina are driving demand for high-throughput SNP panels in crop breeding programs.
Market Restraints
- Reagent Supply Concentration:Specialty polymerase and probe chemistries rely on a limited supplier base concentrated in Germany and Switzerland, creating input vulnerability.
- ISO 15189 Accreditation Burden:Medical laboratory certification requirements in multiple jurisdictions extend platform validation timelines and restrict vendor eligibility for clinical procurement.
- Next-Generation Sequencing Substitution:Falling per-base sequencing costs are displacing array-based genotyping for complex trait analysis requiring dense variant coverage.
Strategic Opportunities
- India Diagnostic Expansion:CDSCO streamlined medical device registration and rising private hospital investment create entry points for mid-throughput PCR platforms.
- Point-of-Care Pharmacogenomics:Miniaturized assay formats targeting cardiology and psychiatry prescribing workflows address decentralized testing demand.
- Cloud-Connected Instrumentation:Integration of genotyping hardware with laboratory information systems and AI-assisted variant interpretation is opening subscription revenue models.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of computational biologists capable of pipeline development and regulatory-compliant variant reporting constrains assay commercialization.
- Legacy System Interoperability:Hospital electronic health record integration requires custom API development and delays pharmacogenomic panel deployment in established health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single Nucleotide Polymorphism (SNP) Genotyping Market |
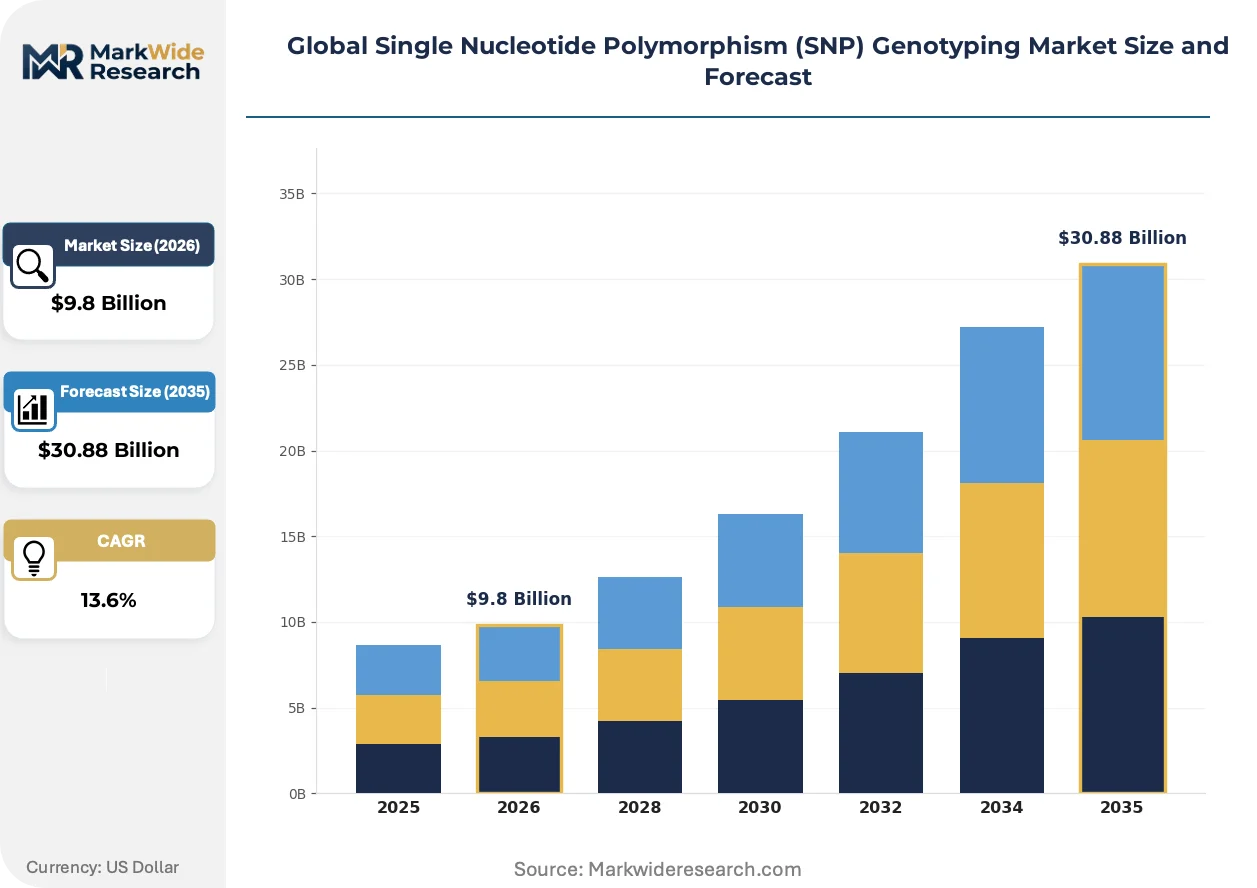
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $30.88 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarrays, PCR-based Assays, Sequencing Platforms, SNP Panels Application: Pharmacogenomics, Plant Breeding, Animal Genetics, Forensic Studies, Nutrigenomics End User: Research Laboratories, Biopharmaceutical Companies, Academic Institutions, Forensic Agencies Technology: Real-Time PCR, MassARRAY, Next-Generation Sequencing, TaqMan Assays |
| Companies Covered | Bio-Rad Laboratories, QIAGEN, Illumina, Luminex Corporation, Fluidigm Corporation, Thermo Fisher Scientific, LGC Group, Promega Corporation, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single Nucleotide Polymorphism (SNP) Genotyping Market Shifts & Advancements
Digital PCR and microfluidic sample preparation are compressing assay turnaround times while regulatory data submission requirements are hardening around analytical validation standards.
Digital PCR is electrifying rare variant detection workflows in liquid biopsy and transplant monitoring applications. Oncology reference laboratories in the United States and Germany are adopting these platforms at accelerated replacement cycles. This technology is electrifying sensitivity benchmarks that array-based methods cannot meet, forcing incumbent vendors to defend installed bases through service contract bundling.
EMA pharmacogenomic biomarker qualification pathways are tightening evidentiary standards for drug-diagnostic co-development. Companion diagnostic sponsors now face parallel scientific advice procedures that extend development timelines but reduce regulatory risk at marketing authorization. European biopharmaceutical companies are responding by front-loading analytical validation studies and engaging notified bodies earlier in design control phases.
Consolidated procurement through national tender programs is displacing decentralized instrument purchasing in public health systems. France and Italy have centralized genotyping platform acquisition through regional laboratory networks, compressing vendor sales cycles and prioritizing total cost-of-ownership metrics over technical specifications. This shift is most visible in Southern European markets where austerity-era laboratory restructuring has concentrated testing volume in hub-and-spoke configurations.
Global Single Nucleotide Polymorphism (SNP) Genotyping Market Segmentation
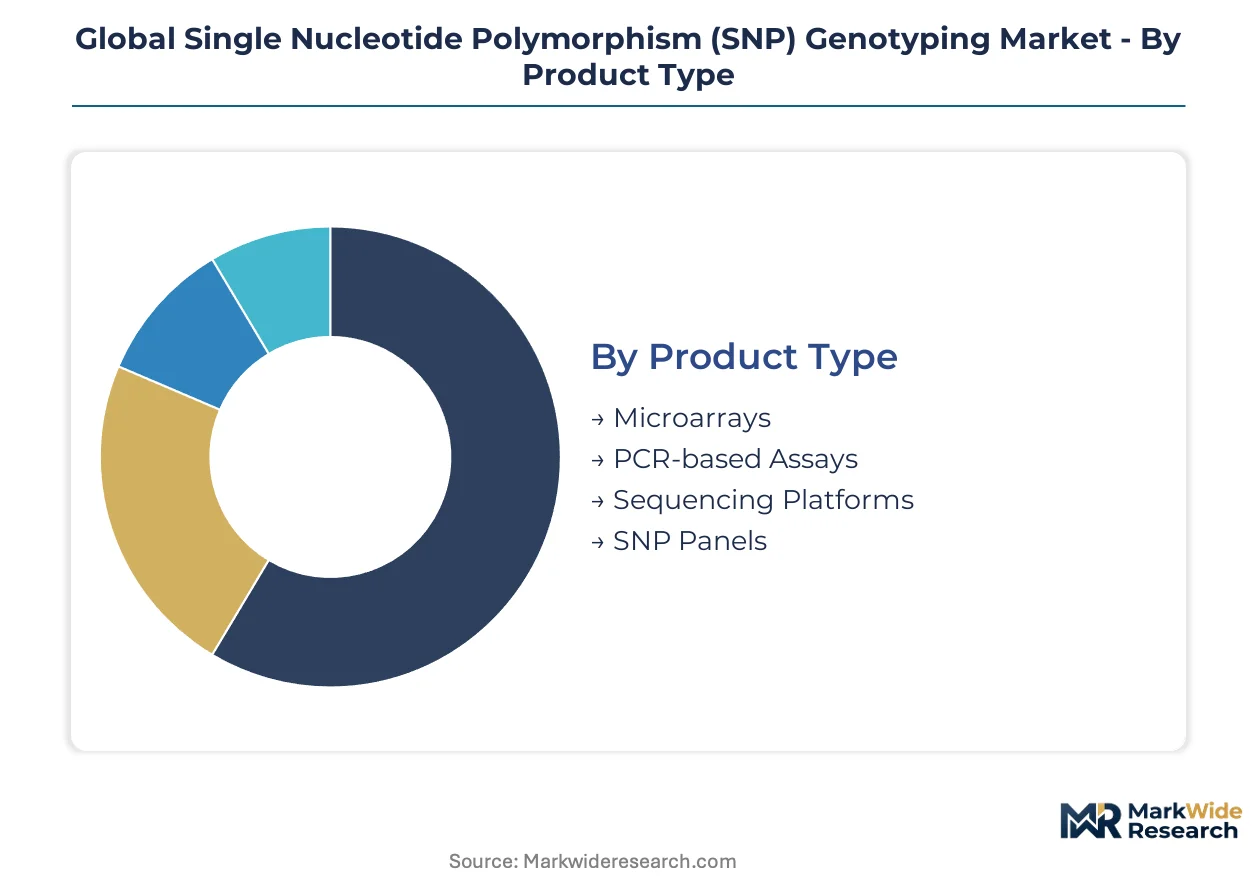
SNP genotyping market segmentation reflects divergent buyer priorities across research and clinical environments. Procurement decisions hinge on throughput requirements, regulatory compliance burden, and integration complexity with existing laboratory infrastructure.
Product Type:
Capital allocation patterns separate high-volume screening operations from targeted validation workflows.
- Microarrays:High-density variant detection across hundreds of thousands of loci enables genome-wide association studies. Agricultural biotechnology corridors in Brazil and the United States anchor demand for crop trait mapping applications.
- PCR-based Assays:Allele-specific amplification delivers rapid turnaround for clinical pharmacogenomic panels. Biopharmaceutical quality control laboratories in Germany and Switzerland sustain repeat consumable purchases for batch release testing.
- Sequencing Platforms:Next-generation systems capture complex structural variants exceeding array detection limits. Academic medical centers prioritize these for multi-omics integration projects.
- SNP Panels:Preconfigured variant sets reduce assay development burden for standardized clinical tests. Diagnostic laboratories favor these for FDA companion diagnostic compliance.
Volume sits with PCR-based Assays; growth tilts toward Sequencing Platforms.
Application:
Revenue concentration follows regulatory validation status and reimbursement pathway clarity.
- Pharmacogenomics:Drug-gene interaction testing guides dosing decisions in cardiology and psychiatry. FDA companion diagnostic guidelines and EMA biomarker qualification pathways are tightening evidentiary standards for assay commercialization.
- Plant Breeding:Marker-assisted selection accelerates trait fixation in soybean and corn programs. Brazil and Argentina drive procurement for drought tolerance and yield optimization screening.
- Animal Genetics:Parentage verification and disease resistance screening support livestock improvement programs. Brazil and Australia concentrate demand for cattle and sheep breeding applications.
- Forensic Studies:Identity testing and criminal casework require ISO 17025 compliant workflows. National DNA databases in the United States and United Kingdom sustain platform refresh cycles.
- Nutrigenomics:Diet-gene interaction analysis targets consumer wellness segments with limited reimbursement coverage. Direct-to-consumer testing companies in the United States and China drive intermittent demand spikes.
Pharmacogenomics commands premium positioning; Plant Breeding is climbing the fastest.
End User:
Procurement authority and budget stability vary sharply across institutional categories.
- Research Laboratories:Exploratory genotyping projects prioritize platform flexibility over regulatory clearance. National research councils in France and Japan fund large-scale population cohort studies.
- Biopharmaceutical Companies:Companion diagnostic co-development mandates FDA-submissible validation packages. Quality control departments sustain high-throughput screening for cell line authentication.
- Academic Institutions:Training programs and principal investigator grants drive mid-throughput instrument placement. United States medical schools anchor demand for pharmacogenomics curriculum integration.
- Forensic Agencies:Government crime laboratories require vendor qualification through national tender processes. Centralized procurement in Italy and Spain has compressed sales cycles for approved suppliers.
Biopharmaceutical Companies dominate consumable revenue; Academic Institutions show steepest expansion trajectory.
Technology:
Detection chemistry and data output format determine integration complexity with downstream analysis pipelines.
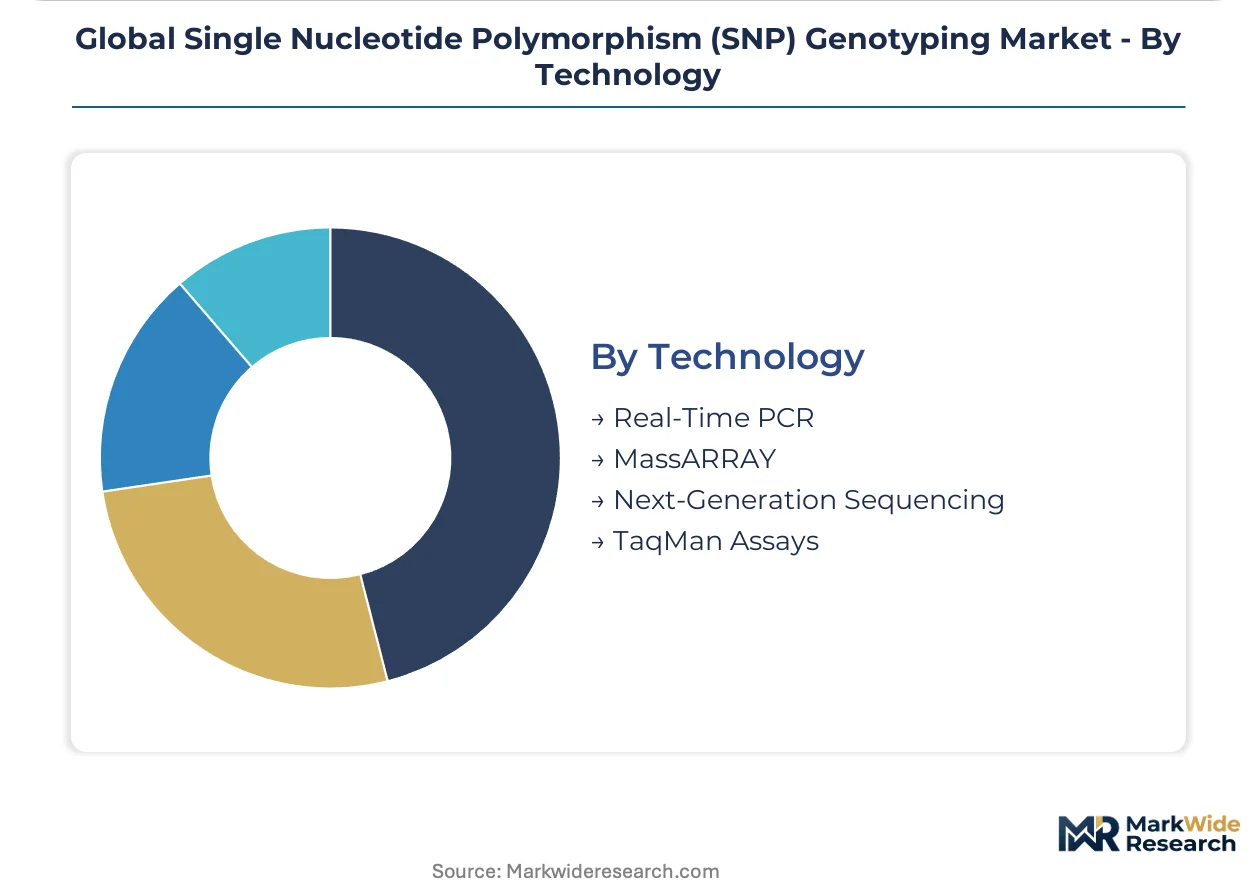
- Real-Time PCR:Fluorescence-based quantification dominates routine screening with established reagent supply chains. Biopharmaceutical QC labs in Germany and Switzerland lock in platform loyalty through service contracts.
- MassARRAY:MALDI-TOF mass spectrometry enables medium-plex genotyping without sequencing infrastructure. Reference laboratories in the United States adopt these for somatic mutation confirmation.
- Next-Generation Sequencing:Massively parallel readouts capture rare variants and phasing information. Oncology testing programs in the United States and Germany are displacing arrays for complex trait analysis.
- TaqMan Assays:Probe-based specificity supports single-SNP clinical decisions with minimal bioinformatics burden. Diagnostic laboratories favor these for FDA-cleared pharmacogenomic reporting.
Real-Time PCR holds installed base dominance; Next-Generation Sequencing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform manufacturing concentrates in Germany, Switzerland, and the United States, while clinical consumption clusters in American academic medical centers and European reference laboratories. Brazil and India represent the fastest procurement expansion corridors for agricultural and diagnostic applications respectively.
United States
FDA companion diagnostic guidelines and pharmacogenomic reimbursement decisions drive platform procurement in academic medical centers. The 21st Century Cures Act provisions accelerate biomarker qualification pathways for drug-diagnostic co-development. Boston and San Diego anchor biopharmaceutical quality control lab clusters where Thermo Fisher Scientific and Illumina sustain instrument placement dominance.
Germany
ISO 15189 medical laboratory accreditation requirements and EMA biomarker qualification standards shape vendor eligibility for clinical procurement. The country's national pharmaceutical regulator enforces stringent analytical validation protocols for reimbursed testing. Munich and Heidelberg concentrate oncology reference laboratories adopting digital PCR platforms for rare variant detection workflows.
Brazil
Marker-assisted selection programs for soybean and corn breeding drive demand for high-throughput SNP panels in agricultural biotechnology corridors. ANVISA streamlined medical device registration creates entry points for mid-throughput PCR platforms in private diagnostic networks. São Paulo and Mato Grosso anchor crop breeding program procurement where drought tolerance screening accelerates platform refresh cycles.
India
CDSCO streamlined medical device registration and rising private hospital investment create entry points for pharmacogenomic testing infrastructure. The country's national pharmaceutical regulator harmonizes with IMDRF guidelines to accelerate assay import approvals. Maharashtra and Karnataka concentrate diagnostic laboratory networks pursuing ISO 15189 accreditation for reimbursed genetic testing menus.
Switzerland
Specialty polymerase and probe chemistry manufacturing anchors reagent supply concentration for European quality control laboratories. Swissmedic enforces medical device quality management system requirements that extend platform validation timelines. Basel and Zurich cluster biopharmaceutical manufacturing sites sustaining repeat consumable purchases for batch release genotyping.
Global Single Nucleotide Polymorphism (SNP) Genotyping Market Competitive Landscape
The competitive structure tilts toward sequencing-platform ecosystems and integrated PCR-based assay systems. Illumina leverages its installed base in academic institutions to anchor high-throughput genotyping workflows, while Thermo Fisher Scientific competes through biopharmaceutical quality control lab penetration. Three archetypes dominate: platform-anchored ecosystem providers, integrated assay-instrument bundlers, and specialty reagent chemists. M&A activity concentrates on bioinformatics pipeline acquisitions and regional diagnostic laboratory network integration.
Within the platform-anchored ecosystem tier, Illumina and Thermo Fisher Scientific exemplify divergent competitive vectors. Illumina occupies a position tied to next-generation sequencing infrastructure in academic medical centers, while Thermo Fisher Scientific sits within the PCR-based repeat-purchase revenue model serving biopharmaceutical quality control operations. QIAGEN represents the sample-to-insight integration archetype spanning assay chemistries and bioinformatics interpretation layers.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| QIAGEN |
| Illumina |
| Luminex Corporation |
| Fluidigm Corporation |
| Thermo Fisher Scientific |
| LGC Group |
| Promega Corporation |
| Agilent Technologies |
| Others |
Supply & Pricing Matrix
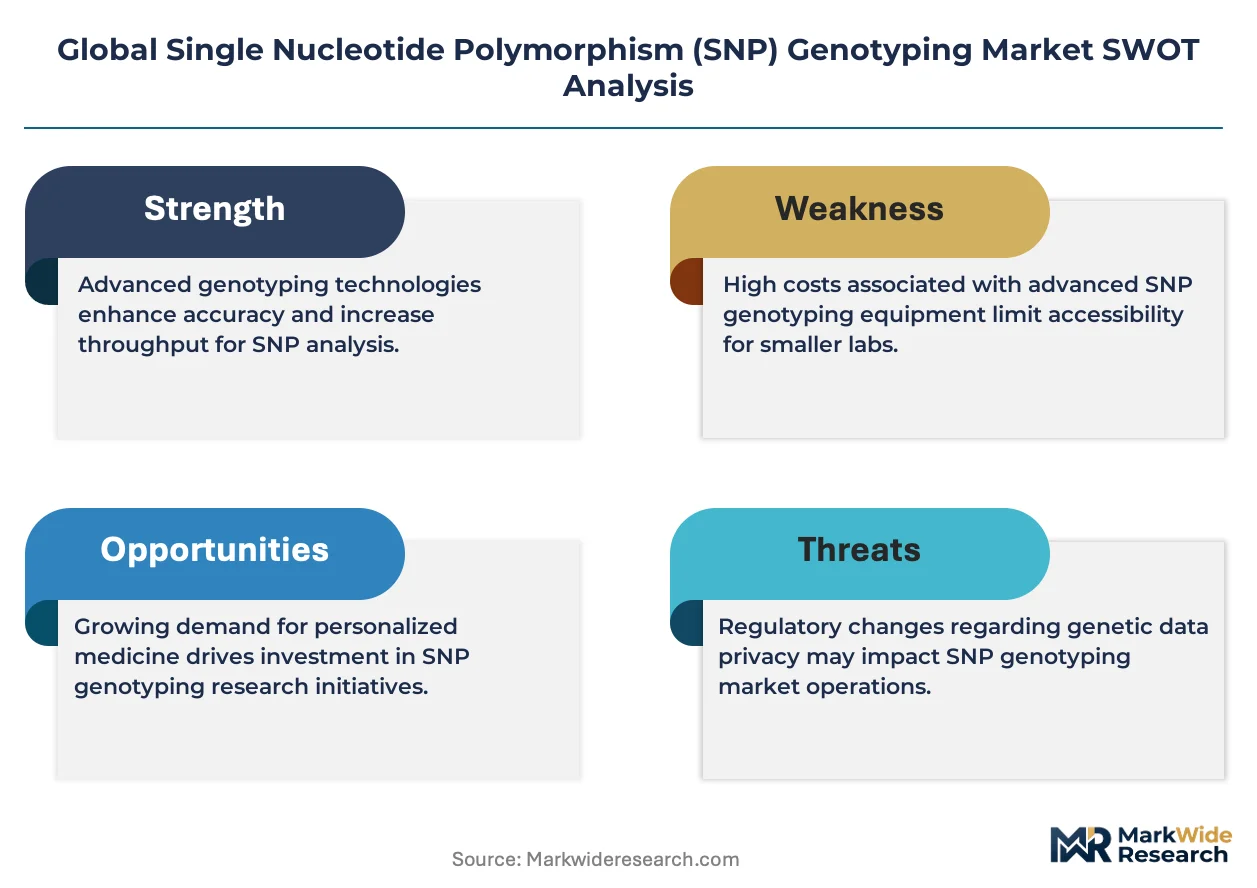
Specialty polymerase price indices from German and Swiss chemical suppliers cascade through reagent manufacturing tiers into three distinct pricing levels for end-user laboratories. Procurement managers at academic medical centers and biopharmaceutical quality control operations face escalating input costs that compress margins at the standard tier while premium certified assays retain pricing power.
Pricing Analysis
Margin tightening in mid-throughput PCR platforms reflects ISO 15189 accreditation cost pass-throughs and consumable bundling discounts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic panels from research-grade reagents and unvalidated import alternatives. Price differentiation hinges on certification tier and after-sales service intensity. Diagnostic laboratories in India and Brazil exhibit highest price sensitivity; biopharmaceutical QC labs in Germany and Switzerland demonstrate lowest.
Supply Chain Analysis
Taq polymerase and fluorescent probe chemistries rest on specialty chemical manufacturing concentrated in Germany, Switzerland, and the United States. Raw material dependencies include high-fidelity DNA polymerases, MALDI-TOF matrix compounds, and synthetic oligonucleotide precursors. Single-source vulnerability around heat-stable enzyme formulations creates procurement risk for assay manufacturers. Distribution runs through authorized distributor networks serving hospital laboratories and direct OEM supply contracts with biopharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform ecosystem consolidation is accelerating as FDA companion diagnostic requirements and ISO 15189 accreditation burdens force sub-scale reagent suppliers toward exit. Next-generation sequencing substitution pressure compounds margin compression for array-based vendors.
For Market Incumbents: Deepen backward integration into specialty polymerase manufacturing to secure input cost stability against German and Swiss chemical supplier concentration. Expand service contract bundling in biopharmaceutical QC labs to defend installed bases against digital PCR substitution in rare variant detection workflows. For New Entrants and Emerging Players: Launch via cloud-connected instrument leasing models targeting mid-throughput diagnostic laboratories in Maharashtra and Karnataka pursuing ISO 15189 accreditation. White-space concentration sits with point-of-care pharmacogenomics miniaturization for cardiology and psychiatry prescribing workflows in decentralized Indian and Brazilian healthcare networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor bioinformatics pipeline specialists with regulatory-compliant variant reporting capabilities in the United States and Germany. Long-term viability hinges on AI-assisted interpretation layer integration. The signal to monitor is payer coverage expansion for pharmacogenomic panels beyond academic medical center research budgets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Companion Diagnostic Submission | Accelerates biomarker qualification pathways for drug-diagnostic co-development in oncology and cardiology. |
| ISO 15189 Accreditation Investment | Unlocks reimbursed clinical testing eligibility in European and Asian diagnostic laboratory networks. |
| Cloud-Connected Instrument Integration | Enables subscription revenue models through AI-assisted variant interpretation and LIS connectivity. |
| Backward Integration into Reagent Chemistry | Reduces vulnerability to German and Swiss specialty polymerase supply concentration. |
| Point-of-Care Miniaturization Launch | Addresses decentralized pharmacogenomics demand in psychiatry and cardiology prescribing workflows. |
Research Methodology
Multi-period observation of instrument placement cycles, consumable purchasing patterns, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with assay development scientists, diagnostic laboratory directors, biopharmaceutical QC managers, and hospital procurement committees. Secondary validation drew from FDA 510(k) filings, EMA scientific advice procedures, CDSCO medical device registration databases, and ISO 15189 accreditation records. Bottom-up segmentation modeling triangulated against top-down market sizing from capital expenditure disclosures and tender award documentation.
Segment-weighting across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. Pharmacogenomics reimbursement trajectory, agricultural biotechnology R&D intensity, and next-generation sequencing cost curves served as core forecast inputs. CAGRs were derived from installed base evolution and consumable attach rate assumptions rather than extrapolated point estimates.
The model assumes a particular technology adoption path; alternative pathways for digital PCR and nanopore sequencing would alter the outlook for array-based genotyping platforms. Forecasts reflect assumptions around FDA companion diagnostic guidance implementation speed and EMA biomarker qualification pathway harmonization. A small set of triggers—payer coverage decisions, reagent supply disruptions, and sequencing cost inflections—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Apolipoprotein Test Market
Genomics
Spatial OMICS Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Genomics and Transcriptomics Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Transcriptomics Technologies Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
China Genetic Testing Market
Genomics
Personal Genome Testing Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Agrigenomics Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Middle East and Africa Genetic Testing Market