
 DNA Microarray Market | 2026-2036
DNA Microarray Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Microarray Market Intelligence
A shift from in-house array production to outsourced services from specialized contract research organizations is restructuring the competitive landscape. Thermo Fisher Scientific Inc. leverages its extensive distribution network to serve academic and diagnostic labs globally. Agilent Technologies, Inc. differentiates through its focus on customized oligonucleotide arrays for specific research applications. Illumina, Inc. sustains its market position through leadership in high-throughput sequencing and complementary microarray technologies.
A DNA microarray is a solid substrate, often a glass slide, onto which thousands of microscopic DNA spots are attached in an ordered grid. These arrays are fabricated using precise techniques like photolithographic in situ synthesis or robotic spotting to create high-density probes. Oligonucleotide arrays represent the dominant product type due to their high specificity and reproducibility. Within applications, molecular diagnostics and drug discovery are the primary value pools, driven by demand from biopharmaceutical companies.
Regulatory frameworks from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA govern the use of microarrays in clinical diagnostics. These regulations define the stringent validation requirements and quality system standards necessary for market approval of diagnostic tests. The key strategic decision for vendors will be balancing investment in established spotting technologies against the development of novel label-free detection systems.
Market Dynamics
The structural shift towards outsourced services from specialized contract research organizations is the central force shaping the market. This trend is driven by the increasing complexity and capital requirements of high-throughput, bead-based array technologies used in personalized medicine.
Growth Catalysts
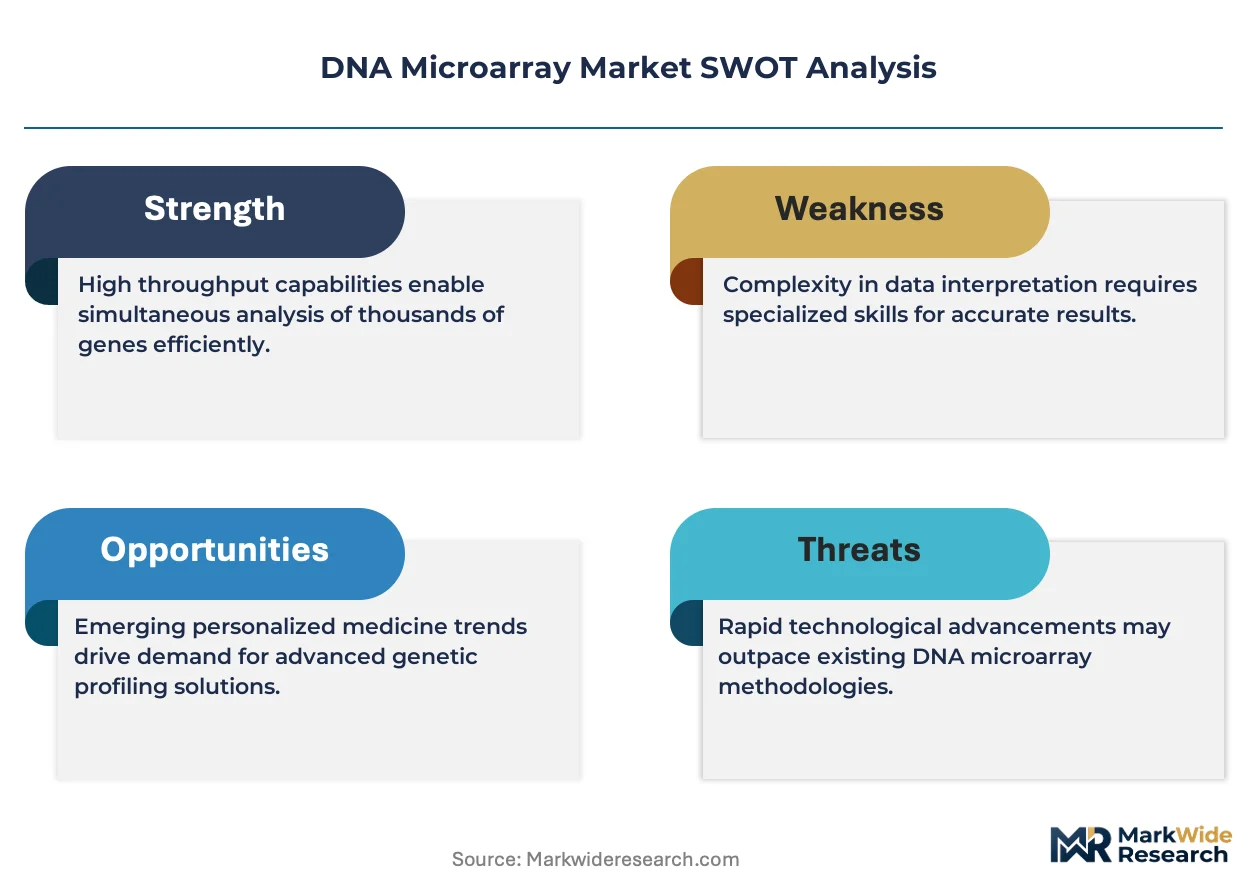
- Personalized Medicine Demand:Expanding applications in molecular diagnostics, particularly for oncology and pharmacogenomics, create sustained demand from biopharmaceutical companies and clinical laboratories for high-specificity arrays.
- Technical Enablement:The transition to higher-throughput technologies, such as bead-based arrays, allows for more comprehensive genomic analysis, supporting large-scale population studies and drug discovery programs.
- Government Research Funding:Public funding initiatives for genomic research, particularly within academic and research institutes in the United States and China, provide a stable demand base for microarray consumables and instruments.
Market Restraints
- Substitution by NGS:The increasing cost-effectiveness and broader data output of Next-Generation Sequencing technologies present a significant substitution threat for certain research applications, particularly discovery-phase genomics.
- High Capital Expenditure:The substantial upfront investment required for microarray scanners, robotic spotters, and associated laboratory automation systems creates a high barrier to entry for smaller research labs.
- Clinical Validation Hurdles:Stringent validation requirements imposed by regulatory bodies like the US FDA and the EMA for diagnostic assays create long and costly development cycles for clinical-grade microarrays.
Strategic Opportunities
- Agrigenomics Expansion:Applying microarray technology to agriculture for crop improvement, livestock breeding, and aquaculture genetics represents a significant, underpenetrated application area beyond human health.
- Label-Free Detection:Development of novel label-free detection systems offers an opportunity to simplify workflows, reduce reagent costs, and shorten turnaround times, appealing to cost-sensitive clinical labs.
- Diagnostic Market Entry in Brazil:Establishing clinical diagnostic capabilities in emerging markets like Brazil, supported by ANVISA's evolving framework for in-vitro diagnostics, presents a key geographic growth vector.
Industry Challenges
- Bioinformatics Skill Gap:A shortage of trained bioinformaticians capable of managing and interpreting the massive datasets generated by high-density arrays creates a significant operational bottleneck for many research institutions.
- Data Standardization Deficit:The absence of universally accepted standards for data formatting, normalization, and quality control across different microarray platforms complicates cross-study comparisons and meta-analyses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Microarray Market |
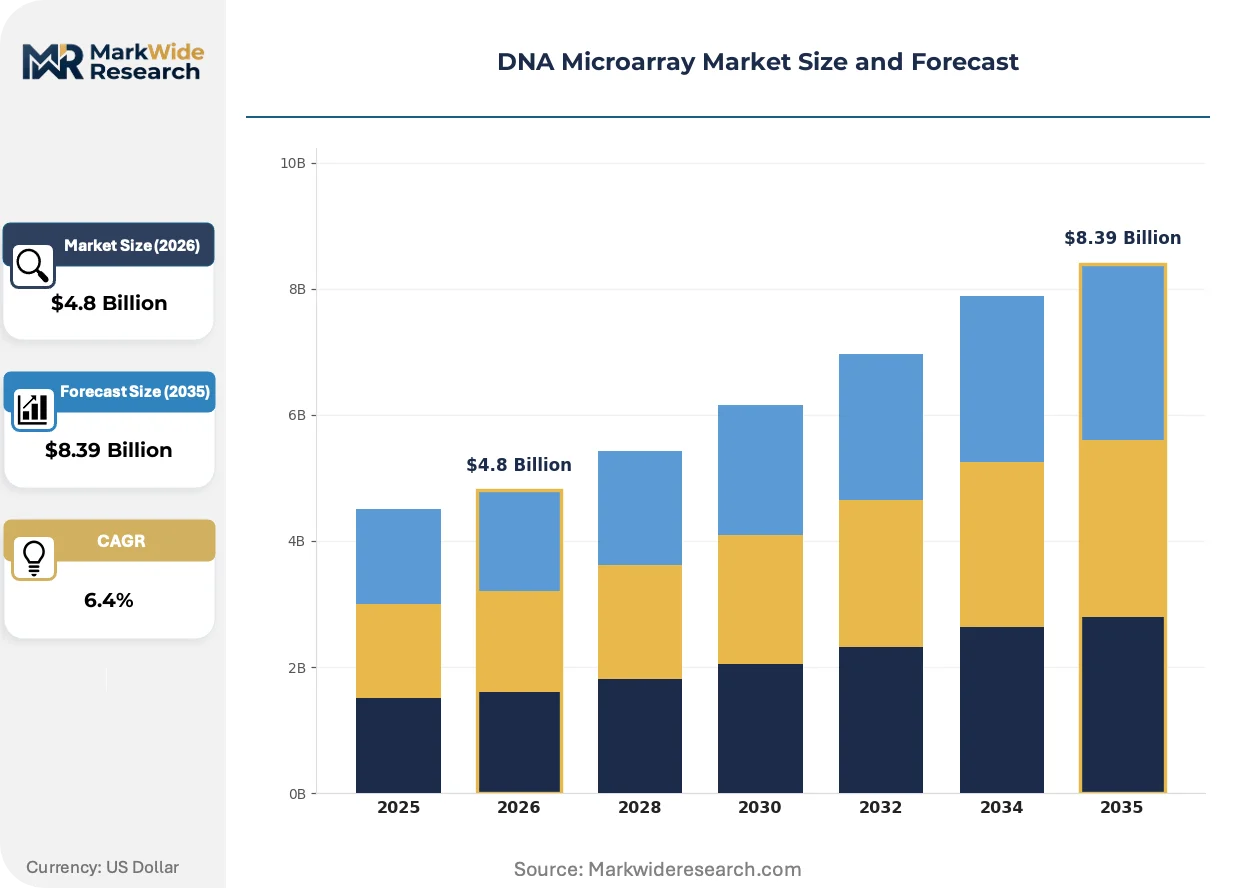
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oligonucleotide Array, cDNA Array, Protein Array, Tissue Array, Peptide Array Technology: In Situ Synthesis, Spotting, Bead-Based, Label-Free Detection, Electrochemical Detection Application: Genetic Research, Drug Discovery, Toxicology, Molecular Diagnostics, Agricultural Biotechnology End User: Biopharmaceutical Companies, Academic & Research Institutes, Diagnostic Laboratories, Contract Research Organizations, Agricultural Firms |
| Companies Covered | F. Hoffmann-La Roche AG, QIAGEN N.V., Illumina, Inc., Arrayit Corporation, PerkinElmer, Inc., Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Merck KGaA, Agilent Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Microarray Market Strategic Shifts & Innovations
Technological convergence is defining the market's evolution, pushing microarrays beyond pure research into integrated, multi-omic workflows. The primary focus is on enhancing data utility for clinical decision-making and streamlining complex analytical processes for broader adoption.
High-density bead-based arrays function by attaching oligonucleotide probes to microscopic beads, which are then randomly assembled onto a substrate. Genomic research centers and biopharmaceutical companies are the principal adopters for population-scale genotyping. This high-throughput format is absorbing the analytical workload previously handled by multiple lower-plex arrays, consolidating screening workflows.
The European Union's In Vitro Diagnostic Regulation (MDR/IVDR) imposes stricter requirements for clinical evidence and post-market surveillance. This regulation compels manufacturers to generate more extensive performance validation data for diagnostic utility. Vendors of microarray-based kits for the EU market are thus investing heavily in clinical trials and quality management systems to ensure compliance.
A behavioral shift involves moving from capital expenditure on in-house platforms to an operational model using outsourced services. This trend disrupts the direct-to-lab instrument sales channel, favoring specialized contract research organizations. The pattern is most pronounced among academic institutions and emerging biopharma firms lacking the scale for internal genomic analysis.
DNA Microarray Market Segmentation
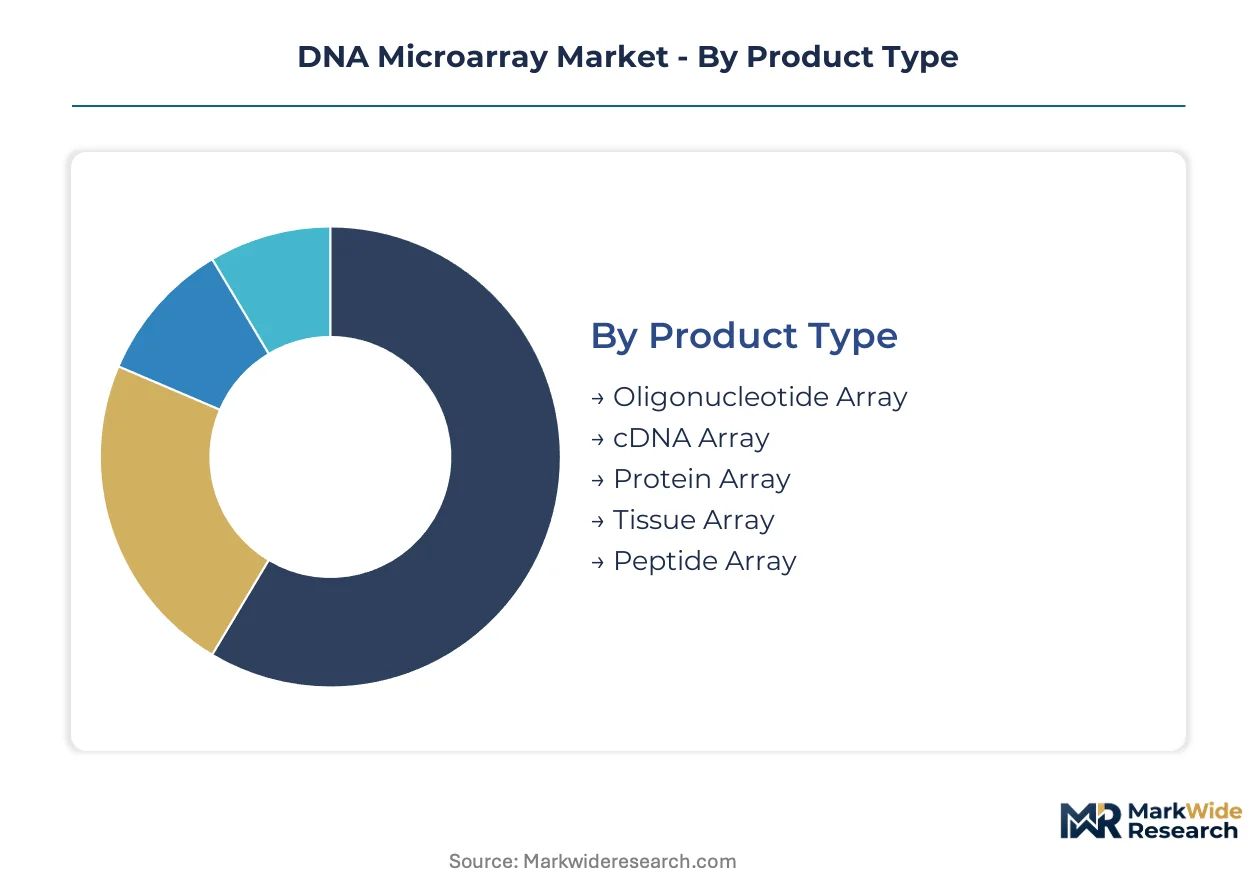
The DNA microarray market's segmentation reflects the diverse technological approaches and specialized application needs driving its evolution. Understanding these distinct segments is crucial for vendors to align product development with specific end-user requirements and capitalize on emerging opportunities across the value chain.
Product Type:
The upgrade and replacement cycles within product types are increasingly driven by the need for higher specificity and multiplexing capabilities in genomic analysis.
- Oligonucleotide Array:These arrays feature short, synthetic DNA sequences (oligonucleotides) directly synthesized or spotted onto a solid substrate, offering high specificity and reproducibility for gene expression profiling and genotyping. Demand concentrates in academic and diagnostic labs globally, driven by their reliability in large-scale genomic studies.
- Protein Array:Comprising immobilized proteins for the detection of protein-protein interactions, antibody profiling, or biomarker discovery, these arrays offer a distinct analytical approach beyond nucleic acids. Demand is concentrating within biopharmaceutical companies for drug target identification and validation.
- cDNA Array:Utilizing longer complementary DNA sequences, these arrays were historically used for gene expression analysis but are largely being superseded by higher-density oligonucleotide and bead-based formats.
- Tissue Array:Constructed by extracting cylindrical core samples from multiple paraffin-embedded tissue blocks and re-embedding them into a single recipient block, these arrays enable high-throughput histological analysis.
- Peptide Array:Featuring synthetic peptides immobilized on a surface, these arrays are employed for epitope mapping, enzyme profiling, and studying protein interactions, particularly in immunology research.
Volume placements concentrate in Oligonucleotide Array; the faster expansion belongs to Protein Array.
Technology:
The tiered cost structure of various microarray technologies influences adoption, with higher-throughput and novel detection methods commanding premium investment for advanced research capabilities.
- Bead-Based:This technology involves attaching oligonucleotide probes to microscopic beads, which are then randomly assembled onto a substrate, enabling high-throughput, multiplexed genomic analysis for population-scale genotyping. Biopharmaceutical companies and genomic research centers are the principal adopters, leveraging its capacity for comprehensive genomic screening.
- Label-Free Detection:These systems identify molecular interactions without the need for fluorescent or radioactive labels, simplifying workflows, reducing reagent costs, and shortening turnaround times. Clinical diagnostic labs are increasingly seeking these solutions to streamline their analytical processes.
- In Situ Synthesis:Probes are chemically synthesized directly on the microarray surface, allowing for highly customized and dense arrays, primarily used in specialized research applications.
- Spotting:Pre-synthesized DNA probes are robotically deposited onto a solid substrate, a traditional method offering flexibility for various array designs.
- Electrochemical Detection:This method uses an electrical signal generated by a redox reaction at the probe surface upon target binding, offering high sensitivity and miniaturization potential for point-of-care diagnostics.
The adoption trajectory for Bead-Based technologies is steeper than for Spotting methods.
Application:
The market's volume dynamics are heavily influenced by the specific analytical needs of diverse applications, ranging from fundamental research to clinical diagnostics and agricultural science.
- Molecular Diagnostics:This application involves using microarrays for disease diagnosis, prognosis, and pharmacogenomic testing, particularly in oncology and inherited genetic disorders. Demand from clinical laboratories and biopharmaceutical companies is a primary value pool, driven by personalized medicine initiatives.
- Drug Discovery:Microarrays are utilized in target identification, validation, and toxicology screening during the pharmaceutical development process, enabling high-throughput analysis of gene expression changes in response to drug candidates. Biopharmaceutical companies are significant consumers for accelerating their R&D pipelines.
- Genetic Research:Encompassing studies of gene function, genetic variation, and disease mechanisms, this application forms the foundational demand for microarray platforms in academic and research institutes.
- Toxicology:Microarrays are applied to assess the toxicological effects of compounds by analyzing changes in gene expression patterns in response to chemical exposure, supporting drug safety evaluation.
- Agricultural Biotechnology:Utilizing microarray technology for crop improvement, livestock breeding, and aquaculture genetics, this application area is gaining traction for enhancing food security and productivity.
Demand diversification across Molecular Diagnostics and Drug Discovery is a defining market feature.
End User:
The customer type significantly shapes procurement patterns, with large-scale organizations often seeking comprehensive solutions while smaller entities leverage specialized outsourced services.
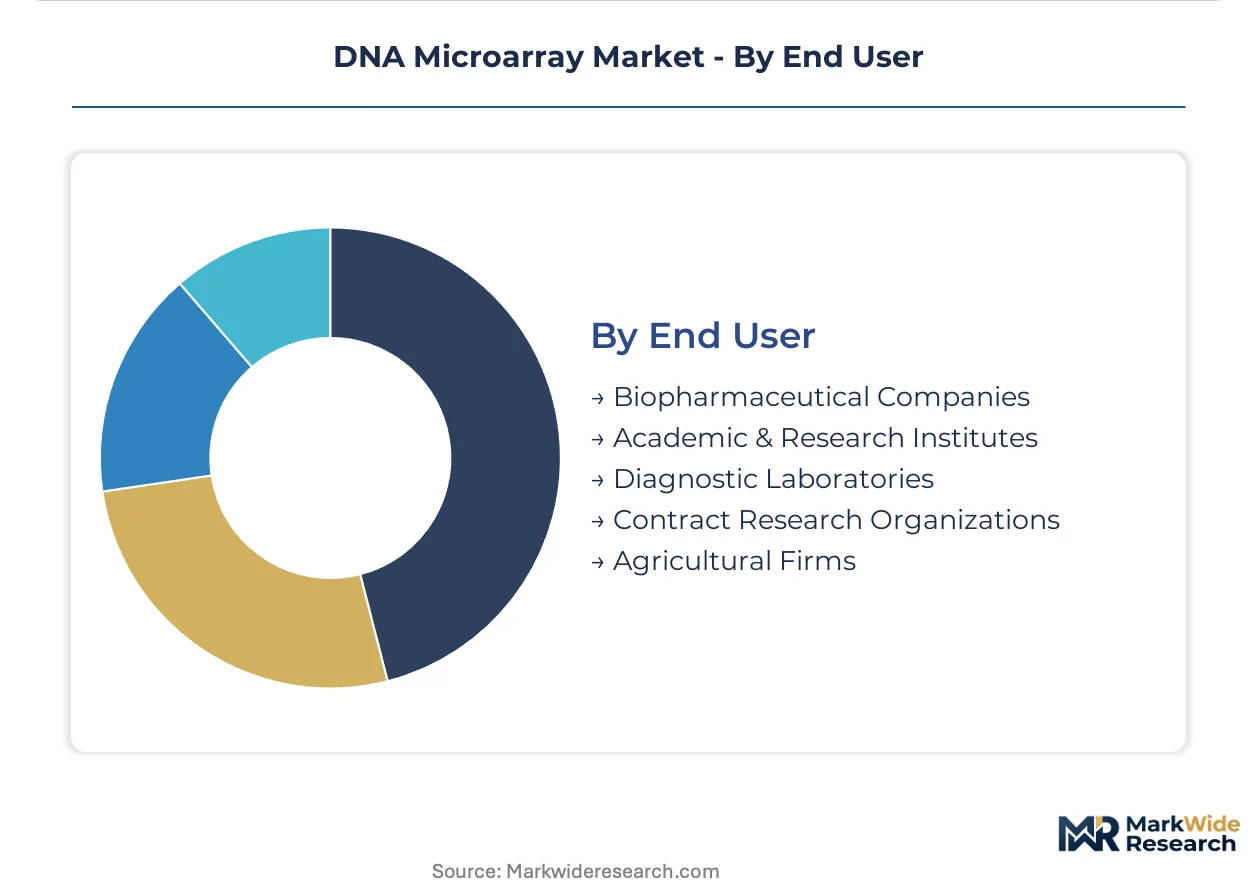
- Biopharmaceutical Companies:These firms use microarrays extensively for drug discovery, development, and molecular diagnostics research, driven by the need for high-throughput genomic analysis in R&D. These companies represent a significant portion of the market's revenue pool.
- Academic & Research Institutes:Public funding initiatives for genomic research within these institutions provide a stable demand base for microarray consumables and instruments, supporting fundamental scientific discovery.
- Diagnostic Laboratories:Clinical diagnostic labs adopt microarrays for routine genetic testing, disease screening, and personalized medicine applications, adhering to stringent regulatory validation requirements.
- Contract Research Organizations:CROs provide outsourced microarray services to biopharmaceutical companies and academic institutions, offering specialized expertise and high-throughput capabilities without the need for in-house capital expenditure.
- Agricultural Firms:These entities apply microarray technology for genetic profiling in plant and animal breeding programs, aiming to improve yield, disease resistance, and desirable traits.
The strategic importance of Biopharmaceutical Companies for innovation contrasts with the operational scale of Academic & Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its robust biopharmaceutical sector and extensive research infrastructure, anchors global demand for DNA microarray technology. This concentration supports advanced molecular diagnostics and drug discovery initiatives. Public and private investments drive innovation in high-throughput genomic analysis.
United States
Personalized medicine applications and oncology research drive significant demand for DNA microarrays in the United States. US FDA validation requirements for diagnostic assays shape product development and market entry. The Boston-Cambridge biotech hub fosters extensive collaboration between academic institutions and biopharmaceutical companies for advanced genomic research.
Germany
Academic research funding and pharmacogenomics studies generate consistent demand for microarray platforms in Germany. European Medicines Agency (EMA) guidelines influence the development and approval of clinical diagnostic products. The Munich and Heidelberg regions host strong university hospitals and biotech firms focused on precision medicine.
China
Government genomic initiatives and large-scale population studies expand the DNA microarray market in China. China's NMPA regulations govern the approval and use of in-vitro diagnostics within the country. The Yangtze River Delta region sees biopharmaceutical companies and research institutes actively engaging in high-throughput screening.
Japan
Advanced biomedical research and drug discovery efforts underpin demand for DNA microarrays in Japan. The PMDA provides stringent oversight for medical devices, including microarray-based diagnostic tools. Tokyo and Osaka areas host established pharmaceutical companies and university research centers driving innovation.
Brazil
Emerging clinical diagnostic capabilities and agricultural biotechnology applications are expanding the market in Brazil. ANVISA's evolving framework for in-vitro diagnostics creates new market entry opportunities for vendors. São Paulo state contains growing private diagnostic labs and agricultural research institutions adopting genomic tools.
DNA Microarray Market Key Industry Players
Strategic partnerships dominate the current landscape, driven by the increasing complexity and capital requirements of high-throughput genomic analysis. The market structure is tiered, featuring global diversified life science tool providers, specialized oligonucleotide array manufacturers, and contract research organizations. These archetypes engage in portfolio diversification, geographic expansion, and technology licensing to maintain competitive positioning. Capacity expansion in bead-based array production also represents a significant competitive move.
At the scale-driven end, Thermo Fisher Scientific Inc. represents a global diversified life science tools provider, leveraging its extensive distribution network to serve academic and diagnostic labs. Agilent Technologies, Inc. occupies a position as a specialized provider, exemplifying a focus on customized oligonucleotide arrays for specific research applications. Illumina, Inc. sits within the high-throughput sequencing and complementary microarray technologies segment, anchoring its market presence through technological leadership. These major players collectively illustrate the varied strategic approaches necessary for success, from broad market reach to niche specialization and integrated genomic solutions.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| QIAGEN N.V. |
| Illumina, Inc. |
| Arrayit Corporation |
| PerkinElmer, Inc. |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| Agilent Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Divergence between high-throughput bead-based arrays and traditional spotting methods shapes both pricing and supply chain configurations. Advanced technologies command premium pricing due to enhanced capabilities, while established techniques face greater cost scrutiny. Supply chain optimization focuses on securing specialized components for high-tech solutions.
Pricing Analysis
Warranty and service bundling often differentiates offerings, with comprehensive support packages accompanying premium instruments and outsourced services. The dominant pricing model combines per-unit transactional sales for consumables with project-based fees for specialized services and capital expenditure for instruments. Price differentiation stems from certification levels, particularly US FDA and EMA validation, and the degree of customization for specific research applications. Pricing pressure stems from the increasing cost-effectiveness of Next-Generation Sequencing technologies. Academic institutions and smaller research labs exhibit the highest price sensitivity, often opting for outsourced services.
Supply Chain Analysis
Logistics and freight costs significantly influence the global distribution of microarray instruments and reagents. Geographic supply concentration for specialized components centers on the United States, Germany, and Japan, reflecting their advanced manufacturing capabilities. Raw material dependencies include high-purity oligonucleotides, specialized glass substrates, and microscopic beads. Single-source vulnerability for proprietary reagents represents a structural supply chain risk. Distribution runs through a combination of direct sales channels for major vendors and a network of specialized distributors serving local markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DNA microarray market is experiencing a vertical-integration race, with players pursuing control over outsourced service capabilities as a key downstream lever.
For Market Incumbents: Lock in existing customer bases through long-term service contracts and integrated workflow solutions. Expand capacity in high-throughput bead-based array production to counter competitive threats from specialized contract research organizations. Invest in label-free detection system development to address the demand for simplified workflows, mitigating the substitution threat from Next-Generation Sequencing. Reinforce global distribution networks to maintain market reach.
For New Entrants and Emerging Players: Launch via strategic partnerships with academic institutions and specialized contract research organizations to gain initial market traction. Target underpenetrated application areas like agrigenomics and novel label-free detection systems for clinical diagnostic labs. Focus on developing cost-effective, high-specificity oligonucleotide arrays for emerging markets, leveraging a value-based go-to-market angle. Prioritize regulatory compliance pathways for rapid market entry.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized technology developers given the market's shift towards advanced detection systems and outsourced services. Long-term viability hinges on the continued expansion of personalized medicine applications and multi-omic research workflows. Target acquisition archetypes include niche providers of label-free detection technologies or contract research organizations with strong bioinformatics capabilities. Regulatory approvals for novel clinical diagnostic assays represent a crucial inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Bead-Based Arrays | Strengthens market leadership for high-throughput genomic analysis among biopharmaceutical companies. |
| Investment in Label-Free Detection R&D | Addresses demand from clinical laboratories for simplified workflows and reduced reagent costs. |
| Partnerships with Contract Research Organizations | Expands market reach into outsourced service models for academic institutions and emerging biopharma. |
| Geographic Expansion into Emerging Markets | Captures growth in regions like Brazil for clinical diagnostics and agricultural biotechnology applications. |
| Product Diversification into Agrigenomics | Unlocks new revenue streams beyond human health applications, enhancing market resilience. |
Research Approach
Multi-period observation of market dynamics, competitive actions, and technological shifts anchored the trend analysis, supplemented by interviews with industry experts. Primary research involved discussions with biopharmaceutical R&D directors, academic principal investigators, diagnostic lab managers, and CRO executives. Secondary validation drew from regulatory filings with the US FDA, EMA, and China's NMPA, scientific publications, company annual reports, and genomic research databases. This approach enabled comprehensive bottom-up and top-down triangulation.
Segment-specific weighting, derived from historical market share and growth trajectories, informed the quantitative projections across the modeling period. The analytical framework incorporated segmentation dimensions such as product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from a regression analysis of historical data and projected market drivers. Public research funding levels and personalized medicine adoption rates served as key industry-specific forecast inputs.
Next-Generation Sequencing advancements, shifts in regulatory validation requirements, and global public health priorities are the dominant revision risks for future market trajectories. Forecasts reflect assumptions documented through extensive primary and secondary research. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Japan Next Generation Sequencing Market
Genomics
Kearns-Sayre Syndrome Market
Genomics
Apolipoprotein Test Market
Genomics
Agrigenomics Market
Genomics
DNA Sequencing Market
Genomics
Genetic Testing Service Market
Genomics
United States DNA Sequencing Products Market
Genomics
Genetic Testing Panels Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Dna Polymerase Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Alagille Syndrome Market
Genomics
Antisense Oligonucleotides Market
Genomics
Europe Cancer Biomarkers Market
Genomics
Global Artificial Intelligence in Genomics Market