
 Probiotic Yeast Market | 2026-2036
Probiotic Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Yeast Market Intelligence
Ingredient-as-a-service revenue is rewriting margin economics for probiotic yeast suppliers. Lallemand Inc. leverages its Montreal-based fermentation infrastructure to control strain development from culture collection to finished active ingredient. Lesaffre Group anchors European supply through its Marcq-en-Baroeul headquarters and vertically integrated yeast propagation network. Angel Yeast Co. Ltd. dominates Asian manufacturing scale with its Yichang production complex, competing on unit cost for bulk nutritional yeast.
Probiotic yeast comprises live or heat-inactivated Saccharomyces cerevisiae and Saccharomyces boulardii strains, typically delivered at minimum viable counts exceeding 10^9 CFU per gram for therapeutic applications, with cell wall components beta-glucan and mannan-oligosaccharide driving immunomodulatory function in human and animal digestive systems. The application dimension shows dietary supplements commanding premium pricing due to clinical substantiation requirements, while animal feed represents the volume anchor as livestock producers seek antibiotic alternatives under veterinary prescription restrictions. Product type segmentation reveals specialty yeast isolates capturing expanding margin pools as strain-specific patents mature, whereas baker's yeast remains a commoditized base with limited probiotic positioning.
EFSA novel food approvals and FDA GRAS self-affirmation pathways shape strain commercialization timelines and label claim permissibility across European and North American markets. FSSAI's functional food regulations in India and China's NMPA health food blue-hat registration create divergent compliance burdens for multinational suppliers. Stakeholders must monitor evolving strain-specific substantiation standards as regulators tighten evidence thresholds for live microbe efficacy claims.
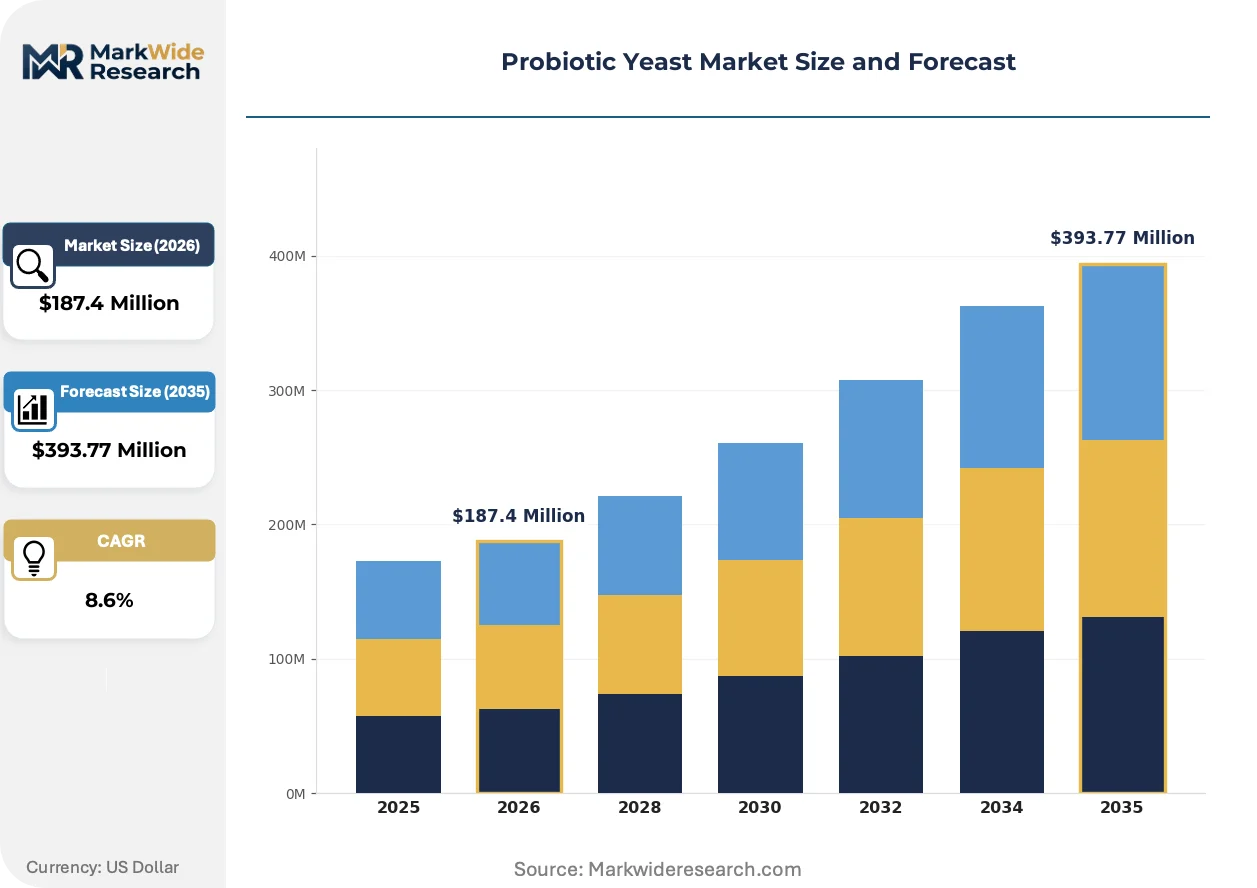
Market Dynamics
Strain-specific substantiation requirements under EFSA and FDA frameworks are forcing suppliers to rebuild R&D pipelines around clinically validated isolates rather than commodity yeast biomass, compressing commercialization timelines while expanding margin pools for credentialed players.
Growth Catalysts
- Veterinary prescription restrictions:Livestock producers across Germany and France are substituting antibiotic growth promoters with Saccharomyces cerevisiae feed additives to maintain weight gain performance. Regulatory mandates from the EU Veterinary Medicines Regulation accelerate this transition.
- EFSA novel food pathways:Strain-specific health claims for heat-inactivated yeast cell wall components are unlocking premium positioning in human dietary supplements. Approved beta-glucan immunomodulatory claims differentiate finished products from generic fiber additives.
- Gut microbiome research convergence:Academic institutions and contract research organizations are generating strain-level efficacy data that supports GRAS self-affirmation submissions to FDA. This evidence base enables suppliers to command pricing premiums over uncharacterized bulk yeast.
Market Restraints
- Molasses feedstock volatility:Cane and beet molasses prices fluctuate with sugar crop yields in Brazil and India, squeezing fermentation economics for bulk nutritional yeast producers who lack long-term supply contracts.
- Strain banking concentration:Authenticated Saccharomyces boulardii reference cultures concentrate in European national collections, creating licensing bottlenecks for North American and Asian suppliers seeking to develop proprietary isolates.
- Thermal stability limitations:Live probiotic yeast loses viability above 45°C, excluding inclusion in hot-extruded animal feed and baked functional foods without microencapsulation investments that erode unit economics.
Strategic Opportunities
- India functional food registration:FSSAI's evolving health food regulations create first-mover advantage for suppliers who establish local strain characterization and stability testing capabilities ahead of multinational entrants.
- Pet nutrition premiumization:Companion animal owners in the United States are purchasing yeast-based digestive supplements at human-grade price points, with veterinary channel distribution expanding beyond traditional feed-store retail.
- Precision fermentation convergence:Recombinant protein platforms originally developed for alternative proteins are being repurposed for high-purity beta-glucan extraction, enabling pharmaceutical-grade immunomodulatory ingredient supply.
Industry Challenges
- CFU enumeration standardization:Inconsistent viable count methodologies across ISO and AOAC protocols create batch release disputes between suppliers and finished goods manufacturers, delaying inventory turns and triggering contract penalties.
- Phage contamination control:Viral infections in yeast propagation tanks require multi-million dollar clean-room infrastructure upgrades and continuous monitoring systems that strain mid-scale fermentation operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Yeast Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker's Yeast, Nutritional Yeast, Brewer's Yeast, Specialty Yeast Application: Food & Beverages, Dietary Supplements, Animal Feed, Pharmaceuticals End User: Healthcare Providers, Retail Consumers, Food Manufacturers, Animal Nutritionists Packaging Type: Bags, Drums, Sachets, Jars |
| Companies Covered | Lallemand Inc., Lesaffre Group, Angel Yeast Co. Ltd., Chr. Hansen Holdings A/S, Alltech, DSM-Firmenich, ADM, Kerry Group, Associated British Foods Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Yeast Market Strategic Shifts & Innovations
Bioprocessing architecture and regulatory science are advancing in parallel, with automation and strain analytics converging to compress development cycles while expanding the therapeutic evidence base for yeast-derived ingredients.
Lyophilization technology is migrating from pharmaceutical-grade bacterial probiotics to yeast applications, preserving cell membrane integrity through controlled ice crystal formation during sublimation drying. Dietary supplement contract manufacturers in Switzerland and the United States are retrofitting freeze-drying lines originally built for Lactobacillus to handle larger yeast cell diameters. This equipment repurposing is enabling shelf-stable formulations that previously required refrigerated distribution, compressing logistics costs and expanding retail channel access for mass-market positioning.
EFSA's 2023 updated guidance on novel food safety assessments now explicitly addresses postbiotic definitions for heat-inactivated yeast preparations, clarifying evidentiary thresholds for immunomodulatory claims. The industrial consequence is a bifurcation in R&D investment between live culture suppliers pursuing gut colonization mechanisms and cell wall fraction processors targeting toll-like receptor activation pathways. Human dietary supplement applications in Germany and France are most affected, with reformulation pipelines accelerating to capture the first wave of approved postbiotic positioning ahead of competitive saturation.
Direct-to-practitioner distribution is displacing traditional wholesale-veterinary clinic supply chains for livestock probiotic yeast in the United States. Nutrition consultants and herd health veterinarians are purchasing strain-specific formulations through specialized e-commerce portals that provide batch-level certificates of analysis and on-farm application protocols. This channel shift concentrates in dairy operations exceeding 500 head in Wisconsin and California, where precision feeding investments justify premium pricing for documented CFU stability through the rumen environment.
Probiotic Yeast Market Segmentation
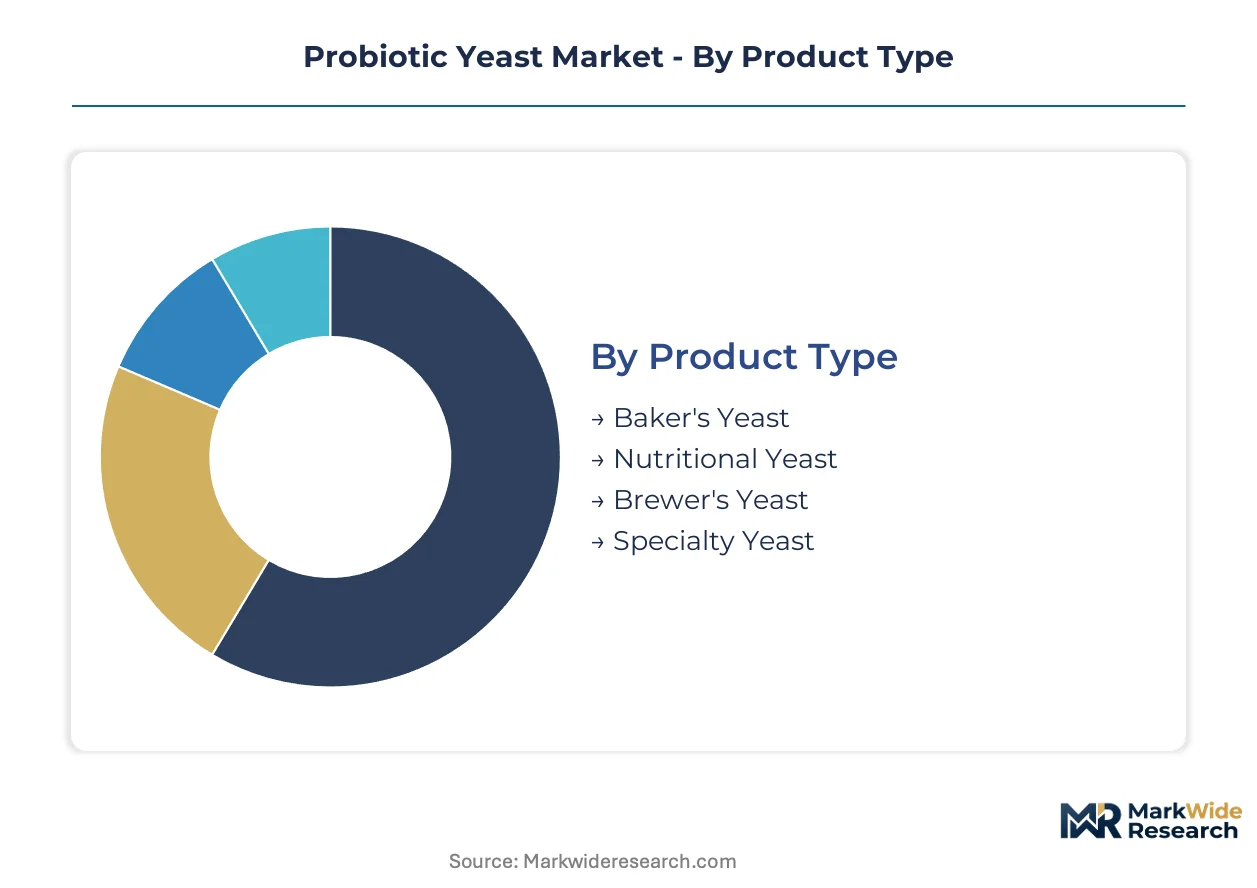
Segmentation in probiotic yeast markets separates commodity biomass from clinically substantiated isolates. Strain-specific patents and regulatory approvals create pricing tiers that reshape supplier economics across every category.
Product Type:
After-sales technical support intensity varies sharply across product tiers, with specialty yeast demanding strain-specific stability monitoring and baker's yeast requiring minimal post-sale engagement.
- Specialty Yeast:Proprietary Saccharomyces boulardii and engineered S. cerevisiae isolates with documented CFU stability through gastric transit. Demand concentrates in German and French dietary supplement channels where EFSA novel food approvals command pricing premiums over generic alternatives.
- Nutritional Yeast:Inactivated whole-cell preparations rich in B-vitamins and beta-glucan cell wall fractions. Fortification applications in United States plant-based dairy alternatives are expanding as clean-label ingredient sourcing becomes a purchase criterion for food manufacturers.
- Baker's Yeast:Standard fermentation-derived biomass with limited probiotic positioning due to leavening-focused strain selection and processing temperatures that compromise viability.
- Brewer's Yeast:Spent fermentation byproduct historically sold for animal feed, now repositioning through debittering processes for human-grade supplement applications.
By volume, baker's yeast leads. By growth pace, specialty yeast is expanding most quickly.
Application:
Cost tier stratification separates clinical-grade formulations from commodity feed additives, with dietary supplements capturing 3-5x the unit economics of bulk animal nutrition applications.
- Dietary Supplements:Capsule, tablet, and powder formats delivering 10^9 CFU minimum viable counts with strain-specific identity preservation. United States direct-to-consumer channels and Swiss contract manufacturing clusters concentrate demand where GRAS self-affirmation and stability documentation justify premium shelf positioning.
- Animal Feed:Pellet-compatible and rumen-stable formulations for antibiotic replacement in EU livestock operations. German and French dairy producers under EU Veterinary Medicines Regulation mandates are the primary volume purchasers seeking documented weight gain performance.
- Food & Beverages:Functional fortification in ambient-stable formats, constrained by thermal processing limits that exclude live cultures from most hot-fill applications without microencapsulation investments.
- Pharmaceuticals:Prescription and over-the-counter enteric formulations for antibiotic-associated diarrhea, with clinical trial substantiation requirements limiting supplier participation to credentialed fermentation houses.
Animal feed dominates shipment volumes. Dietary supplements are gaining share fastest through premium positioning.
End User:
Customer type determines procurement sophistication, with healthcare providers demanding batch-level certificates of analysis and retail consumers responding to strain-specific branding claims.
- Healthcare Providers:Hospitals, clinics, and veterinary practices prescribing Saccharomyces boulardii for gastrointestinal indications. United States gastroenterology practices and French hospital pharmacies concentrate demand where formulary inclusion requires published clinical evidence.
- Animal Nutritionists:Herd health consultants and feed formulators specifying strain-specific yeast additives for precision livestock operations. Wisconsin and California dairy consultants are displacing traditional wholesale channels through direct e-commerce procurement.
- Food Manufacturers:Clean-label product developers sourcing inactivated yeast for texture and umami modulation, with R&D collaboration requirements driving preferred supplier relationships.
- Retail Consumers:Mass-market purchasers of shelf-stable supplements, price-sensitive to branded versus private-label positioning but increasingly responsive to CFU count transparency on packaging.
Animal nutritionists purchase the largest individual order quantities. Healthcare providers are climbing the fastest as prescription and practitioner-channel formats expand.
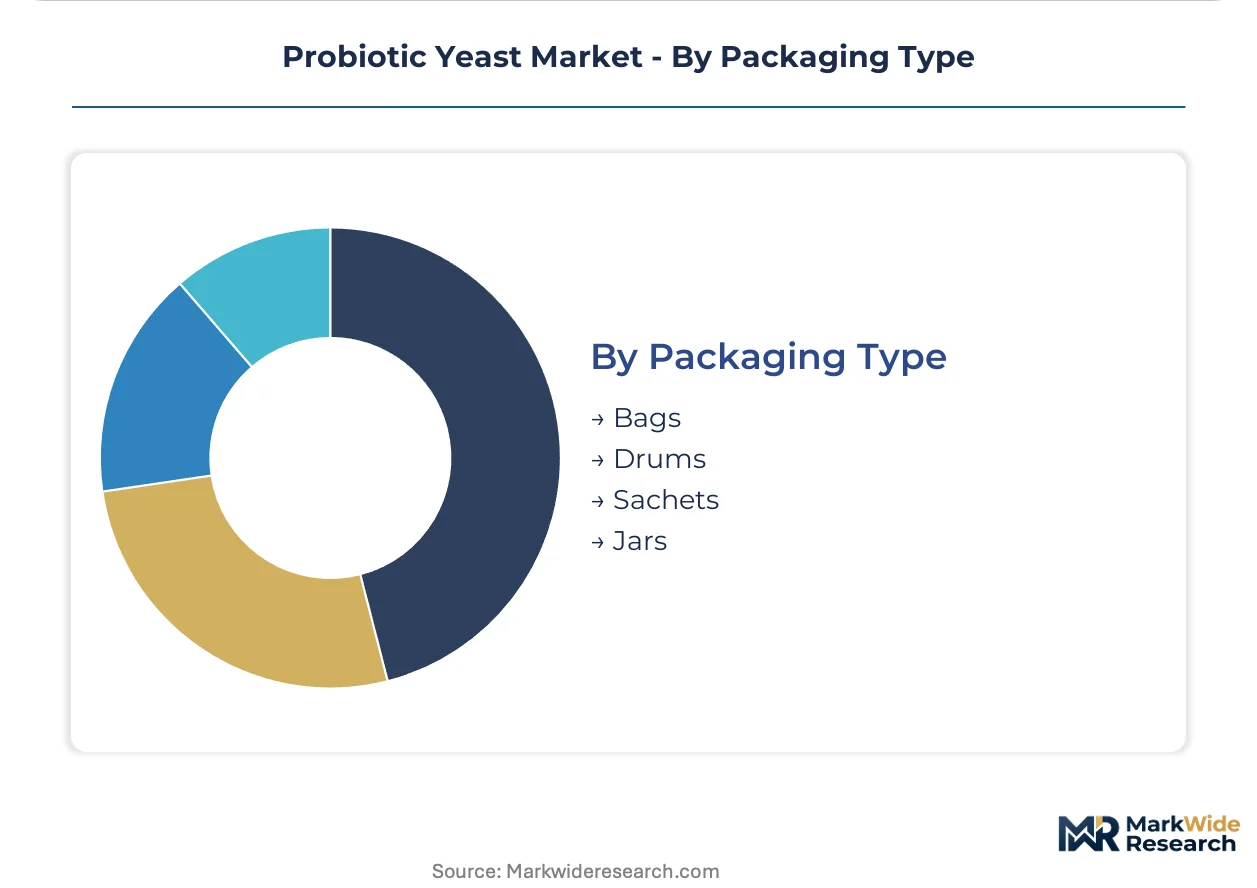
Packaging Type:
Supply concentration in industrial formats reflects the feed industry's volume dominance, while unit-dose innovation targets supplement channel premiumization.
- Drums:Multi-kilogram industrial containers for bulk active ingredient shipment to contract manufacturers and feed mills. Montreal and Yichang fermentation complexes ship primarily in this format to European and North American compounding facilities.
- Sachets:Single-serve moisture-barrier pouches for clinical and travel-use probiotic yeast. Swiss lyophilization specialists are expanding sachet filling capacity as shelf-stable formats displace refrigerated distribution.
- Bags:Intermediate bulk flexible containers for nutritional yeast and feed-grade biomass, with modified atmosphere options for oxidation-sensitive products.
- Jars:Consumer-facing rigid packaging for powder supplements, requiring desiccant integration and light-blocking opacity to preserve viability through retail shelf life.
Drums lead by tonnage shipped. Sachets show the steepest expansion trajectory as unit-dose convenience penetrates practitioner and direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China exhibit the highest price elasticity, prioritizing unit cost over strain-specific documentation. German and French purchasers accept substantial premiums for EFSA-validated isolates. United States demand splits between cost-driven feed applications and premium supplement channels.
United States
Direct-to-practitioner procurement is displacing wholesale veterinary supply chains for livestock probiotic yeast. FDA GRAS self-affirmation pathways enable faster strain commercialization than European novel food routes. Wisconsin and California dairy operations exceeding 500 head now purchase strain-specific formulations through specialized e-commerce portals providing batch-level certificates of analysis.
Germany
Dietary supplement manufacturers command premium pricing for EFSA-approved heat-inactivated yeast cell wall components with beta-glucan immunomodulatory claims. EU Veterinary Medicines Regulation mandates accelerate antibiotic replacement with Saccharomyces cerevisiae feed additives in livestock operations. The Marcq-en-Baroeul industrial cluster anchors European yeast propagation through vertically integrated fermentation infrastructure.
France
Hospital pharmacies and gastroenterology practices concentrate demand for prescription Saccharomyces boulardii formulations requiring published clinical evidence. EFSA novel food approvals for postbiotic definitions drive reformulation pipelines toward toll-like receptor activation pathways. Paris and Lyon serve as formulation hubs where contract manufacturers retrofit lyophilization lines for yeast cell diameters.
China
NMPA health food blue-hat registration creates divergent compliance burdens for multinational suppliers seeking market entry. Angel Yeast Co. Ltd.'s Yichang production complex dominates Asian manufacturing scale through bulk nutritional yeast output. Domestic buyers prioritize unit economics over strain-specific substantiation, compressing margins for credentialed international players.
India
FSSAI functional food regulations are evolving to create first-mover advantage for suppliers establishing local strain characterization capabilities. Livestock producers seek antibiotic alternatives under veterinary prescription restrictions, though price sensitivity limits adoption of premium isolates. Mumbai and Ahmedabad fermentation facilities are expanding capacity to serve regional feed compounders.
Probiotic Yeast Market Key Industry Players
Capability concentration sits with heritage fermentation houses possessing strain banking infrastructure and clinical substantiation archives; scale advantage sits with bulk nutritional yeast producers competing on unit cost and geographic proximity to molasses supply. The market structures around three tiers: patent-protected specialty isolate suppliers, vertically integrated regional propagators, and commodity biomass traders. Consolidation pressure intensifies as EFSA and FDA evidence thresholds rise, favoring players with captive R&D infrastructure. Dominant competitive moves include backward integration into molasses sourcing and technology licensing for microencapsulation stability.
Within the heritage fermentation tier, Lallemand Inc. and Lesaffre Group exemplify capability concentration through strain development control from culture collection to finished active ingredient. Angel Yeast Co. Ltd. anchors the scale-driven Asian manufacturing position. DSM-Firmenich and Chr. Hansen Holdings A/S occupy intermediate positions bridging pharmaceutical-grade substantiation with nutritional applications. Kerry Group and ADM represent diversified ingredient conglomerates leveraging existing distribution infrastructure for market access.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Lesaffre Group |
| Angel Yeast Co. Ltd. |
| Chr. Hansen Holdings A/S |
| Alltech |
| DSM-Firmenich |
| ADM |
| Kerry Group |
| Associated British Foods Plc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese nutritional yeast fermentation is compressing global spot prices while simultaneously forcing European and North American suppliers toward specialty isolate premiumization. This utilization asymmetry rewards players with strain banking infrastructure and EFSA novel food dossiers while punishing bulk biomass traders exposed to molasses cost volatility.
Pricing Analysis
Ingredient-as-a-service contracts and multi-year stability guarantees drive lifetime value for specialty yeast suppliers serving German and French dietary supplement channels. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated isolates from GRAS-affirmed commodities and uncharacterized bulk biomass. Cost compression in the nutritional yeast tier is intensifying because Angel Yeast's Yichang scale advantages and domestic Chinese demand softness. Animal feed compounders in India exhibit highest price sensitivity, while United States gastroenterology practices accept substantial premiums for batch-documented CFU stability.
Supply Chain Analysis
Molasses feedstock from Brazilian cane and Indian beet operations anchors fermentation economics for bulk yeast producers, with supply concentration in these two countries creating correlated commodity risk. Saccharomyces boulardii reference cultures draw from European national strain banks, amplifying licensing bottlenecks for North American and Asian developers seeking proprietary isolates. Single-source vulnerability in authenticated reference materials threatens commercialization timelines for credentialed entrants. Distribution runs through Montreal and Yichang fermentation complexes to regional compounding facilities, with drum-format industrial shipment dominating tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology repurposed from alternative protein platforms is disrupting traditional yeast propagation economics, compressing development cycles for pharmaceutical-grade beta-glucan extraction and reshaping competitive moats around strain-specific substantiation archives.
For Market Incumbents: Harden strain banking infrastructure against phage contamination through clean-room propagation upgrades, and deepen captive R&D pipelines around clinically validated isolates before EFSA evidence thresholds tighten further. Patent-protected specialty isolates face margin pressure from recombinant protein platforms; backward integration into molasses sourcing defends feedstock security against Brazilian crop volatility. For New Entrants and Emerging Players: India's evolving FSSAI functional food regulations represent the most penetrable entry point for suppliers establishing local strain characterization capabilities ahead of multinational licensing. United States direct-to-practitioner veterinary channels for livestock probiotic yeast offer second white-space opportunity, with specialized e-commerce portals displacing traditional wholesale supply chains. Target precision feeding consultants in Wisconsin and California dairy operations through batch-level certificate of analysis protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage fermentation houses possessing vertically integrated propagation networks and clinical substantiation archives. Long-term viability across the analysis window favors players with captive strain development infrastructure over commodity biomass traders exposed to molasses price cycles. Watch for EFSA postbiotic guidance enforcement as inflection signal separating cell wall fraction processors from live culture suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Infrastructure Investment | Clean-room propagation capacity in Montreal and Marcq-en-Baroeul secures phage-resistant supply continuity for credentialed suppliers. |
| EFSA Novel Food Dossier Submission | Postbiotic definitions for heat-inactivated yeast unlock premium positioning in German and French immunomodulatory supplement channels. |
| Precision Fermentation Platform Repurposing | Recombinant protein infrastructure originally built for alternative proteins enables pharmaceutical-grade beta-glucan extraction economics. |
| Direct-to-Practitioner Channel Development | Specialized e-commerce portals providing batch-level certificates of analysis displace wholesale veterinary supply chains in Wisconsin and California. |
| Molasses Supply Contract Securement | Long-term offtake agreements with Brazilian and Indian sugar processors hedge fermentation cost volatility for bulk nutritional yeast output. |
Research Approach
A spread of perspectives from fermentation process engineers, regulatory affairs specialists at EFSA and FDA, veterinary nutrition consultants, dietary supplement contract manufacturers, and hospital pharmacy procurement managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation through EFSA novel food register entries, FDA GRAS notification filings, FSSAI functional food guidance documents, and trade flow data from customs records. Bottom-up strain-level demand modeling and top-down sector aggregation were triangulated to establish market size boundaries.
Demand-supply-balance dynamics across the analysis window were modeled through segmented adoption curves for specialty yeast isolates, nutritional yeast fortification applications, and animal feed antibiotic replacement. Segmentation dimensions included product type tier, application channel, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical EFSA approval timelines and veterinary prescription restriction implementation schedules. Forecast inputs incorporated lyophilization technology diffusion rates and precision fermentation platform repurposing announcements.
Practitioners should monitor EFSA novel food approval velocity, Brazilian molasses spot price movements, and FSSAI registration pathway finalization for early signals of forecast revision. Quarterly review of strain-specific substantiation standards, phage contamination incident reports, and direct-to-practitioner channel penetration metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Eubiotics Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market