
 Global Genotyping Assay Market | 2026-2036
Global Genotyping Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Genotyping Assay Market Foresight
The performance gap between premium and commodity genotyping tiers is broadening as clinical-grade assays require FDA-cleared instruments while research laboratories accept lower-cost PCR-based alternatives. Thermo Fisher Scientific Inc. leverages its vertical integration across reagent manufacturing and thermal cycler production to sustain margin capture in both segments. Illumina, Inc. anchors the high-throughput sequencing tier through instrument placement strategies that lock in consumable pull-through. QIAGEN competes in sample preparation workflows that bridge quality levels across the price spectrum.
A genotyping assay is a laboratory procedure that detects specific DNA sequence variations—typically single nucleotide polymorphisms, insertions, deletions, or copy number variants—using fluorescent probes, hybridization matrices, or sequencing chemistries to generate discrete genetic profiles for diagnostic or research purposes. PCR-based assays occupy the largest installed base due to established protocols and accessible instrumentation, while next-generation sequencing captures the fastest expansion as clinical laboratories validate comprehensive panels for oncology and rare disease applications. Pharmacogenomics represents a concentrated margin pool where diagnostic laboratories and health systems negotiate reimbursement for drug-gene interaction testing.
The FDA regulates clinical genotyping assays as in vitro diagnostics under 21 CFR Part 820 quality system requirements, while the EMA's In Vitro Diagnostic Regulation mandates notified body certification for CE-marked products entering European clinical laboratories. ISO 15189 accreditation shapes operational standards for diagnostic laboratories processing patient samples across multiple jurisdictions. Stakeholders must monitor how divergent regulatory timelines between the FDA's premarket approval pathway and the EU IVDR transition create competitive windows for market entry in each geography.
Market Dynamics
The FDA's 2024 guidance on next-generation sequencing-based oncology panels is compressing validation timelines and forcing clinical laboratories to choose between rapid panel deployment and comprehensive analytical validation protocols.
Growth Catalysts
- Pharmacogenomics Integration:Academic medical centers in the United States are embedding drug-gene interaction testing into routine clinical workflows, creating standardized demand for CLIA-validated assays.
- EMA IVDR Transition:The European Union's In Vitro Diagnostic Regulation mandates notified body certification for CE-marked products, accelerating consolidation among manufacturers capable of meeting enhanced quality system requirements.
- NGS Platform Manufacturing:China's biocluster corridor between Shanghai and Suzhou is scaling domestic next-generation sequencing instrument production, reducing import dependency for regional clinical laboratories.
Market Restraints
- Consumable Cost Concentration:Reagent pricing remains tethered to proprietary instrument lock-in strategies, limiting laboratory negotiating leverage against Thermo Fisher and Illumina consumable bundles.
- Validation Timeline Burden:FDA premarket approval pathways for complex genotyping panels extend 18-24 months, freezing product pipelines for mid-tier assay developers.
- PCR Substitution Ceiling:Established polymerase chain reaction protocols in research settings resist displacement despite next-generation sequencing's superior multiplexing capacity.
Strategic Opportunities
- Direct-to-Consumer Channel:Regulatory frameworks in the United Kingdom are stabilizing for wellness-oriented genetic screening, opening pharmacy and telehealth distribution pathways.
- Artificial Intelligence Convergence:Machine learning variant classification algorithms are compressing bioinformatics bottlenecks, enabling smaller laboratories to offer clinical-grade interpretation without captive bioinformatics teams.
- Rare Disease Panel Expansion:Japan's PMDA has streamlined orphan disease test reimbursement, creating concentrated demand for comprehensive exome sequencing in pediatric tertiary centers.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories face acute shortages of variant scientists capable of bridging wet-lab assay performance with regulatory-grade interpretation pipelines.
- Legacy LIMS Integration:Hospital information systems built on decade-old laboratory information management architectures resist seamless genotyping data flow, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Genotyping Assay Market |
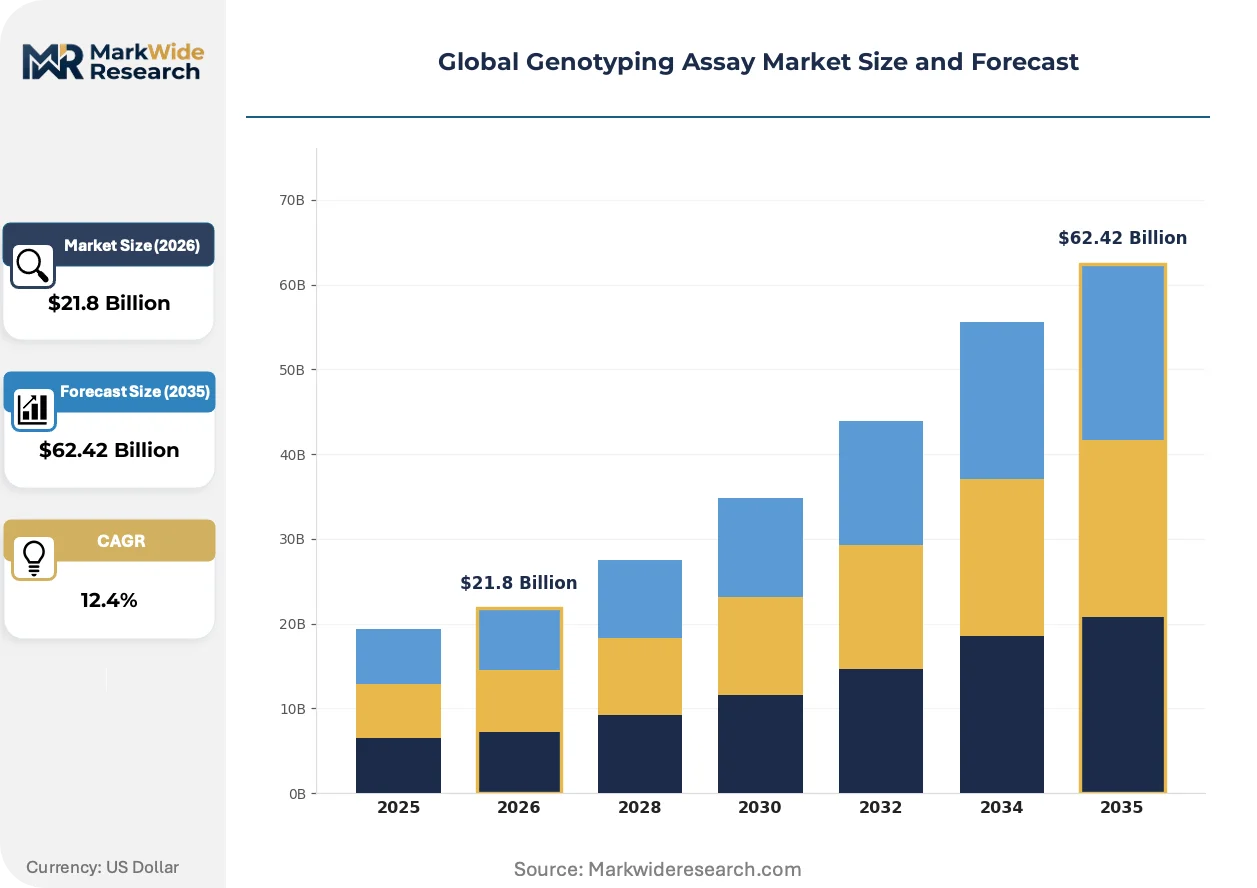
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $62.42 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarray, PCR-Based Assays, Next-Generation Sequencing, Single Nucleotide Polymorphism, DNA Hybridization Application: Pharmacogenomics, Agricultural Biotechnology, Forensic Analysis, Genetic Disease Research, Ancestry Testing End User: Research Institutes, Biotech Companies, Diagnostic Laboratories, Academic Centers, Government Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Outsourced Services, Mobile Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina, Inc., Danaher Corporation, QIAGEN, Agilent Technologies, F. Hoffmann-La Roche Ltd., Bio-Rad Laboratories Inc., Eurofins Scientific, Revvity Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Genotyping Assay Market Shifts & Advancements
Three intersecting developments are restructuring competitive positioning: point-of-care nucleic acid testing platforms, regulatory harmonization pressures across the FDA-EMA divergence, and procurement centralization by integrated delivery networks.
Portable PCR and isothermal amplification devices are decentralizing infectious disease and pharmacogenomic testing from centralized reference laboratories into ambulatory settings and retail pharmacy clinics. Community health systems in the United States are piloting these platforms for same-day warfarin and clopidogrel dosing protocols. This geographic redistribution of testing capacity is compressing reference laboratory specimen volumes while expanding addressable test occasions.
The EU's In Vitro Diagnostic Regulation is forcing manufacturers to rebuild technical documentation for legacy assays previously self-certified under the IVDD framework. German notified bodies are experiencing 14-month backlogs for conformity assessments, delaying CE-marked product launches. Manufacturers are responding by sequencing regulatory submissions to prioritize FDA 510(k) clearance for United States market entry while European approvals lag.
Integrated delivery networks in the United States are consolidating genotyping procurement under centralized laboratory stewardship committees, replacing individual hospital laboratory purchasing autonomy. These committees negotiate multi-year sole-source agreements with preferred vendors, extracting volume discounts in exchange for consumable exclusivity. The concentration of buying power is most visible in Texas and Florida health systems where Catholic and for-profit IDNs control regional laboratory services.
Global Genotyping Assay Market Segmentation
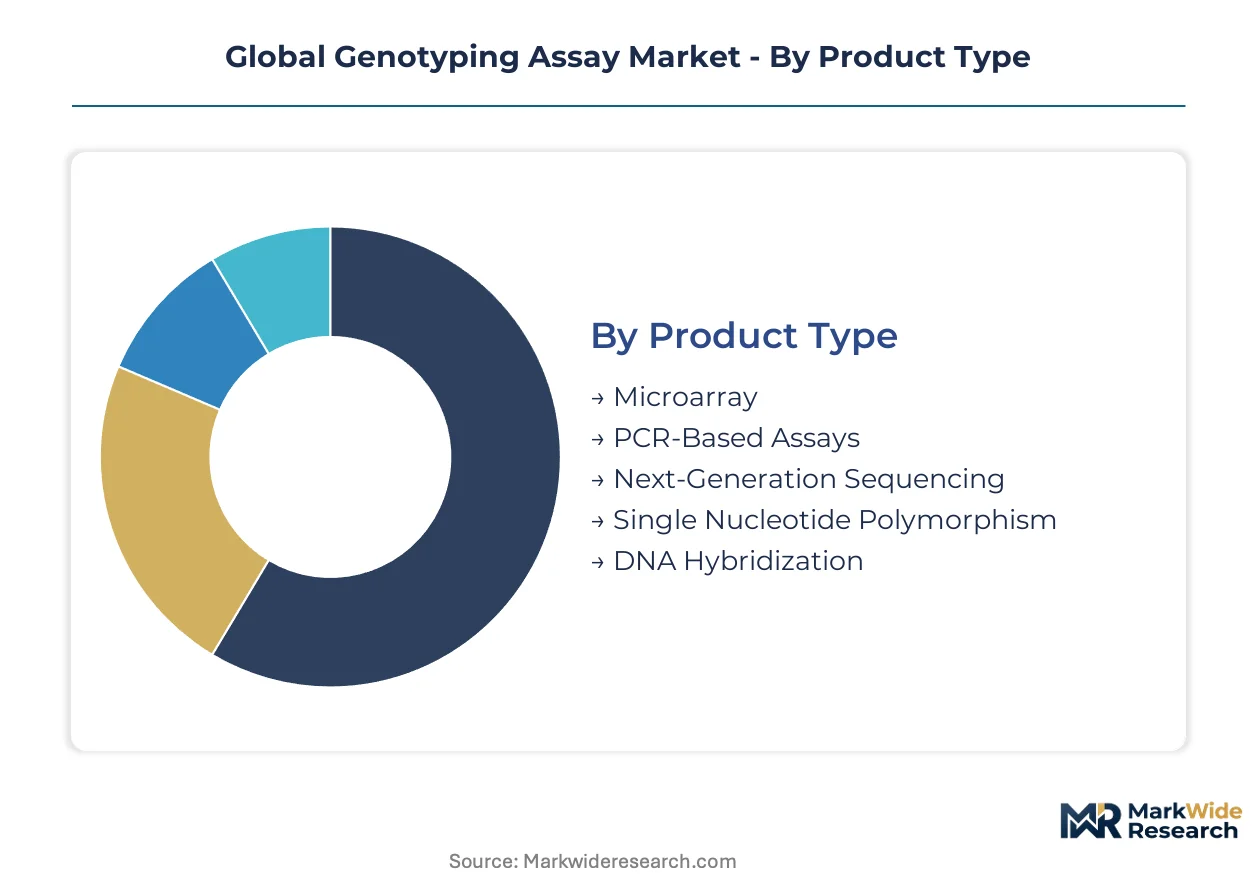
Genotyping assay segmentation reveals how technical specifications, regulatory pathways, and end-use economics fragment procurement decisions across clinical and research environments. Supply concentration varies dramatically by product tier, with FDA-cleared platforms commanding premium positioning against commoditized research-grade alternatives.
Product Type:
Supply concentration clusters around instrument-reagent bundling strategies that lock laboratories into proprietary consumable ecosystems.
- Microarray:High-density oligonucleotide arrays enable parallel interrogation of thousands of loci simultaneously. Agricultural biotechnology programs in Brazil and research consortia in Germany sustain demand for this mature format despite NGS displacement pressure.
- PCR-Based Assays:Thermal cycling amplification of target sequences remains the most accessible entry point for resource-constrained settings. Community hospitals across India's tier-2 cities and point-of-care clinics in Nigeria rely on this technology for pharmacogenomic and infectious disease applications where infrastructure limitations preclude sequencing platforms.
- Next-Generation Sequencing:Massively parallel sequencing chemistries dominate oncology panel validation workflows at academic medical centers in the United States and tertiary hospitals in South Korea.
- Single Nucleotide Polymorphism:Targeted detection of point mutations supports ancestry testing direct-to-consumer channels in the United Kingdom and paternity testing laboratories in Italy.
- DNA Hybridization:Probe-based sequence matching retains niche utility in forensic reference laboratories processing criminal casework in Australia and Canada.
Today's leader: PCR-Based Assays. Tomorrow's challenger: Next-Generation Sequencing.
Application:
Margin capture potential separates clinical reimbursement-eligible testing from research-funded discovery work.
- Pharmacogenomics:Drug-gene interaction testing guides therapeutic dosing decisions at Vanderbilt University Medical Center and other academic institutions embedding preemptive genotyping into electronic health records. United States health systems negotiate coverage with private payers for CYP2C19 and SLCO1B1 variants.
- Agricultural Biotechnology:Marker-assisted selection accelerates crop improvement programs at Bayer's Monheim research campus and Chinese Academy of Agricultural Sciences facilities in Beijing. Seed companies in Iowa and São Paulo contract genotyping services for genomic estimated breeding value calculations.
- Forensic Analysis:STR profiling and mitochondrial sequencing support criminal DNA databases maintained by the FBI and analogous agencies across European Union member states.
- Genetic Disease Research:Rare variant discovery drives funding at Wellcome Sanger Institute and RIKEN Center for Integrative Medical Sciences in Yokohama.
- Ancestry Testing:Consumer-facing genetic genealogy products face regulatory stabilization in France and Germany following earlier restrictions on direct-to-consumer health claims.
Pharmacogenomics commands the steepest expansion trajectory as reimbursement frameworks mature; agricultural biotechnology offers defensive volume stability against clinical cyclicality.
End User:
Procurement authority and validation requirements reshape vendor access patterns across institutional categories.
- Research Institutes:Basic science laboratories at Max Planck Institute and Broad Institute prioritize multiplexing flexibility and publication-grade data quality over regulatory certification.
- Biotech Companies:Pharmaceutical development groups at Roche and Novartis contract genotyping for biomarker qualification in clinical trials.
- Diagnostic Laboratories:CLIA-certified facilities at LabCorp and Quest Diagnostics process patient samples under FDA oversight for clinical decision support.
- Academic Centers:Medical school-affiliated hospitals in Texas and Florida integrate pharmacogenomics into routine prescribing workflows.
- Government Agencies:Public health laboratories at CDC and ECDC deploy genotyping for pathogen surveillance and outbreak investigation.
Diagnostic Laboratories concentrate revenue capture today; Academic Centers are scaling fastest as implementation science matures.
Deployment:
Capital intensity and data sovereignty concerns fragment infrastructure strategies across laboratory networks.
- On-Premises:Installed instruments within hospital laboratory walls satisfy HIPAA and GDPR data localization requirements at Mayo Clinic and Charité – Universitätsmedizin Berlin.
- Cloud-Based:Variant interpretation pipelines hosted on AWS and Azure enable smaller laboratories to access clinical-grade bioinformatics without captive informatics teams.
- Hybrid:Mixed architectures separate primary analysis on local servers from tertiary interpretation in cloud environments at medium-sized regional health systems.
- Outsourced Services:Reference laboratory contracts at BGI Genomics and Eurofins Genomics absorb overflow capacity and specialized testing menus.
- Mobile Laboratories:Containerized sequencing units deployed by Chinese public health authorities to Xinjiang and Tibet address geographic access gaps.
On-Premises retains regulatory preference; Cloud-Based deployment gains share fastest as security frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Variant scientists and bioinformatics specialists concentrate in the United States, Germany, China, Japan, and the United Kingdom, anchoring regional competitive positioning through specialized workforce availability and research infrastructure depth.
United States
Academic medical centers at Vanderbilt University Medical Center and Mayo Clinic embed pharmacogenomics into electronic health record workflows. FDA premarket approval pathways for complex genotyping panels extend 18-24 months, freezing pipelines for mid-tier developers. The Boston-Cambridge corridor concentrates CRISPR and NGS platform startups alongside established sequencing service providers.
Germany
Notified bodies in Germany experience 14-month backlogs for IVDR conformity assessments, delaying CE-marked product launches. The EMA's In Vitro Diagnostic Regulation mandates technical documentation rebuilds for legacy assays previously self-certified under IVDD. Munich and Heidelberg host dense clusters of molecular diagnostics manufacturers and clinical research organizations serving European hospital networks.
China
Domestic NGS platform builders scale manufacturing capacity in the Shanghai-Suzhou biocluster corridor, reducing import dependency for regional clinical laboratories. NMPA regulatory frameworks accelerate approval timelines for locally manufactured sequencing instruments versus imported alternatives. Beijing and Shenzhen anchor competing innovation hubs for CRISPR-based diagnostic development and point-of-care nucleic acid testing platforms.
Japan
PMDA streamlined orphan disease test reimbursement, creating concentrated demand for comprehensive exome sequencing in pediatric tertiary centers. METI funding programs support domestic genotyping assay manufacturers competing against imported platforms. The Kanto region around Tokyo and Yokohama concentrates pharmaceutical company genotyping contracts for biomarker qualification in clinical trials.
United Kingdom
Regulatory frameworks stabilize for wellness-oriented genetic screening, opening pharmacy and telehealth distribution pathways for direct-to-consumer channels. The Wellcome Sanger Institute in Cambridge drives rare variant discovery funding that sustains research-grade genotyping demand. London health systems pilot same-day pharmacogenomic testing protocols in community pharmacy settings.
Global Genotyping Assay Market Competitive Landscape
Top-tier vendors anchor the FDA-cleared instrument segment, while mid-tier assay developers compete on research-grade PCR-based alternatives. Thermo Fisher Scientific Inc. leverages backward integration across reagent manufacturing and thermal cycler production to sustain margin capture across both segments. Illumina, Inc. anchors the high-throughput sequencing tier through instrument placement strategies that lock in consumable pull-through. Strategic moves concentrate on M&A for bioinformatics capabilities and capacity expansion in China's biocluster corridor.
Within the vertically integrated tier, Thermo Fisher Scientific Inc., Illumina, Inc., and QIAGEN exemplify distinct competitive archetypes. Thermo Fisher represents the full-stack reagent-to-instrument model spanning both clinical and research quality levels. Illumina occupies a position as the sequencing platform anchor, with consumable bundling strategies defining laboratory lock-in economics. QIAGEN sits within the sample preparation workflow niche that bridges quality tiers across the price spectrum. These three structures illustrate how supply concentration in genotyping assays fragments across technical specifications and regulatory pathways rather than consolidating around interchangeable commodity positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Danaher Corporation |
| QIAGEN |
| Agilent Technologies |
| F. Hoffmann-La Roche Ltd. |
| Bio-Rad Laboratories Inc. |
| Eurofins Scientific |
| Revvity Inc. |
| Others |
Supply & Pricing Matrix
Fluorescent probe chemistries flow from specialty reagent manufacturers in Germany and the United States through three distinct pricing tiers before reaching end laboratories. Research-grade PCR consumables absorb minimal regulatory markup, while FDA-cleared NGS reagent bundles carry proprietary instrument lock-in premiums that compress laboratory negotiating leverage. The cost cascade intensifies as China's NMPA accelerates domestic platform approvals, forcing multinational suppliers to reposition mid-tier offerings.
Pricing Analysis
Bundled instrument-reagent contracts dominate clinical laboratory procurement, while unbundled reagent sales persist in research settings with lower switching costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared oncology panels from CLIA-validated research assays and commodity PCR primers. Cost compression in the standard tier is intensifying because domestic Chinese manufacturers are scaling NGS platform production. Academic medical centers demonstrate highest price sensitivity due to grant-funded budget constraints, while integrated delivery networks extract volume discounts through sole-source agreements.
Supply Chain Analysis
Domestic-content mandates in China's biocluster corridor between Shanghai and Suzhou are reshaping sourcing patterns for regional clinical laboratories. Manufacturing concentrates in China, Germany, and the United States, with oligonucleotide synthesis anchored in Rhineland facilities and thermal cycler assembly distributed across Shenzhen and Carlsbad. The chain draws from fluorophore dyes, polymerase enzymes, and semiconductor detection chips as critical inputs. Single-source vulnerability concentrates in Illumina's patterned flowcell supply. Distribution runs through authorized distributor networks serving hospital laboratory stewardship committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
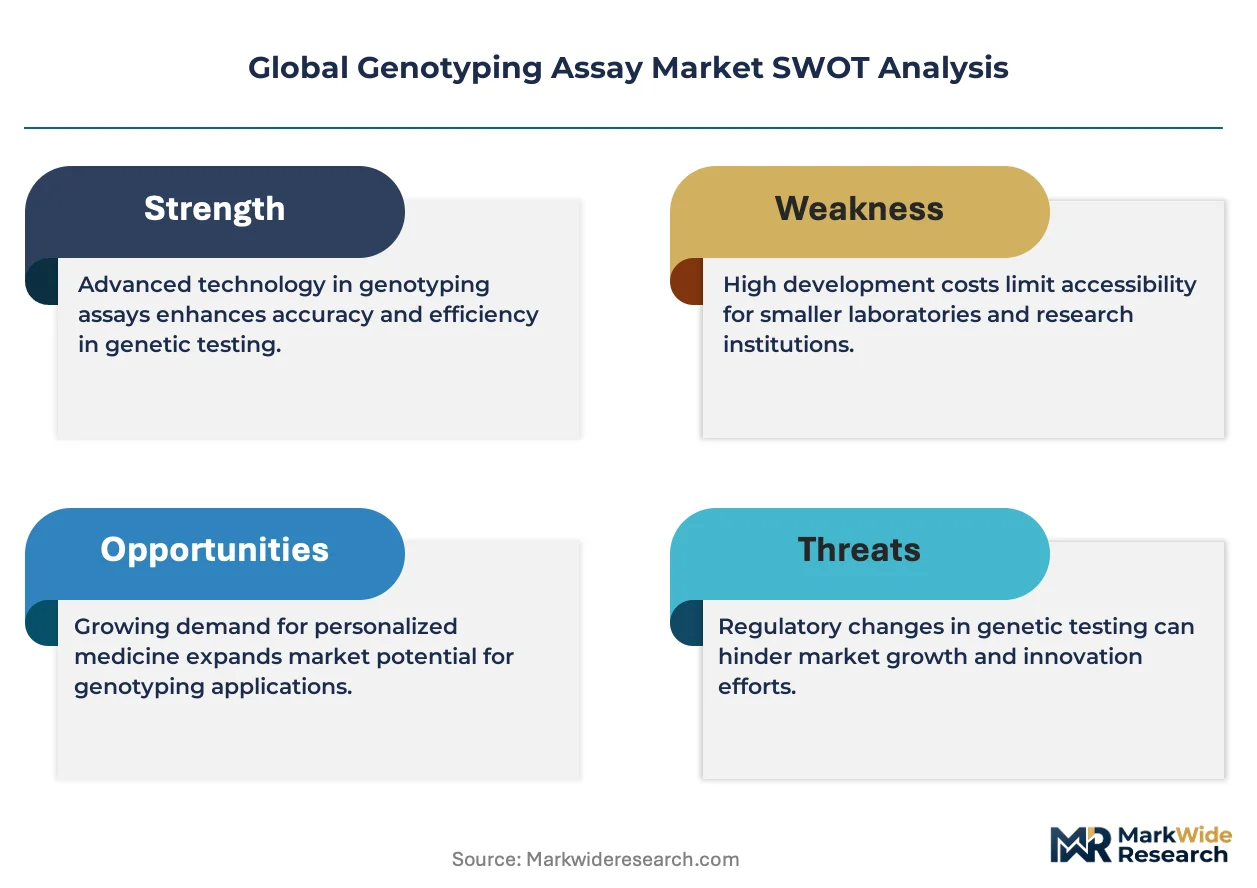
The Global Genotyping Assay Market functions as a stable compounder where pharmacogenomics reimbursement expansion generates predictable recurring revenue streams. Regulatory validation requirements create durable competitive moats around incumbent positions.
For Market Incumbents: Deploy consumable bundling strategies to deepen laboratory lock-in against emerging domestic Chinese platform builders. Defensive priorities center on backward integration into oligonucleotide synthesis capacity and accelerated FDA 510(k) submissions for oncology panel expansions. The threat of NMPA-favored domestic competitors in China's biocluster corridor demands preemptive volume commitments from integrated delivery networks. For New Entrants and Emerging Players: CRISPR-based diagnostic platforms offer a technology-first wedge into point-of-care pharmacogenomic testing where infrastructure limitations preclude sequencing platforms. White-space targets concentrate in India's tier-2 city hospitals and Nigeria's community clinics seeking same-day warfarin dosing protocols. The most penetrable segment spans portable PCR devices for ambulatory settings, with pharmacy channel partnerships as the preferred go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where IVDR conformity assessment backlogs strand mid-tier European manufacturers without notified body certification. Long-term viability favors platforms with dual FDA-EMA regulatory clearance and captive bioinformatics interpretation capabilities. Acquisition targets include variant classification algorithm developers and sample preparation workflow specialists. Watch for PMDA orphan disease reimbursement expansion in Japan as the signal indicating exome sequencing demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Conformity Assessment Completion | German notified body certification unlocks CE-marked product launches across European hospital networks. |
| Pharmacogenomics EHR Integration | Vanderbilt University Medical Center-style preemptive genotyping embeds testing into routine prescribing workflows. |
| Domestic NGS Platform Manufacturing | Shanghai-Suzhou biocluster production reduces import dependency for China's regional clinical laboratories. |
| AI Variant Classification Development | Machine learning algorithms compress bioinformatics bottlenecks for smaller laboratories without captive informatics teams. |
| Point-of-Care PCR Miniaturization | Portable thermal cycling devices decentralize testing from reference laboratories into retail pharmacy clinics. |
Research Methodology
Bottom-up diagnostic laboratory procurement modeling reconciled against top-down NGS instrument placement tracking forms the analytical core of this study. Primary interviews with CLIA laboratory directors, FDA regulatory affairs specialists, hospital purchasing committee members, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov pharmacogenomic protocol registrations, and CMS Medicare reimbursement databases. Cross-referencing manufacturer consumable revenue disclosures against installed instrument bases enables triangulation of market sizing.
Historical trendline analysis of academic medical center pharmacogenomics program rollouts and integrated delivery network consolidation patterns informs projection frameworks. Segmentation modeling spans product type, application, end user, and deployment architecture dimensions across the analysis window. CAGRs derive from instrument replacement cycles, consumable pull-through rates, and reimbursement expansion trajectories. Forecast inputs incorporate NMPA approval velocity for domestic Chinese platforms and PMDA orphan disease test coverage decisions.
The model holds under stable regulatory reimbursement conditions; deviation in FDA guidance timelines or IVDR notified body capacity would shift competitive entry windows. Forecasts reflect documented assumptions regarding pharmacogenomics adoption curves and NGS panel validation standards. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Prenatal Genetic Testing Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Restriction Endonucleases Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Genomic Biomarkers Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Oligonucleotide Pool Market
Genomics
Kearns-Sayre Syndrome Market
Genomics
North America Genetic Testing Market
Genomics
North America DNA Sequencing Products Market
Genomics
DNA Sequencing Services Market
Genomics
Europe Epigenetics Market
Genomics
Animal Genetics Market
Genomics
Cancer Biomarkers Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market