
 Microbial Pesticides Market | 2026-2036
Microbial Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Pesticides Market Outlook
Organic Materials Review Institute (OMRI) listing is rotating as the decisive gate for premium channel access in North American specialty agriculture. Bayer leverages its global fermentation infrastructure to supply bacillus-based active ingredients at scale. Certis Biologicals anchors its position through deep specialization in bacterial and fungal biofungicides for high-value fruit and vegetable markets. Koppert Biological Systems dominates live beneficial organism distribution with controlled cold-chain logistics across European horticulture.
Microbial pesticides are biologically derived crop protection agents containing viable microorganisms—bacteria, fungi, viruses, or protozoa—as active ingredients, typically formulated with cell counts exceeding 10^8 colony-forming units per gram and stabilized through desiccation or oil encapsulation to ensure field viability. These agents function through pathogenic infection, competitive exclusion, or induced systemic resistance in host plants, serving as alternatives or complements to synthetic chemistry in integrated pest management programs. Bacterial formulations currently command the largest share of commercial volume given their ease of industrial fermentation and broad-spectrum efficacy against lepidopteran and coleopteran pests. Liquid formulations attract the fastest growth in adoption due to compatibility with precision application equipment and drip irrigation systems. Agricultural applications retain the deepest margin pools where row-crop operators calculate biological inputs against yield protection value.
EPA biopesticide registration under FIFRA Section 3(c)(5) shapes product development timelines and label claims, while EU REACH and the Sustainable Use Directive constrain synthetic chemical alternatives and expand biological substitution incentives. USDA National Organic Program standards further codify microbial pesticides as permitted inputs, locking in channel access for certified operations. Stakeholders must track how EPA's streamlined biopesticide data requirements evolve relative to conventional chemistry, as this regulatory asymmetry determines competitive entry costs and portfolio allocation between biological and synthetic R&D pipelines.
Market Dynamics
EPA's streamlined biopesticide registration under FIFRA Section 3(c)(5) is compressing development timelines from conventional chemistry standards, redirecting R&D investment toward bacterial fermentation platforms and live organism formulations as resistance pressure mounts against synthetic pyrethroids in Brazil's soybean belt.
Growth Catalysts
- FIFRA Section 3(c)(5) Streamlining:EPA's reduced data requirements for biopesticides slash registration costs versus conventional chemistry, accelerating commercialization pathways for bacillus-based formulations in US specialty agriculture.
- EU Sustainable Use Directive:Mandatory reduction targets for synthetic pesticides under this framework expand biological substitution mandates across member state agricultural programs.
- Precision Application Technology:Compatibility with drip irrigation systems and drone-based spraying is pulling liquid microbial formulations into California Central Valley nut and vine operations.
Market Restraints
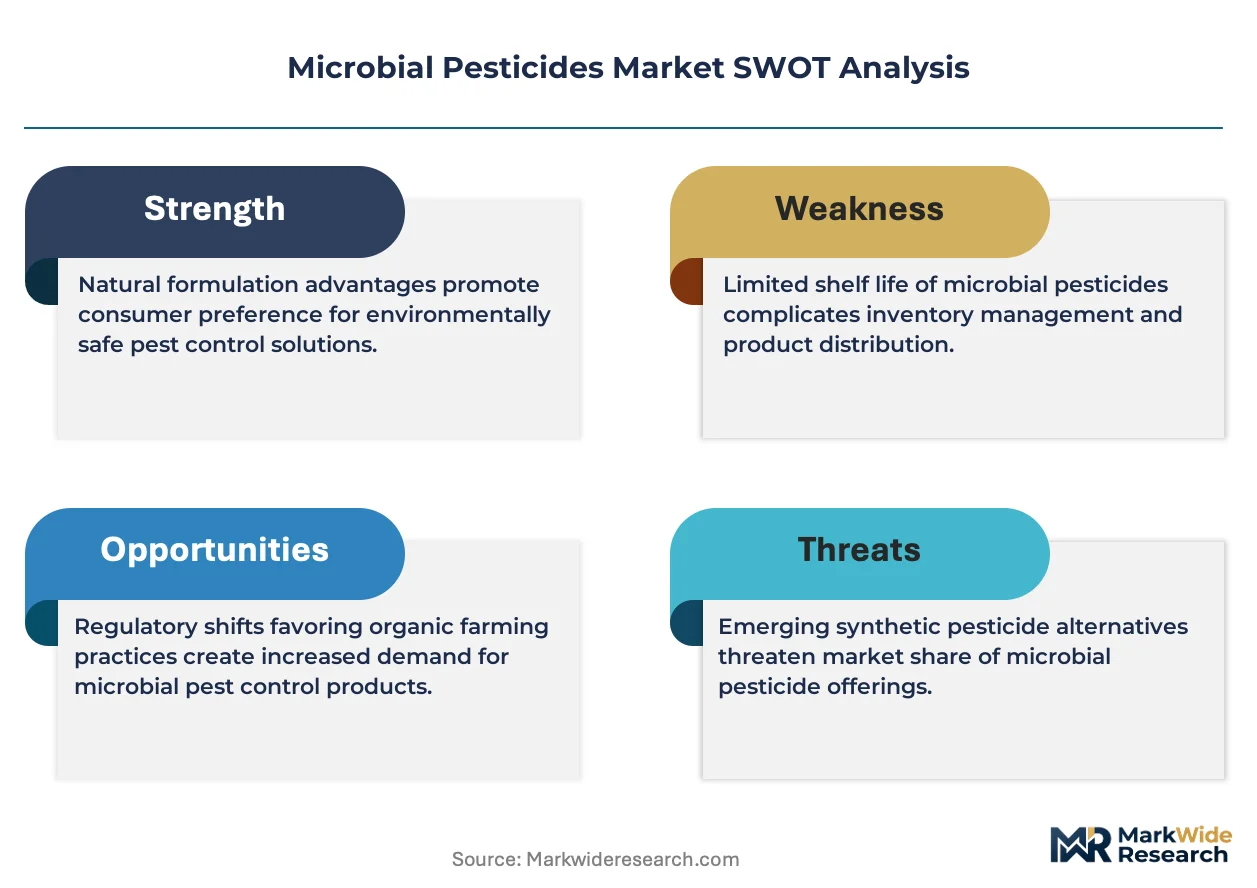
- Cold-Chain Infrastructure Costs:Live beneficial organisms require controlled temperature logistics from fermentation through field application, elevating distribution costs above chemical alternatives.
- Shelf Stability Limitations:Desiccation and oil encapsulation technologies still constrain viable cell counts below synthetic pesticide longevity standards, complicating inventory management.
- Resistance Management Complexity:Farmers must rotate microbial actives with synthetic chemistry to preserve efficacy, increasing operational planning burden versus single-mode solutions.
Strategic Opportunities
- USDA National Organic Program Certification:Codified acceptance of microbial pesticides as permitted inputs locks premium channel access for certified operations seeking OMRI-listed products.
- Seed Treatment Integration:Coating technologies enabling direct application of fungal and bacterial biocontrol agents onto planting material bypass foliar spraying constraints.
- India Specialty Crop Expansion:Horticulture intensification in Maharashtra and Karnataka creates demand for residue-free pest management compatible with export market standards.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Industrial microbiology expertise for maintaining cell viability at commercial bioreactor volumes remains concentrated among limited specialist operators.
- Field Efficacy Variability:Environmental sensitivity of live organisms to UV exposure, drought, and soil pH creates inconsistent performance versus synthetic chemistry, demanding technical support investment.
- Integrated Pest Management Integration Complexity:Compatibility testing with existing chemical programs requires extensive field validation, slowing adoption timelines among risk-averse row-crop operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Pesticides Market |
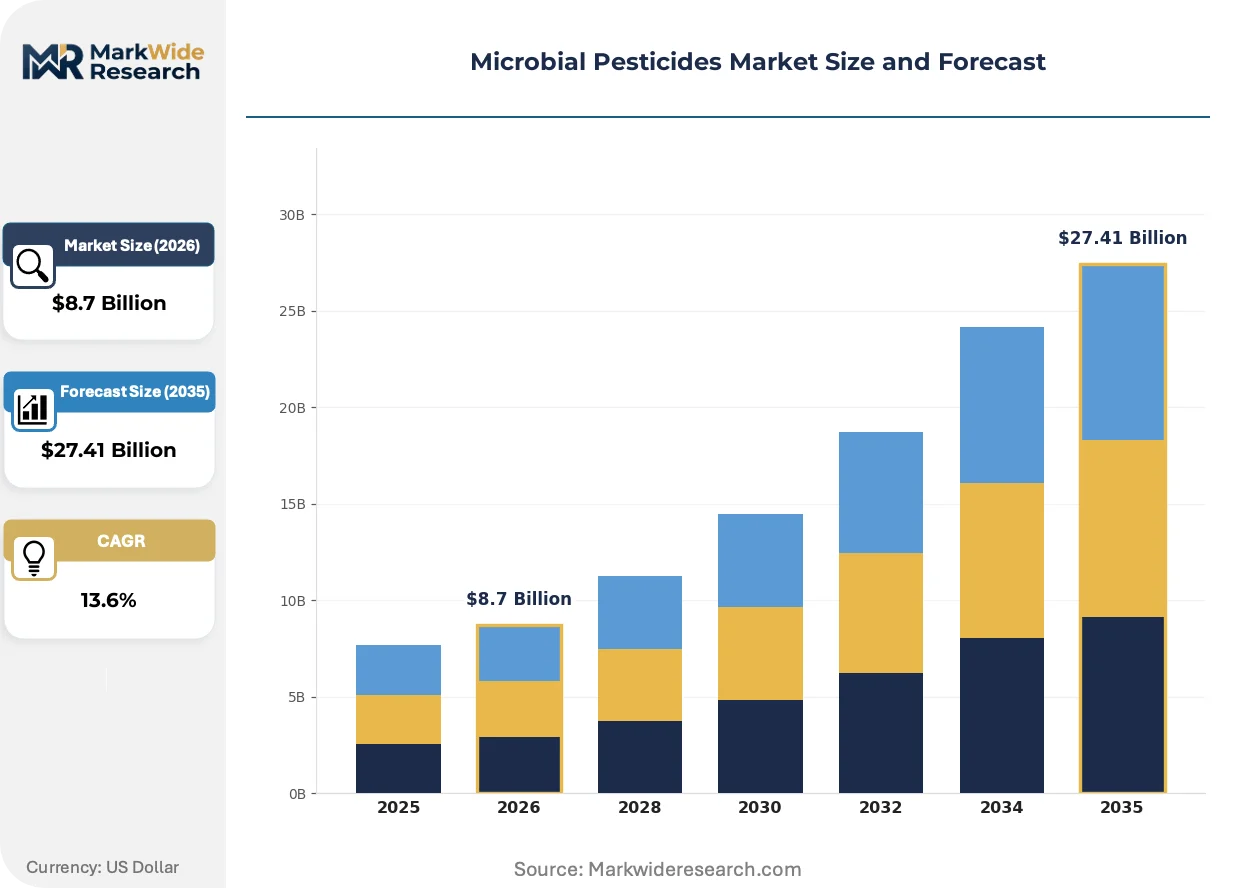
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial, Fungal, Viral, Protozoan Application: Agricultural, Horticultural, Forestry, Turf Management End User: Farmers, Agricultural Cooperatives, Garden Centers, Research Institutions Delivery Mode: Granular Formulations, Liquid Formulations, Coated Formulations, Wettable Powders |
| Companies Covered | Valent BioSciences, Corteva Agriscience, Bayer, BASF, Certis Biologicals, Koppert Biological Systems, FMC Corporation, Syngenta, Marrone Bio Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Pesticides Market Strategic Shifts
Formulation science is separating winners from followers as manufacturers engineer desiccation matrices and oil carriers that extend field viability of live organisms. This technical arms race determines which products survive distribution lag times and environmental stress at the point of application.
Encapsulation technology is bifurcating the competitive landscape. Advanced polymer and lipid shell systems protect bacterial and fungal cells from desiccation and UV degradation during storage and application. High-value fruit and vegetable growers in Mediterranean climates are adopting these premium formulations despite cost premiums. The technology is compressing margins for conventional wettable powder products that cannot match field persistence.
EU REACH registration requirements for synthetic active ingredients are tightening discharge standards for aquatic ecosystems. This regulatory pressure expands the addressable market for microbial alternatives in watershed-sensitive cropping regions. German and Dutch horticulture operations are responding by mandating biological-first pest management protocols in supplier qualification programs.
Direct-to-grower digital platforms are displacing traditional agrichemical distributor networks for microbial product procurement. Specialty crop operators in California and Florida are accessing technical documentation, application calculators, and cold-chain tracking through manufacturer portals. This channel shift is most pronounced among organic-certified farms with established OMRI verification workflows and limited local retail access.
Microbial Pesticides Market Segmentation
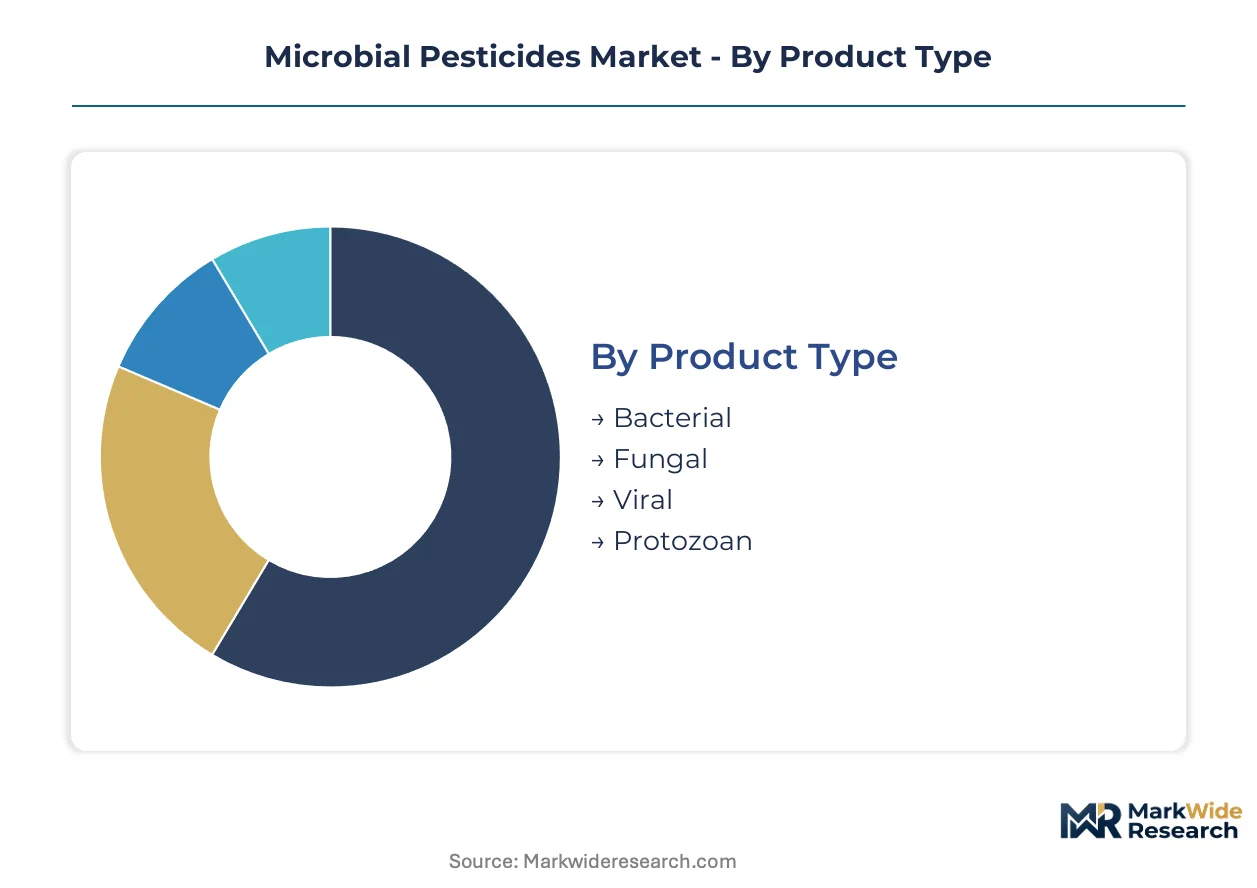
Microbial pesticide segmentation reveals distinct channel economics across product categories. Bacterial formulations flow through commodity agricultural distributors, while live organism products require specialized cold-chain networks that reshape margin structures.
Product Type:
Channel access for each microbial category depends heavily on formulation stability and storage requirements, with desiccation-tolerant bacterial products reaching broader retail networks than temperature-sensitive alternatives.
- Bacterial:Industrial fermentation of Bacillus thuringiensis and Bacillus subtilis yields stable cell concentrates exceeding 10^8 CFU per gram. California Central Valley nut growers and Brazil's soybean operators anchor volume demand as resistance to synthetic pyrethroids intensifies.
- Fungal:Trichoderma and Beauveria bassiana formulations require precise moisture control throughout distribution. European horticulture clusters in the Netherlands and Spain concentrate procurement through controlled-environment agriculture suppliers.
- Viral:Nucleopolyhedrovirus preparations target specific lepidopteran pests with high host specificity.
- Protozoan:Nosema locustae and related organisms serve niche locust and grasshopper control applications.
By volume, bacterial formulations lead. By growth pace, fungal products are ahead.
Application:
Margin pools vary dramatically across application contexts, with agricultural row crops rewarding scale efficiencies and horticultural segments paying premiums for residue-free certification compliance.
- Agricultural:Row-crop operators in Brazil and the US Midwest calculate biological inputs against yield protection value. EPA FIFRA Section 3(c)(5) registration streamlining accelerates label expansion for broad-acre deployment.
- Horticultural:High-value fruit and vegetable producers in California and Mediterranean climates absorb cost premiums for OMRI-listed products compatible with export market standards.
- Forestry:Aerial application of viral and bacterial agents targets defoliating pests across managed timber stands.
- Turf Management:Golf course and sports field operators integrate microbial grub control into maintenance protocols.
Agricultural applications generate the deepest revenue pools. Horticultural segments command the steepest price premiums per treated hectare.
End User:
Procurement sophistication divides end users between price-sensitive commodity buyers and specification-driven certified operations.
- Farmers:Individual operators in India's Maharashtra and Karnataka horticulture belts source through direct-to-grower digital platforms with OMRI verification workflows.
- Agricultural Cooperatives:Aggregated purchasing power in Brazil's Mato Grosso soybean belt negotiates volume pricing for bacterial fermentation products.
- Garden Centers:Retail channels move consumer-packaged bacterial and fungal formulations for residential pest management.
- Research Institutions:University extension services and government agricultural departments conduct field efficacy trials.
Cooperatives dominate volume procurement. Individual farmers are expanding most quickly as digital platforms reduce distribution friction.
Delivery Mode:
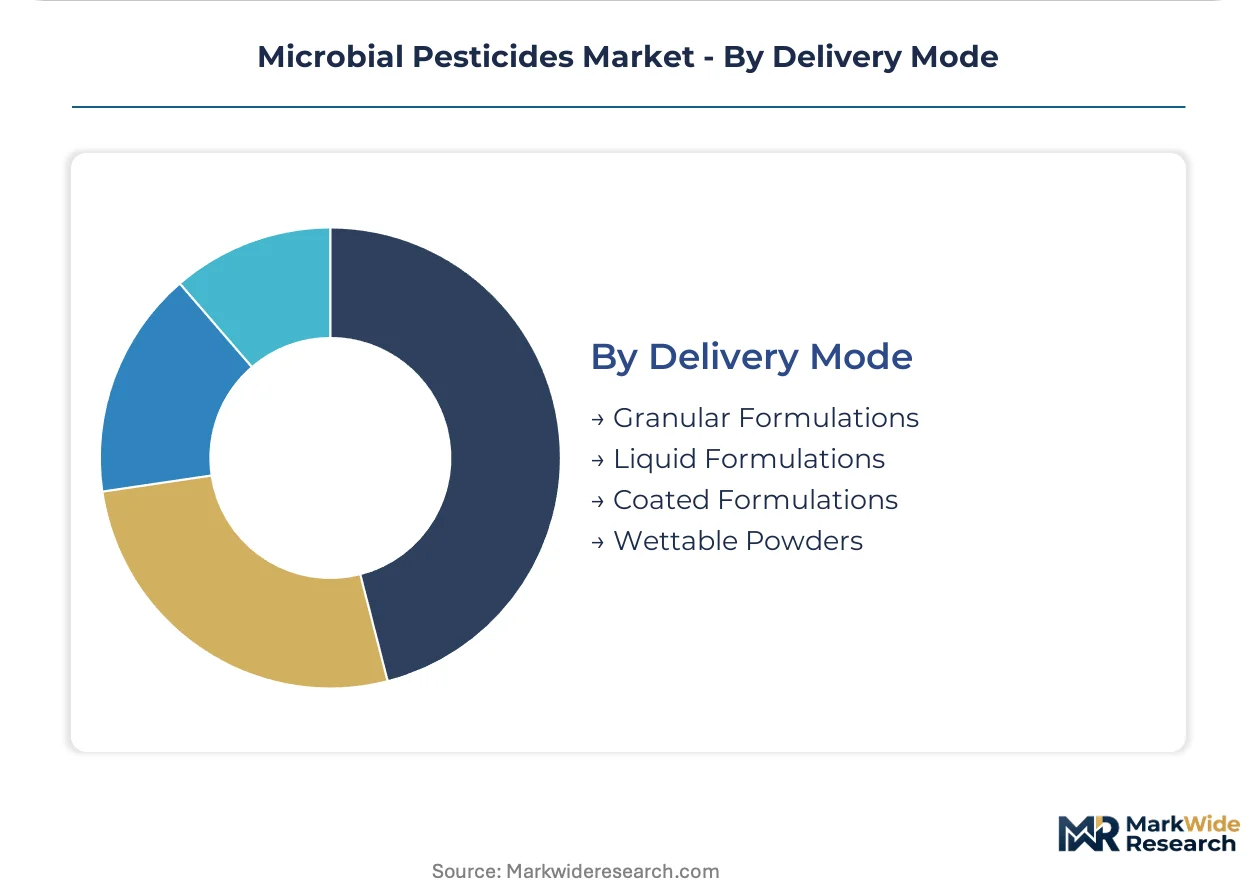
Formulation technology determines compatibility with precision application infrastructure and irrigation integration.
- Liquid Formulations:Suspension concentrates and oil-based carriers enable drip irrigation injection and drone-based spraying. California Central Valley nut and vine operations drive adoption for compatibility with existing chemigation infrastructure.
- Granular Formulations:Clay-based carriers protect desiccation-sensitive organisms for soil incorporation. Turf management and forestry applications favor broadcast spreading equipment compatibility.
- Coated Formulations:Seed treatment integration bypasses foliar spraying constraints for fungal and bacterial biocontrol agents.
- Wettable Powders:Conventional dry formulations face margin compression from advanced encapsulation technologies.
Liquid formulations lead volume growth. Coated formulations are gaining share fastest through seed treatment partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA biopesticide registration streamlining under FIFRA Section 3(c)(5) accelerates product entry in the United States. Brazil's soybean belt drives volume demand as pyrethroid resistance intensifies. European horticulture clusters adopt biological-first protocols under REACH discharge constraints.
United States
California Central Valley nut and vine operators anchor bacterial formulation demand through drip irrigation integration. EPA FIFRA Section 3(c)(5) reduced data requirements compress development timelines versus conventional chemistry. Fresno County specialty crop clusters expand biological pest control programs as registration pathways clarify.
Brazil
Mato Grosso soybean belt farmers calculate microbial inputs against yield protection value amid mounting synthetic pyrethroid resistance. ANVISA alignment with international biopesticide standards streamlines import approval for foreign fermentation products. Rondonópolis agricultural cooperatives negotiate volume pricing for bacillus-based active ingredients.
Germany
REACH tightening of aquatic discharge standards for synthetic actives expands microbial alternatives in watershed-sensitive regions. ECHA registration requirements for conventional chemistry elevate biological substitution incentives across member state programs. Lower Saxony controlled-environment agriculture suppliers concentrate procurement of desiccation-tolerant formulations.
India
Maharashtra and Karnataka horticulture belts generate demand for residue-free pest management compatible with export market standards. FSSAI and APEDA codify microbial pesticides as permitted inputs for certified organic operations. Nashik grape-growing clusters adopt direct-to-grower digital platforms with OMRI verification workflows.
Netherlands
EU Sustainable Use Directive mandatory reduction targets for synthetic pesticides expand biological mandates across Dutch agricultural programs. Wageningen University extension services validate field efficacy trials for live organism formulations. Westland greenhouse horticulture operations mandate biological-first pest management protocols in supplier qualification programs.
Microbial Pesticides Market Competitive Environment
Listed leaders compete with private specialists across fermentation scale and cold-chain logistics capabilities. The vendor base stratifies between multinational agrochemical conglomerates with captive biological platforms and dedicated microbial specialists with deep formulation expertise. Three archetypes dominate: diversified agrochemical majors leveraging global fermentation infrastructure, pure-play biological specialists concentrating on high-value horticultural segments, and controlled-environment agriculture distributors with captive cold-chain networks. Competitive moves center on seed treatment integration partnerships and precision application technology alliances.
Within the pure-play biological tier, Certis Biologicals and Koppert Biological Systems exemplify divergent specialization vectors. Certis anchors position through bacterial and fungal biofungicide concentration for fruit and vegetable markets. Koppert dominates live beneficial organism distribution with European horticulture cold-chain logistics. Bayer represents the diversified major archetype, supplying bacillus-based actives through global fermentation infrastructure at commercial scale.
| Leading Market Players |
|---|
| Valent BioSciences |
| Corteva Agriscience |
| Bayer |
| BASF |
| Certis Biologicals |
| Koppert Biological Systems |
| FMC Corporation |
| Syngenta |
| Marrone Bio Innovations |
| Others |
Value Chain & Pricing Dynamics
OMRI listing gates both supply qualification and price differentiation simultaneously, separating premium channel access from commodity distribution in North American specialty agriculture. Certification compliance costs filter supplier tiers while commanding 15-40% price premiums over non-listed alternatives.
Pricing Analysis
Certification level (OMRI-listed versus conventional) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium encapsulated formulations, standard wettable powders, and economy bulk concentrates dominates. Pricing pressure stems from fermentation scale-up costs as demand outpaces specialist bioreactor capacity. Agricultural cooperatives in Brazil exhibit highest price sensitivity, while California organic-certified operations absorb premiums for residue-free guarantees.
Supply Chain Analysis
Inventory lead times stretch 8-16 weeks for live organism products versus 2-4 weeks for desiccated bacterial formulations. Supply concentrates in the United States, Brazil, and the Netherlands, with fermentation infrastructure anchored in California's Central Valley and Rondonópolis agricultural clusters. Raw material dependencies include molasses feedstock, specialized bioreactor vessels, and cold-chain packaging. Single-source vulnerability around industrial microbiology talent elevates disruption risk. Distribution runs through controlled-environment agriculture suppliers for live organisms and commodity agricultural distributors for stable bacterial products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across formulation technologies and certification tiers creates niche opportunities as precision application demand splits buyer requirements. Direct-to-grower digital platforms accelerate this splintering by reducing minimum viable scale for specialized entrants.
For Market Incumbents: Shield market position through backward integration into fermentation infrastructure and captive cold-chain logistics. Bayer's global bioreactor network exemplifies this defensive moat against specialist challengers. Prioritize OMRI certification maintenance to preserve premium channel access as EPA registration streamlines competitive entry. For New Entrants and Emerging Players: Anchor in India's Maharashtra horticulture belt where residue-free export standards drive biological substitution faster than supply maturation. Seed treatment integration partnerships offer the most penetrable entry vector, bypassing established foliar spraying distribution. Target direct-to-grower digital platforms with OMRI verification workflows to reduce channel friction. For Investors and Strategic Acquirers: EPA FIFRA Section 3(c)(5) streamlining reshapes the acquisition landscape by compressing development timelines and elevating fermentation scale-up capabilities as scarce assets. Pure-play biological specialists with proven formulation science command premium multiples over commodity distributors. Watch ANVISA alignment progress with international biopesticide standards as the signal for Brazil market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Seed Treatment Integration Partnership | Bypasses foliar spraying constraints for fungal and bacterial biocontrol agents entering row-crop markets. |
| Controlled Cold-Chain Logistics Investment | Enables live beneficial organism distribution across European horticulture with viability guarantees. |
| OMRI Certification Fast-Track Program | Locks premium channel access for certified organic operations seeking listed biological inputs. |
| Precision Application Technology Alliance | Aligns liquid formulation development with California Central Valley drip irrigation infrastructure. |
| Fermentation Scale-Up Capacity Expansion | Addresses industrial microbiology talent scarcity constraining commercial bioreactor volumes. |
Study Parameters
Desk research of EPA registration databases, EU Sustainable Use Directive implementation reports, and ANVISA biopesticide approval precedents preceded structured interviews with fermentation plant managers, agricultural cooperative procurement leads, controlled-environment agriculture distributors, and technical R&D directors at biological formulation specialists. Secondary validation drew from USDA National Organic Program standards documentation, customs and trade flow data, and SEC filings of listed agrochemical conglomerates. Bottom-up volume modeling and top-down market sizing triangulated segment estimates.
Variance decomposition across bacterial, fungal, viral, and protozoan product types shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include formulation stability tier, application method compatibility, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from historical adoption curves adjusted for EPA registration pathway acceleration and pyrethroid resistance intensity in Brazil's soybean belt. Industry-specific inputs encompassed fermentation yield rates and cold-chain logistics cost structures.
Material uncertainties — regulatory timeline delays, fermentation contamination events, and live organism field efficacy variability — sit outside the modeled envelope. Forecasts reflect assumptions about EPA data requirement stability and EU REACH enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Europe Acaricides Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Canada Nematicides Market
Crop Protection
South America Acaricides Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Isoxaflutole Market
Crop Protection
South America Insecticide Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Global Termite Control Market