
 Agricultural Biofungicides Market | 2026-2036
Agricultural Biofungicides Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Biofungicides Market Insights
Buyer concentration among large-scale greenhouse operators is decoupling from traditional row-crop distributor networks, fragmenting procurement channels across controlled-environment agriculture. Bayer AG leverages its biologicals pipeline to anchor supply relationships with vertical farming consortia in Western Europe. BASF SE sustains R&D intensity through dedicated fermentation capacity for Bacillus-based formulations. Syngenta AG competes by extending its integrated pest management advisory services to mid-scale vegetable producers.
Agricultural biofungicides comprise living microorganisms or their derived metabolites formulated to suppress fungal and oomycete pathogens through antibiosis, mycoparasitism, or induced systemic resistance, typically requiring colony-forming unit counts above 10^8 per milliliter for field efficacy. These agents serve commercial agriculture by reducing synthetic fungicide residues in export-bound produce and managing resistance development in pathogen populations. Trichoderma dominates volume production due to established fermentation economics and broad-spectrum antagonism against soilborne diseases. Bacillus segments capture premium positioning in seed treatment applications where endospore stability enables extended shelf life. Yeast-based formulations represent the fastest-growing product type, driven by novel strain discoveries and compatibility with integrated biological programs.
EPA biopesticide registration pathways and EU REACH biocidal product frameworks shape formulation standards and market access timelines for entrants. BIS certification requirements in India and ANVISA biological input regulations in Brazil further segment compliance burdens by geography. Stakeholders must monitor evolving residue tolerance negotiations between export markets and domestic regulators to align portfolio investments with shifting compliance thresholds.
Market Dynamics
Substitution mandates under the EU Green Deal are compressing synthetic fungicide shelf space while Brazil's tropical disease pressure pulls biological formulations into mainstream soybean protection, fragmenting procurement channels between controlled-environment specialists and row-crop distributors.
Growth Catalysts
- EU Farm to Fork Strategy:Binding reduction targets for chemical pesticide use are mandating biological alternatives in vegetable and fruit production across member states.
- Brazilian soybean expansion:Tropical humidity and persistent Asian soybean rust pressure are concentrating grower demand for Bacillus-based seed treatments in Mato Grosso and Paraná.
- Controlled-environment agriculture:Vertical farming consortia in the Netherlands and Belgium are specifying residue-free protocols that exclude synthetic fungicides from procurement lists.
Market Restraints
- Fermentation input volatility:Molasses and corn steep liquor prices fluctuate with biofuel demand, compressing margins for Trichoderma bulk producers.
- Cold chain concentration:Viability of yeast-based formulations depends on refrigerated logistics networks concentrated in Western Europe and coastal Brazil.
- EPA registration timelines:Biopesticide pathway reviews average 18-24 months, creating competitive lag against accelerated synthetic fungicide re-approvals.
Strategic Opportunities
- Indian export vegetable corridors:BIS certification alignment with EU residue standards opens biological positioning in Karnataka and Maharashtra tomato processing clusters.
- Drone application compatibility:Low-volume spray protocols for UAV deployment are converging with micro-encapsulation advances in Bacillus formulations.
- Carbon credit stacking:EU Carbon Border Adjustment Mechanism compliance is creating premium pricing bandwidth for verified low-input biological programs.
Industry Challenges
- Fermentation scale-up talent:Industrial microbiology expertise for 10,000-liter+ bioreactor operation remains concentrated in Basel and Research Triangle Park corridors.
- Multi-jurisdiction dossier compilation:ANVISA, EPA, and EFSA data requirements diverge on colony-forming unit validation methods, extending compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Biofungicides Market |
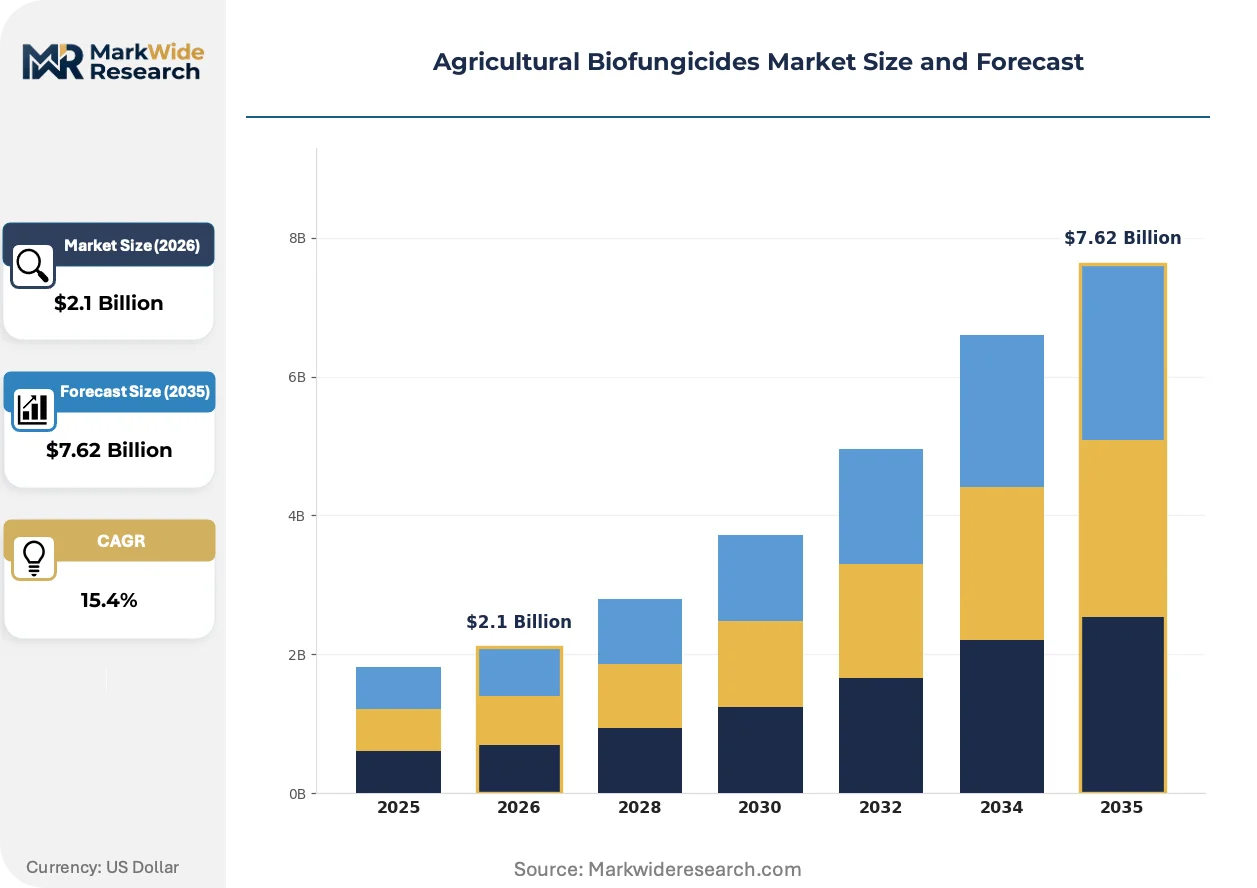
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trichoderma, Bacillus, Yeast, Actinomycetes Application Method: Soil Application, Foliar Spray, Seed Treatment, Soil Drench Crops: Cereals, Fruits, Vegetables, Oilseeds Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Bayer AG, BASF SE, Syngenta AG, Corteva Agriscience, FMC Corporation, Marrone Bio Innovations, Valent BioSciences, UPL Limited, Koppert Biological Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Biofungicides Market Trends and Innovations
Formulation science and delivery mechanism advances are compressing the efficacy gap between biological and synthetic fungicides while regulatory pressure accelerates substitution timelines in export-oriented production zones.
RNA interference technology is integrating into biofungicide development pipelines as a precision targeting mechanism against oomycete pathogens. Large-scale greenhouse operators in Almería and the Netherlands are piloting spray programs combining siRNA triggers with Trichoderma colonization. This convergence is integrating molecular specificity with established biological manufacturing infrastructure, reducing development risk for platform extensions.
EU REACH biocidal product framework revisions are tightening metabolite characterization requirements for microbial formulations. Manufacturers must now submit full genomic sequencing data and secondary metabolite profiling for strain authorization. Seed treatment specialists face the steepest compliance burden, as endospore stability claims require extended field trial documentation under the updated guidance.
Direct contracting between biological input manufacturers and controlled-environment agriculture consortia is displacing traditional distributor intermediaries. Bayer and BASF have established dedicated technical service teams for vertical farming operators in Belgium and the UK, bypassing agronomy retail channels. This channel compression is most visible in specialty tomato and leafy green production, where residue specifications are negotiated directly with supermarket procurement divisions.
Agricultural Biofungicides Market Segmentation
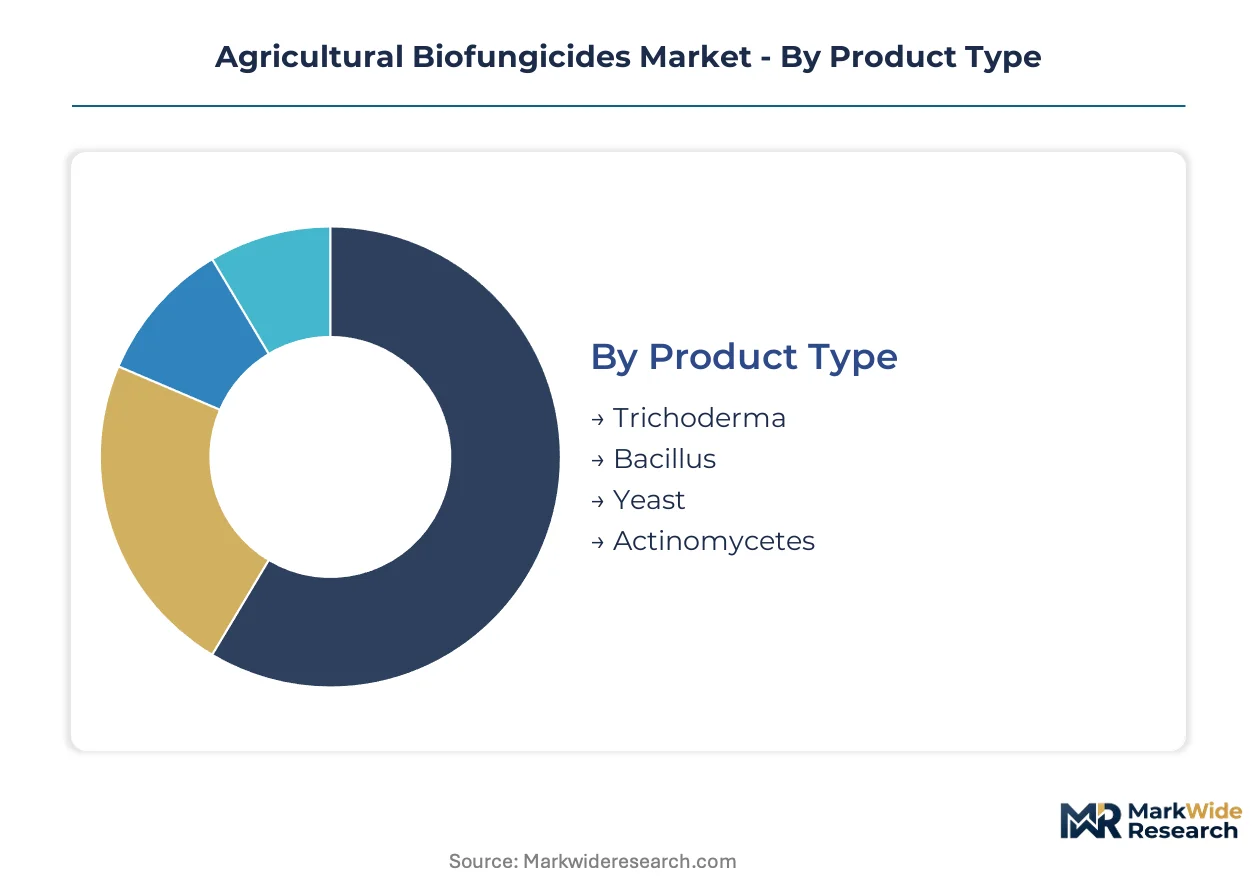
Segmentation in agricultural biofungicides reveals how capital deployment, technical specifications, and channel economics fragment procurement patterns across microbial platforms and delivery systems. Distinct investment thresholds separate fermentation-based bulk production from specialized formulation technologies, reshaping competitive entry points.
Product Type:
Fermentation infrastructure requirements create steep capital barriers, with bioreactor scale-up costs varying dramatically across microbial genera and metabolite complexity.
- Trichoderma:Filamentous fungal strains requiring submerged fermentation at 10,000-liter scale produce chitinase and glucanase enzymes for soilborne pathogen suppression. Demand concentrates in Brazil's Mato Grosso soybean belt where Asian rust pressure drives bulk procurement of granular formulations.
- Bacillus:Endospore-forming bacteria enable extended shelf stability through micro-encapsulation, commanding premium positioning in seed treatment applications. Netherlands greenhouse consortia specify Bacillus-based protocols for residue-free tomato exports to German retail chains.
- Yeast:Novel strain discoveries in Metschnikowia and Aureobasidium genera drive compatibility with integrated biological programs requiring refrigerated logistics.
- Actinomycetes:Streptomyces-derived secondary metabolites face extended EFSA authorization timelines under REACH metabolite characterization rules.
Trichoderma absorbs the bulk of installed capacity; Yeast is expanding most quickly.
Application Method:
Equipment compatibility and labor intensity separate high-volume mechanized deployment from precision manual applications in controlled environments.
- Soil Application:Granular and liquid in-furrow delivery systems dominate row-crop deployment, requiring tractor-mounted applicators calibrated to 10^8 CFU per gram specification thresholds.
- Foliar Spray:UAV-compatible low-volume protocols converge with micro-encapsulation advances, enabling drone deployment in Karnataka tomato processing corridors where labor costs accelerate mechanization.
- Seed Treatment:Film-coating technology integrates biologicals with synthetic chemistries, commanding formulation premiums in Paraná soybean seed multiplication zones.
- Soil Drench:High-volume aqueous delivery suits greenhouse substrate disinfection protocols in Almería pepper production clusters.
Soil Application captures the largest equipment investment base; Foliar Spray is climbing the fastest on precision agriculture adoption.
Crops:
Export orientation and residue tolerance thresholds create divergent pricing bandwidth across commodity and specialty production systems.
- Cereals:Wheat and rice applications focus on Fusarium and Rhizoctonia suppression in high-volume markets with thin margin structures.
- Fruits:Grape and citrus producers in Spain and Italy face EU Maximum Residue Level compression, mandating biological substitution for post-harvest rot control.
- Vegetables:Leafy green and tomato greenhouse operations in Belgium and the Netherlands specify zero-residue procurement protocols, creating premium pricing tiers for certified biological programs.
- Oilseeds:Brazilian soybean expansion pulls Bacillus seed treatments into mainstream protection packages against Asian rust and SDS complex.
Vegetables command the steepest compliance premiums; Oilseeds are gaining share fastest on tropical acreage expansion.
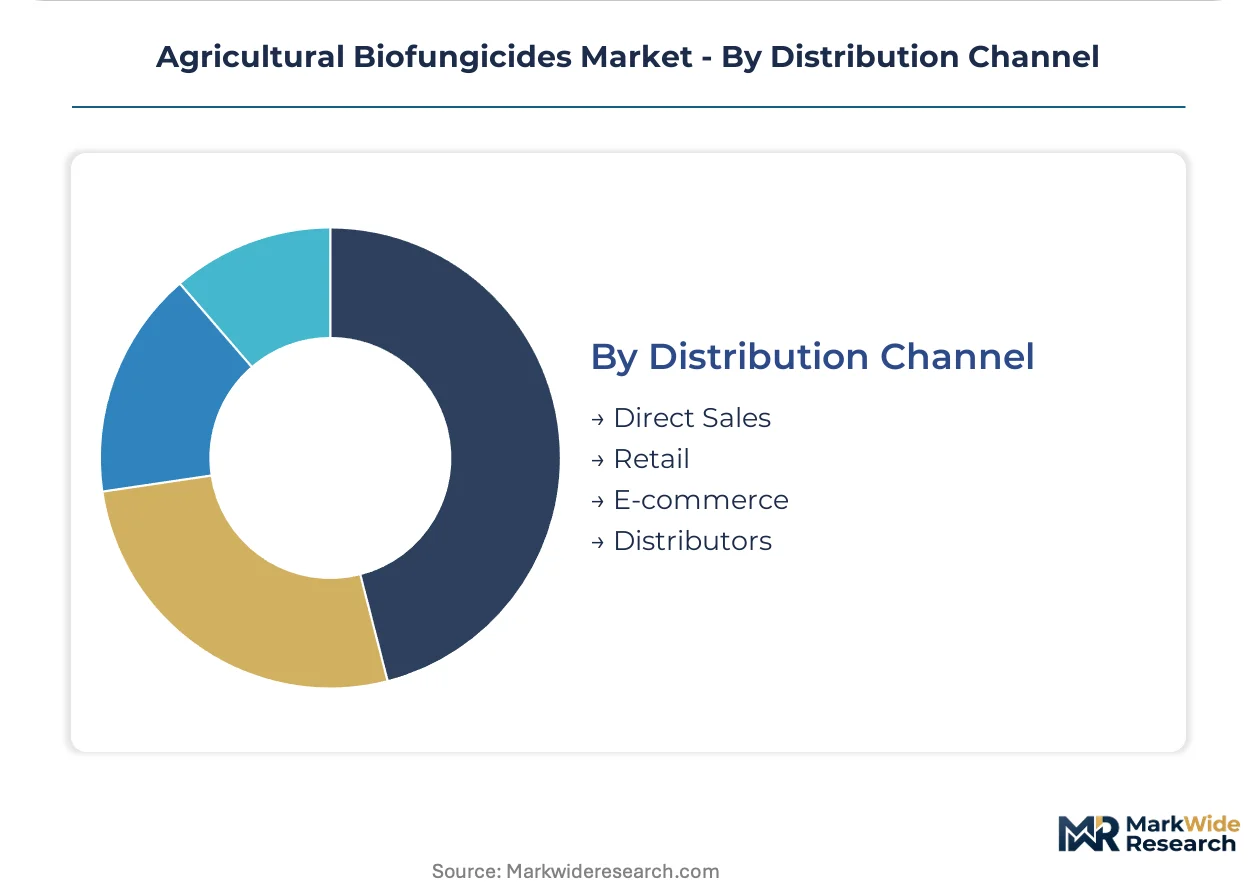
Distribution Channel:
Channel concentration reflects technical service requirements and buyer scale fragmentation across row-crop and controlled-environment segments.
- Direct Sales:Manufacturer technical teams contract directly with vertical farming consortia in Western Europe, bypassing traditional agronomy retail and capturing margin compression from eliminated intermediaries.
- Retail:Brick-and-mortar agronomy stores serve mid-scale vegetable producers in Maharashtra with localized application guidance and credit terms.
- E-commerce:Digital platforms aggregate smallholder demand in India, though cold-chain viability constraints limit yeast-based formulation availability.
- Distributors:Traditional networks retain dominance in Brazilian soybean regions where volume logistics and seasonal financing requirements favor established agricultural supply cooperatives.
Distributors retain the deepest geographic penetration; Direct Sales is expanding most quickly on greenhouse operator consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's tropical soybean belt and Western Europe's controlled-environment vegetable clusters, with regulatory substitution mandates in the EU and disease pressure in South America pulling biological formulations into mainstream crop protection.
Brazil
Tropical humidity and Asian soybean rust pressure drive Bacillus-based seed treatment demand across Mato Grosso and Paraná. ANVISA biological input regulations govern strain authorization and field trial documentation. Campo Grande anchors the Mato Grosso cluster where agricultural supply cooperatives distribute bulk granular formulations to expanding soybean acreage.
Germany
EU Green Deal pesticide reduction targets mandate biological alternatives in specialty crop production. EFSA authorization requirements under REACH biocidal product frameworks tighten metabolite characterization standards. The Rhine-Main corridor around Frankfurt concentrates formulation R&D facilities serving greenhouse consortia across the Netherlands and Belgium border regions.
United States
EPA biopesticide registration pathways shape market access timelines for microbial formulations entering vegetable and fruit production. The agency's 18-24 month review averages create competitive lag against synthetic alternatives. Research Triangle Park in North Carolina anchors industrial microbiology expertise for large-scale bioreactor operations serving domestic seed treatment markets.
India
BIS certification requirements for biological inputs align with EU residue standards for export-bound tomato and vegetable processing. Karnataka and Maharashtra processing clusters specify certified biological programs for European supermarket procurement divisions. Pune-based technical service teams support mid-scale producers transitioning from synthetic fungicide dependence.
Netherlands
Vertical farming consortia in the Randstad specify zero-residue protocols that exclude synthetic fungicides from procurement lists. EU Farm to Fork Strategy binding targets accelerate substitution in greenhouse tomato and leafy green production. The Westland municipality anchors the densest concentration of controlled-environment agriculture operations in Europe.
Agricultural Biofungicides Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized fermentation platforms and regional formulation partnerships. The market structures around three maturity tiers: global agrochemical conglomerates with biological pipelines, dedicated microbial specialists with captive fermentation capacity, and regional formulators serving localized compliance requirements. Dominant competitive moves include direct technical service contracting with large-scale greenhouse operators and strategic fermentation capacity expansion in tropical disease-pressure zones.
Among global agrochemical conglomerates, Bayer AG, BASF SE, and Syngenta AG exemplify distinct strategic positioning archetypes. Bayer anchors supply relationships through dedicated biologicals pipeline integration. BASF represents sustained R&D intensity via captive fermentation infrastructure. Syngenta occupies the integrated pest management advisory services tier, extending technical support to mid-scale producers. These three entities collectively illustrate how multinational scale converges with biological specialization to address fragmented procurement channels across controlled-environment and row-crop segments.
| Leading Market Players |
|---|
| Bayer AG |
| BASF SE |
| Syngenta AG |
| Corteva Agriscience |
| FMC Corporation |
| Marrone Bio Innovations |
| Valent BioSciences |
| UPL Limited |
| Koppert Biological Systems |
| Others |
Pricing and Supply Chain Analysis
Vertical farming consortia in Belgium and the Netherlands anchor pricing power through zero-residue procurement mandates that exclude synthetic alternatives, compressing margins for suppliers unable to meet certification thresholds. This buyer concentration forces tiered pricing stratification across premium biological formulations, standard microbial bulk products, and economy-grade regional generics.
Pricing Analysis
Volume production of Trichoderma granular formulations in Brazil's Mato Grosso soybean belt runs on thin commodity margins, while Bacillus-based seed treatments and yeast-derived specialty products capture premium positioning through endospore stability and refrigerated logistics requirements. Price differentiation stems from EU REACH biocidal certification tiers and cold-chain delivery costs to controlled-environment operators. Cost compression in bulk fermentation is intensifying because molasses and corn steep liquor prices fluctuate with biofuel demand. Mid-scale vegetable producers in Maharashtra retail channels exhibit highest price sensitivity; Dutch greenhouse consortia show lowest sensitivity due to residue-free protocol mandates.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian molasses suppliers and Western European refrigerated logistics networks that yeast-based formulations depend on for viability. Manufacturing concentrates in Germany's Rhine-Main corridor, Brazil's Campo Grande cluster, and India's Pune technical service hubs. Raw material dependencies encompass agricultural fermentation feedstocks, specialized bioreactor equipment, and genomic sequencing services for regulatory dossiers. Tariff exposure on Brazilian soybean exports to EU markets threatens formulation demand. Distribution runs through agricultural supply cooperatives in row-crop regions and direct manufacturer contracting with greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural biofungicides sector sits in a technology-transition phase where RNA interference platforms are displacing legacy microbial antagonism in precision oomycete control. This substitution dynamic reshapes R&D allocation and partnership strategies across the competitive landscape.
For Market Incumbents: Extend technical service teams into drone-compatible formulation development to defend against UAV-application specialists capturing precision agriculture share. Anchor backward integration into captive molasses supply contracts in Brazil to buffer fermentation input volatility. Prioritize REACH metabolite characterization investments ahead of EFSA authorization timeline compressions.
For New Entrants and Emerging Players: Launch via e-commerce platforms aggregating smallholder demand in Karnataka tomato processing corridors where BIS certification alignment opens EU export pathways. Target yeast-based formulations for fastest penetration given refrigerated logistics infrastructure expansion in coastal Brazil. Pursue white-space in Indian export vegetable biological programs where mid-scale producers transition from synthetic dependence.
For Investors and Strategic Acquirers: The window for entry favors dedicated microbial specialists with captive 10,000-liter bioreactor capacity and established ANVISA dossier experience. Long-term viability hinges on fermentation scale-up talent concentration in Basel and Research Triangle Park corridors. Watch EPA biopesticide registration pathway acceleration as the inflection signal for competitive lag elimination against synthetic alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Captive 10,000-liter fermentation infrastructure in Mato Grosso secures Brazilian soybean supply relationships. |
| REACH Metabolite Characterization Investment | Full genomic sequencing submission accelerates EFSA authorization for seed treatment specialists. |
| Direct Technical Service Contracting | Bypassing agronomy retail channels captures margin compression from eliminated intermediaries in Dutch greenhouse clusters. |
| Drone Application Compatibility Development | Micro-encapsulation advances for UAV deployment align with Karnataka mechanization trends. |
| Cold Chain Logistics Partnership | Refrigerated network access enables yeast-based formulation viability beyond Western Europe. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fermentation plant managers, biological input procurement leads at greenhouse consortia, ANVISA regulatory affairs specialists, and agricultural supply cooperative distribution heads provided operational validation. Secondary sources encompassed EPA biopesticide registration databases, EU EFSA authorization filings, Brazilian customs export records, and BIS certification registries. Bottom-up strain-level production estimates and top-down crop protection expenditure aggregates were reconciled through triangulation.
Data-stream reconciliation across shipment volumes, installed bioreactor capacity, and crop acreage expansion patterns informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed microbial genera, application method, crop category, and distribution channel structure. CAGRs were derived from slope analysis of biological substitution rates against synthetic fungicide re-approval timelines. Industry-specific forecast inputs incorporated EU Farm to Fork Strategy binding target implementation schedules and Brazilian soybean acreage expansion trajectories.
Regulatory authorization delays, fermentation feedstock price volatility, and cold-chain infrastructure expansion shortfalls are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding EPA review timeline stability and ANVISA biological input framework continuity. Deviation in EU REACH metabolite characterization requirement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Agricultural Adjuvants Market