
 Europe Acaricides Market | 2026-2036
Europe Acaricides Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Acaricides Market Foresight
Buyer concentration among large-scale greenhouse operators in the Netherlands and Belgium is recalibrating procurement volumes across the supply base. FMC Corporation leverages its pyrethroid portfolio to sustain shelf presence in Mediterranean horticulture channels. BASF SE anchors its position through formulation expertise in emulsifiable concentrates. Bayer AG competes via biological acaricide development aligned with EU residue limits.
Acaricides are crop protection agents specifically formulated to kill or suppress mites and ticks, typically containing active ingredients such as abamectin, bifenazate, or spiromesifen at concentrations between 1.5% and 20% w/w, and are manufactured through multi-step synthesis or fermentation processes followed by formulation into sprayable or soil-applied products. Their primary commercial purpose is to prevent yield loss in high-value fruit, vegetable, and ornamental crops where mite infestations reduce photosynthetic efficiency and marketable quality. Pyrethroids remain the largest product category by volume, though biological acaricides represent the fastest-expanding margin pool as growers face pressure from the EU's Farm to Fork strategy. Liquid formulations dominate application in greenhouse settings, while wettable powders retain share in broad-acre agriculture where tank-mix flexibility governs purchasing decisions.
EMA and EFSA jointly shape residue limit thresholds that determine which chemistries retain market access across EU member states. REACH registration requirements and the EU Green Deal's pesticide reduction targets are forcing reformulation investments and accelerating biological product registrations. The F-Gas Regulation indirectly influences acaricide adjuvant sourcing by restricting fluorinated greenhouse gases used in certain manufacturing steps. Stakeholders must monitor the EU's upcoming revision of maximum residue levels for legacy organochlorines and position biological portfolios ahead of anticipated restrictions.
Market Dynamics
The EU Green Deal's pesticide reduction mandates are forcing acaricide manufacturers to restructure portfolios toward biological alternatives, compressing registration timelines for synthetic chemistries while accelerating microbial product development pipelines.
Growth Catalysts
- Integrated Pest Management Mandates:The EU Farm to Fork strategy compels specialty crop growers in Spain and Italy to adopt acaricides compatible with biocontrol protocols, expanding procurement of fermentation-derived products.
- Beauveria bassiana Formulations:Advances in fungal entomopathogen stabilization are extending field persistence of biological acaricides, narrowing efficacy gaps with pyrethroids in greenhouse tomato and pepper operations.
- Netherlands Greenhouse Cluster:Concentrated buyer power among Dutch glasshouse operators is consolidating procurement volumes, creating scale incentives for formulation innovation in liquid concentrate delivery systems.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers dominate abamectin and spiromesifen technical-grade supply, exposing European formulators to input cost volatility and shipping disruptions.
- REACH Registration Burden:ECHA data requirements for existing synthetic acaricides are consuming 18-24 month compliance cycles, delaying reformulation launches and freezing legacy product renewals.
- Biological Substitution Threat:Predatory mites and parasitic nematodes are gaining traction in Mediterranean stone fruit orchards, displacing chemical acaricide applications in IPM-intensive zones.
Strategic Opportunities
- Poland Orchard Expansion:Underpenetrated apple and cherry acreage in Polish voivodeships offers first-mover positioning for biological acaricide portfolios ahead of anticipated EU residue tightening.
- Drone Application Integration:Convergence of unmanned aerial systems with ultra-low-volume spraying technology is creating new service channels for broad-acre viticulture in Portuguese Douro Valley estates.
- F-Gas Regulatory Tailwind:Restrictions on fluorinated greenhouse gases used in certain manufacturing adjuvants are favoring suppliers with reformulated, compliant emulsifiable concentrate platforms.
Industry Challenges
- Microbial Formulation Expertise Gap:European manufacturers face acute shortages of fermentation scientists capable of scaling Beauveria and Metarhizium production to commercial viability.
- Tank-Mix Compatibility Certification:Grower demand for simultaneous acaricide-fungicide applications requires extensive EFSA residue interaction studies, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Acaricides Market |
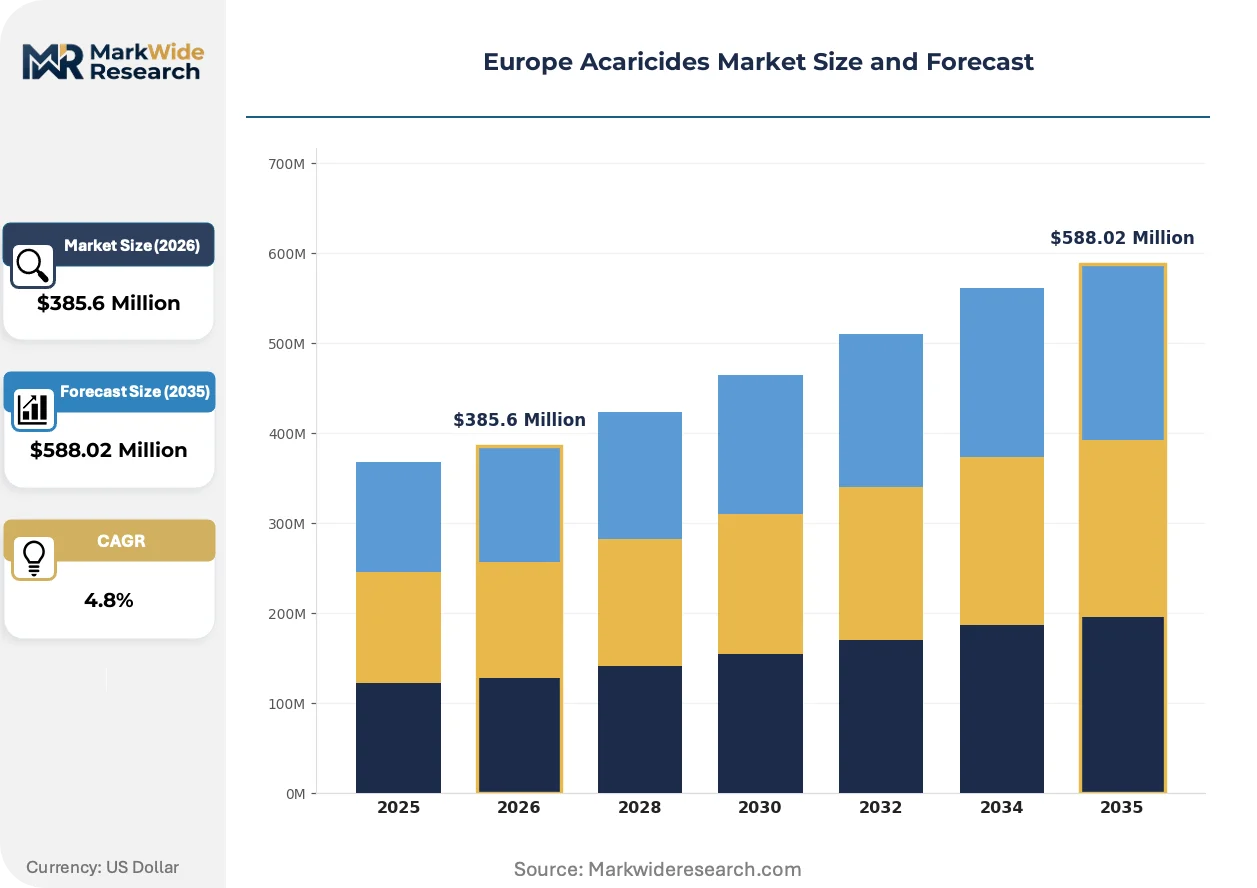
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organochlorines, Pyrethroids, Neonicotinoids, Biological Acaricides Application: Agriculture, Horticulture, Forestry, Greenhouse Formulation: Liquid, Granular, Emulsifiable Concentrate, Wettable Powder Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | FMC Corporation, UPL Limited, BASF SE, Sumitomo Chemical Co., Ltd., Nufarm Limited, Bayer AG, Nissan Chemical Corporation, Gowan Company, Syngenta, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Acaricides Market Shifts & Advancements
Biological acaricide development is outpacing synthetic chemistry pipelines as regulatory pressure compresses innovation cycles, while digital agriculture tools are reshaping how mite pressure gets monitored and treated across European growing regions.
RNA interference technology targeting specific mite gene sequences is modularizing precision pest control approaches. Research consortia in Germany and France are advancing dsRNA formulations that disrupt arachnid molting processes. Greenhouse operators in Belgium are piloting these platforms in ornamentals production, where zero-residue requirements are most stringent.
REACH registration requirements for microplastic-free formulations are forcing adjuvant redesigns across the supply base. ECHA scrutiny of polymer-based drift retardants is accelerating adoption of vegetable-oil-derived alternatives. Spanish citrus cooperatives are demanding compliant concentrates ahead of anticipated 2026 enforcement milestones.
Consolidated procurement by Belgian and Dutch buying cooperatives is compressing supplier margins while demanding extended payment terms. Traditional distribution through national agrochemical wholesalers is yielding to direct manufacturer relationships with large-scale greenhouse operators. This channel compression is most visible in Almería's intensive vegetable production zone, where three buying groups now control majority acaricide volumes.
Europe Acaricides Market Segmentation
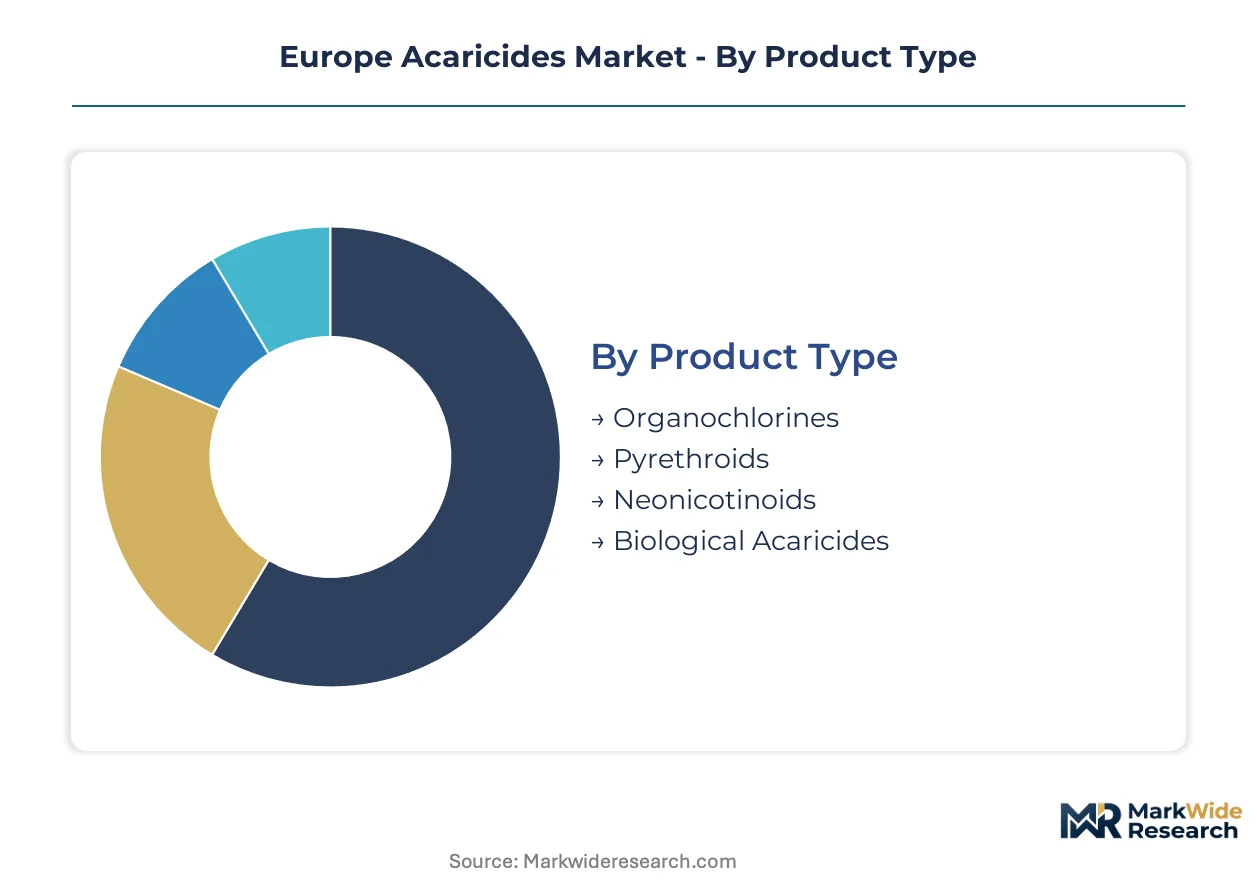
Acaricide procurement patterns across Europe diverge sharply by crop system, regulatory exposure, and operational scale. Formulation chemistry and channel access determine which suppliers capture value in Mediterranean horticulture versus northern greenhouse clusters.
Product Type:
Supply concentration among Chinese technical-grade manufacturers shapes competitive dynamics across all chemistry classes, with European formulators scrambling to secure backward integration into fermentation capacity for biological alternatives.
- Organochlorines:Legacy chlorinated hydrocarbon formulations face accelerating ECHA review under REACH substance evaluation. Spanish citrus growers in Valencia and Murcia retain limited procurement for specific mite strains, though residue detection risks are displacing volumes toward compliant alternatives.
- Pyrethroids:Synthetic esters derived from chrysanthemum acid analogues dominate current shelf presence in Italian tomato and pepper protected cultivation. FMC Corporation and BASF SE anchor supply through emulsifiable concentrate and microencapsulated delivery systems, though resistance management protocols are compressing application windows.
- Neonicotinoids:Systemic nitroguanidine and chloronicotinyl compounds retain niche use in broad-acre viticulture where vine mealybug vectors threaten. Regulatory pressure from EFSA pollinator risk assessments is restricting approved uses to post-bloom applications in French Bordeaux and Portuguese Alentejo estates.
- Biological Acaricides:Fermentation-derived Beauveria bassiana and Metarhizium anisopliae suspensions are climbing the fastest as Dutch and Belgian greenhouse operators mandate zero-residue protocols ahead of EU Green Deal milestones.
Today's leader: Pyrethroids. Tomorrow's challenger: Biological Acaricides.
Application:
End-use economics dictate formulation selection, with high-value protected crops justifying premium biological inputs while broad-acre systems prioritize tank-mix flexibility and unit cost control.
- Agriculture:Field-grown cereals and oilseeds in Polish and Romanian farming systems rely on wettable powder and granular acaricides for spider mite suppression during drought stress periods. Commodity pricing limits procurement to generic pyrethroid and organophosphate alternatives.
- Horticulture:Open-field vegetable production in Italy's Po Valley and Spain's Extremadura combines acaricide rotation with predator mite releases under IPM certification schemes. Stone fruit orchards in Aragón drive seasonal demand spikes timed to bud break and harvest intervals.
- Forestry:Conifer plantations in Scandinavian Baltic states and Scottish Highlands deploy specialized formulations against pine spider mite and spruce budworm vectors. Public procurement through national forest services favors bulk concentrate supply with extended payment terms.
- Greenhouse:Dutch glasshouse clusters in Westland and Belgian vegetable cooperatives near Mechelen represent the steepest expansion trajectory for biological acaricide penetration, with integrated climate control enabling precise humidity management for fungal entomopathogen efficacy.
Greenhouse applications command premium pricing. Agricultural volumes anchor supplier scale.
Formulation:
Manufacturing complexity and adjuvant chemistry determine which European formulators can meet ECHA microplastic-free deadlines without reformulation delays.
- Liquid:Ready-to-use suspensions and solutions dominate Belgian and Dutch greenhouse procurement, with automated dosing systems requiring consistent viscosity and compatibility with hydroponic nutrient lines.
- Granular:Clay-based and polymer-coated slow-release formulations serve soil-applied mite control in Portuguese vineyard inter-rows and Spanish almond orchards, reducing drift exposure and operator handling risk.
- Emulsifiable Concentrate:Oil-in-water systems remain standard for Mediterranean horticulture, though F-Gas Regulation restrictions on fluorinated solvent adjuvants are forcing vegetable-oil-derived reformulations.
- Wettable Powder:Dry flowable formulations retain share in Eastern European broad-acre agriculture where tank-mix flexibility with fungicides and foliar fertilizers governs purchasing decisions among Polish farmer cooperatives.
Liquid formulations lead greenhouse penetration. Wettable powders defend broad-acre positioning.
Distribution Channel:
Channel economics reflect buyer scale consolidation, with large-scale operators extracting direct manufacturer terms while smaller growers remain tethered to distributor credit and technical service bundling.
- Direct Sales:Manufacturer relationships with Dutch buying cooperatives and Almería-based vegetable export consortia are displacing traditional wholesale intermediaries, compressing margin pools but securing volume commitments.
- Retail:Agricultural supply stores and garden centers serve hobbyist and smallholder segments in France and Germany, with acaricide SKUs bundled into seasonal pest control kits for ornamental and home vegetable production.
- Online:E-procurement platforms are gaining traction among mid-scale Italian horticulture operations seeking price transparency on biological acaricide alternatives, though regulatory compliance documentation requirements limit pure digital transaction completion.
- Distributors:National agrochemical wholesalers retain relevance in fragmented Eastern European markets where technical advisory services and localized storage infrastructure justify markup capture.
Direct sales capture greenhouse consolidation. Distributors defend fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain and the Netherlands diverge in acaricide procurement intensity despite both ranking among Europe's top agricultural producers. Spanish growers favor broad-spectrum chemistries for open-field Mediterranean crops, while Dutch operators mandate residue-free biological inputs for glasshouse export certification. EFSA residue protocols and EU Green Deal milestones are recalibrating investment patterns across both systems.
Spain
Valencia and Murcia citrus cooperatives drive seasonal acaricide demand tied to red spider mite pressure in humid coastal microclimates. REACH substance evaluation is accelerating organochlorine phase-out timelines, forcing procurement shifts toward pyrethroid alternatives. Almería's intensive vegetable export zone concentrates buyer power among three purchasing consortia that negotiate direct manufacturer terms.
Netherlands
Westland glasshouse clusters command premium biological acaricide pricing for zero-residue tomato and pepper protocols destined for German retail chains. The F-Gas Regulation restricts fluorinated adjuvants in manufacturing, favoring suppliers with vegetable-oil-derived emulsifiable concentrate platforms. Wageningen University research partnerships anchor microbial formulation development pipelines.
Italy
Po Valley horticulture and Sicilian citrus operations combine acaricide rotation with predator mite releases under integrated pest management certification schemes. EMA residue limit revisions for legacy chemistries are compressing approved application windows. Apulia's table grape sector is piloting Beauveria bassiana formulations ahead of anticipated EU restrictions on synthetic alternatives.
Poland
Masovian and Greater Poland voivodeships present underpenetrated apple and cherry acreage for biological acaricide first-movers. National subsidies for orchard modernization are expanding protected cultivation infrastructure. Lublin's emerging berry cooperatives are negotiating volume commitments with formulation suppliers ahead of EU Farm to Fork compliance deadlines.
Belgium
Flemish vegetable cooperatives near Mechelen consolidate procurement volumes through centralized buying groups demanding extended payment terms. ECHA microplastic-free formulation requirements are forcing adjuvant redesigns for wettable powder suppliers. Limburg's strawberry propagation facilities represent high-value targets for liquid concentrate biological products.
Europe Acaricides Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and biological development vectors. The supplier base organizes into three tiers: multinational agrochemical majors with pyrethroid portfolios, mid-scale European formulators with REACH compliance expertise, and microbial technology startups scaling fermentation capacity. Consolidation pressures are intensifying as Dutch buying cooperatives extract direct manufacturer terms, while regulatory complexity favors players with dedicated ECHA registration teams. Strategic moves center on backward integration into Chinese technical-grade supply and accelerated biological product pipeline investment.
Among the multinational tier, FMC Corporation and BASF SE occupy positions anchored by emulsifiable concentrate expertise and Mediterranean distribution infrastructure. Bayer AG exemplifies the biological pivot archetype, repositioning development resources toward microbial alternatives aligned with EU residue limits. These three entities represent contrasting strategic postures: pyrethroid defense, formulation platform leverage, and biological transition investment.
| Leading Market Players |
|---|
| FMC Corporation |
| UPL Limited |
| BASF SE |
| Sumitomo Chemical Co., Ltd. |
| Nufarm Limited |
| Bayer AG |
| Nissan Chemical Corporation |
| Gowan Company |
| Syngenta |
| Others |
Supply & Pricing Matrix
Abamectin technical-grade price volatility from Chinese manufacturers cascades through European formulation tiers, compressing margins for mid-scale formulators while concentrating pricing power with vertically integrated majors serving Dutch greenhouse cooperatives.
Pricing Analysis
Capacity additions in Chinese fermentation facilities are reshaping price floors for biological acaricide intermediates, forcing European formulators into three-tier pricing structure across premium, standard, and economy levels. Certification under EU Green Deal compliance tiers separates premium biological formulations from standard pyrethroid alternatives. Pricing pressure stems from REACH registration cost absorption squeezing mid-tier suppliers. Smallholder cooperatives in Eastern Europe exhibit highest price sensitivity, while Dutch glasshouse operators prioritize residue-free certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers dominating abamectin and spiromesifen technical-grade supply. European formulators draw from fermentation inputs sourced in China, India, and domestic bioreactor capacity. Raw material dependencies center on chrysanthemum acid analogues, nitroguanidine intermediates, and fungal entomopathogen culture media. Tariff exposure on fluorinated solvent adjuvants under F-Gas Regulation restrictions threatens emulsifiable concentrate supply. Distribution runs through direct manufacturer relationships with consolidated Dutch buying groups and national agrochemical wholesalers serving fragmented Mediterranean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Acaricides Market operates as a regulatory compounder where EU Farm to Fork pesticide reduction mandates accelerate biological substitution timelines and reshape procurement priorities across specialty crop systems.
For Market Incumbents: To counter biological substitution threats from predatory mites and parasitic nematodes in Mediterranean stone fruit zones, incumbents must accelerate backward integration into Beauveria bassiana fermentation capacity and secure REACH-compliant microplastic-free formulation platforms ahead of ECHA enforcement milestones.
For New Entrants and Emerging Players: RNA interference technology targeting mite gene sequences offers entry wedge into Belgian and German ornamental greenhouse segments where zero-residue requirements are most stringent. Underpenetrated Polish apple and cherry voivodeships present first-mover positioning for microbial formulation suppliers. Partner with Wageningen University research consortia to validate field persistence claims.
For Investors and Strategic Acquirers: Consolidation pressure builds where ECHA registration teams and fermentation scientists remain scarce relative to biological pipeline expansion needs. Five-to-ten year viability favors acquirers of mid-scale European formulators with captive technical-grade supply agreements. Monitor EU maximum residue level revision announcements for legacy organochlorines as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Beauveria bassiana production insulates margin compression from Chinese technical-grade volatility. |
| REACH-Compliant Microplastic-Free Reformulation | Vegetable-oil-derived adjuvant platforms satisfy ECHA deadlines and retain shelf presence. |
| Drone Application Service Partnerships | Ultra-low-volume spraying convergence opens Portuguese Douro Valley viticulture channels. |
| Direct Procurement Relationships with Dutch Cooperatives | Volume commitments from Westland glasshouse clusters secure formulation innovation funding. |
| RNA Interference Platform Development | dsRNA formulations targeting arachnid molting processes capture Belgian ornamental zero-residue demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation R&D directors, procurement leads at Dutch greenhouse cooperatives, ECHA registration specialists, and Spanish citrus cooperative agronomists with secondary validation against customs trade data, EFSA residue limit databases, SEC filings of listed agrochemical majors, and EU Farm to Fork implementation progress reports. Bottom-up volume modeling triangulated against top-down market sizing.
Comparable-period anchoring linked projection assumptions to historical procurement patterns across the analysis window, with segmentation dimensions spanning chemistry class, crop system, formulation type, and distribution channel. CAGRs derived from trend extrapolation of biological penetration rates and synthetic chemistry phase-out timelines. Industry-specific inputs included EMA residue revision calendars and F-Gas Regulation adjuvant restriction schedules.
The model holds under stable EU Green Deal implementation pace; deviation in REACH substance evaluation acceleration or Chinese export licensing disruptions would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Tebuconazole Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
North America Acaricides Market
Crop Protection
US Insecticide Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Global Algaecides Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Fumigation Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
South America Nematicides Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Canada Nematicides Market
Crop Protection
US Herbicide Market