

5G Automotive Grade Product Market Size, Share, and Industry Trends Forecast 2026-2036
5G Automotive Grade Product Market Insights
Edge-native network slicing is reconfiguring how automotive-grade 5G stacks are architected for deterministic latency. Qualcomm leverages its modem-RF system integration to dominate premium embedded module supply. Samsung Electronics anchors manufacturing scale across Korea and Vietnam for CPE device production. Robert Bosch specializes in V2X software-layer integration atop third-party silicon.
5G automotive grade products comprise hardened communication modules, onboard units, and antenna systems engineered to ISO 26262 functional safety thresholds and AEC-Q100 thermal cycling standards, purpose-built for vehicle-to-everything data exchange. NR SA architectures are gaining fastest among technology segments as OEMs require standalone core-network independence for autonomous driving pipelines. Embedded modules capture the deepest margin pools because they bundle protocol stacks, thermal management, and automotive cybersecurity in single-SKU procurement.
The Federal Communications Commission governs C-V2X spectrum allocation in the United States, while the European Telecommunications Standards Institute mandates interoperability testing under its 5G-V2X certification framework. Japan's Ministry of Internal Affairs and Communications coordinates 28 GHz mmWave licensing for automotive use cases. Stakeholders must weigh spectrum fragmentation against module SKU proliferation as regional band plans diverge.
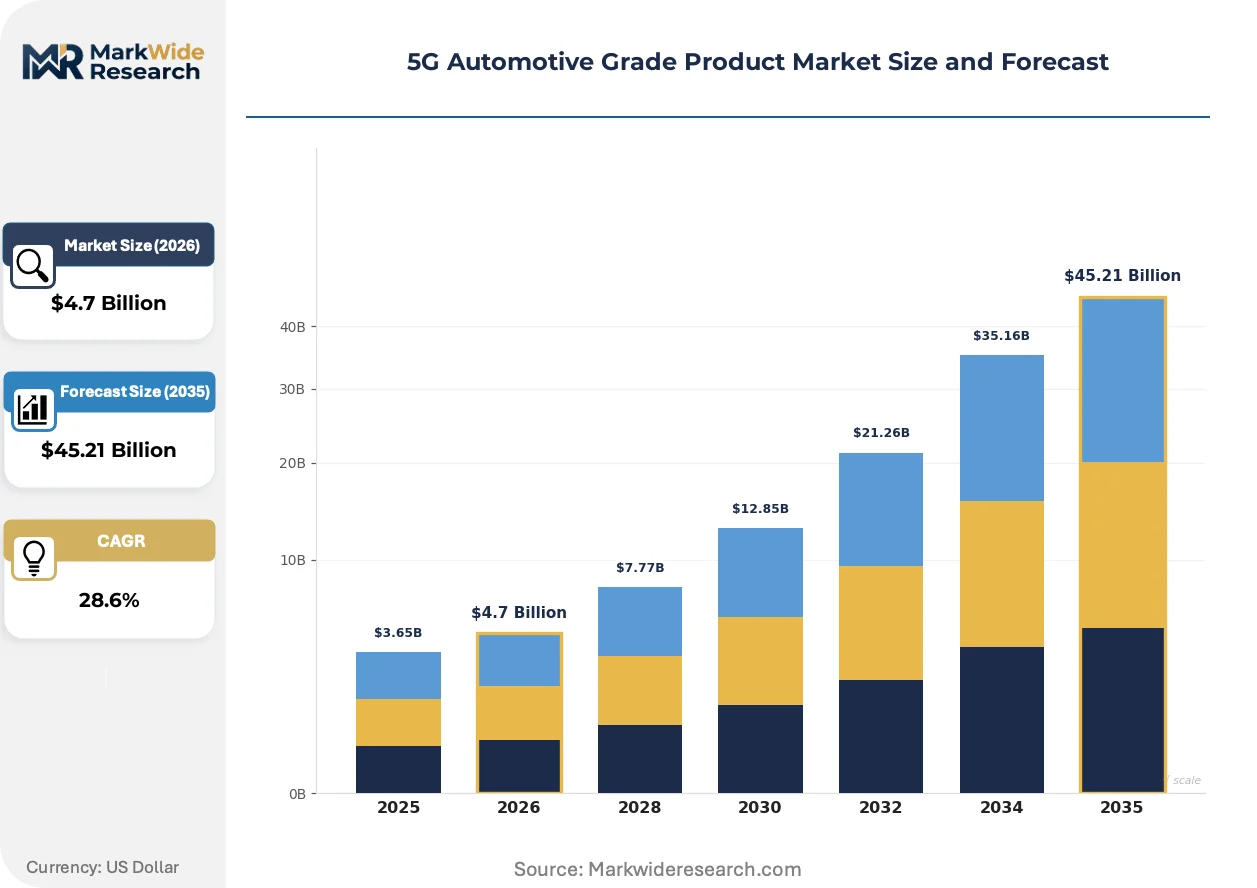
Market Dynamics
3GPP Release 16's ultra-reliable low-latency specifications are forcing OEMs to redesign hardware certification pipelines around standalone 5G architectures. This standards migration compresses module development cycles while elevating thermal and functional safety thresholds.
Growth Catalysts
- EU 5G-V2X Certification Framework:ETSI-mandated interoperability testing accelerates module procurement across German automotive engineering clusters.
- Edge-native network slicing:Deterministic latency architectures enable autonomous driving pipelines to meet ISO 26262 safety thresholds.
- C-V2X spectrum allocation:FCC licensing in the 5.9 GHz band unlocks vehicle-to-infrastructure deployment timelines in US metropolitan corridors.
Market Restraints
- Silicon supply concentration:Advanced modem-RF system fabrication depends on Taiwan and Korea foundry capacity, creating single-source vulnerability.
- Regional band fragmentation:Divergent mmWave licensing between Japan's 28 GHz allocation and European sub-6 GHz prioritization forces SKU multiplication.
- Thermal management cost escalation:AEC-Q100 Grade 2 cycling requirements drive substrate material costs upward for embedded modules.
Strategic Opportunities
- India PLI scheme for automotive electronics:Production-linked incentives attract module assembly investment away from traditional East Asian manufacturing bases.
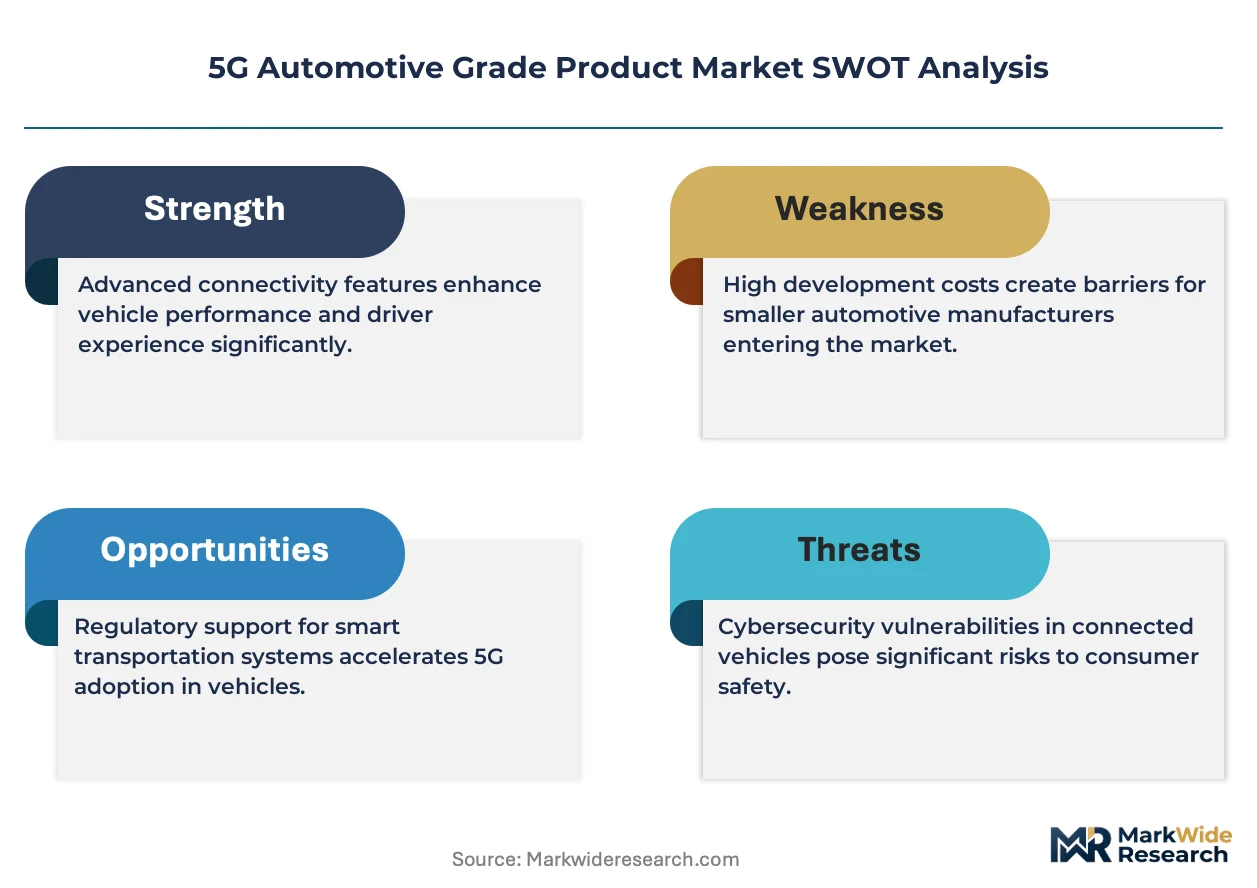
- Cybersecurity-integrated protocol stacks:Bundled hardware-software security architectures open premium pricing tiers for embedded module suppliers.
- Antenna system disaggregation:Separated antenna procurement from module integration creates aftermarket service revenue streams.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise concentrates in Germany and Japan, constraining development team scaling.
- Legacy CAN bus integration complexity:5G module retrofitting into existing vehicle electrical architectures demands custom gateway hardware.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Automotive Grade Product Market Trends and Innovations
NR standalone architectures are reconfiguring how automotive communication stacks handle mission-critical data flows. This technological pivot demands simultaneous advances in thermal engineering, cybersecurity hardening, and spectrum agility.
Network slicing for vehicular applications is digitizing how OEMs partition bandwidth between infotainment, telematics, and autonomous driving subsystems. Tier 1 suppliers are embedding slice-aware modems into domain controller designs. This capability is digitizing the traditional hardware-software boundary in automotive electronics procurement.
Japan's MIC coordinates 28 GHz mmWave licensing specifically for automotive use cases, creating a regulatory sandbox for high-bandwidth V2X trials. The allocation permits roadside unit deployment along expressway corridors. Autonomous shuttle operators in Tokyo and Osaka prefectures are first movers under this framework.
Fleet operators now specify outcome-based connectivity contracts tied to uptime guarantees rather than hardware procurement. This model displaces capital expenditure patterns with operational expenditure structures. German commercial vehicle leasing companies pioneered this shift, with North American logistics networks following.
5G Automotive Grade Product Market Segmentation
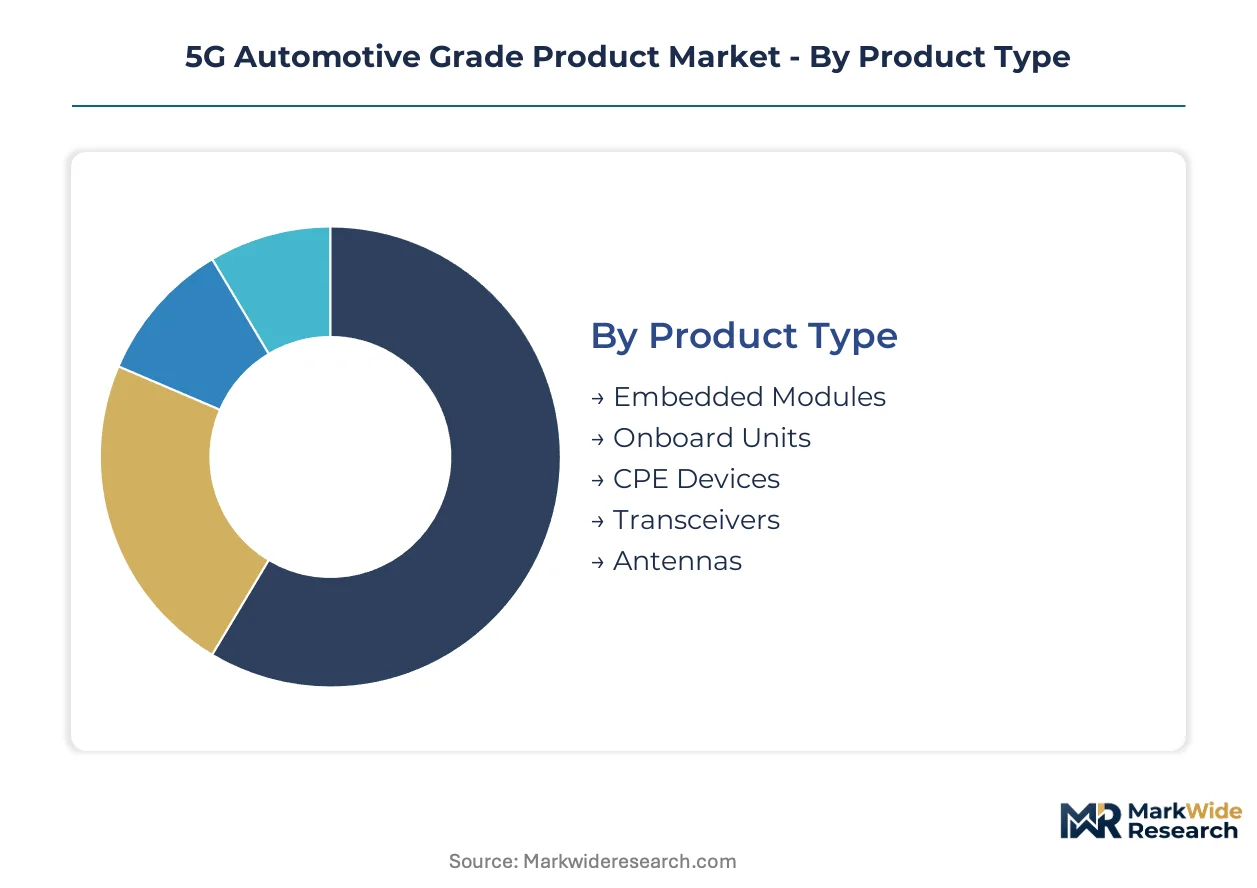
Segmentation in automotive-grade 5G markets reveals how procurement priorities diverge across hardware form factors, air interface standards, and integration depths. OEMs structure supplier selection around thermal certification tiers and standalone core-network independence rather than generic connectivity metrics.
Product Type:
Mature automotive electronics procurement patterns favor hardened modules with pre-certified protocol stacks, while emerging antenna disaggregation models reshape aftermarket service economics.
- Embedded Modules:These units integrate modem-RF systems, thermal management substrates, and automotive cybersecurity stacks within single-SKU offerings. German OEM engineering clusters drive procurement concentration here, prioritizing AEC-Q100 Grade 2 cycling compliance for powertrain-adjacent mounting locations.
- Onboard Units:Standalone communication gateways engineered for retrofit compatibility with legacy CAN bus architectures. Fleet operators in US metropolitan corridors specify these for vehicle-to-infrastructure deployment timelines accelerated by FCC 5.9 GHz licensing.
- CPE Devices:Customer premise equipment scaled for manufacturing across Korean and Vietnamese production bases.
- Transceivers:RF front-end components hardened for ISO 26262 functional safety thresholds.
- Antennas:Separable aperture systems enabling aftermarket service revenue streams outside module-integrated procurement.
Embedded modules retain volume leadership; antennas hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium standalone architectures from transitional non-standalone deployments still tethered to LTE core dependencies.
- NR SA:Standalone 5G architectures with independent core-network capability purpose-built for autonomous driving pipelines. Japanese MIC 28 GHz licensing frameworks accelerate trials for Tokyo and Osaka autonomous shuttle operators demanding deterministic latency.
- NR NSA:Non-standalone configurations leveraging existing LTE infrastructure for telematics and infotainment workloads where latency tolerance permits transitional deployment.
- LTE Advanced Pro:Legacy bridge technology sustaining connectivity in markets with incomplete 5G roadside unit coverage.
- Massive MIMO:Antenna array systems enabling spectral efficiency gains for high-density vehicle clusters.
- Beamforming:Directional signal processing techniques optimizing mmWave link reliability in urban canyon environments.
NR SA commands premium procurement pricing; NR NSA maintains installed base dominance.
Application:
Customer type differentiation separates mission-critical safety systems from discretionary infotainment workloads with divergent certification burdens.
- Autonomous Driving:Ultra-reliable low-latency communication pipelines governed by 3GPP Release 16 specifications. ETSI-mandated interoperability testing under the EU 5G-V2X certification framework concentrates module integration timelines in German engineering clusters.
- Vehicle Telematics:Remote diagnostic and prognostic data streams with moderate latency requirements.
- Fleet Management:Outcome-based connectivity contracts pioneered by German commercial vehicle leasing companies now displacing capital expenditure patterns with operational expenditure structures across North American logistics networks.
- Infotainment Systems:High-bandwidth consumer-facing content delivery with relaxed functional safety thresholds.
Autonomous driving captures the steepest technology investment trajectory; fleet management leads contract value expansion.
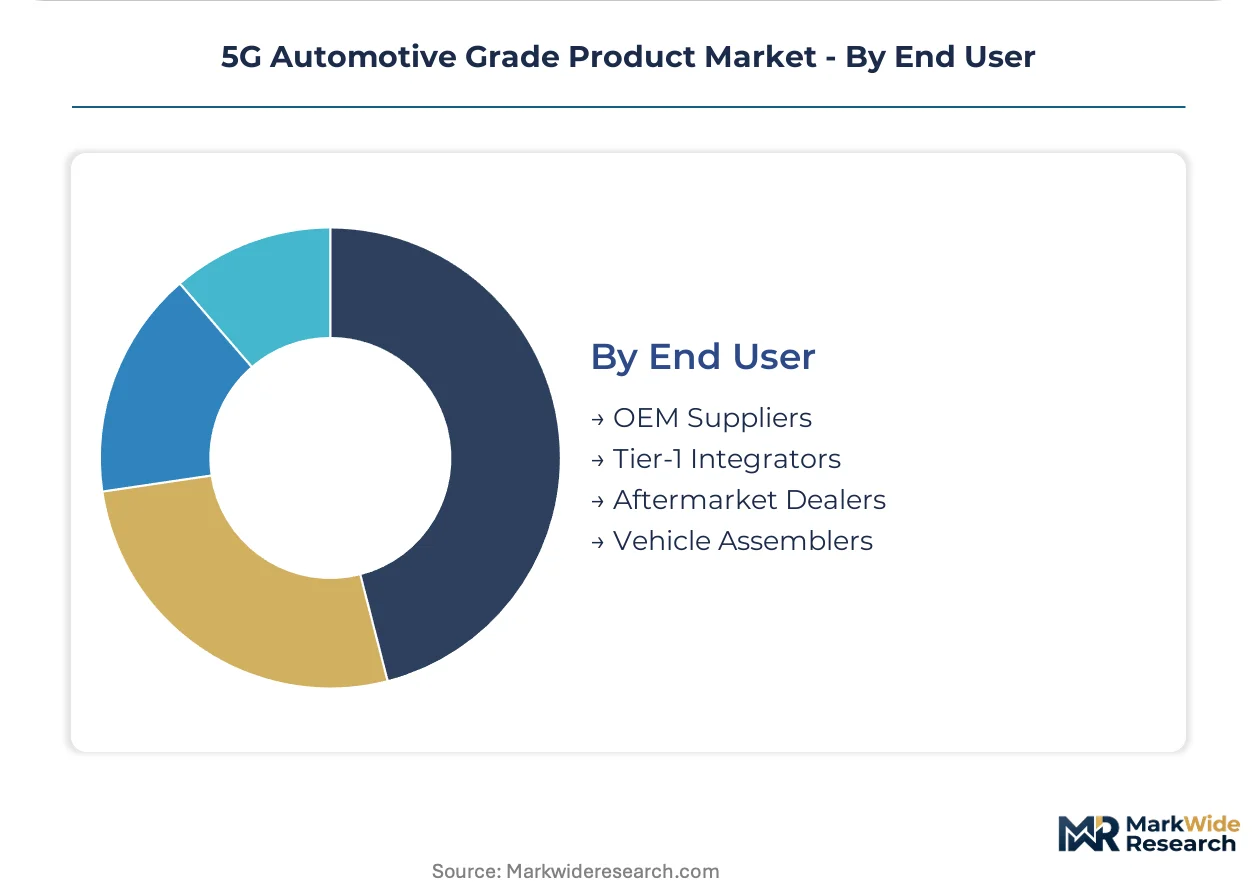
End User:
Supply concentration patterns concentrate ISO 26262 certification expertise within Tier-1 integrator and OEM supplier tiers, constraining development team scaling for smaller vehicle assemblers.
- Tier-1 Integrators:Domain controller specialists embedding slice-aware modems and managing V2X software-layer integration atop third-party silicon. These suppliers bridge OEM specification requirements with foundry-scale manufacturing.
- OEM Suppliers:Captive electronics divisions within vehicle manufacturers controlling embedded module procurement decisions.
- Vehicle Assemblers:Final-stage manufacturers dependent on upstream module certification.
- Aftermarket Dealers:Service channel operators capitalizing on antenna system disaggregation for retrofit revenue.
Tier-1 integrators anchor procurement volume; aftermarket dealers are expanding most quickly through disaggregated hardware service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports automotive-grade 5G modules to North American and Asian OEM assembly plants, establishing a trade corridor that concentrates certification expertise and procurement decision-making in Bavarian engineering clusters.
Germany
Automotive OEM engineering clusters in Munich and Stuttgart drive embedded module procurement for powertrain-adjacent mounting locations. ETSI mandates interoperability testing under the EU 5G-V2X certification framework, compressing supplier qualification timelines. Baden-Württemberg's supplier ecosystem integrates V2X software layers atop third-party silicon for Series production vehicles.
United States
Fleet operators in metropolitan corridors specify onboard units for vehicle-to-infrastructure deployment timelines. FCC governs C-V2X spectrum allocation in the 5.9 GHz band, unlocking roadside unit deployment. Michigan's automotive testing facilities validate module performance for Detroit-based OEM captive electronics divisions.
Japan
Autonomous shuttle operators in Tokyo and Osaka prefectures demand deterministic latency for high-bandwidth V2X trials. Ministry of Internal Affairs and Communications coordinates 28 GHz mmWave licensing specifically for automotive use cases. Nagoya's Chubu region anchors RF front-end component fabrication for Tier-1 integrators.
South Korea
Modem-RF system integrators leverage domestic foundry capacity for premium embedded module supply. National regulators prioritize sub-6 GHz spectrum for connected vehicle platforms alongside mmWave R&D investments. Seoul Capital Area concentrates domain controller specialists embedding slice-aware modems into automotive electronics.
India
Module assembly investment shifts toward production-linked incentive schemes for automotive electronics. Bureau of Indian Standards and TRAI coordinate spectrum allocation frameworks for connected vehicle trials. Tamil Nadu and Karnataka automotive corridors attract Tier-1 suppliers establishing captive manufacturing for export markets.
5G Automotive Grade Product Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where modem-RF system integration, V2X software-layer specialization, and manufacturing scale define distinct competitive positions. The vendor base clusters around three archetypes: silicon-integrated platform suppliers, automotive electronics integrators, and telecommunications infrastructure specialists. Dominant competitive moves include strategic partnerships between semiconductor vendors and Tier-1 automotive suppliers, plus geographic expansion of module assembly capacity into incentive-linked manufacturing jurisdictions.
Within the silicon-integrated platform tier, Qualcomm and Samsung Electronics exemplify modem-RF system integration archetypes, while Huawei Technologies occupies a position representing telecommunications infrastructure specialization with automotive adaptation capabilities.
| Leading Market Players |
|---|
| Qualcomm |
| Huawei Technologies |
| Samsung Electronics |
| Nokia |
| Ericsson |
| NXP Semiconductors |
| Continental |
| Robert Bosch |
| Intel |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam maritime freight corridors govern landed cost differentials for automotive-grade 5G modules, amplifying procurement arbitrage between German engineering clusters and East Asian assembly bases while compressing margin buffers for non-integrated distributors.
Pricing Analysis
NR SA versus NR NSA versus LTE Advanced Pro architectures stratify pricing tiers across the module landscape. Three-tier pricing structure across premium, standard, and economy levels reflects AEC-Q100 Grade 2 certification depth and protocol stack integration density. Pricing pressure stems from Taiwan foundry capacity constraints elevating modem-RF substrate costs. Fleet operators exhibit highest price sensitivity due to outcome-based contract structures, while German OEM captive electronics divisions absorb premium tiers for autonomous driving pipelines.
Supply Chain Analysis
Extended payment terms from Korean and Vietnamese CPE manufacturers now stretch to 90-120 days, straining working capital for European module integrators. Geographic supply concentration centers on Taiwan for advanced silicon, South Korea for RF front-end components, and Germany for V2X software-layer certification. Raw material dependencies include GaN substrates for thermal management, high-frequency laminates for antenna systems, and automotive-grade resin compounds for substrate housings. Single-source vulnerability in Taiwan foundry capacity constitutes the dominant structural risk. Distribution runs through Tier-1 domain controller specialists embedding slice-aware modems into OEM platform specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antenna system disaggregation is expanding aftermarket service revenue faster than embedded module hardware sales, repositioning connectivity economics around recurring diagnostic and retrofit maintenance contracts.
For Market Incumbents: Build certification moats around ISO 26262 functional safety expertise concentrated in German and Japanese engineering clusters. Deepen captive silicon sourcing through strategic partnerships with Taiwan foundry operators to mitigate single-source vulnerability. Invest in cybersecurity-integrated protocol stacks to defend margin position against modular software entrants threatening hardware-software bundling premiums. For New Entrants and Emerging Players: India's Tamil Nadu and Karnataka automotive corridors represent the most penetrable entry point for module assembly investment under production-linked incentive schemes. Target aftermarket antenna retrofit channels capitalizing on disaggregated procurement models displacing integrated module sales. Pursue outcome-based connectivity contracts with North American logistics networks replicating German commercial vehicle leasing structures. For Investors and Strategic Acquirers: Tier-1 domain controller specialists with embedded slice-aware modem capabilities offer the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on 5G-V2X certification framework expansion across EU member states and FCC spectrum allocation stability. Monitor Japan MIC 28 GHz licensing velocity for Tokyo-Osaka autonomous shuttle deployment as the inflection signal for mmWave module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Qualcomm's modem-RF system integration reduces OEM supplier qualification timelines across German engineering clusters. |
| Software-Defined Vehicle Investment | Network slicing architectures digitize hardware-software boundaries in automotive electronics procurement decisions. |
| Battery Supply Agreement | Thermal management substrate sourcing from Korean vendors secures AEC-Q100 Grade 2 cycling compliance for powertrain-adjacent modules. |
| Geographic Manufacturing Footprint | India PLI scheme relocates module assembly capacity from traditional East Asian bases to Tamil Nadu export corridors. |
| Charging Infrastructure Partnership | FCC 5.9 GHz C-V2X licensing accelerates roadside unit deployment timelines for US metropolitan fleet operators. |
Research Methodology
Operator-level perspectives from Tier-1 procurement directors, OEM platform engineers, aftermarket distribution heads, and V2X software integration specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings from semiconductor vendors, ETSI certification registries, FCC spectrum allocation dockets, and vehicle production databases from IHS Markit. Bottom-up module shipment estimates triangulated against top-down OEM platform content assumptions across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling technology segments including NR SA, NR NSA, and LTE Advanced Pro alongside product types from embedded modules to disaggregated antenna systems. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated 3GPP Release 16 standards migration timelines and regional spectrum licensing velocity from Japan MIC and FCC dockets.
Practitioners should monitor Taiwan foundry capacity utilization, EU 5G-V2X certification framework adoption rates, and India PLI scheme disbursement velocity for early signals. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.