
 Superconductor Wire Market | 2026-2036
Superconductor Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Superconductor Wire Market Outlook
Direct procurement between superconductor wire foundries and national laboratories is rewriting traditional distributor relationships in this sector. Sumitomo Electric Industries leverages captive niobium supply chains to anchor its position in low-temperature superconductor wire for fusion research. American Superconductor Corporation competes through specialized manufacturing of second-generation coated conductors for naval degaussing applications. Bruker Corporation dominates niche scientific instrument channels where cryogenic wire specifications exceed commercial grades.
Superconductor wire comprises electrically conductive filaments, typically niobium-titanium or rare-earth barium-copper-oxide compositions, that exhibit zero electrical resistance below critical temperature thresholds and enable high-field electromagnets for scientific and medical equipment. NbTi wire sustains its lead position across Magnetic Resonance Imaging installations where proven cryogenic reliability outweighs transition temperature limitations. Coated Conductors represent the fastest-expanding technology segment as energy utilities pilot resistive fault-current limiters for grid hardening. Research Institutions command concentrated margin pools through bespoke procurement of Nb3Sn cable-in-conduit conductors for high-energy physics facilities.
The US Department of Energy and Japan's METI shape demand through targeted funding mechanisms for fusion energy and grid resilience programs, while ISO and IEC standards govern critical current characterization protocols that determine product qualification. The EU AI Act and CSRD disclosure requirements are beginning to influence procurement criteria for publicly funded research infrastructure. Stakeholders must monitor how evolving superconducting magnet safety standards affect qualification timelines for next-generation accelerator projects.
Market Dynamics
The transition from low-temperature niobium-titanium wire to rare-earth barium-copper-oxide coated conductors is restructuring procurement relationships across energy and healthcare infrastructure. Foundries with captive niobium supply chains command pricing leverage as raw material access becomes the decisive competitive variable.
Growth Catalysts
- Grid Modernization Mandates:The US Department of Energy's fault-current limiter deployment targets are accelerating utility procurement of second-generation coated conductors for substation hardening.
- Fusion Research Funding:Japan's METI energy programs are expanding cable-in-conduit conductor orders for tokamak magnet systems at national laboratories.
- MRI Magnet Replacement Cycles:Healthcare providers in diagnostic imaging are upgrading cryogenic infrastructure, sustaining niobium-titanium wire demand for superconducting magnet refurbishment.
Market Restraints
- Helium Supply Concentration:Cryogenic cooling dependency locks NbTi wire economics to helium market volatility, with Qatar and the United States controlling over three-quarters of global liquefaction capacity.
- Substrate Material Bottlenecks:Hastelloy and nickel-tungsten tape supply for coated conductor manufacturing concentrates among specialty alloy producers in Germany and Japan.
- Critical Current Density Limitations:Nb3Sn conductors face strain sensitivity constraints that restrict their deployment in high-field pulsed magnet applications beyond 15 Tesla.
Strategic Opportunities
- Offshore Wind Grid Integration:European utilities are piloting superconducting DC cables for subsea transmission from North Sea wind clusters, creating demand for kilometer-scale coated conductor lengths.
- Quantum Computing Cryogenics:Dilution refrigerator manufacturers require specialized low-current superconducting wire for qubit interconnects, opening premium specification channels.
- EU CSRD Disclosure Requirements:Publicly funded research infrastructure procurement in Europe is incorporating lifecycle carbon metrics, favoring domestic coated conductor foundries with verified supply chain transparency.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:System integrators face recruitment bottlenecks for thermal management specialists capable of commissioning large-scale superconducting magnet installations.
- ISO/IEC Certification Timelines:Critical current characterization protocols require 18-24 month qualification cycles, delaying product release for next-generation accelerator magnet designs.
- Legacy MRI Service Integration:Field maintenance networks for installed niobium-titanium magnet bases resist migration to hybrid cooling architectures, constraining aftermarket revenue models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superconductor Wire Market |
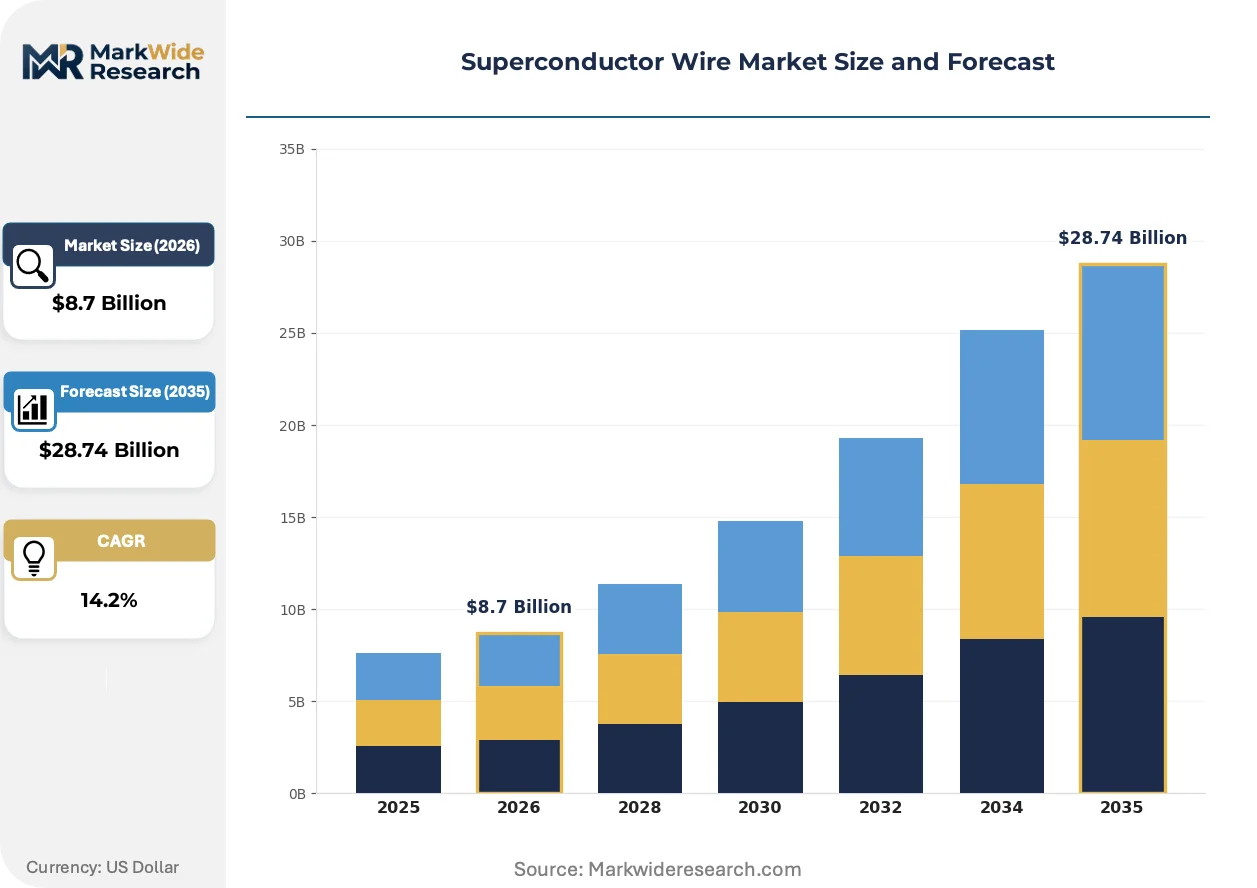
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bi-2223, NbTi, Nb3Sn, MgB2 Application: Magnetic Resonance Imaging, Energy Storage, Particle Accelerators, Power Transmission End User: Healthcare, Research Institutions, Energy Utilities, Transportation Technology: Low-Temperature Superconductors, High-Temperature Superconductors, Coated Conductors, Fundamental Research |
| Companies Covered | Sumitomo Electric Industries, Ltd., Fujikura Ltd., Furukawa Electric Co., Ltd., Bruker Corporation, American Superconductor Corporation, Nexans SA, LS Cable & System Ltd., MetOx Technologies, Inc., Japan Superconductor Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superconductor Wire Market Strategic Shifts
Manufacturing process intensification and regulatory disclosure requirements are compressing traditional supply chain hierarchies. Buyers now demand verified provenance data alongside electrical performance specifications.
Reactive co-evaporation deposition for rare-earth barium-copper-oxide layer formation is collapsing the cost structure for kilometer-length coated conductors. Wind turbine manufacturers in Denmark and Germany are qualifying these tapes for generator field windings. The technology is collapsing the historical price premium between low-temperature and high-temperature superconductor wire for power applications above 10 megawatts.
Japan's METI has revised its Strategic Energy Plan to prioritize superconducting grid infrastructure for urban load centers. The policy redirects national laboratory procurement toward domestic coated conductor foundries in the Tokyo-Osaka industrial corridor. Utilities are responding by accelerating pilot installations of resistive fault-current limiters ahead of 2030 resilience targets.
Direct contracting between end-users and wire foundries is displacing traditional distributor networks for high-specification orders. Research institutions and national laboratories now negotiate multi-year supply agreements that bundle material, characterization, and field engineering support. This pattern concentrates most visibly in fusion energy programs across Japan, the United States, and European member states.
Superconductor Wire Market Segmentation
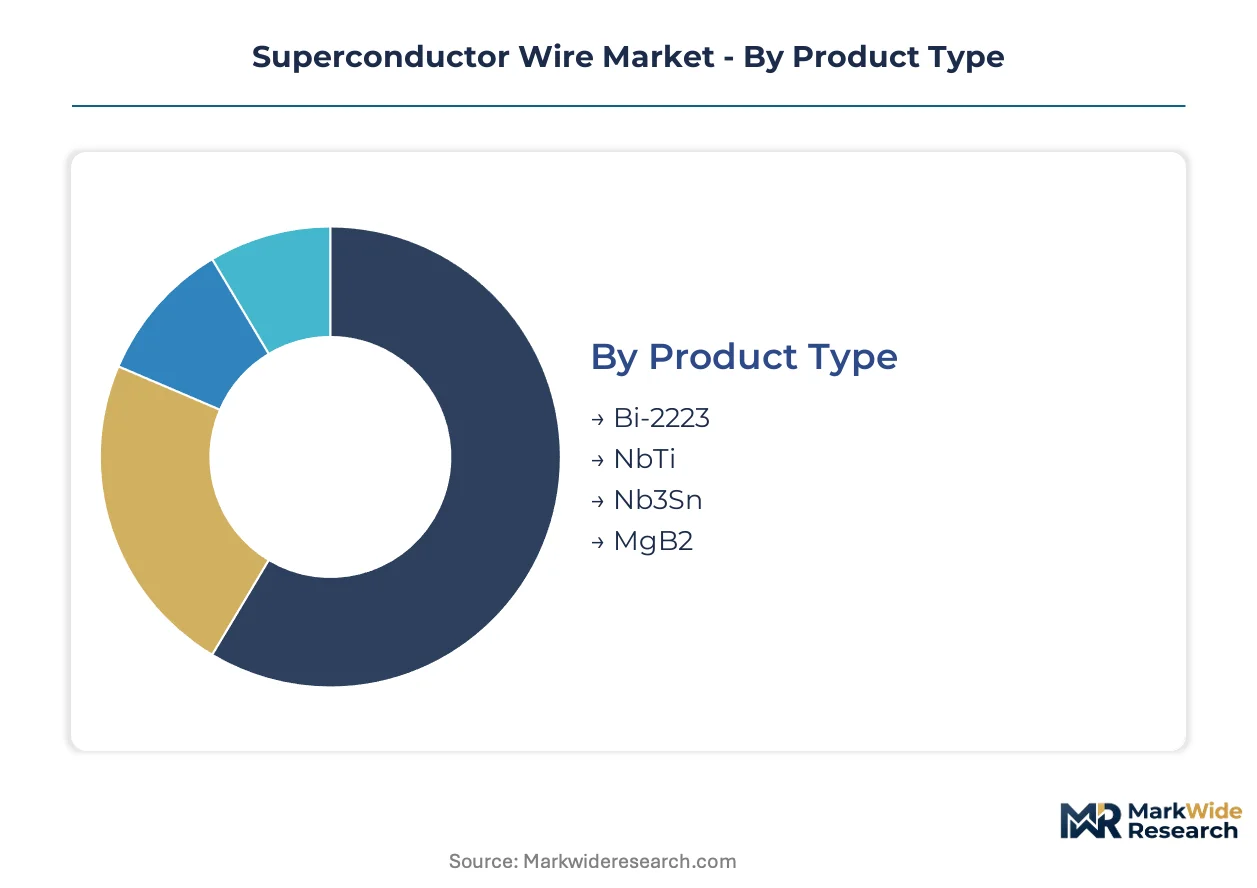
Superconductor wire procurement patterns diverge sharply across cooling architectures, end-use specifications, and institutional buyer types. Each segmentation dimension reveals distinct margin structures, qualification timelines, and supply chain dependencies that shape competitive positioning.
Product Type:
Material composition determines critical temperature thresholds, cryogenic infrastructure requirements, and field reliability profiles across installation bases.
- NbTi:Niobium-titanium alloys operate at liquid helium temperatures and sustain dominant deployment in clinical MRI magnets where decades of operational data validate cryogenic system designs. Healthcare providers in diagnostic imaging favor this chemistry for magnet refurbishment cycles, though helium supply volatility constrains total cost of ownership.
- Coated Conductors:Rare-earth barium-copper-oxide tapes deposited on flexible metallic substrates enable operation at liquid nitrogen temperatures, collapsing cooling infrastructure costs for utility-scale applications. The steepest expansion trajectory runs through grid hardening programs where fault-current limiters demand kilometer-scale conductor lengths.
- Bi-2223:Bismuth-strontium-calcium-copper-oxide round wires serve niche high-field magnet applications in scientific instrumentation.
- Nb3Sn:Niobium-tin intermetallic compounds achieve higher critical fields than NbTi, concentrating demand in fusion research magnet systems.
- MgB2:Magnesium diboride offers intermediate temperature operation with simpler manufacturing chemistry, attracting interest for emerging industrial motor applications.
NbTi commands the established base. The steepest expansion runs through Coated Conductors.
Application:
End-use engineering requirements dictate conductor specifications, from cryogenic stability margins in medical equipment to mechanical flexibility in grid infrastructure.
- Magnetic Resonance Imaging:Superconducting magnets for diagnostic imaging demand wire with proven strain tolerance through thousands of thermal cycles. Hospital procurement concentrates on niobium-titanium based systems where service networks and helium logistics are mature.
- Power Transmission:Resistive fault-current limiters and superconducting cables require coated conductors with uniform critical current across extended lengths. European utilities pilot subsea DC links from North Sea wind clusters, creating demand for specialized termination engineering.
- Energy Storage:Superconducting magnetic energy systems utilize high-current capacity conductors for grid-scale buffering applications.
- Particle Accelerators:High-energy physics facilities commission cable-in-conduit conductors with precise strain management for pulsed magnet operation.
Magnetic Resonance Imaging commands the established base. The steepest expansion runs through Power Transmission.
End User:
Buyer sophistication and procurement authority vary from clinical equipment managers to national laboratory program offices, reshaping contract structures and technical support requirements.
- Healthcare:Hospital systems and imaging center operators prioritize magnet uptime and service response over conductor specifications, locking in long-term service agreements with OEMs. Procurement concentrates on replacement cycles for installed base refurbishment rather than greenfield technology transitions.
- Research Institutions:National laboratories and university physics departments negotiate bespoke cable-in-conduit conductor orders with integrated characterization and field engineering support. Japan's fusion energy programs anchor concentrated demand for Nb3Sn and coated conductor development.
- Energy Utilities:Grid operators pilot fault-current limiters under regulatory resilience mandates, requiring multi-year performance validation before scale deployment.
- Transportation:Naval degaussing and emerging levitation systems utilize specialized conductor configurations for mobile platform applications.
Healthcare commands the established base. The steepest expansion runs through Research Institutions.
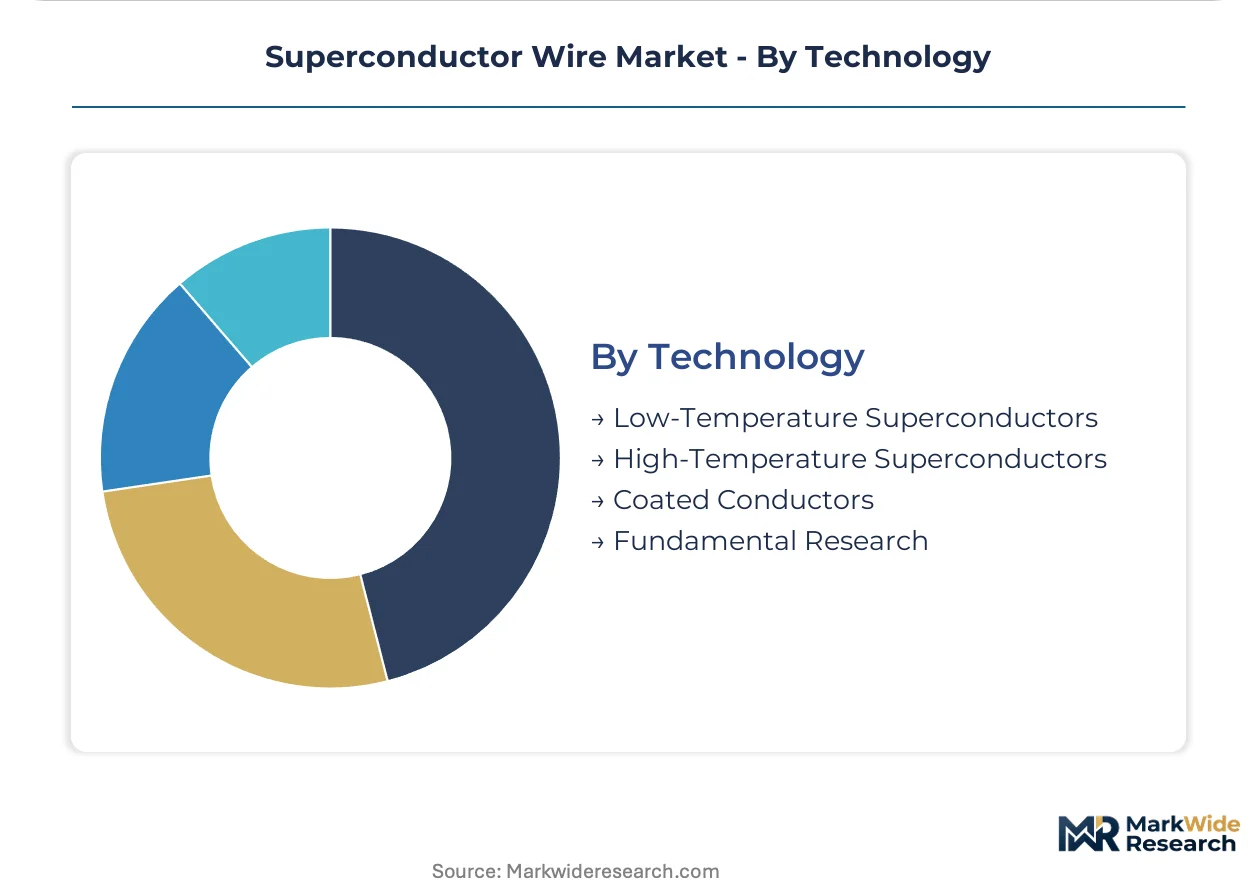
Technology:
Temperature classification separates mature cryogenic architectures from emerging high-temperature systems with divergent supply chain and engineering talent requirements.
- Low-Temperature Superconductors:Niobium-based wires operating below 10 Kelvin dominate installed medical and scientific magnet bases. Foundries with captive niobium supply chains in Japan and the United States control pricing leverage for this mature technology category.
- High-Temperature Superconductors:Rare-earth cuprate materials enable liquid nitrogen cooling, collapsing infrastructure costs for new grid and industrial applications. METI funding priorities in Japan are accelerating domestic manufacturing capacity for coated conductor tape.
- Coated Conductors:Second-generation tape architectures represent the primary commercialization pathway for high-temperature superconductors in power applications.
- Fundamental Research:Novel material systems including iron-based superconductors remain confined to laboratory characterization without production-scale wire drawing processes.
Low-Temperature Superconductors command the established base. The steepest expansion runs through High-Temperature Superconductors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates in Japanese foundries with captive niobium access, while European buyers absorb transport premiums for specialized alloy substrates. This asymmetry reshapes procurement patterns across three continents.
United States
The Department of Energy's grid modernization mandates accelerate utility procurement of fault-current limiters for substation hardening. FERC resilience directives shape transmission operator investment timelines. Boston-area research clusters anchor cable-in-conduit conductor development for fusion programs.
Japan
Tokyo-Osaka industrial corridors host concentrated RBSOC wire manufacturing for domestic tokamak magnet systems. METI's Strategic Energy Plan redirects national laboratory procurement toward domestic coated conductor foundries. Nagoya-based engineering centers specialize in kilometer-length tape qualification for grid pilots.
Germany
Specialty alloy producers in the Ruhr region control Hastelloy and nickel-tungsten substrate supply for European coated conductor manufacturing. REACH compliance requirements extend qualification timelines for imported wire. Munich-area cryogenic engineering firms cluster around accelerator magnet service contracts.
China
State-backed fusion energy programs expand procurement of Nb3Sn conductors for experimental reactor construction. GB standards govern critical current characterization protocols for domestic grid applications. Shanghai-based research institutes pilot superconducting DC cable installations for urban load centers.
South Korea
KEPCO grid resilience investments create demand for resistive fault-current limiters in metropolitan substations. MFDS safety standards influence superconducting magnet qualification for medical equipment imports. Daegu-Gyeongbuk manufacturing zones concentrate wire drawing capacity for export markets.
Superconductor Wire Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in captive supply relationships. The vendor base organizes around three archetypes: diversified industrial conglomerates with metallurgical heritage, pure-play superconductor foundries with process specialization, and scientific instrument OEMs with verticalized magnet assembly. Consolidation pressures concentrate in substrate alloy supply, while differentiation persists in cryogenic system integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves as buyers demand bundled characterization and field engineering support.
Among Japanese industrial conglomerates, Sumitomo Electric Industries, Ltd., Fujikura Ltd., and Furukawa Electric Co., Ltd. occupy positions anchored in captive niobium supply chains and decades of low-temperature superconductor wire production. These entities exemplify the diversified archetype where metallurgical process knowledge extends across multiple advanced material categories. Their geographic concentration in the Tokyo-Osaka corridor reflects historical industrial policy alignment rather than emergent clustering dynamics.
| Leading Market Players |
|---|
| Sumitomo Electric Industries, Ltd. |
| Fujikura Ltd. |
| Furukawa Electric Co., Ltd. |
| Bruker Corporation |
| American Superconductor Corporation |
| Nexans SA |
| LS Cable & System Ltd. |
| MetOx Technologies, Inc. |
| Japan Superconductor Technology Inc. |
| Others |
Value Chain & Pricing Dynamics
The Pacific Rim container corridor from Yokohama to Long Beach transmits substrate alloy premiums that concentrate pricing power among Japanese foundries with captive niobium access, while European buyers absorb transport surcharges that widen spreads between standard and configured-to-order conductor grades.
Pricing Analysis
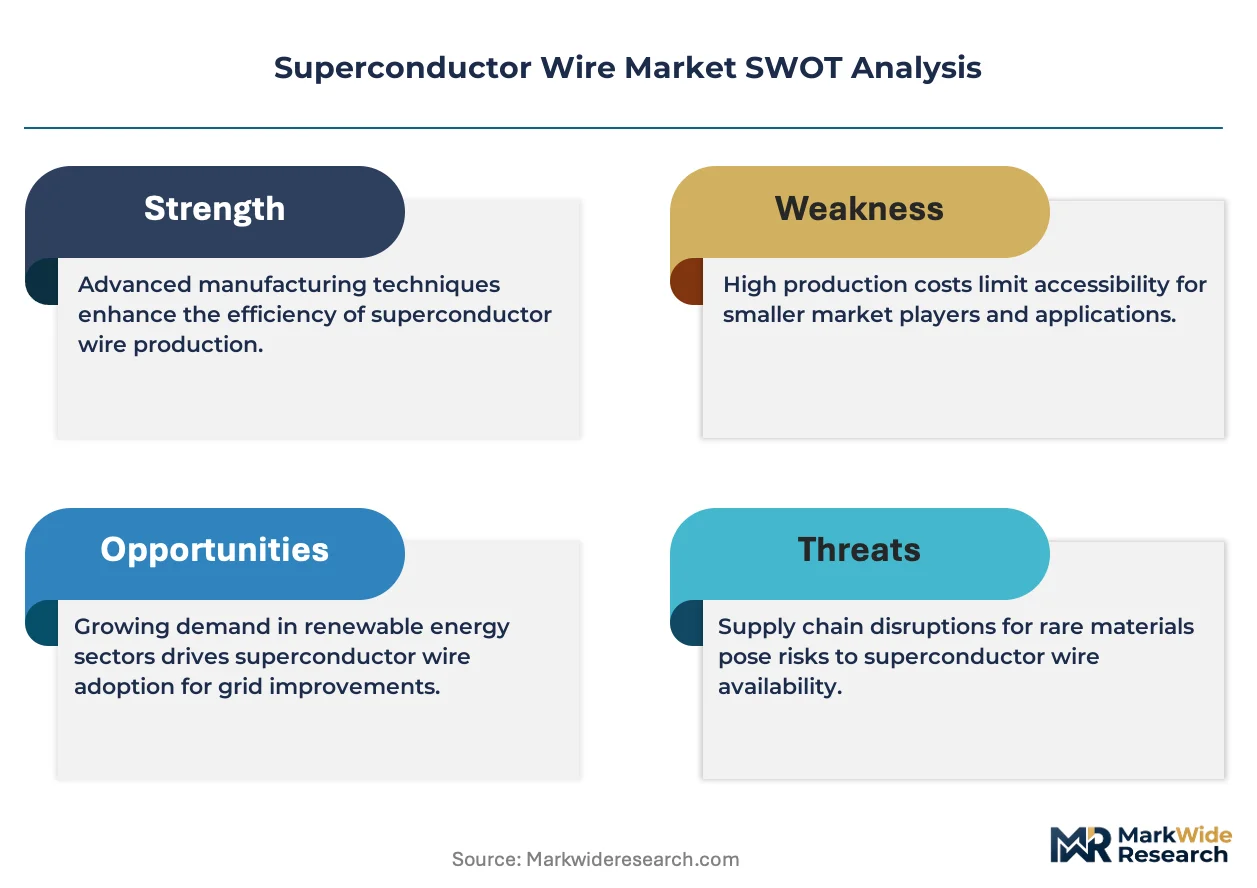
The customization-premium spread separates standard niobium-titanium wire lots from cable-in-conduit conductors with integrated strain management and field engineering support. Pricing stratifies across premium, standard, and economy tiers where ISO/IEC critical current certification tiers anchor the top bracket. Cost compression in standard NbTi wire runs through helium market volatility and Qatar's liquefaction capacity constraints. Healthcare procurement committees exhibit highest price sensitivity due to total cost of ownership pressures from cryogenic infrastructure, while national laboratories demonstrate lowest sensitivity given bespoke performance requirements and bundled technical support.
Supply Chain Analysis
Supplier-financing facilities from Japanese trading houses extend 180-day payment terms to coated conductor foundries in the Tokyo-Osaka corridor, easing working capital constraints for kilometer-scale tape production. Raw material sourcing draws from Brazilian niobium mines, German Hastelloy substrate producers, and rare-earth processors in China. Single-source vulnerability concentrates in nickel-tungsten alloy supply from Ruhr-region specialty metallurgists. Distribution runs through direct contracting between wire foundries and national laboratories, displacing traditional distributor networks for high-specification orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through ISO/IEC certification timelines creates 18-24 month qualification barriers that protect incumbent positions against unproven entrants.
For Market Incumbents: Insulate market position by deepening backward integration into niobium supply chains and expanding Nagoya-based kilometer-length tape qualification capacity. METI funding redirection toward domestic coated conductor foundries threatens foreign competitors without Japanese manufacturing footprints. Prioritize certification investment in next-generation accelerator magnet protocols to extend qualification barriers. For New Entrants and Emerging Players: European offshore wind grid integration projects represent the most penetrable entry point for kilometer-scale coated conductor supply without established service network requirements. Quantum computing cryogenics for dilution refrigerator manufacturers offers secondary white-space with premium specification tolerance. Pursue joint development agreements with Danish or German turbine OEMs rather than direct utility sales to bypass incumbent field engineering relationships. For Investors and Strategic Acquirers: Substrate alloy specialists with REACH compliance documentation and Hastelloy supply relationships command scarcity premium in European coated conductor manufacturing. The sector's five-to-ten year viability hinges on fusion energy program funding continuity and grid modernization mandate durability. Monitor Japan's METI Strategic Energy Plan revision cycles as policy inflection signals for domestic procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Niobium Supply | Captive raw material access anchors pricing leverage against helium market volatility. |
| Kilometer-Length Tape Qualification Expansion | Nagoya engineering centers validate coated conductors for European offshore wind pilots. |
| ISO/IEC Critical Current Certification Investment | Eighteen-month qualification cycles create regulatory moats protecting incumbent positions. |
| Direct Foundry-to-Laboratory Contracting | Bundled characterization and field engineering support displaces traditional distribution. |
| Quantum Computing Cryogenics Partnership | Dilution refrigerator manufacturers require specialized low-current wire for qubit interconnects. |
Study Parameters
Initial hypotheses were tested against primary input from superconducting magnet system integrators, cryogenic engineering specialists, national laboratory procurement officers, and utility grid planning directors and refined through secondary validation against SEC filings from publicly traded wire manufacturers, METI energy program disclosures, FERC grid resilience directives, and ISO/IEC standards documentation. Bottom-up demand modeling from end-use installations triangulated against top-down supply capacity assessments from foundry expansion announcements.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning material composition, cooling architecture, end-use application, and institutional buyer type. CAGRs were derived from installation base growth rates, replacement cycle timing, and policy-funded program expansion. Fusion research funding trajectories and grid modernization mandate implementation schedules served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in helium market pricing, rare-earth export restrictions, or fusion energy program funding would shift the trajectory. Forecasts reflect documented assumptions regarding substrate alloy supply continuity and certification timeline stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
AMD Motherboards Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market