
 Lichen Sclerosus Treatment Market | 2026-2036
Lichen Sclerosus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lichen Sclerosus Treatment Market Outlook
Combination treatment bundling is restructuring how prescribers and payers evaluate lichen sclerosus protocols, merging topical therapies with systemic medications into integrated care pathways rather than sequential trials. Pfizer leverages its dermatology R&D scale to sustain development of novel corticosteroid formulations. Glenmark Pharmaceuticals anchors its position in emerging markets through cost-efficient topical manufacturing. Bristol-Myers Squibb competes via its immunology pipeline breadth, positioning biologic alternatives for refractory cases.
Lichen sclerosus treatment encompasses pharmaceutical and procedural interventions targeting chronic inflammatory skin changes, primarily involving high-potency topical corticosteroids such as clobetasol propionate applied to anogenital and extragenital plaques to halt sclerosis progression and restore tissue elasticity. The primary commercial purpose centers on preventing scarring, malignancy transformation, and quality-of-life deterioration in predominantly female patient populations. Topical therapies dominate current prescription volume due to established efficacy profiles and payer familiarity, while combination treatments represent the fastest-growing segment as clinicians seek to reduce corticosteroid exposure duration. Delivery mode innovation concentrates on transdermal patches, where sustained release kinetics promise improved adherence over conventional cream applications.
FDA oversight of topical corticosteroid potency classifications and EMA guidance on chronic genital condition management jointly shape formulation standards and label claims across developed markets. The EU MDR framework adds compliance complexity for device-drug combination products targeting vulvar lichen sclerosus. Stakeholders must monitor how payer consolidation and specialty pharmacy channel expansion alter patient access economics for branded versus generic topical options.
Market Dynamics
Combination treatment bundling is restructuring prescriber-payer relationships in lichen sclerosus care, merging topical corticosteroids with systemic immunomodulators into integrated pathways that reduce sequential trial-and-error protocols. This shift compresses formulary negotiation timelines and rewards manufacturers with bundled indication breadth.
Growth Catalysts
- FDA Labeling Evolution:Updated potency classification guidance for topical corticosteroids is streamlining approval pathways for novel formulations targeting genital application sites. Dermatology centers are expanding service lines to capture chronic condition management revenue.
- Patient Advocacy Infrastructure:United States-based vulvar health organizations are driving specialist referral network density and reducing diagnostic delays for anogenital presentations.
- Transdermal Delivery Innovation:Sustained-release patch technology is automating adherence improvement over conventional cream applications in long-term maintenance protocols.
Market Restraints
- API Concentration Risk:Clobetasol propionate active pharmaceutical ingredient supply concentrates among Indian and Chinese contract manufacturers, exposing formulation sponsors to import inspection volatility.
- Generic Substitution Pressure:High-potency topical corticosteroid commoditization in mature markets erodes branded pricing power despite formulation differentiation investments.
- EMA Genital Condition Complexity:Chronic genital indication labeling requirements add clinical trial burden for device-drug combination products targeting vulvar lichen sclerosus.
Strategic Opportunities
- Pediatric Indication White Space:Prepubertal lichen sclerosus remains underaddressed by current labeling, creating first-mover advantage for sponsors completing juvenile toxicology programs.
- Specialty Pharmacy Channel Expansion:Limited distribution networks for biologic alternatives to corticosteroids in refractory cases enable premium capture and patient data accumulation.
- EU MDR Device-Drug Convergence:The Medical Device Regulation framework creates compliance moats for integrated delivery systems combining topical therapy with physical modalities.
Industry Challenges
- Dermatology Workforce Density:Specialist availability constraints in rural United States regions delay diagnosis and compress addressable patient pools for premium therapies.
- Long-Term Safety Documentation:Chronic corticosteroid exposure registries require sustained investment to satisfy post-market surveillance commitments across multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lichen Sclerosus Treatment Market |
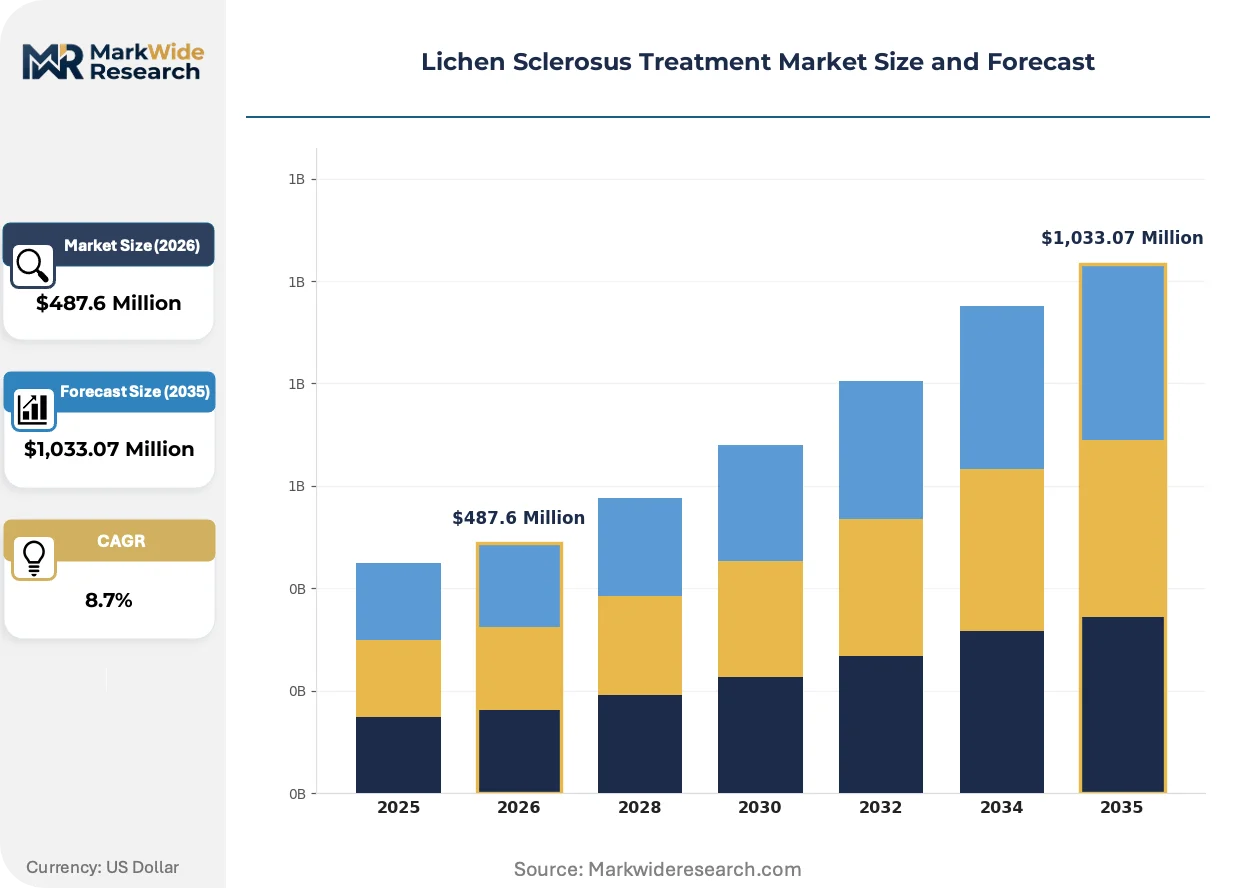
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Therapies, Systemic Medications, Surgical Procedures, Combination Treatments End User: Clinics, Hospitals, Dermatology Centers, Home Care Settings Delivery Mode: Transdermal Patches, Oral Tablets, Injectable Solutions, Creams Therapy Area: Autoimmune Disorders, Skin Conditions, Inflammatory Diseases, Rare Disorders |
| Companies Covered | GlaxoSmithKline, Johnson & Johnson, Pfizer, AstraZeneca, Novartis, Sanofi, Bristol-Myers Squibb, Teva Pharmaceuticals, Glenmark Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lichen Sclerosus Treatment Market Strategic Shifts
Digital pathology integration and biomarker stratification are reshaping how clinicians segment lichen sclerosus severity and predict malignant transformation risk. These capabilities enable precision dosing and earlier intervention thresholds.
Microbiome-targeted topical formulations are automating the shift from broad immunosuppression to localized dysbiosis correction in vulvar lichen sclerosus maintenance therapy. Academic medical centers in Germany and the Netherlands are piloting these protocols in refractory patient cohorts. The approach promises reduced corticosteroid exposure duration and improved tissue elasticity outcomes.
EMA guidance on chronic genital condition management is tightening evidentiary standards for quality-of-life claims in anogenital indications. Sponsors must now incorporate validated patient-reported outcome instruments into pivotal trials. This elevates development costs but creates differentiation barriers for competitors relying on legacy efficacy endpoints.
Specialist referral consolidation is compressing the traditional primary-care-to-dermatology diagnostic pathway in the United States. Large academic health systems are deploying teledermatology triage to capture regional patient volumes. This channel shift favors manufacturers with established relationships at hub institutions over those dependent on community prescriber networks.
Lichen Sclerosus Treatment Market Segmentation
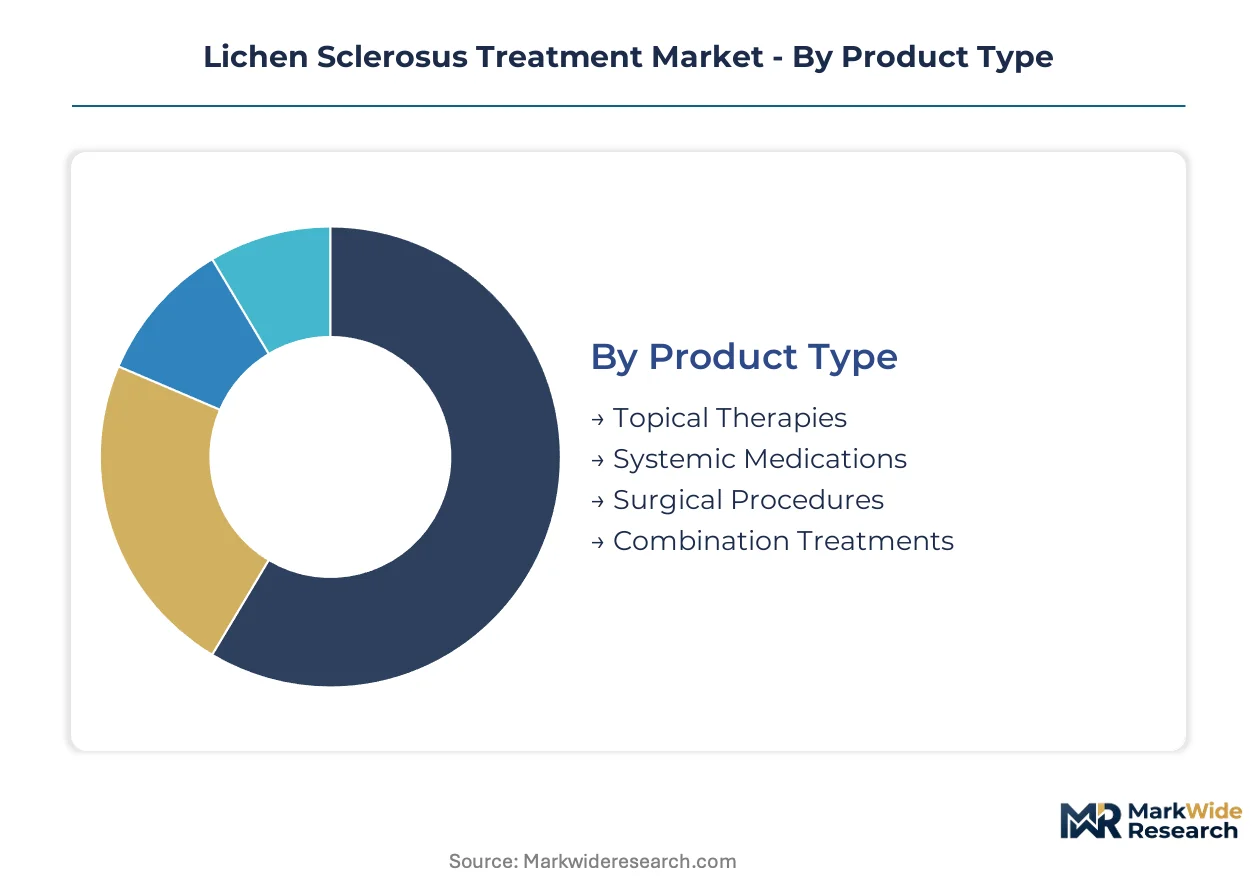
Segmentation in lichen sclerosus treatment reveals distinct capital allocation patterns across therapeutic modalities. Manufacturers prioritize segments with favorable reimbursement trajectories and regulatory clarity over those burdened by complex trial designs.
Product Type:
Capital intensity varies sharply across therapeutic categories, with formulation complexity and clinical trial scale driving upfront investment requirements.
- Topical Therapies:High-potency corticosteroid formulations such as clobetasol propionate creams and ointments dominate prescription volumes. Demand concentrates in United States dermatology centers where FDA potency classification guidance streamlines formulary placement.
- Systemic Medications:Oral immunomodulators and biologic agents target refractory cases unresponsive to localized treatment. Germany and Netherlands academic medical centers pilot these protocols for tissue elasticity restoration in vulvar presentations.
- Surgical Procedures:Excision and reconstruction interventions address advanced scarring or malignancy transformation risk.
- Combination Treatments:Bundled protocols merging topical corticosteroids with systemic immunomodulators reduce sequential trial-and-error burden.
Topical therapies absorb the bulk of installed manufacturing capacity; combination treatments are expanding most quickly as prescribers seek corticosteroid exposure reduction.
End User:
Channel economics diverge based on patient acuity, with high-complexity cases concentrating in institutional settings while maintenance therapy shifts toward ambulatory access.
- Clinics:Primary care and gynecology clinics serve as diagnostic entry points, though referral density varies by geography. United States rural regions face specialist availability constraints that compress addressable pools for premium therapies.
- Hospitals:Academic medical centers anchor severe case management and malignant transformation surveillance. Large United States health systems deploy teledermatology triage to capture regional volumes.
- Dermatology Centers:Specialist hubs concentrate chronic condition management revenue and combination therapy protocols.
- Home Care Settings:Long-term maintenance applications favor patient-administered topical regimens with adherence support infrastructure.
Hospitals command the highest per-patient revenue intensity; dermatology centers capture the steepest volume expansion as service lines proliferate.
Delivery Mode:
Technology differentiation in administration methods creates distinct competitive moats based on bioavailability engineering and patient compliance automation.
- Transdermal Patches:Sustained-release kinetics automate adherence improvement over conventional applications in long-term maintenance protocols. Pilot programs in German academic centers evaluate tissue elasticity outcomes.
- Oral Tablets:Systemic immunomodulators enable whole-body intervention for multifocal or refractory presentations.
- Injectable Solutions:Biologic alternatives target corticosteroid-resistant populations through specialty pharmacy channels.
- Creams:Conventional semisolid formulations retain cost advantages and payer familiarity despite application burden.
Creams retain dominant unit volume; transdermal patches gain share fastest on adherence automation merits.
Therapy Area:
Indication framing shapes regulatory pathway complexity and reimbursement negotiation leverage across disease category boundaries.
- Autoimmune Disorders:Immunology pipeline positioning enables biologic alternatives for refractory lichen sclerosus cases. Bristol-Myers Squibb competes via pipeline breadth in this framing.
- Skin Conditions:Dermatology-focused development emphasizes topical corticosteroid potency optimization and tissue elasticity restoration endpoints.
- Inflammatory Diseases:Broad immunosuppression mechanisms align with existing payer categories but require safety documentation investments.
- Rare Disorders:Orphan designation potential in prepubertal presentations creates pediatric indication white space for first movers.
Skin conditions anchor current labeling concentration; autoimmune disorder framing shows the most rapid pipeline repositioning activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of high-potency topical corticosteroids concentrates in Indian and Chinese contract manufacturing facilities, while consumption clusters in United States dermatology centers and European academic hospitals where diagnostic infrastructure and specialist referral networks are most developed.
United States
FDA potency classification guidance for genital application sites streamlines approval pathways for novel formulations. Patient advocacy organizations anchor specialist referral density in metropolitan corridors. Mayo Clinic and Cleveland Clinic anchor severe case management protocols in the Midwest.
Germany
Academic medical centers in Berlin and Munich pilot microbiome-targeted maintenance therapies for tissue elasticity restoration. EMA chronic genital indication labeling requirements elevate evidentiary standards for quality-of-life claims. Heidelberg and Hamburg concentrate refractory case research cohorts.
India
Cost-efficient topical manufacturing anchors supply for emerging market access programs. CDSCO oversight of active pharmaceutical ingredient quality adds inspection volatility for export-dependent formulation sponsors. Mumbai and Hyderabad cluster contract manufacturing capacity for clobetasol propionate supply.
United Kingdom
NHS specialist referral consolidation compresses diagnostic pathways toward academic dermatology hubs. MHRA post-Brexit regulatory autonomy creates parallel approval timelines for device-drug combination products. London and Manchester concentrate teledermatology triage infrastructure.
Japan
PMDA dermatology labeling standards emphasize long-term safety documentation for chronic corticosteroid exposure registries. Aging demographics expand the addressable pool for maintenance therapy protocols. Tokyo and Osaka anchor university hospital research networks for refractory case management.
Lichen Sclerosus Treatment Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with dermatology R&D scale and established payer relationships. Tier-one players command formulary placement through bundled indication breadth, while mid-scale specialists compete on cost-efficient manufacturing for emerging market access. Three archetypes dominate: Big Pharma dermatology divisions with immunology pipeline breadth, emerging market-focused generic topical manufacturers, and biologic developers targeting corticosteroid-resistant populations. M&A activity concentrates on microbiome platform acquisitions and specialty pharmacy channel consolidation.
Within the Big Pharma tier, Pfizer leverages its dermatology R&D infrastructure to sustain novel corticosteroid formulation development. Glenmark Pharmaceuticals exemplifies the emerging market specialist archetype through cost-efficient topical manufacturing positioning. Bristol-Myers Squibb occupies the biologic alternative segment for refractory case management.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Johnson & Johnson |
| Pfizer |
| AstraZeneca |
| Novartis |
| Sanofi |
| Bristol-Myers Squibb |
| Teva Pharmaceuticals |
| Glenmark Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Specialty pharmacy buyers and dermatology center procurement committees concentrate demand for branded topical corticosteroids, anchoring a contract-based pricing model that rewards formulary breadth and patient adherence infrastructure over per-unit commodity competition.
Pricing Analysis
Margin tightening in high-potency topical segments reflects generic clobetasol propionate commoditization and Indian contract manufacturer price aggression. Three-tier pricing structure across premium novel formulations, standard branded creams, and economy generics stratifies by FDA potency classification and pediatric labeling status. Cost-down pressure on maintenance therapy protocols accelerates as United States payers mandate step-therapy requirements. Community clinics exhibit highest price sensitivity; academic medical centers with bundled indication contracts demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in Indian API synthesis hubs and Chinese contract manufacturing zones concentrate clobetasol propionate active pharmaceutical ingredient production. Mumbai and Hyderabad facilities draw from specialized chemical engineering talent pools; Shanghai and Tianjin plants rest on phytosterol precursor supply chains anchored in soybean processing. Single-source vulnerability to CDSCO and NMPA import inspection volatility elevates supply risk. Distribution runs through specialty pharmacy networks and dermatology center direct accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active pharmaceutical ingredient manufacturing capacity constraints in Indian and Chinese contract facilities prop pricing power for sponsors with captive supply or dual-source qualification, creating a supply-constrained market structure favoring integrated players.
For Market Incumbents: Hedge against generic substitution pressure by securing backward integration into clobetasol propionate API production or exclusive Indian contract manufacturing agreements. Invest in pediatric indication toxicology programs to capture labeling white space before competitor entry. Channel control through specialty pharmacy limited distribution networks protects premium positioning. For New Entrants and Emerging Players: The price-point gap between biologic alternatives for refractory cases and economy generic corticosteroids creates entry space for microbiome-targeted topical formulations. German and Netherlands academic medical center pilot programs represent the most penetrable adoption channel. Pursue EMA quality-of-life endpoint validation to differentiate from legacy efficacy claims. For Investors and Strategic Acquirers: The window for entry favors microbiome platform developers with German academic partnerships and pediatric toxicology data packages. Long-term viability hinges on regulatory moat construction through EU MDR device-drug combination compliance. Watch FDA labeling guidance evolution for genital application sites as inflection indicator for formulation investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Expansion | Juvenile toxicology programs unlock prepubertal labeling white space with orphan designation potential. |
| Microbiome Platform Acquisition | German academic partnerships accelerate localized dysbiosis correction formulation development timelines. |
| Specialty Pharmacy Channel Control | Limited distribution networks enable patient data accumulation and premium capture in refractory segments. |
| EU MDR Compliance Investment | Device-drug combination certification creates regulatory moats for integrated vulvar delivery systems. |
| API Manufacturing Backward Integration | Captive clobetasol propionate supply reduces CDSCO inspection volatility exposure for formulation sponsors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dermatology R&D directors, formulary access specialists, hospital procurement managers, and payer contract negotiators. FDA 510(k) submissions, EMA marketing authorization applications, ClinicalTrials.gov registries, and Indian CDSCO manufacturing facility inspection records provided validation anchors. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated for convergence.
Reconciliation across patient-reported outcome instrument databases, teledermatology platform utilization metrics, and specialty pharmacy dispensing records informed the analytical framework. Segmentation dimensions included therapeutic modality, delivery mode innovation tier, end-user channel type, and regional regulatory cluster. CAGRs were derived from weighted average of historical trajectory and indication expansion scenarios, incorporating FDA labeling guidance evolution and EMA genital condition evidentiary standards as scenario inputs.
Inputs from clinical trial registries and formulary placement databases were available through the study window; gaps in long-term corticosteroid exposure registry completion rates introduce uncertainty bands around safety surveillance cost projections. Forecasts reflect documented assumptions regarding pediatric indication approval timelines and microbiome-targeted formulation clinical translation. Material deviation in FDA genital application site guidance or CDSCO inspection enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Australia Skin Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Rosacea Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Immunodermatology Market
Dermatology
Global Rosacea Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Global Hirsutism Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Folliculitis Treatment Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Prescription Dermatology Therapeutics Market