
 Connected Health and Wellness Devices Market | 2026-2036
Connected Health and Wellness Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Health and Wellness Devices Market Analysis
FDA's Software as a Medical Device framework is repositioning the cost-of-entry calculus for connected health device manufacturers. Medtronic leverages its deep regulatory expertise to navigate premarket submission pathways for continuous glucose monitors. Abbott Laboratories anchors its competitive position through in-house biosensor manufacturing and vertical control over consumable supply chains. Apple differentiates via consumer-grade health metrics that bridge wellness tracking and clinical-grade data streams.
Connected health and wellness devices encompass networked hardware systems that collect, transmit, and analyze physiological data through embedded sensors, wireless protocols including Bluetooth Low Energy and cellular LTE-M, and cloud-connected software platforms. These systems serve industrial and commercial purposes by enabling real-time patient surveillance outside traditional clinical settings, reducing acute care utilization while generating longitudinal health datasets. Wearables and health monitors lead product type segments due to established consumer familiarity and expanding reimbursement codes, while remote monitoring applications capture the fastest growth trajectory as health systems shift toward value-based care models. Fitness tracking retains mature volume characteristics with compressed margins, whereas chronic disease management concentrates margin pools through recurring software subscriptions and clinician dashboard licensing.
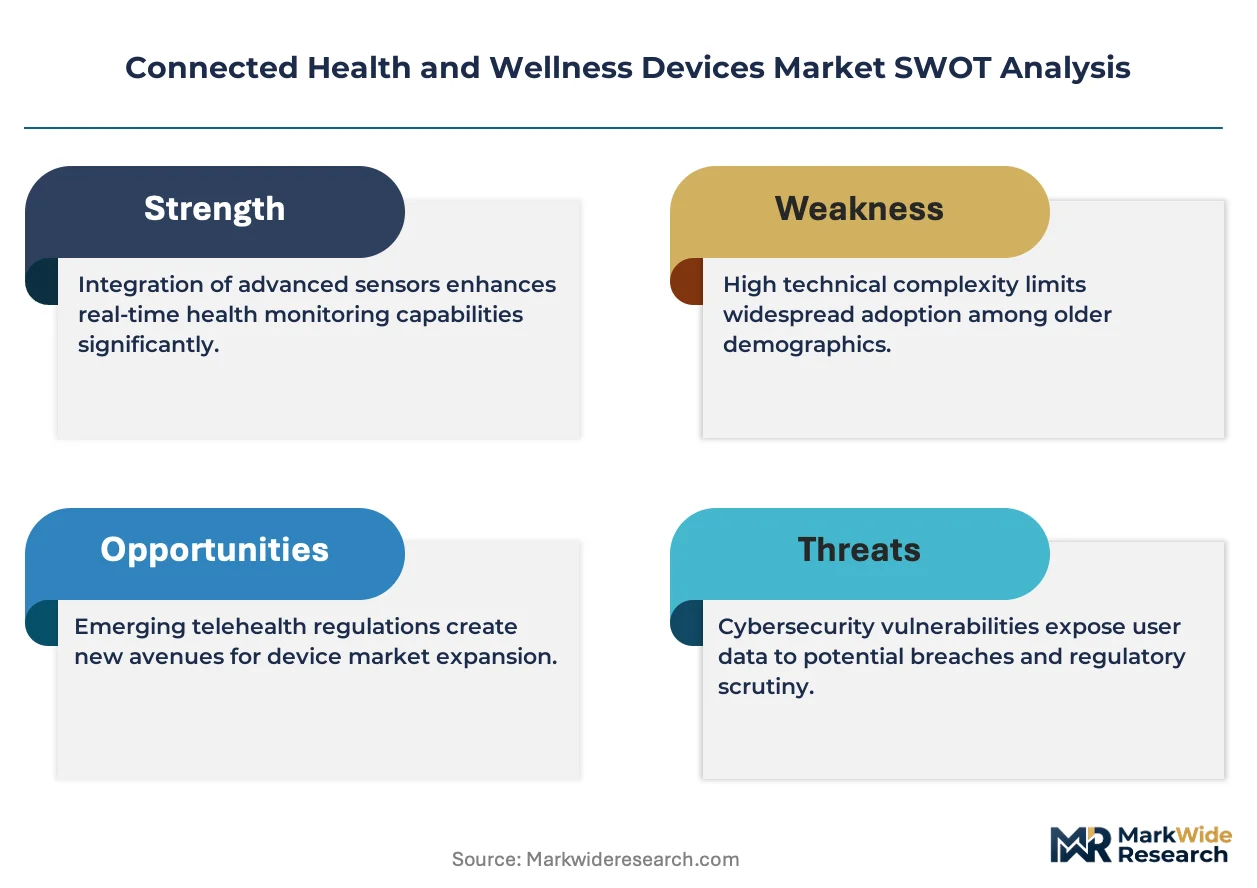
FDA digital health oversight, HIPAA privacy mandates, and EU MDR device classification collectively shape product standards, data governance obligations, and cross-border market access requirements. The EU AI Act introduces additional conformity burdens for diagnostic algorithms embedded in connected wellness platforms, particularly affecting cellular-enabled devices with autonomous decision-support capabilities. Stakeholders must monitor evolving reimbursement parity between remote physiologic monitoring and in-person clinical encounters across national health systems.
Market Dynamics
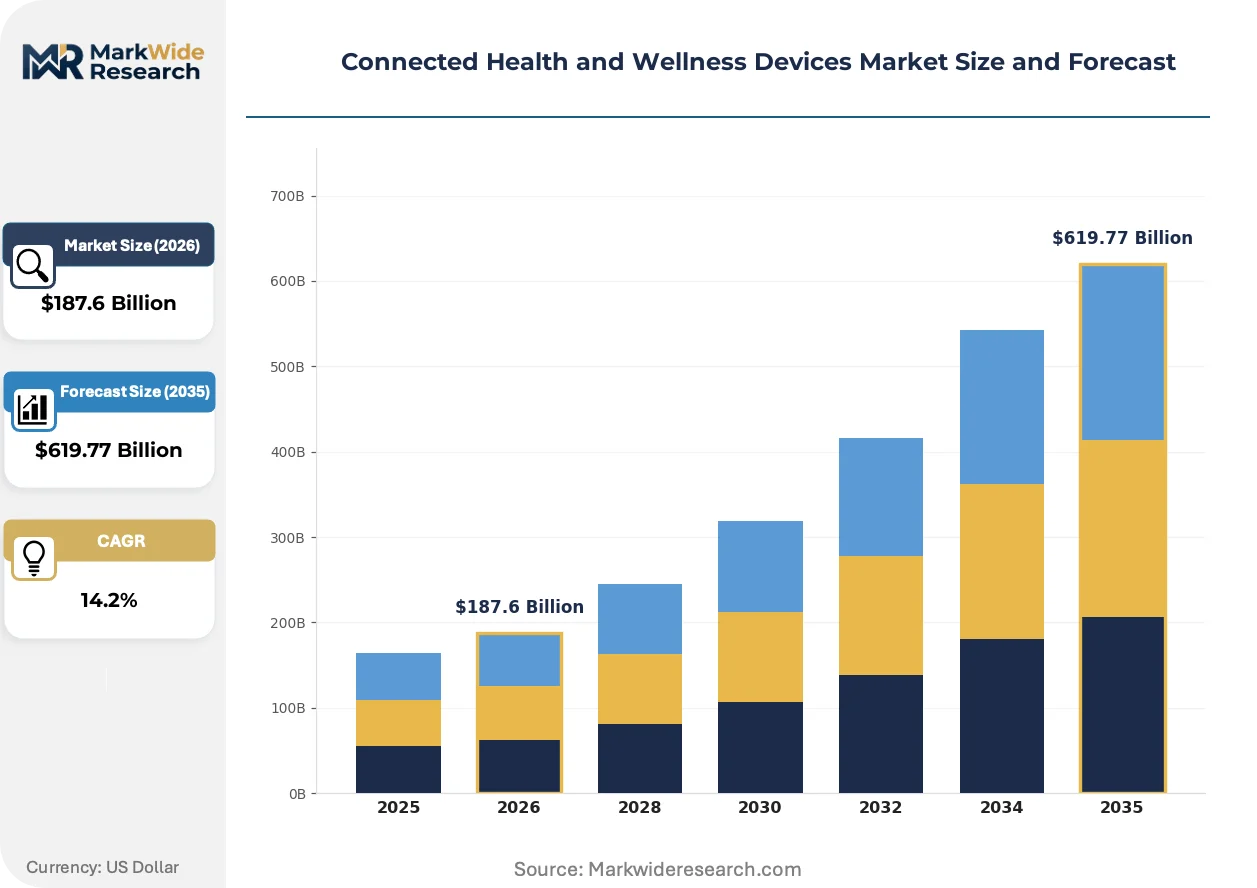
The Connected Health and Wellness Devices Market pivots on reimbursement parity expansion as payors in the United States, Germany, and Japan establish remote physiologic monitoring codes that convert consumer wellness hardware into billable clinical infrastructure.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare and Medicaid Services in the United States added CPT codes for remote patient monitoring in 2018 and has since broadened coverage to continuous glucose monitors and blood pressure cuffs, converting out-of-pocket consumer purchases into reimbursed medical expenses.
- Bluetooth Low Energy 5.3:The wireless protocol's improved power efficiency and extended range enable multi-day continuous monitoring without daily charging cycles, removing the adherence barrier that plagued earlier generation wearables in chronic disease management applications.
- Value-based care contracts:United States health systems under bundled payment arrangements deploy connected devices to reduce 30-day readmission penalties, creating institutional procurement pull distinct from individual consumer demand.
Market Restraints
- Semiconductor supply concentration:Advanced biosensor fabrication depends on TSMC and Samsung foundries concentrated in Taiwan and South Korea, exposing device manufacturers to geopolitical disruption and foundry allocation priorities favoring automotive and smartphone clients.
- EU MDR conformity costs:The Medical Device Regulation's expanded clinical evidence requirements for Class IIa and above devices extend time-to-market by 18-24 months and require notified body involvement that bottlenecks at limited accredited organizations.
- Clinical validation thresholds:FDA 510(k) clearance for diagnostic algorithms requires predicate device equivalence or prospective clinical trials, creating capital barriers that exclude wellness-focused startups from clinical-grade market segments.
Strategic Opportunities
- Japan's Super City initiative:METI's designated smart cities in Osaka and Fukuoka pilot integrated health data platforms that aggregate connected device streams into municipal health management systems, creating first-mover advantages for platform-integrated hardware vendors.
- Mental health biomarker expansion:Galvanic skin response and heart rate variability algorithms applied to anxiety and depression monitoring open reimbursement pathways through behavioral health integration that lags physical chronic disease by approximately five years.
- Direct-to-employer channels:Self-insured corporations in the United States bypass traditional payor distribution by contracting directly with device manufacturers for workforce wellness programs, capturing margin pools that health plans previously intermediated.
Industry Challenges
- FDA Software as a Medical Device classification ambiguity:Determining whether algorithm updates trigger new premarket submissions creates compliance uncertainty that slows agile development cycles and requires dedicated regulatory affairs headcount at early-stage companies.
- Interoperability standard fragmentation:Competing data exchange protocols including FHIR, Continua, and proprietary cloud APIs force manufacturers to maintain multiple integration engineering teams, inflating R&D overhead without differentiation value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Health and Wellness Devices Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Fitness Trackers, Smart Scales, Health Monitors End User: Consumers, Healthcare Providers, Fitness Centers, Insurers Technology: Bluetooth, Wi-Fi, NFC, Cellular Application: Remote Monitoring, Fitness Tracking, Chronic Disease Management, Health Coaching |
| Companies Covered | Medtronic, Abbott Laboratories, Philips Healthcare, GE HealthCare, Omron Healthcare, Fitbit, Apple, Samsung Electronics, Dexcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Health and Wellness Devices Market Emerging Trajectories
Sensor fusion architectures are compressing the form factor and power requirements of multi-modal health monitoring, enabling clinical-grade data capture in consumer-acceptable device sizes and battery lifecycles.
Photoplethysmography combined with bioimpedance spectroscopy is consolidating optical and electrical sensing modalities into single-chip solutions that reduce component count and assembly complexity. Medtronic and Abbott Laboratories integrate these fused sensors into continuous glucose monitors that now capture hydration and blood pressure proxies without additional hardware. The consolidation of sensing layers into unified semiconductor packages is compressing bill-of-materials costs and accelerating design cycles for next-generation wearables.
The EU AI Act's risk classification system for medical decision-support algorithms imposes conformity assessment burdens on connected wellness platforms with autonomous diagnostic capabilities. Device manufacturers must now document training data provenance and algorithmic transparency for notified body review before CE marking. Cellular-enabled chronic disease management devices with embedded AI triage features face the steepest compliance trajectory, with some vendors stripping autonomous features to remain below high-risk thresholds.
Employer wellness procurement is fragmenting across specialized vendors rather than consolidating through health plan intermediaries. Self-insured corporations in the United States contract directly with device manufacturers for population health monitoring, displacing traditional insurance channel distribution. This channel shift concentrates volume with vendors capable of enterprise data integration and HIPAA-compliant workforce analytics, visible most acutely in Fortune 500 manufacturing and technology sectors seeking to reduce workers compensation and disability claims.
Connected Health and Wellness Devices Market Segmentation
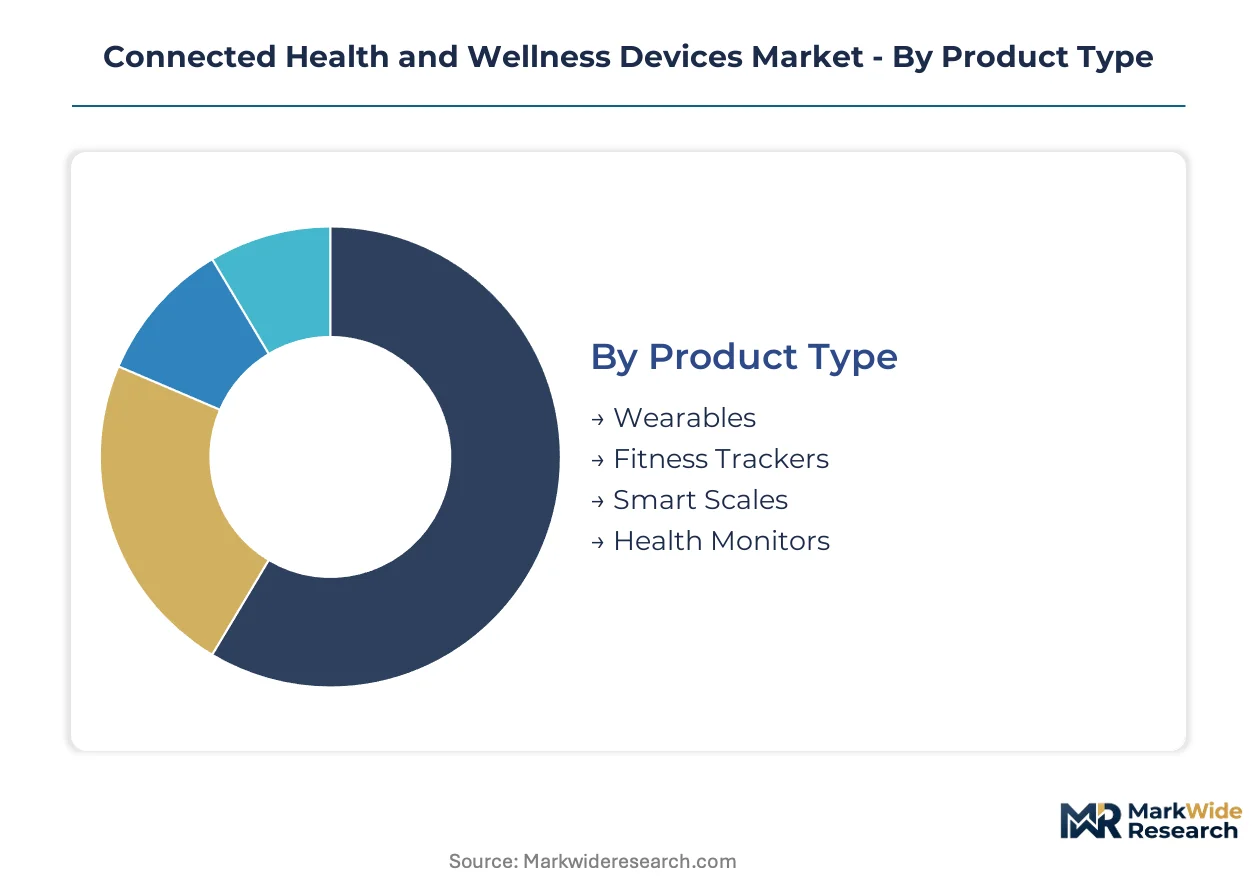
Segmentation in connected health devices separates consumer wellness hardware from reimbursed clinical infrastructure, with product type and application dimensions capturing the sharpest divergence in margin profiles and regulatory pathways.
Product Type:
Wearables dominate volume shipments while health monitors command premium pricing through clinical-grade certification requirements.
- Wearables:Multi-sensor wristbands and smartwatches integrate photoplethysmography, accelerometry, and galvanic skin response into unified semiconductor packages. Demand concentrates in the United States among Medicare Advantage plans subsidizing Apple Watch and Fitbit devices for senior populations under remote patient monitoring reimbursement codes.
- Health Monitors:Dedicated physiological measurement devices including continuous glucose monitors, blood pressure cuffs, and pulse oximeters deliver FDA-cleared diagnostic accuracy. German statutory health insurance funds now reimburse selected connected blood pressure monitors, converting retail consumer purchases into prescribed medical equipment.
- Fitness Trackers:Single-purpose activity bands with step counting and sleep staging capabilities face margin compression as smartphone health apps absorb basic wellness tracking functions.
- Smart Scales:Bioimpedance-enabled body composition analyzers transmit weight and metabolic data to clinician dashboards through Bluetooth Low Energy protocols.
Today's leader: Wearables. Tomorrow's challenger: Health Monitors.
End User:
Procurement authority is fragmenting from individual consumers toward institutional purchasers with population-scale deployment mandates.
- Healthcare Providers:Hospital systems and accountable care organizations deploy connected devices to reduce 30-day readmission penalties under bundled payment arrangements. United States health systems under value-based contracts represent the fastest-expanding procurement channel for cellular-enabled remote monitoring hardware.
- Insurers:Payors in Japan and Germany establish preferred device formularies that steer beneficiary selection toward manufacturer partners with proven data interoperability. These formulary decisions increasingly override individual consumer brand preferences.
- Consumers:Out-of-pocket purchasers drive volume in fitness tracking and basic wellness monitoring segments where reimbursement codes remain unavailable.
- Fitness Centers:Commercial gyms integrate member wearables into training program personalization, though this channel captures minimal share of clinical-grade device shipments.
Healthcare Providers concentrate purchasing power. Insurers are gaining procurement influence fastest.
Technology:
Connectivity protocol selection determines battery lifecycle, data transmission reliability, and regulatory classification boundaries.
- Bluetooth:Bluetooth Low Energy 5.3 enables multi-day continuous monitoring without daily charging cycles, removing adherence barriers that plagued earlier generation wearables in chronic disease management applications.
- Cellular:LTE-M and NB-IoT modules support autonomous data transmission without smartphone pairing, qualifying devices for remote patient monitoring reimbursement that requires uninterrupted clinician access to patient data streams.
- Wi-Fi:Higher bandwidth connectivity supports firmware updates and streaming diagnostics in home-based monitoring hubs, though power consumption limits portable deployment.
- NFC:Near-field communication enables rapid device pairing and medication adherence verification in institutional settings with controlled access points.
Bluetooth anchors installed base. Cellular is climbing the fastest toward reimbursement-qualified deployments.
Application:
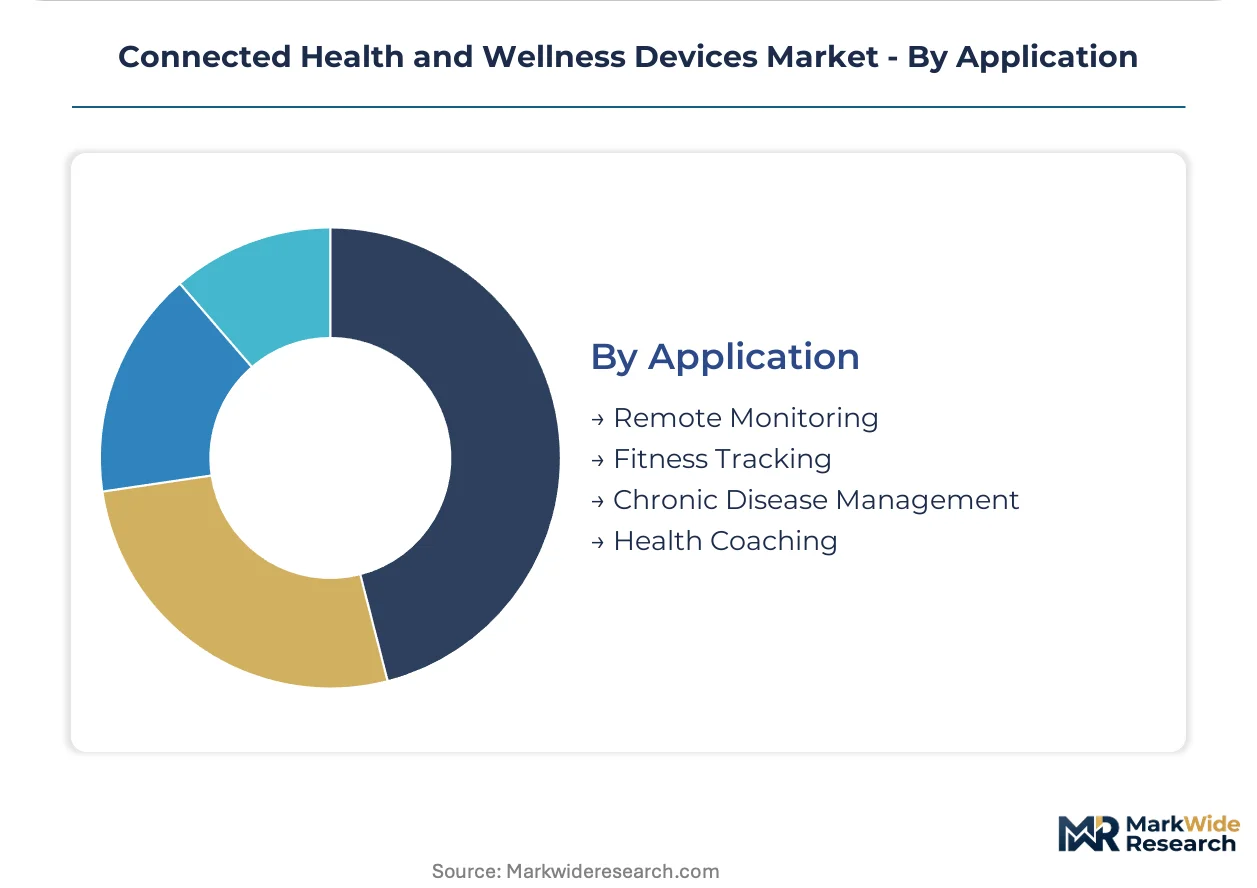
Application segmentation tracks the migration from wellness-oriented consumer use cases toward clinically reimbursed disease management workflows.
- Remote Monitoring:Real-time physiologic surveillance outside traditional clinical settings generates longitudinal datasets that qualify for CPT reimbursement codes when prescribed by licensed clinicians. This application captures the steepest expansion trajectory as health systems shift toward value-based care models.
- Chronic Disease Management:Continuous glucose monitoring for diabetes, hypertension management through connected blood pressure cuffs, and heart failure surveillance via weight and impedance tracking concentrate margin pools through recurring software subscriptions and clinician dashboard licensing.
- Fitness Tracking:Activity measurement and sleep staging retain mature volume characteristics with compressed margins as smartphone sensors and free health applications displace dedicated hardware.
- Health Coaching:Behavioral intervention platforms integrate device data with human or algorithmic coaching, though reimbursement parity for preventive wellness coaching lags physical chronic disease management by approximately five years.
Remote Monitoring leads reimbursement expansion. Chronic Disease Management is gaining share fastest through recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized talent pools in biomedical engineering and digital health software development anchor geographic demand concentration. Regulatory innovation and reimbursement policy divergence across national health systems create distinct market access conditions.
United States
Medicare Advantage plans and self-insured employers drive institutional procurement of remote monitoring hardware. FDA's Software as a Medical Device framework and CMS reimbursement code expansion reshape compliance requirements and channel economics. The Boston-Cambridge corridor and San Francisco Bay Area concentrate digital health venture capital and FDA-cleared device development.
Germany
Statutory health insurance funds now reimburse selected connected blood pressure monitors and continuous glucose monitors. EU MDR conformity assessment and the national digital health act (Digitale-Versorgung-Gesetz) mandate interoperability standards for prescribed devices. The Rhine-Ruhr and Munich metropolitan regions host medical device engineering clusters and notified body accreditation.
Japan
METI's Super City initiative in Osaka and Fukuoka pilots integrated municipal health data platforms aggregating connected device streams. PMDA's evolving software medical device guidance and aging demographics accelerate institutional adoption. The Tokyo-Yokohama corridor anchors domestic manufacturing and health system procurement authority.
United Kingdom
NHS England's remote monitoring programs and integrated care systems create procurement pull for cellular-enabled chronic disease management devices. MHRA post-Brexit regulatory autonomy and NHSX interoperability frameworks reshape market access. The Oxford-Cambridge-London golden triangle concentrates health tech venture formation and clinical validation partnerships.
China
NMPA's streamlined Class II medical device review pathways and hospital procurement centralization accelerate domestic market penetration. MIIT's health IoT standards and provincial elderly care digitization mandates drive institutional deployment. The Yangtze River Delta and Beijing-Tianjin-Hebei corridor concentrate connected health hardware manufacturing and hospital system purchasing power.
Connected Health and Wellness Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures intensify as reimbursement qualification requirements raise capital barriers for early-stage entrants. Three archetypes dominate: vertically integrated medical device incumbents with regulatory expertise, consumer electronics platforms bridging wellness and clinical data, and specialized biosensor manufacturers with captive semiconductor fabrication. Dominant competitive moves include strategic partnerships for data interoperability and portfolio diversification into adjacent chronic disease monitoring applications.
Among diversified medical technology conglomerates, Medtronic and Abbott Laboratories occupy positions anchored by deep regulatory affairs capabilities and in-house biosensor manufacturing. Apple sits within the consumer-platform archetype, leveraging ecosystem integration to bridge wellness tracking and clinical-grade data streams. These three entities exemplify divergent strategic postures: medical-grade certification depth versus consumer-scale distribution velocity.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Philips Healthcare |
| GE HealthCare |
| Omron Healthcare |
| Fitbit |
| Apple |
| Samsung Electronics |
| Dexcom |
| Others |
Supply Flow & Price Mechanics
Silicon wafer spot prices and foundry utilization rates at TSMC cascade through connected health device manufacturing into three distinct pricing tiers: clinical-grade reimbursed hardware, enterprise wellness deployments, and direct-to-consumer wellness trackers.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from recurring software-subscription models. Three-tier pricing structure across premium, standard, and economy levels tracks FDA certification status, with 510(k)-cleared continuous glucose monitors commanding substantial premiums over wellness-grade alternatives. Cost compression in the fitness tracker tier is intensifying because smartphone health applications absorb basic functionality without dedicated hardware purchase. Healthcare providers under value-based contracts exhibit the lowest price sensitivity due to bundled reimbursement codes, while individual consumers purchasing wellness devices face the highest.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Singapore, and California operate hub-and-spoke patterns that position finished devices within 48-hour delivery windows of major health system procurement hubs. Advanced biosensor fabrication draws from Taiwan, South Korea, and Japan, while final assembly concentrates in China, Mexico, and Malaysia. Single-source vulnerability in TSMC's 7nm and 5nm foundry capacity for AI-enabled diagnostic chips exposes device manufacturers to allocation rationing during automotive and smartphone demand surges. Distribution runs through medical device distributors with GPO contracts, direct-to-hospital logistics, and retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: FDA premarket submission costs in the United States run substantially higher than EU MDR conformity assessment timelines in Germany, creating divergent capital efficiency for multi-market entrants.
For Market Incumbents: To counter algorithmic triage feature stripping triggered by EU AI Act high-risk classification thresholds, deepen in-house regulatory affairs capabilities and establish dedicated notified body relationships in Germany and the Netherlands. Backward integration into biosensor semiconductor design secures supply allocation priority during foundry constraints. For New Entrants and Emerging Players: Enter via employer wellness procurement channels that bypass traditional health plan intermediation, targeting Fortune 500 manufacturing and technology sectors with HIPAA-compliant workforce analytics platforms. Mental health biomarker applications for anxiety and depression monitoring represent the most penetrable white space, with reimbursement pathways lagging physical chronic disease management by approximately five years. For Investors and Strategic Acquirers: Consolidation pressure builds where reimbursement qualification requirements raise capital barriers beyond early-stage venture capacity, favoring acquisition of FDA-cleared device developers with existing CPT code alignment. Acquisition target archetypes include specialized biosensor manufacturers with captive semiconductor fabrication and software platforms with proven clinician dashboard adoption. The signal to watch is CMS expansion of remote physiologic monitoring codes to additional chronic conditions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | 510(k) clearance converts consumer wellness hardware into billable clinical infrastructure under CMS reimbursement codes. |
| CE Marking Pathway | EU MDR conformity assessment in Germany opens statutory health insurance fund reimbursement for prescribed devices. |
| Hospital System Partnership | Accountable care organization contracts reduce 30-day readmission penalties through remote monitoring deployment. |
| Software Companion Development | Clinician dashboard licensing generates recurring revenue streams beyond one-time hardware transactions. |
| Reimbursement Strategy | CPT code alignment with CMS and Japan's MHLW determines procurement pull from institutional purchasers. |
Methodological Framework
Coverage spans the United States, Germany, Japan, and the United Kingdom, with primary inputs from each market's regulatory and procurement stakeholders. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs directors combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body registers, and hospital procurement records. Bottom-up and top-down triangulation cross-validated shipment estimates against reimbursement claim volumes and health system capital expenditure disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application, end user, technology protocol, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for technology adoption and reimbursement policy implementation timelines. Industry-specific forecast inputs incorporate Bluetooth Low Energy protocol penetration rates and cellular LTE-M module cost trajectories.
The model holds under stable reimbursement code expansion and foundry allocation continuity; deviation in FDA Software as a Medical Device classification rulings or Taiwan Strait logistics disruption would shift volume and value outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market
Digital Health Solutions
Digital Brain Health Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Amblyopia Treatment Softwares Market