
 Healthcare Digital Experience Platform Market | 2026-2036
Healthcare Digital Experience Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Digital Experience Platform Market Intelligence
Subscription-based software-defined patient engagement layers is recalibrating what health systems purchase, shifting capital budgets toward recurring operational expenditure models. Accenture leverages its cloud migration practice to anchor large hospital contracts across North America. GE Healthcare sustains technology leadership in clinical workflow integration, embedding analytics directly into imaging and monitoring ecosystems. Cognizant competes through vertical depth in payer-provider data exchange, occupying a niche between insurance platforms and hospital EMR systems.
A Healthcare Digital Experience Platform constitutes an integrated software environment that unifies patient portals, telehealth interfaces, clinical workflow engines, and real-time analytics dashboards through API-first architectures and FHIR-compliant data exchange protocols. Its primary commercial purpose is to reduce administrative friction while improving patient retention and clinical throughput across ambulatory and acute care settings. Cloud-based deployments command the largest revenue share due to elastic scalability and faster implementation cycles, while telehealth platforms represent the fastest-expanding product category as asynchronous virtual care becomes standard in post-acute follow-up. Workflow automation tools sit at the margin pool center, where robotic process automation reduces prior-authorization costs for insurance providers.
FDA oversight of software-as-a-medical-device, HIPAA security rule enforcement by the Office for Civil Rights, and ONC interoperability certification requirements collectively shape product roadmaps and vendor qualification timelines. The Cures Act information blocking provisions force incumbents to open patient data access, creating entry points for modular platform specialists. Stakeholders must monitor how state-level Medicaid expansion and Medicare Advantage penetration alter the addressable base for platform vendors serving safety-net and commercial populations.
Market Dynamics
Interoperability mandates from the ONC Cures Act Final Rule are forcing hospital procurement teams to prioritize FHIR-compliant platforms over legacy portal architectures. This regulatory pressure compresses vendor qualification timelines while expanding the addressable market for modular API-first specialists.
Growth Catalysts
- ONC Cures Act Information Blocking Provisions:Federal mandates require patient data accessibility, dismantling incumbent data silos and creating entry points for platform vendors with open-API architectures.
- Cloud-native infrastructure migration:Integrated delivery networks across the United States are replacing on-premise patient portals with elastic SaaS deployments that reduce implementation cycles.
- Asynchronous virtual care standardization:Telehealth platforms for post-acute follow-up are displacing synchronous video visits as the default modality for chronic condition management.
Market Restraints
- HIPAA Security Rule enforcement:OCR audit expansion elevates compliance costs for vendors lacking hardened cloud security postures, disproportionately burdening mid-tier platform providers.
- FDA software-as-medical-device oversight:Ambiguity in SaMD classification for diagnostic algorithms creates regulatory friction that delays product roadmaps for clinical decision support modules.
- Legacy EMR integration complexity:Proprietary data formats from dominant hospital information systems impose technical debt on platform vendors seeking seamless workflow embedding.
Strategic Opportunities
- Medicare Advantage penetration expansion:Commercial plan growth creates demand for member engagement platforms that bridge payer analytics with provider workflow tools.
- Robotic process automation convergence:Prior-authorization automation tools are integrating with patient portals to reduce administrative friction for insurance providers and hospital revenue cycle teams.
- State Medicaid expansion:Safety-net population growth in expansion states generates addressable demand for multilingual, low-bandwidth platform configurations.
Industry Challenges
- FHIR implementation expertise scarcity:Health systems report acute shortages of integration engineers capable of mapping legacy data structures to standardized exchange protocols.
- Multi-stakeholder certification timelines:Simultaneous ONC certification, HIPAA attestation, and state-level telehealth licensure requirements extend sales cycles for cross-border platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Digital Experience Platform Market |
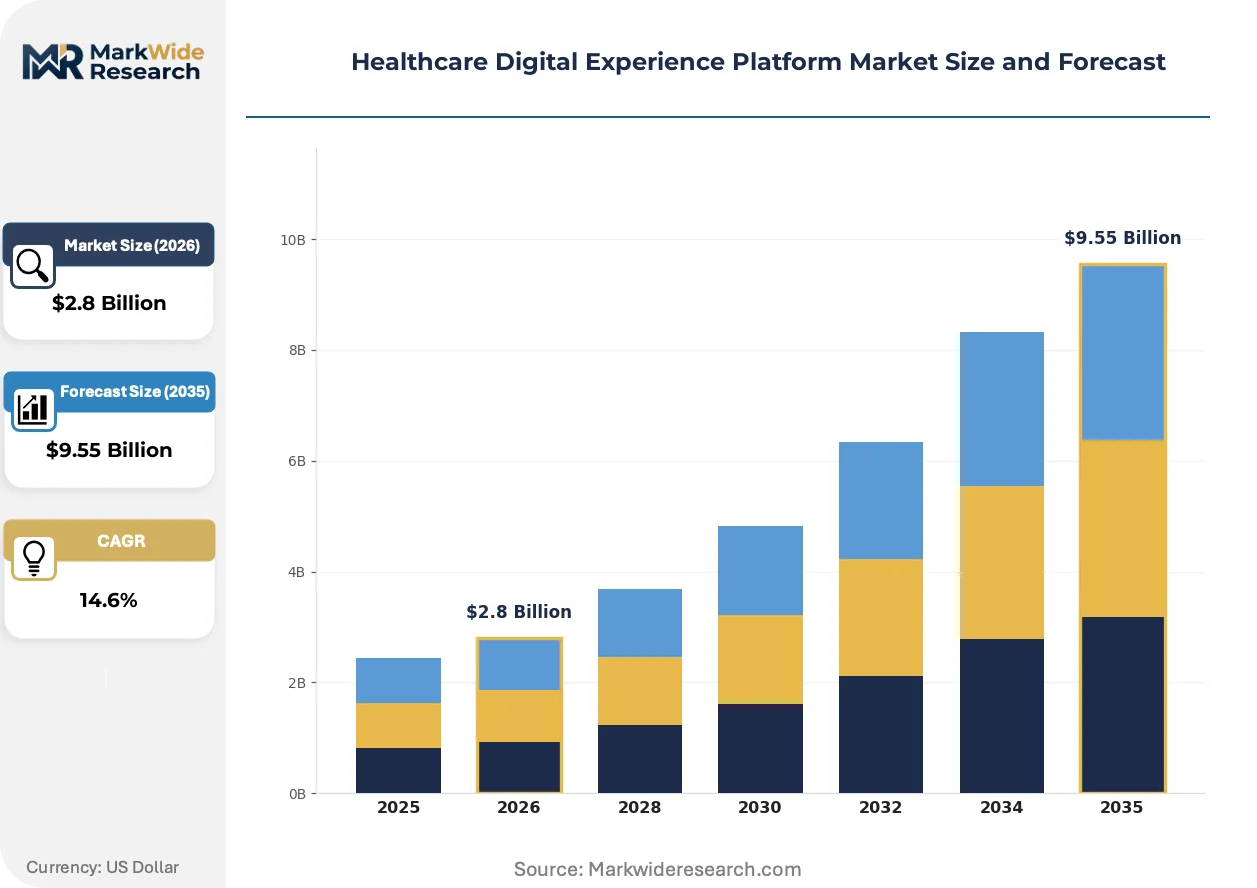
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Engagement Solutions, Telehealth Platforms, Workflow Automation Tools, Analytics Suites End User: Hospitals, Clinics, Pharmaceutical Companies, Insurance Providers Deployment: Cloud-Based, On-Premise, Hybrid Solutions, Mobile Applications Application: Remote Monitoring, Care Coordination, Virtual Consultations, Patient Feedback Systems |
| Companies Covered | Infosys, Zymr, Accenture, Orangesoft, Netguru, GE Healthcare, UST, HTD Health, Cognizant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Digital Experience Platform Market Strategic Shifts & Innovations
Workflow automation technologies are compressing administrative cost structures while regulatory data liberation mandates reconfigure competitive moats around patient data custody. Platform vendors now compete on API ecosystem breadth rather than portal feature depth.
Robotic process automation is automating prior-authorization workflows by extracting clinical documentation from EMR systems and submitting structured requests to payer portals. Large integrated delivery networks in the United States are deploying these tools across revenue cycle operations, reducing denial rates and accelerating cash conversion. This capability is compressing the addressable market for manual utilization management services.
The EU AI Act's risk classification framework for healthcare algorithms is forcing platform vendors to reengineer clinical decision support modules for transparency and human oversight requirements. Medium-risk diagnostic assistance tools must now maintain audit trails and performance monitoring dashboards. European hospital systems are prioritizing vendors with pre-positioned conformity assessment documentation.
Subscription-based platform procurement is displacing perpetual license purchases as hospital capital budgets contract under margin pressure. Chief information officers now prioritize operational expenditure models with usage-based scaling for patient engagement modules. This pattern is most visible in United States community hospital systems with limited IT depreciation reserves.
Healthcare Digital Experience Platform Market Segmentation
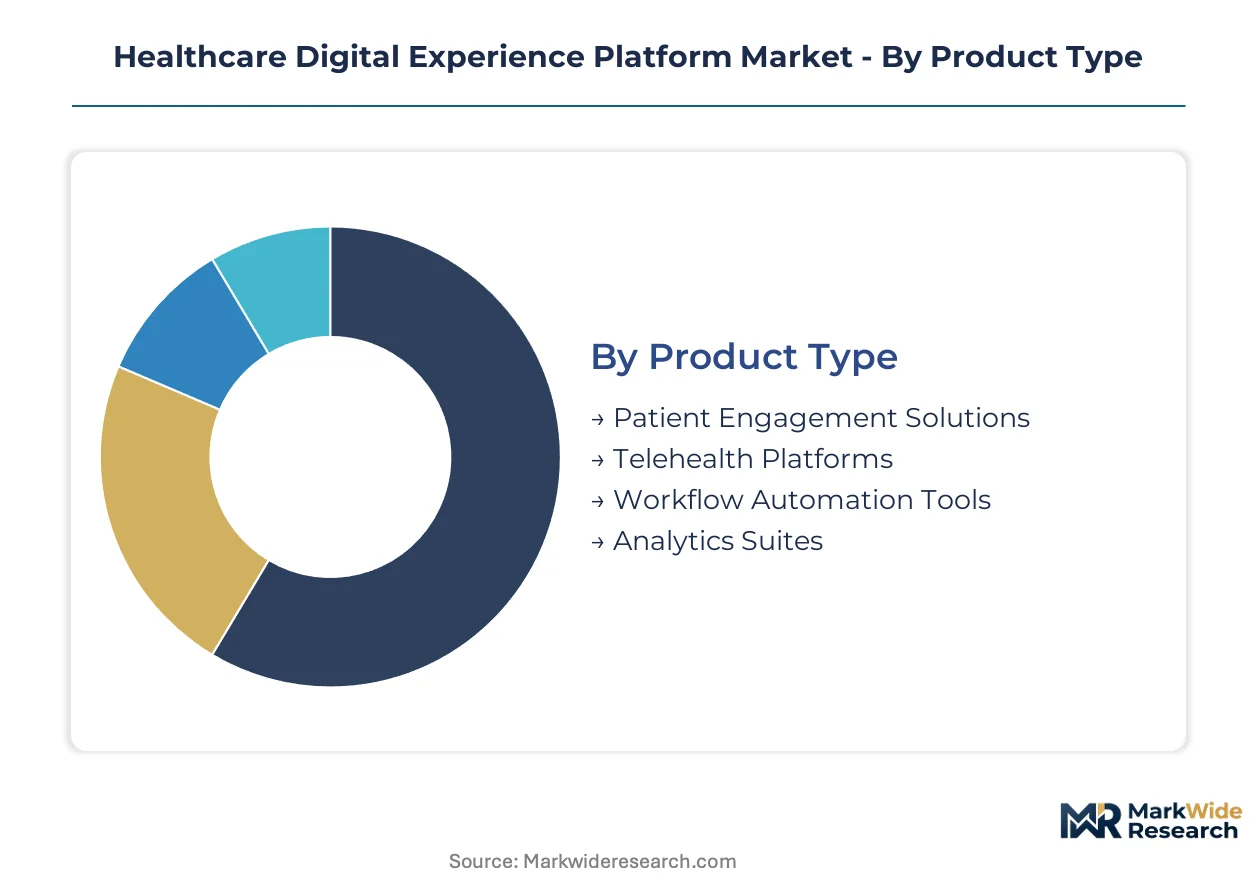
Platform procurement patterns diverge sharply across deployment architectures and clinical use cases. Hospital CIOs weight interoperability certification differently than ambulatory network operators, creating tiered demand profiles within each segment axis.
Product Type:
Functional specialization determines integration complexity and regulatory qualification pathways.
- Patient Engagement Solutions:Modular portal architectures combining appointment scheduling, secure messaging, and billing transparency through FHIR-enabled data exchange. United States integrated delivery networks prioritize these for Medicare Advantage member retention programs.
- Telehealth Platforms:Asynchronous and synchronous virtual care interfaces with embedded clinical documentation workflows. Post-acute follow-up applications in chronic disease management are expanding most quickly as reimbursement codes stabilize.
- Workflow Automation Tools:Robotic process automation for prior authorization and revenue cycle operations.
- Analytics Suites:Real-time dashboards aggregating clinical and operational metrics for population health management.
Mature deployment sits with Patient Engagement Solutions. Newer deployment is concentrated in Workflow Automation Tools.
End User:
Budget authority and procurement timelines vary substantially across provider and payer organizations.
- Hospitals:Large acute care systems with complex EMR integration requirements and multi-year implementation horizons. Cloud-native platform migration dominates capital planning cycles as ONC certification deadlines approach.
- Clinics:Federally qualified health centers and specialty practices seeking lightweight, rapid-deployment patient portal modules. Safety-net clinic networks in Medicaid expansion states drive multilingual interface demand.
- Pharmaceutical Companies:Patient support program platforms and clinical trial recruitment interfaces.
- Insurance Providers:Member engagement portals with integrated utilization management and care gap closure tools.
Volume concentration rests with Hospitals. Margin expansion is strongest with Insurance Providers.
Deployment:
Infrastructure choices reflect data sovereignty requirements and IT staffing constraints.
- Cloud-Based:Elastic SaaS architectures with API-first integration layers and automated security patching. United States community hospital systems favor these for reduced on-premise maintenance overhead.
- On-Premise:Self-managed server installations for organizations with strict data localization mandates.
- Hybrid Solutions:Split architectures keeping protected health information on-premise while leveraging cloud analytics.
- Mobile Applications:Native iOS and Android patient-facing interfaces with offline functionality for low-bandwidth environments.
Procurement momentum favors Cloud-Based deployment. Regulatory complexity peaks with Hybrid Solutions.
Application:
Clinical workflow embedding determines platform stickiness and renewal rates.
- Remote Monitoring:Continuous physiologic data ingestion from connected devices with automated alert triage. Chronic heart failure and diabetes management programs in United States Medicare Advantage plans anchor initial deployments.
- Care Coordination:Multi-provider care plan synchronization and transition-of-care documentation.
- Virtual Consultations:Scheduled and on-demand video visits with integrated e-prescribing.
- Patient Feedback Systems:Real-time experience surveys and complaint resolution workflows.
Revenue stability characterizes Remote Monitoring. Implementation velocity defines Patient Feedback Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors North American healthcare digital platform development, with Massachusetts General Hospital and Brigham and Women's Hospital serving as early deployment sites for FHIR-compliant patient engagement systems.
United States
Integrated delivery networks in Texas and Florida are replacing legacy patient portals with cloud-native architectures ahead of ONC certification deadlines. HIPAA Security Rule enforcement by the Office for Civil Rights elevates procurement scrutiny for vendors lacking hardened security postures. The Research Triangle in North Carolina hosts concentrated platform engineering talent serving hospital systems nationwide.
Germany
University hospitals in Berlin and Munich are piloting EU AI Act-compliant clinical decision support modules with embedded audit trails. The Bundesamt für Sicherheit in der Informationstechnik enforces stringent data localization requirements for patient health information. Baden-Württemberg's medical device manufacturing corridor is integrating digital experience layers directly into diagnostic equipment workflows.
United Kingdom
NHS England's Federated Data Platform procurement is driving demand for API-first patient engagement architectures across acute trusts. The Medicines and Healthcare products Regulatory Agency oversees software-as-medical-device classifications for diagnostic algorithms. London's health tech cluster around King's Cross is attracting platform vendors seeking NHS validation credentials.
India
Hospital chains in Maharashtra and Karnataka are deploying multilingual patient portals for tier-2 and tier-3 city expansion. The Central Drugs Standard Control Organization is developing software medical device guidelines that will shape vendor qualification timelines. Hyderabad's pharmaceutical services corridor is emerging as a hub for payer-provider data exchange platform development.
Japan
Metropolitan hospital systems in Tokyo and Osaka are adopting hybrid cloud architectures to satisfy data sovereignty requirements while leveraging analytics scalability. The Ministry of Economy, Trade and Industry promotes healthcare data utilization frameworks that accelerate platform procurement. Nagoya's medical device manufacturing base is embedding patient-facing interfaces into chronic disease monitoring equipment.
Healthcare Digital Experience Platform Market Key Industry Players
Capital-heavy infrastructure providers compete with asset-light software specialists across the healthcare digital experience platform landscape. The vendor base segments into three tiers: global systems integrators with cloud migration practices, clinical workflow specialists with embedded analytics capabilities, and modular API-first platform developers. Consolidation pressure intensifies as hospital procurement teams prioritize single-vendor accountability over best-of-breed integration. Dominant competitive moves include strategic partnerships between EMR incumbents and cloud-native platform developers, plus vertical capability acquisitions to fill interoperability certification gaps.
Within the global systems integrator tier, Accenture and Cognizant occupy positions defined by healthcare vertical depth and payer-provider bridge capabilities. GE Healthcare exemplifies the clinical workflow archetype, embedding patient engagement layers directly into imaging and monitoring ecosystems. Among specialized platform developers, Zymr and HTD Health represent the API-first modular approach that is gaining procurement traction under ONC interoperability mandates.
| Leading Market Players |
|---|
| Infosys |
| Zymr |
| Accenture |
| Orangesoft |
| Netguru |
| GE Healthcare |
| UST |
| HTD Health |
| Cognizant |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs cascade through Healthcare Digital Experience Platform pricing tiers, with hyperscaler compute and storage fees anchoring subscription rates for United States hospital systems before downstream markups for FHIR compliance certification and API management layers.
Pricing Analysis
Outcome-based pricing tied to patient portal uptime guarantees and clinical workflow throughput metrics anchors enterprise contracts for large integrated delivery networks. Pricing stratifies across premium, standard, and economy tiers based on ONC certification level and EMR integration complexity. Cost compression in the mid-market tier is intensifying because HIPAA Security Rule audit expansion forces security infrastructure investments. Federally qualified health centers exhibit highest price sensitivity, while Medicare Advantage plans show lowest sensitivity due to member retention value attribution.
Supply Chain Analysis
Domestic-content mandates in Germany's Bundesamt für Sicherheit in der Informationstechnik regulations and India's data localization requirements are reshaping sourcing patterns for patient data hosting infrastructure. Supply concentration rests on United States hyperscalers, German sovereign cloud providers, and Indian IT services corridors for platform engineering talent. Raw material dependencies include silicon for edge computing devices, lithium for remote monitoring hardware, and rare earth elements for MRI-integrated patient interfaces. Single-source vulnerability in FHIR implementation expertise creates procurement bottlenecks. Distribution runs through direct enterprise sales teams and systems integrator partnerships for hospital system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare Digital Experience Platform market functions as a cost-of-compliance story where ONC Cures Act certification requirements erect barrier-to-entry moats favoring vendors with pre-positioned interoperability credentials.
For Market Incumbents: Anticipate margin compression from modular API-first specialists by accelerating vertical integration into clinical decision support modules and robotic process automation engines. Consolidate through targeted acquisition of FHIR implementation boutiques to close certification gaps. Channel control via exclusive partnerships with dominant EMR incumbents represents the critical defensive lever against cloud-native disruptors. For New Entrants and Emerging Players: Launch via white-label platform partnerships with federally qualified health centers in Medicaid expansion states, where incumbent coverage remains thin and procurement timelines compress. Safety-net clinic networks in Texas and Florida offer the most penetrable entry segment due to multilingual interface demand and limited IT depreciation reserves. A care-gap closure analytics module bundled with revenue cycle automation provides the sharpest go-to-market angle. For Investors and Strategic Acquirers: Medicare Advantage plan penetration crossing critical mass in specific metropolitan statistical areas is the leading indicator that member engagement platform demand is accelerating beyond supply response capacity. Five-to-ten year viability hinges on vendors bridging payer analytics with provider workflow tools. Acquisition targets should profile as API-first modular developers with pre-certified ONC interoperability credentials. The signal to watch is state-level Medicaid procurement RFP language shifting toward mandatory FHIR compliance specifications.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Investment | ONC Cures Act compliance opens procurement doors at United States integrated delivery networks. |
| Robotic Process Automation Integration | Prior-authorization automation reduces denial rates for hospital revenue cycle operations. |
| Hospital System Partnership | Long-term enterprise agreements anchor recurring revenue against competitive displacement. |
| Software Companion Development | Clinical decision support modules embedded in imaging ecosystems deepen workflow stickiness. |
| Reimbursement Strategy Alignment | Medicare Advantage coding stabilization enables asynchronous virtual care platform monetization. |
Research Approach
Document review covered hospital procurement databases, GPO contracts, CMS Medicare data, and ONC certification registries, complemented by interviews with hospital CIOs, health system purchasing committee members, biomedical engineers, and FHIR integration specialists. Secondary validation drew from FDA software-as-medical-device filings, HIPAA Security Rule enforcement actions by the Office for Civil Rights, and state-level telehealth licensure records. Bottom-up sizing of vendor-reported deployments and top-down triangulation against health system IT expenditure surveys anchored market estimates.
Segment-level revenue outputs across the projection horizon reflect modeled deployment velocity by cloud-native versus on-premise architecture, patient engagement versus workflow automation functional category, and hospital versus clinic versus insurance provider end-user archetype. CAGRs were derived from elasticity-adjusted adoption curves incorporating regulatory deadline effects and EMR replacement cycle timing. Forecast inputs included Medicare Advantage enrollment trajectories and state Medicaid expansion status transitions.
ONC rulemaking delays, HIPAA audit scope expansion, and hyperscaler pricing volatility are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented regulatory timelines and vendor qualification pipeline visibility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Distance Health Technologies Market