
 Global Medical Device Connectors Market | 2026-2036
Global Medical Device Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Device Connectors Market Foresight
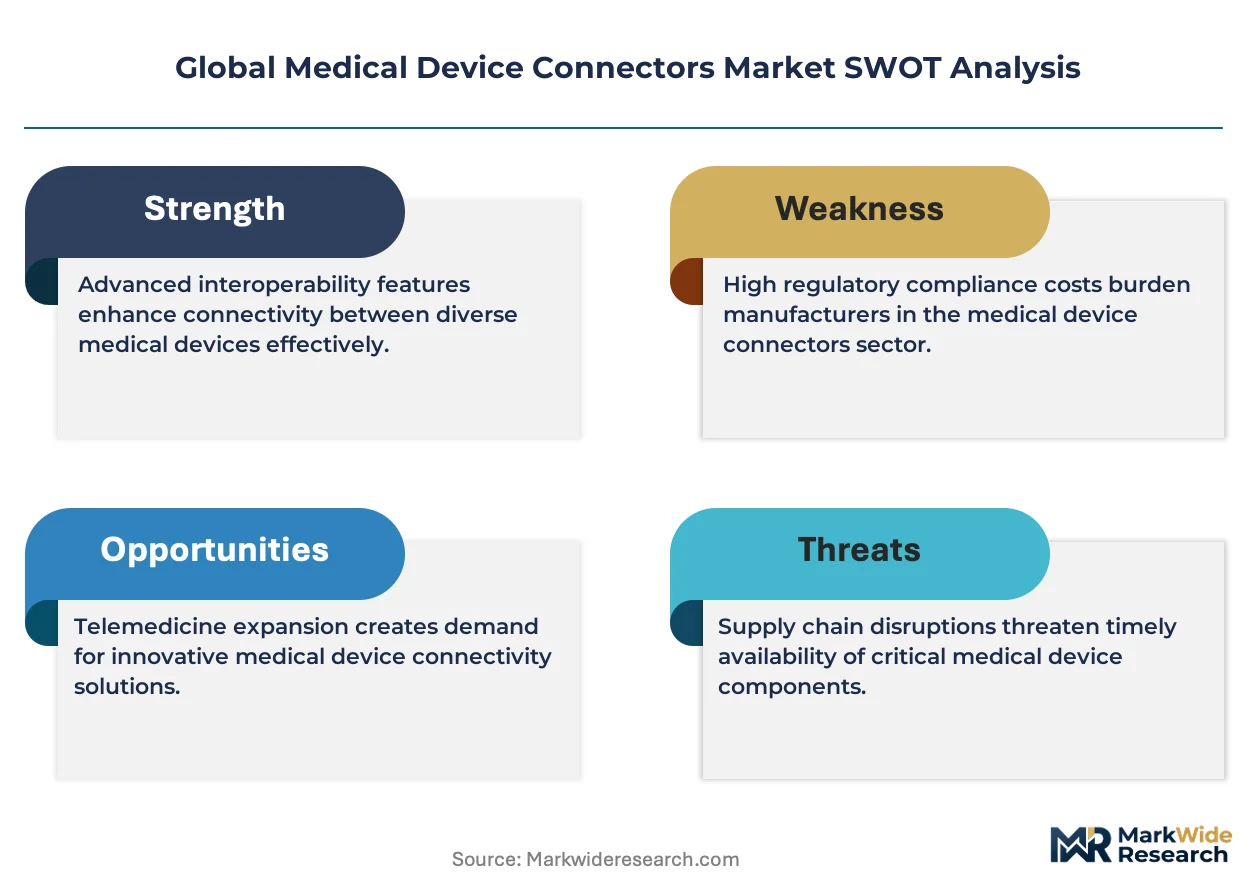
Preventive maintenance contracts and software-defined sterilization tracking is restructuring how connector vendors capture lifetime value from hospital procurement teams. TE Connectivity Ltd. leverages its broad sensor-interconnect portfolio to anchor long-term service agreements with major health systems. Amphenol Corporation competes through specialized hermetic sealing expertise that sustains premium positioning in diagnostic imaging equipment.
Medical device connectors are electromechanical interfaces engineered to transmit power, signals, or fluids between portable, bedside, and surgical equipment, typically manufactured with biocompatible plastics or passivated metals and rated for thousands of mating cycles under sterilization protocols. Their primary purpose is ensuring reliable, contamination-resistant coupling in environments where disconnection risks patient harm or equipment failure. Circular connectors command substantial share in surgical devices where rotational alignment freedom matters, while fiber optic connectors represent the fastest-expanding technology segment as optical signal integrity becomes critical for high-resolution diagnostic imaging. PCB connectors occupy mature margin pools in infusion pumps where board-level integration cost optimization drives purchasing.
The FDA enforces biocompatibility and electrical safety standards that shape connector material selection and validation timelines for US market access, while the EU MDR and REACH compliance requirements in Europe impose additional chemical disclosure and clinical performance documentation burdens. Japan's PMDA maintains stringent sterilization compatibility testing that limits supplier qualification to manufacturers with proven accelerated-aging data. Stakeholders must monitor how converging wireless and RFID technology standards redefine physical connector necessity across ambulatory care and home monitoring segments.
Market Dynamics
FDA interoperability mandates are forcing connector manufacturers to revalidate entire product lines for signal integrity under new electrical safety protocols, compressing development timelines while expanding documentation burdens.
Growth Catalysts
- EU MDR compliance deadlines:European surgical device OEMs are accelerating connector replacement cycles to meet clinical performance documentation requirements, pulling forward upgrade demand.
- Fiber optic signal density:Diagnostic imaging equipment manufacturers specify optical interfaces for high-resolution data transmission, expanding addressable connector specifications.
- Japan:PMDA sterilization compatibility testing protocols limit qualified supplier pools to manufacturers with accelerated-aging datasets, concentrating procurement among validated vendors.
Market Restraints
- Biocompatible polymer feedstock volatility:Medical-grade PEEK and PSU resin prices fluctuate with semiconductor packaging demand, squeezing molded connector margins.
- Swiss hermetic sealing concentration:Premium diagnostic imaging connectors rely on a narrow base of Alpine-region specialists for glass-to-metal sealing expertise.
- Wireless substitution in ambulatory monitoring:Bluetooth Low Energy and NFC protocols reduce physical connector necessity in patient-worn devices.
Strategic Opportunities
- India:CDSCO regulatory harmonization with IMDRF standards opens pathways for pre-qualified connectors to enter price-sensitive surgical device supply chains.
- RFID-integrated traceability:Sterilization cycle tracking embedded in connector housings creates service revenue streams from hospital asset management contracts.
- China NMPA innovation pathways:Priority review channels for domestically manufactured Class III device components accelerate market access for local production investments.
Industry Challenges
- Accelerated-aging test capacity:Validating 10-year sterilization endurance requires specialized climatic chambers with 18-month queue times at accredited laboratories.
- Legacy equipment interface persistence:Hospital capital budgets extend infusion pump lifecycles beyond 15 years, forcing connector vendors to maintain obsolete pin configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Device Connectors Market |
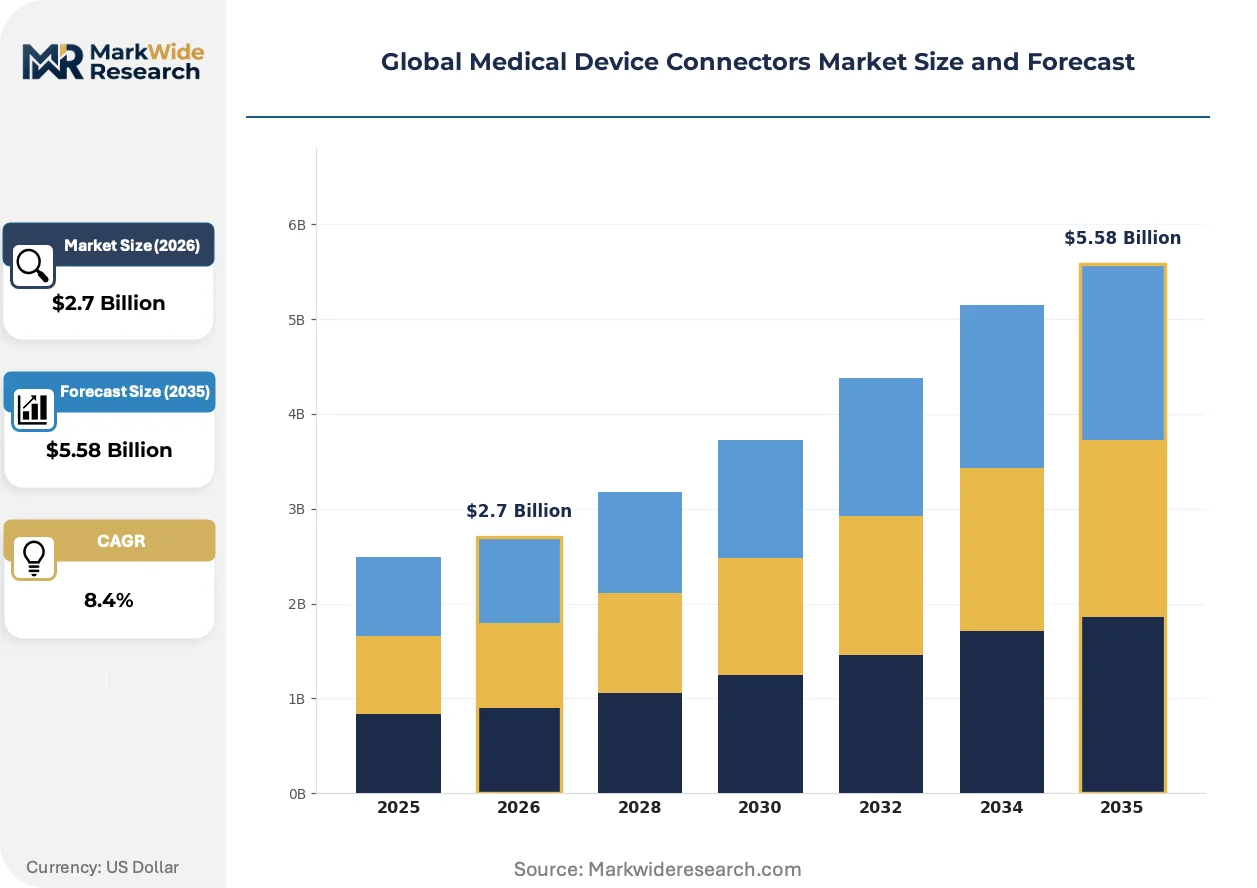
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $5.58 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circular Connectors, Rectangular Connectors, Coaxial Connectors, Fiber Optic Connectors, PCB Connectors Application: Diagnostic Imaging, Patient Monitoring, Surgical Devices, Infusion Pumps, Respiratory Equipment End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Specialty Clinics, Rehabilitation Centers Technology: Magnetic, Fiber Optic, Wireless, USB, RFID |
| Companies Covered | Amphenol Corporation, TE Connectivity Ltd., Molex, Fischer Connectors, Smiths Group, Hirose Electric Co., Ltd., ITT Corporation, Lemo S.A., Samtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Device Connectors Market Shifts & Advancements
Physical-digital convergence is redefining connector value from pure electromechanical function to data-carrying infrastructure, with sterilization-tracked intelligence becoming a baseline procurement criterion.
Hybrid copper-fiber connector assemblies are overtaking pure electrical interfaces in surgical robotics platforms. German OEMs specify these for real-time haptic feedback systems. The shift is compressing demand for legacy multi-pin copper configurations.
REACH chemical disclosure expansion is forcing reformulation of PVC cable jacketing compounds used in patient monitoring leads. ECHA substance-of-very-high-concern listings now cover common plasticizers. Connector vendors serving EU hospitals are accelerating halogen-free thermoplastic elastomer adoption.
Hospital procurement teams unbundle preventive maintenance from capital equipment purchases, awarding connector replacement contracts to independent service organizations. This fragments volume concentration previously captured by original device manufacturers. The pattern is most pronounced in United States health systems pursuing operating expense optimization.
Global Medical Device Connectors Market Segmentation
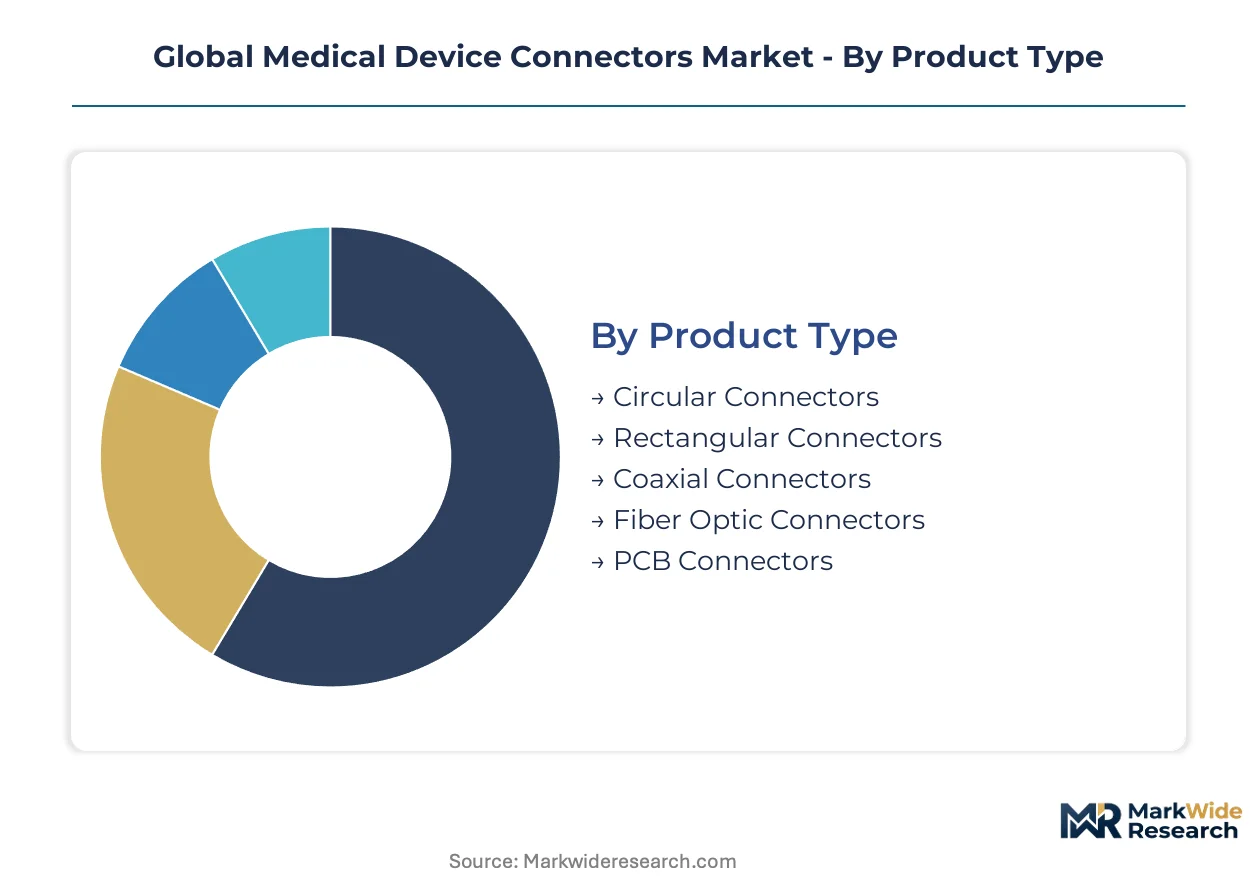
Connector specification diversity reflects the electromechanical complexity spanning sterile surgical fields, bedside monitoring arrays, and portable diagnostic equipment. Procurement teams segment purchases by sterilization protocol compatibility, signal integrity requirements, and device lifecycle duration rather than unit price alone.
Product Type:
Supply concentration for hermetic sealing expertise and precision molding capacity determines competitive positioning across connector geometries.
- Circular Connectors:Rotational alignment freedom enables blind mating in surgical robotics and endoscopic towers. German OEMs dominate procurement for da Vinci-compatible instrument interfaces. Demand concentrates where sterilization autoclave cycling exceeds 5,000 mating cycles.
- Fiber Optic Connectors:Optical signal integrity for high-resolution MRI and CT data transmission requires polished ferrule assemblies with sub-micron alignment tolerance. Diagnostic imaging equipment manufacturers in the United States specify these for 400 Gbps+ bandwidth. This segment expands most quickly as 7 Tesla MRI systems proliferate.
- Rectangular Connectors:High-density pin arrays suit patient monitoring cable assemblies where space constraints dominate.
- Coaxial Connectors:RF shielding performance drives selection in electrosurgical generators and ablation catheters.
- PCB Connectors:Board-level integration cost optimization governs infusion pump purchasing decisions.
Today's leader: Circular Connectors. Tomorrow's challenger: Fiber Optic Connectors.
Application:
Cost tier stratification separates premium sterile surgical interfaces from commoditized bedside monitoring leads.
- Surgical Devices:Hermetic sealing and biocompatible plating withstand repeated steam sterilization. Swiss glass-to-metal specialists control critical supply nodes for robotic instrument connectors. Japanese PMDA validation requirements limit qualified vendor pools.
- Diagnostic Imaging:Fiber optic density and electromagnetic interference shielding determine specification. United States hospital capital budgets favor upgradeable connector architectures for MRI and CT platforms. This segment gains share fastest as imaging resolution demands escalate.
- Patient Monitoring:Disposable leadwire connectors compete on molded plastic cost and color-coding standardization.
- Infusion Pumps:Legacy 15-year equipment lifecycles force connector vendors to maintain obsolete pin configurations.
- Respiratory Equipment:Moisture ingress resistance and oxygen compatibility drive material selection for ventilator circuits.
Surgical Devices command premium pricing. Diagnostic Imaging posts the steepest volume expansion trajectory.
End User:
Customer type determines procurement sophistication, from centralized health system contracts to fragmented clinic purchasing.
- Hospitals:Integrated delivery networks negotiate preventive maintenance contracts bundling connector replacement with capital equipment service agreements. United States health systems unbundle these contracts to independent service organizations.
- Diagnostic Laboratories:High-throughput analyzers demand signal integrity for automated sample handling interfaces. Centralized reference labs in Germany specify industrial-grade sealed connectors.
- Ambulatory Care Centers:Cost-sensitive purchasing favors standard USB and wireless alternatives where sterilization protocols permit.
- Specialty Clinics:Dermatology and ophthalmology practices prioritize compact connector footprints for limited procedure room space.
- Rehabilitation Centers:Durability for patient-handled portable devices outweighs precision specifications.
Hospitals anchor volume concentration. Diagnostic Laboratories drive specification intensity.
Technology:
Maturity curves separate established copper interfaces from emerging optical and wireless protocols.
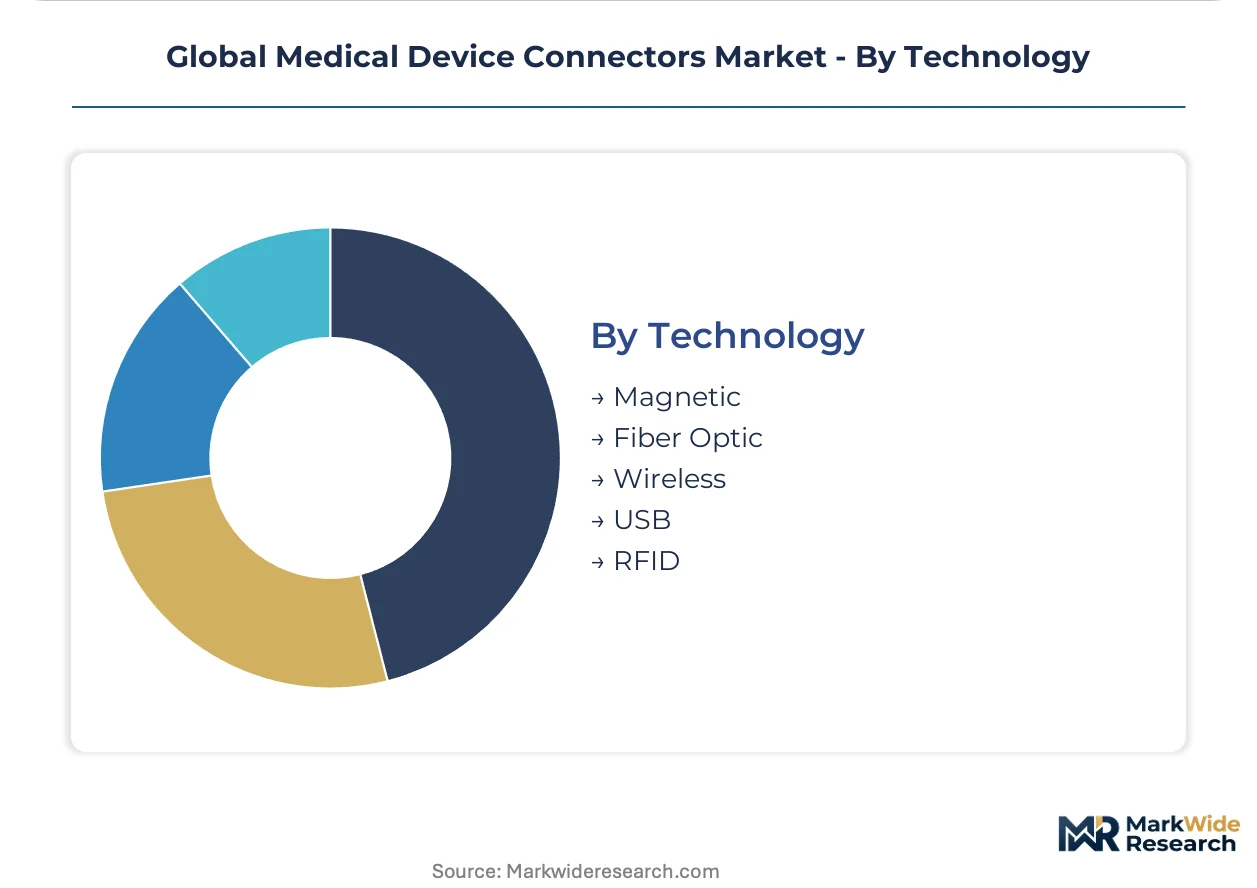
- Fiber Optic:Bandwidth scalability for next-generation imaging modalities positions this technology for surgical robotics haptic feedback systems. German OEMs specify hybrid copper-fiber assemblies.
- RFID:Sterilization cycle tracking embedded in connector housings creates recurring service revenue from hospital asset management contracts. EU MDR traceability mandates accelerate adoption.
- Magnetic:Quick-disconnect safety for patient-worn devices prevents cable entanglement injuries.
- Wireless:Bluetooth Low Energy and NFC protocols reduce physical connector necessity in ambulatory monitoring segments.
- USB:Consumer-electronics compatibility drives adoption in low-acuity home monitoring devices.
Fiber Optic leads technology investment. RFID creates the most defensible service revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connector manufacturers are relocating production to jurisdictions where sterilization validation costs diverge from end-market pricing power. Switzerland and Germany retain premium hermetic sealing clusters despite higher labor costs, while China and India capture volume assembly through regulatory harmonization.
United States
FDA interoperability mandates are forcing connector revalidation for signal integrity under new electrical safety protocols. Hospital procurement teams unbundle preventive maintenance contracts to independent service organizations. Minneapolis and Boston medical device corridors concentrate surgical robotics OEM demand for hybrid copper-fiber assemblies.
Germany
Surgical device OEMs in Baden-Württemberg specify higher-grade sealed connectors for robotic instrument interfaces. EU MDR compliance deadlines accelerate connector replacement cycles for clinical performance documentation. The Stuttgart-Tübingen cluster anchors glass-to-metal hermetic sealing expertise for diagnostic imaging connectors.
Switzerland
Swiss glass-to-metal specialists control critical supply nodes for premium diagnostic imaging connectors. REACH chemical disclosure expansion forces reformulation of legacy PVC cable jacketing compounds. The Lake Geneva region concentrates precision ferrule polishing capacity for fiber optic assemblies serving 7 Tesla MRI systems.
China
NMPA priority review channels for domestically manufactured Class III device components accelerate market access. Yangtze River Delta connector fabricators scale PCB integration for infusion pump board-level cost optimization. Shanghai medical device parks attract sterilization-compatible polymer molding investments.
Japan
PMDA sterilization compatibility testing limits qualified supplier pools to manufacturers with accelerated-aging datasets. Tokyo and Osaka medical device OEMs specify connectors exceeding 5,000 autoclave mating cycles. Domestic vendors leverage JIS standards alignment to defend procurement share against European competitors.
Global Medical Device Connectors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Hermetic sealing expertise concentrates among Alpine-region and Japanese incumbents, while PCB and disposable leadwire connectors fragment across Asian contract fabricators. Three archetypes dominate: integrated interconnect conglomerates with sensor portfolios, precision sealing specialists with clinical validation depth, and high-volume molders serving cost-optimized segments. Competitive moves center on sterilization-tracking RFID integration and preventive maintenance service bundling.
Among diversified interconnect conglomerates, TE Connectivity Ltd. and Amphenol Corporation exemplify scale-driven archetypes with broad sensor-interconnect portfolios. Swiss precision specialists Fischer Connectors and Lemo S.A. occupy positions defined by hermetic sealing heritage and surgical robotics qualification. Hirose Electric Co., Ltd. represents the Japanese validation-focused tier where PMDA-accelerated aging datasets create procurement stickiness. Molex sits within the mid-market PCB integration segment where board-level cost optimization governs purchasing decisions.
| Leading Market Players |
|---|
| Amphenol Corporation |
| TE Connectivity Ltd. |
| Molex |
| Fischer Connectors |
| Smiths Group |
| Hirose Electric Co., Ltd. |
| ITT Corporation |
| Lemo S.A. |
| Samtec |
| Others |
Supply & Pricing Matrix
Medical-grade PEEK and PSU resin feedstock moves from semiconductor packaging demand centers through Swiss precision molders into three-tier pricing structures across premium, standard, and economy levels, with sterilization-autoclave cycling tolerance separating diagnostic imaging contracts from disposable leadwire procurement.
Pricing Analysis
Distributor margins for hermetic sealing specialists absorb 15-25 point markups before reaching OEM procurement teams, while direct-to-manufacturer contracts for PCB connectors compress channel economics. Price differentiation rests on FDA validation tier and autoclave cycle rating, with German surgical robotics OEMs least sensitive and Asian disposable leadwire buyers most cost-focused. Cost compression in standard-grade molded connectors intensifies because resin feedstock competition from semiconductor packaging squeezes compounder margins.
Supply Chain Analysis
Single-source vulnerability sits with Alpine-region glass-to-metal sealing specialists serving diagnostic imaging OEMs, where Swiss and German facilities control precision ferrule polishing for fiber optic assemblies. Raw material dependencies span medical-grade PEEK resin, passivated stainless steel alloys, and halogen-free thermoplastic elastomers replacing legacy PVC compounds. Tariff exposure on Chinese-molded PCB connectors threatens infusion pump supply continuity. Distribution runs through authorized distributors for validated surgical connectors and direct OEM contracts for high-volume disposable leads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with hospital procurement teams unbundling preventive maintenance contracts and demanding sterilization-tracked intelligence as baseline specifications.
For Market Incumbents: Lock in long-term service agreements with United States health systems by embedding RFID sterilization tracking into connector housings, creating recurring revenue streams that resist price erosion from independent service organizations. Deepen backward integration into medical-grade polymer compounding to defend margin position against resin feedstock volatility from semiconductor packaging demand cycles. For New Entrants and Emerging Players: Independent service organizations represent the most penetrable channel partner type for aftermarket connector replacement contracts, particularly where United States hospital systems pursue operating expense optimization. Target CDSCO-harmonized India surgical device supply chains with pre-validated IMDRF-standard connectors, leveraging price-sensitive procurement patterns absent in German premium-tier markets. For Investors and Strategic Acquirers: Consolidation pressure builds where sterilization validation datasets create procurement stickiness exceeding 5,000 autoclave cycles, favoring acquisition of Japanese or Swiss specialists with PMDA-accelerated aging documentation. The inflection signal to watch is FDA interoperability mandate enforcement compressing development timelines for signal integrity revalidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Interoperability mandate compliance accelerates signal integrity revalidation for electrical safety protocols. |
| CE Marking Pathway | EU MDR clinical performance documentation requirements pull forward connector replacement cycles. |
| Hospital System Partnership | Preventive maintenance unbundling creates independent service organization channel access. |
| Software Companion Development | Sterilization cycle tracking embedded in RFID-enabled housings generates recurring asset management revenue. |
| Reimbursement Strategy | Diagnostic imaging capital budget cycles favor upgradeable connector architectures for MRI platforms. |
Research Methodology
Direct dialogue with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and surgical device OEM procurement leads grounded qualitative findings, cross-referenced against FDA 510(k) filings, EU MDR technical documentation databases, PMDA accelerated-aging test records, and hospital capital equipment procurement contracts. Bottom-up connector shipment analysis triangulated with top-down medical device production forecasts across the analysis window.
Segment-level outputs across product type, application, end user, and technology dimensions were generated through hierarchical modeling of sterilization protocol compatibility, signal integrity requirements, and equipment lifecycle duration. CAGRs were derived from regression analysis of historical replacement cycle data and forward projection of regulatory compliance deadlines. Industry-specific inputs included autoclave mating cycle degradation curves and fiber optic bandwidth scaling trajectories for 7 Tesla MRI systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wireless substitution rates in ambulatory monitoring, biocompatible polymer feedstock price volatility, and REACH chemical disclosure expansion forcing compound reformulation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Disposable Lancets Market
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
Airway Management Devices Market