
 China Contraceptive Devices Market | 2026-2036
China Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
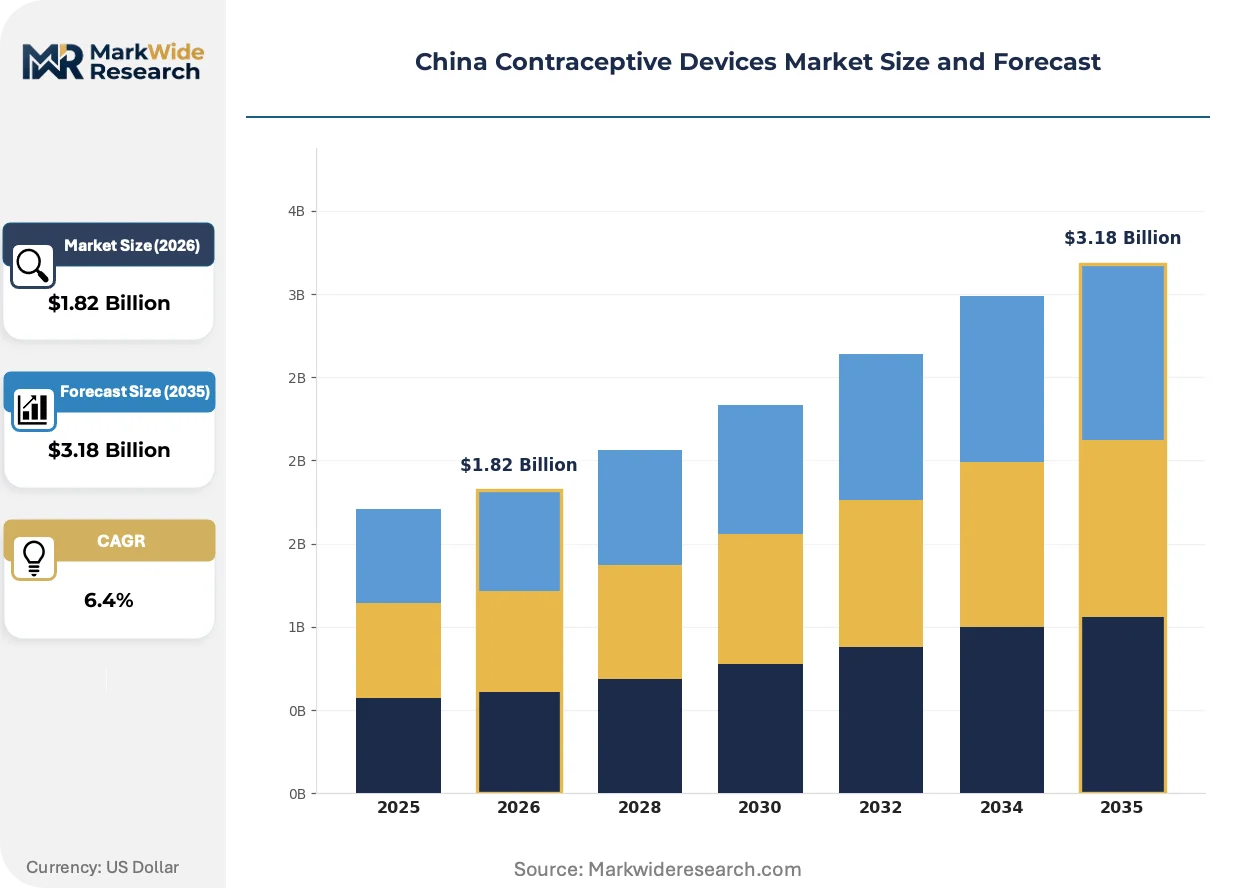
China Contraceptive Devices Market Outlook
Biodegradable polymer formulations and precision-molding automation is narrowing the performance gap between domestic and imported contraceptive devices. Okamoto leverages its polymer science heritage to sustain premium positioning in polyurethane condom segments. GUANGZHOU ICLEAR HEALTHCARE LIMITED anchors regional distribution through deep channel relationships with provincial hospital procurement consortia. Bayer Healthcare competes across hormonal and barrier categories with manufacturing scale that spans multiple therapeutic areas.
Contraceptive devices encompass barrier methods, intrauterine systems, implantable rods, and cervical caps engineered from latex, silicone, copper, or synthetic polymers to prevent fertilization through mechanical obstruction, spermicidal action, or localized hormone release. Intrauterine devices manufactured with copper wire or levonorgestrel cores deliver multi-year efficacy through uterine cavity placement requiring clinical insertion protocols. Condoms dominate volume flows due to over-the-counter accessibility and low unit economics, while contraceptive implants capture disproportionate margin pools through specialist-dependent insertion and removal procedures. Home use channels are expanding fastest as e-commerce platforms normalize discreet purchasing patterns for barrier and emergency contraceptive products.
NMPA device registration requirements and GB standards for latex and silicone biomaterials shape product approval timelines and manufacturing quality benchmarks for domestic and imported contraceptive devices. China's National Health Commission clinical service guidelines determine reimbursement eligibility and provider training mandates for long-acting reversible contraceptive insertion. Stakeholders must monitor evolving provincial centralized procurement rules and digital pharmacy licensing frameworks that will determine channel access economics across China's tiered urban hospital system.
Market Dynamics
Provincial centralized procurement reforms are compressing margin pools for contraceptive device manufacturers while simultaneously expanding volume access through tiered hospital networks. NMPA device registration timelines and GB biomaterial standards create asymmetric compliance burdens that favor domestic manufacturers with established regulatory affairs capabilities.
Growth Catalysts
- Long-acting reversible contraceptive guidelines:China's National Health Commission updated clinical service protocols expand reimbursement eligibility for intrauterine and implantable devices across urban hospital tiers.
- Guangdong and Jiangsu demand concentration:Coastal provinces with elevated per-capita healthcare expenditure and superior insurance coverage drive disproportionate procurement volumes for premium device categories.
- E-commerce platform normalization:Digital pharmacy licensing frameworks enable discreet home-channel purchasing for barrier and emergency contraceptive products, bypassing traditional retail stigma.
Market Restraints
- Latex and silicone input cost volatility:GB standards-compliant biomaterial sourcing faces price pressure from petroleum-derived polymer feedstock fluctuations and specialized medical-grade certification requirements.
- Import dependency in precision-molding equipment:Domestic manufacturers rely on German and Japanese automation systems for copper-wire IUD and hormonal implant fabrication, creating capex bottlenecks.
- NMPA registration friction:Device approval timelines for novel biodegradable polymer formulations extend 18-24 months longer than incremental latex barrier modifications, delaying product pipeline commercialization.
Strategic Opportunities
- Interior province hospital network expansion:Central and western China provinces currently underpenetrated in long-acting reversible contraceptive services present volume growth corridors as tier-3 and tier-4 cities upgrade family planning infrastructure.
- Dual carbon goals alignment:MEE sustainability mandates and MIIT green manufacturing incentives favor domestic producers developing biodegradable polymer alternatives to conventional silicone and latex barrier devices.
- Telemedicine integration:Digital health platforms are converging with contraceptive counseling services to enable remote prescription and home-delivery models for hormonal and barrier methods.
Industry Challenges
- Specialist insertion capability gaps:Clinical training programs for intrauterine and subdermal implant procedures lag behind device availability, constraining effective supply utilization in county-level hospitals.
- Provincial procurement consortium fragmentation:Divergent centralized bidding rules across 31 provincial-level jurisdictions force manufacturers to maintain multiple compliance and pricing configurations simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Contraceptive Devices Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condoms, Intrauterine Devices, Contraceptive Implants, Diaphragms End User: Hospitals, Clinics, Pharmacies, Home Use Distribution Channel: Online Retail, Offline Retail, Medical Supply Stores, Direct Sales Material: Latex, Polyurethane, Copper, Silicone |
| Companies Covered | DKT International, Okamoto, GUANGZHOU ICLEAR HEALTHCARE LIMITED, Shanghai Dahua Pharmaceutical Co. Ltd, Shandong Ming Yuan Latex Co. Ltd, Bayer Healthcare, Reckitt Benckiser, Teva Pharmaceutical Industries Ltd, Cooper Surgical Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Contraceptive Devices Market Strategic Shifts
Biodegradable material science and digital distribution infrastructure are converging to reshape competitive positioning across China's contraceptive device landscape. Manufacturers must adapt product portfolios and channel strategies to capture value from these structural shifts.
Precision-molding automation is digitizing quality control protocols for copper-wire intrauterine device fabrication. Tier-1 municipal hospital procurement consortia in Shanghai and Beijing are adopting these systems fastest, enabling real-time dimensional verification that compresses defect rates and reduces post-market surveillance liabilities for domestic manufacturers.
NMPA's updated GB standards for silicone and latex biomaterials are tightening extractables and leachables testing requirements. Domestic manufacturers with in-house polymer laboratories achieve compliance 8-12 months faster than import-dependent competitors, reshaping competitive access to provincial centralized procurement tenders.
Younger cohorts in coastal cities are displacing traditional pharmacy purchasing with subscription-based digital channels for barrier and emergency contraceptive products. E-commerce platforms with discreet packaging logistics and telemedicine-integrated prescription verification capture disproportionate margin pools from this behavioral pivot.
China Contraceptive Devices Market Segmentation
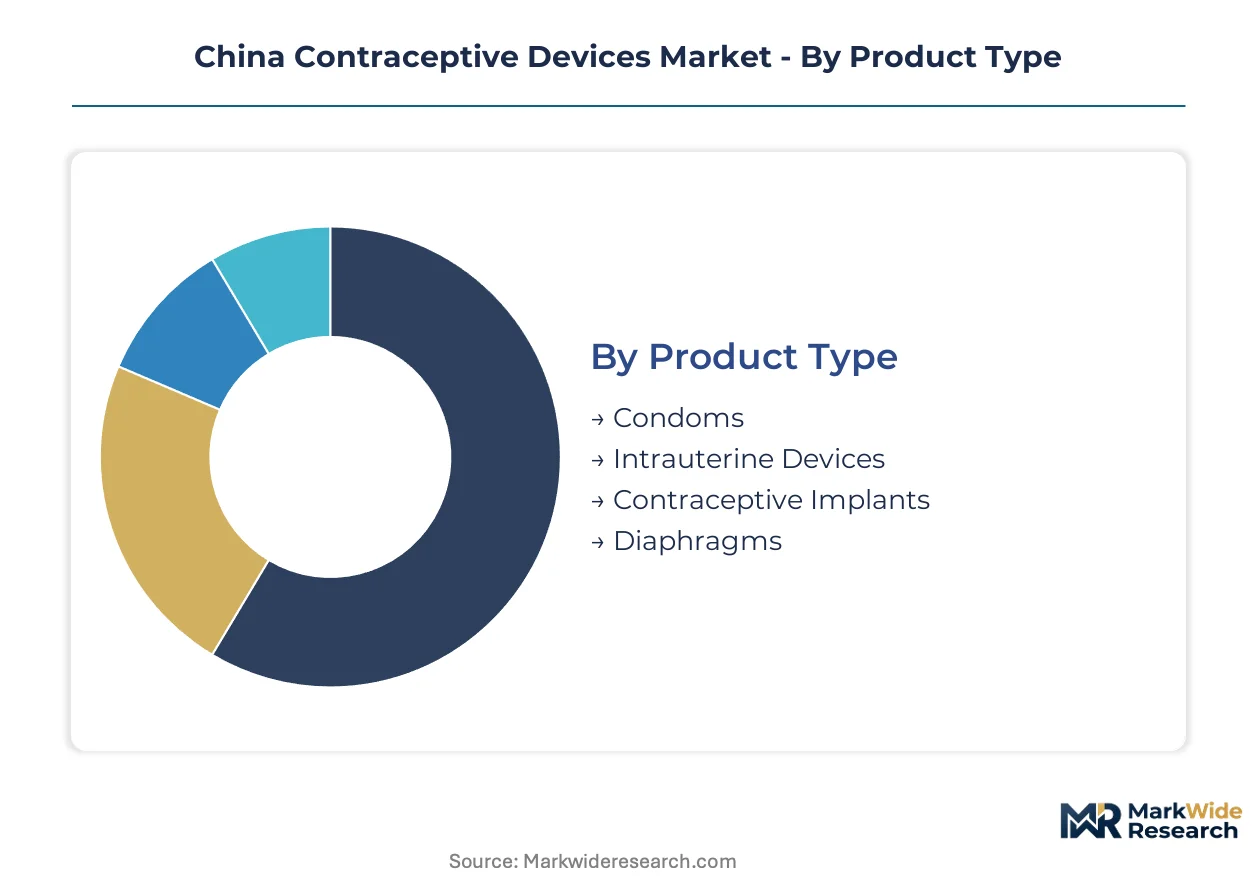
Segmentation in China's contraceptive devices market reveals distinct procurement rhythms and margin structures across product categories. Cycle-time variation between single-use disposables and multi-year implantables creates divergent inventory and distribution economics for manufacturers serving provincial hospital networks versus home-channel platforms.
Product Type:
Cycle times range from immediate consumption for barrier methods to 3-7 year replacement intervals for long-acting reversible devices, reshaping revenue recognition and customer relationship management across the portfolio.
- Condoms:Single-use latex or polyurethane barriers manufactured through automated dipping lines achieve the shortest replenishment cycles in the category. Guangdong province's urban hospital procurement consortia and digital pharmacy channels drive volume concentration, though per-unit margins compress under provincial centralized bidding rules.
- Intrauterine Devices:Copper-wire or levonorgestrel-releasing systems require clinical insertion protocols and deliver multi-year efficacy through uterine cavity placement. Jiangsu province's tier-2 municipal hospitals are expanding IUD service capacity fastest as NMPA clinical guideline updates broaden reimbursement eligibility for long-acting reversible contraceptive procedures.
- Contraceptive Implants:Subdermal rods releasing progestin hormones provide 3-5 year protection through minimally invasive insertion. Specialist-dependent placement constrains supply utilization in county-level facilities.
- Diaphragms:Reusable silicone barriers requiring proper fitting and user training. Limited penetration outside tier-1 coastal cities due to clinical counseling requirements.
Condoms anchor the volume base while intrauterine devices gain share at the steepest rate among long-acting reversible methods.
End User:
Procurement authority and reimbursement eligibility fragment across institutional settings, with provincial health commission guidelines determining which settings qualify for insurance-covered contraceptive services.
- Hospitals:Tier-1 and tier-2 municipal facilities dominate long-acting reversible contraceptive insertion volumes. NMPA device registration requirements and GB biomaterial standards shape tender participation eligibility for intrauterine and implantable device suppliers.
- Clinics:Community health service centers in Shanghai and Beijing are expanding family planning infrastructure fastest. Specialist insertion capability gaps constrain effective device utilization in county-level clinics.
- Pharmacies:Traditional retail channels face displacement from digital platforms for barrier and emergency contraceptive products.
- Home Use:E-commerce platforms with discreet packaging logistics capture disproportionate margin pools from younger cohorts in coastal cities.
Hospitals retain the highest-value procedural revenue while home use channels expand most quickly through telemedicine-integrated prescription models.
Distribution Channel:
Channel economics diverge sharply between regulated medical supply chains and consumer-facing digital platforms, with provincial licensing frameworks determining market access.
- Online Retail:Digital pharmacy licensing frameworks enable subscription-based purchasing for barrier methods. Discreet logistics and telemedicine prescription verification reshape competitive positioning.
- Offline Retail:Traditional pharmacy networks face volume pressure from platform normalization in coastal provinces.
- Medical Supply Stores:Institutional procurement consortia in Guangdong and Jiangsu concentrate demand for copper-wire IUD and hormonal implant inventory.
- Direct Sales:Manufacturer-to-hospital contracts dominate premium polyurethane condom and specialized implantable device segments.
Online retail captures the steepest growth trajectory while medical supply stores retain the highest-margin institutional contracts.
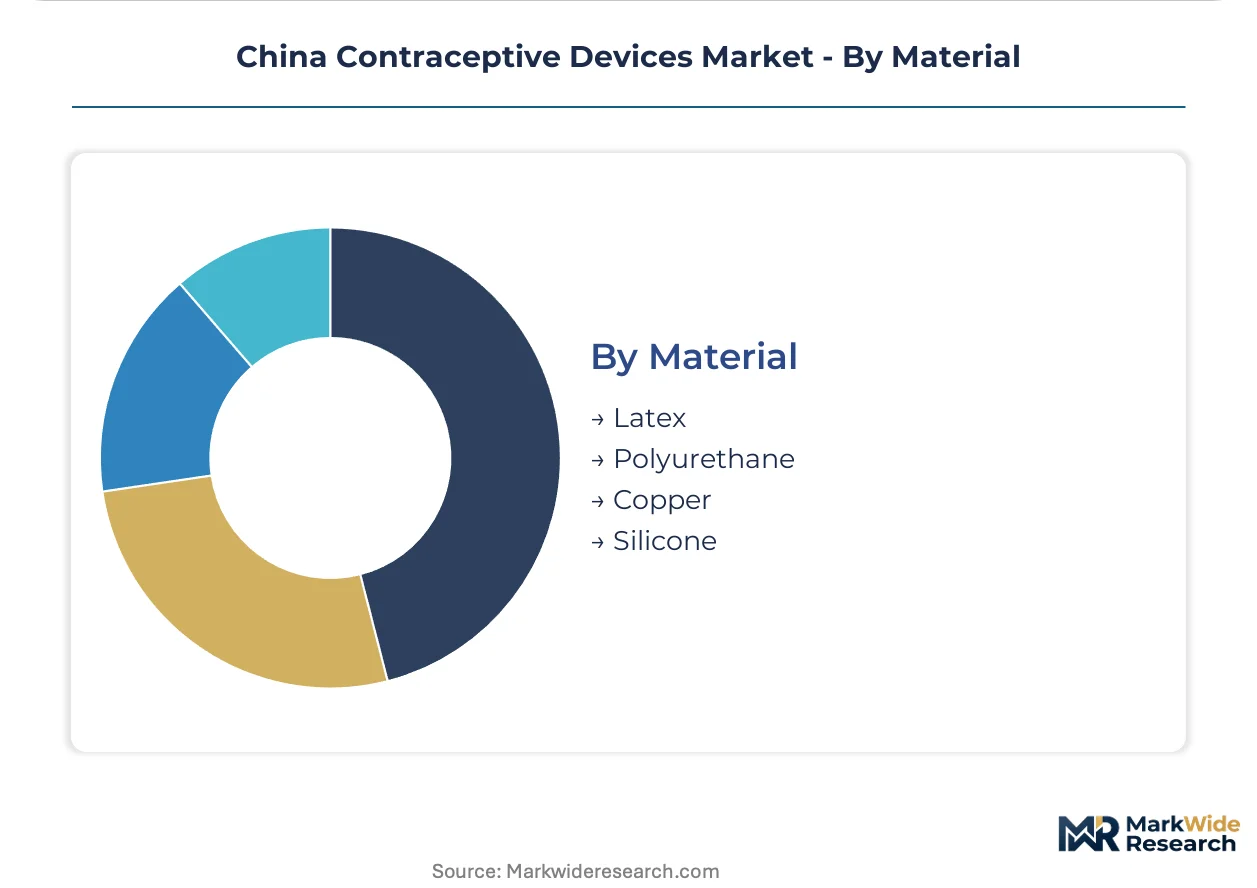
Material:
Biomaterial selection determines NMPA registration complexity, GB standards compliance timelines, and alignment with MEE sustainability mandates under dual carbon goals.
- Latex:Natural rubber barriers face extractables and leachables testing requirements under updated GB standards. Domestic manufacturers with in-house polymer laboratories achieve compliance 8-12 months faster than import-dependent competitors.
- Polyurethane:Synthetic polymer condoms command premium positioning through thinner profiles and hypoallergenic properties. Okamoto leverages polymer science heritage to sustain market share in this segment.
- Copper:Wire-wound intrauterine devices rely on precision-molding automation systems imported from Germany and Japan, creating capex bottlenecks for domestic manufacturers.
- Silicone:Medical-grade formulations for diaphragms and implantable rods face petroleum-derived feedstock price volatility and specialized certification requirements.
Latex retains volume dominance while polyurethane and biodegradable polymer alternatives climb fastest under green manufacturing incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan export precision-molding automation systems to Chinese domestic manufacturers fabricating copper-wire intrauterine devices, while coastal provinces concentrate procurement of finished contraceptive products through hospital network expansion.
Guangdong
Urban hospital procurement consortia in Guangzhou and Shenzhen drive volume concentration for polyurethane condoms and emergency contraceptive products. NMPA device registration requirements shape tender participation eligibility for imported barrier methods. The Pearl River Delta anchors domestic manufacturing clusters supplying latex and silicone formulations to tier-1 municipal facilities.
Jiangsu
Tier-2 municipal hospitals in Nanjing and Suzhou are expanding intrauterine device service capacity fastest among interior coastal provinces. China's National Health Commission clinical guideline updates broaden reimbursement eligibility for long-acting reversible contraceptive procedures in this region. Precision-molding automation adoption concentrates in Kunshan industrial zones serving copper-wire IUD fabrication.
Beijing
Central government procurement mandates from the National Health Commission originate regulatory frameworks that cascade to provincial implementations. GB standards for silicone and latex biomaterials undergo revision through technical committees headquartered in the capital. Beijing-Tianjin-Hebei hospital networks pilot telemedicine-integrated prescription verification for home-channel contraceptive delivery.
Shanghai
Community health service centers in Pudong and Xuhui districts are expanding family planning infrastructure fastest among tier-1 cities. MIIT green manufacturing incentives favor domestic producers developing biodegradable polymer alternatives in Songjiang industrial parks. Specialist insertion training programs for subdermal implants concentrate in municipal hospital networks here.
Sichuan
Chengdu anchors western China distribution corridors for barrier methods reaching underpenetrated county-level clinics. Provincial centralized procurement reforms in this interior market compress margin pools while expanding volume access through tier-3 and tier-4 city hospital upgrades. MEE sustainability mandates drive interest in biodegradable polymer sourcing from domestic manufacturers.
China Contraceptive Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent margin structures in China's contraceptive devices market. Hospital procurement consortia in coastal provinces concentrate demand for premium device categories, while e-commerce platforms capture home-channel volumes for barrier methods. Three archetypes dominate: multinational pharmaceutical conglomerates with cross-therapeutic manufacturing scale, domestic latex and polymer specialists with regional distribution depth, and precision-molding equipment-dependent fabricators facing capex bottlenecks. Competitive moves center on provincial centralized bidding compliance and telemedicine platform partnerships for prescription verification.
Among multinational players, Bayer Healthcare and Reckitt Benckiser occupy positions spanning hormonal and barrier categories with manufacturing scale across multiple therapeutic areas. Domestic specialists including GUANGZHOU ICLEAR HEALTHCARE LIMITED exemplify the regional distribution archetype through deep channel relationships with provincial hospital procurement consortia. Okamoto represents the premium polymer science segment leveraging heritage positioning in polyurethane condom categories. These named entities anchor competitive dynamics without exhausting the vendor landscape.
| Leading Market Players |
|---|
| DKT International |
| Okamoto |
| GUANGZHOU ICLEAR HEALTHCARE LIMITED |
| Shanghai Dahua Pharmaceutical Co. Ltd |
| Shandong Ming Yuan Latex Co. Ltd |
| Bayer Healthcare |
| Reckitt Benckiser |
| Teva Pharmaceutical Industries Ltd |
| Cooper Surgical Inc. |
| Others |
Value Chain & Pricing Dynamics
German and Japanese precision-molding equipment suppliers anchor upstream capex bottlenecks for copper-wire intrauterine device fabrication, concentrating margin capture in coastal hospital procurement consortia that control access to tier-1 municipal facilities. This upstream dependency reshapes where domestic manufacturers can compete on price versus where import-dependent players retain premium positioning.
Pricing Analysis
Current-generation polyurethane condoms command 40-60% premiums over standard latex barriers through hypoallergenic positioning, while next-generation biodegradable polymer formulations await NMPA registration timelines that delay commercial pricing. Three-tier pricing structure across premium polyurethane, standard medical-grade latex, and economy natural rubber barriers separates Okamoto's heritage positioning from domestic volume plays. Cost compression in economy latex tiers intensifies because provincial centralized bidding rules force manufacturers to absorb GB standards compliance investments. County-level clinics exhibit highest price sensitivity for long-acting reversible devices, whereas tier-1 municipal hospitals prioritize clinical efficacy over unit economics.
Supply Chain Analysis
Petroleum-derived polymer feedstock from South Korea, Japan, and domestic Chinese refineries feeds latex and silicone formulation plants concentrated in Guangdong and Jiangsu industrial zones. Copper wire for intrauterine devices draws from Chilean and Peruvian mining output processed through German drawing mills, creating single-source vulnerability for domestic IUD fabricators. Distribution runs through provincial hospital procurement consortia for implantable devices, while e-commerce platforms with captive logistics networks capture barrier method volumes in coastal cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA registration entrenchment creates defensive moats for established domestic manufacturers with in-house polymer laboratories, as 18-24 month approval timelines for novel formulations lock out speculative entrants lacking regulatory affairs depth.
For Market Incumbents: Harden provincial procurement consortium relationships through dedicated regulatory affairs teams that compress GB standards compliance timelines by 8-12 months versus import-dependent competitors. Expand precision-molding automation capacity in Kunshan and Songjiang industrial zones to reduce German and Japanese equipment dependency. Prioritize biodegradable polymer R&D alignment with MEE sustainability mandates under dual carbon goals. For New Entrants and Emerging Players: Build out telemedicine-integrated prescription verification platforms targeting younger cohorts in coastal cities where discreet home-channel purchasing displaces traditional pharmacy stigma. Target Sichuan and western interior provinces currently underpenetrated in long-acting reversible contraceptive services. Anchor go-to-market strategy through digital pharmacy licensing frameworks that bypass hospital procurement consortium fragmentation. For Investors and Strategic Acquirers: Capital is best deployed toward domestic manufacturers with backward integration into medical-grade polymer formulation and established NMPA regulatory affairs capabilities. Long-term viability hinges on positioning for biodegradable material transitions as GB standards tighten extractables testing. Watch for MIIT green manufacturing incentive announcements as inflection indicators for sustainable polymer adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Device Registration Acceleration | Domestic laboratories achieving GB compliance 8-12 months faster reshape tender access. |
| Biodegradable Polymer Manufacturing Scale-Up | MEE sustainability mandates favor producers with green chemistry capabilities in Songjiang. |
| Telemedicine Platform Partnership | Digital prescription verification captures margin pools from coastal city behavioral pivots. |
| Provincial Procurement Consortium Expansion | Deep channel relationships with Guangdong and Jiangsu hospital networks defend volume. |
| Precision-Molding Automation Investment | Reducing German and Japanese equipment dependency lowers capex bottlenecks for IUD fabrication. |
Study Parameters
The analysis maps barrier methods, intrauterine systems, implantable rods, and cervical caps, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and NMPA regulatory affairs specialists. Primary fieldwork combined with secondary validation from NMPA device registration databases, GB standards technical committees, provincial centralized procurement tender records, and hospital procurement consortium disclosures. Bottom-up volume modeling triangulated against top-down healthcare expenditure benchmarks across the analysis window.
Assumption sets held NMPA registration timelines and GB standards compliance requirements fixed while varying provincial procurement reform intensity and e-commerce platform penetration rates. Segmentation dimensions modeled include product type, end-user setting, distribution channel, and biomaterial composition. CAGRs derived from regression analysis against per-capita healthcare expenditure and insurance reimbursement coverage proxies, with specific inputs from long-acting reversible contraceptive guideline update schedules and dual carbon goal implementation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational pharmaceutical conglomerates or accelerated biodegradable polymer breakthroughs by domestic specialists would shift outcomes beyond projected ranges. Cross-checking against National Health Commission family planning service statistics and MIIT green manufacturing incentive disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Pills Technology Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Global Medical Devices Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Artificial Disc Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Kidney Stone Management Devices Market