
 Medical Thermometer Market | 2026-2036
Medical Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Thermometer Market Intelligence
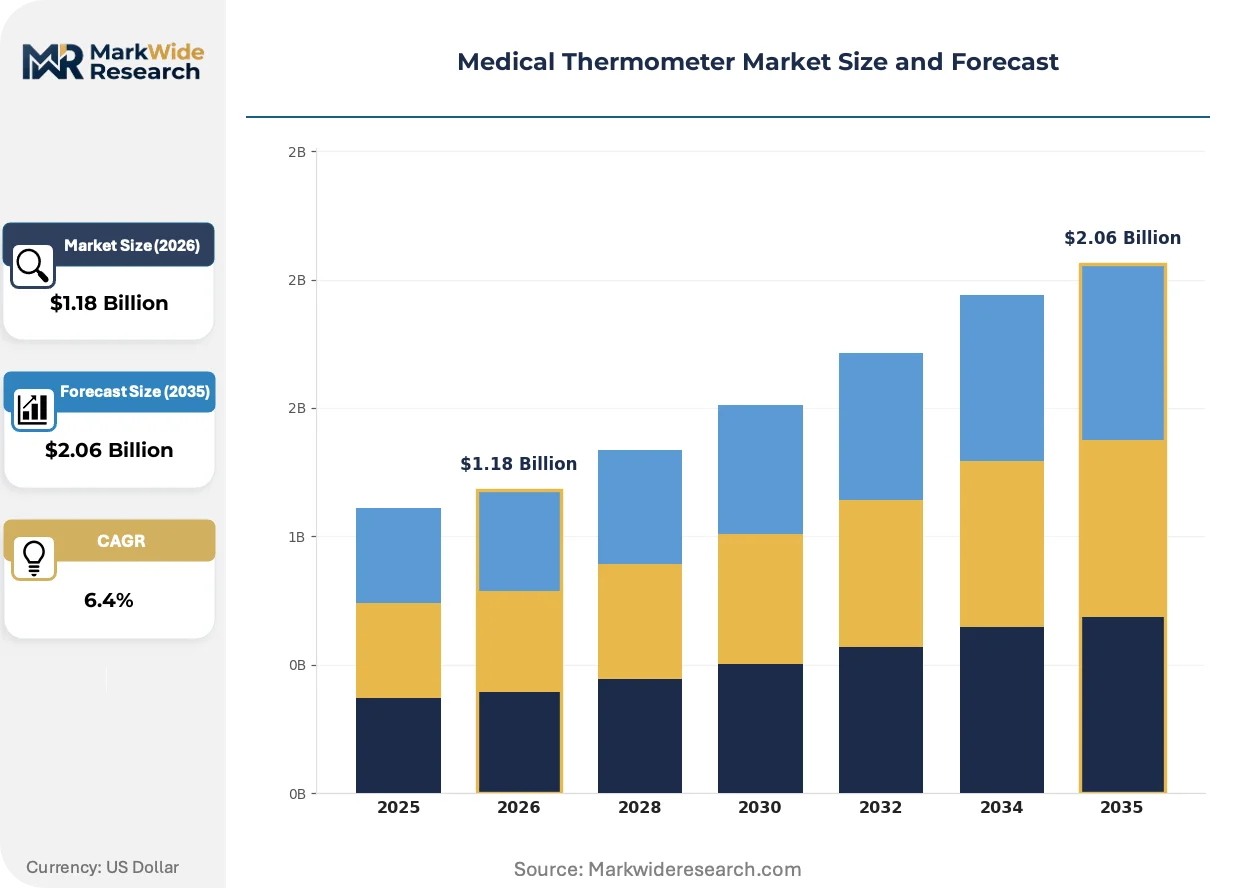
The ISO 13485 quality management standard for medical devices is collapsing the distinction between consumer-grade and clinical-grade temperature monitoring. This forces all manufacturers to adhere to higher production and documentation protocols. Terumo Corporation specializes in high-precision digital thermometers for hospital settings, commanding a premium. In contrast, Microlife Corporation leverages its established brand and distribution network to compete effectively in the rapidly expanding home healthcare and retail pharmacy channels.
A medical thermometer is a device engineered to measure human or animal body temperature with high accuracy, typically within a tolerance of ±0.1°C. Its primary purpose is to aid in the diagnosis and monitoring of fever and other medical conditions. The infrared product type represents the fastest-growing segment, driven by the need for non-contact measurement in public health settings. While hospitals constitute the largest end-user category by volume, the homecare providers segment shows significant expansion due to telehealth integration.
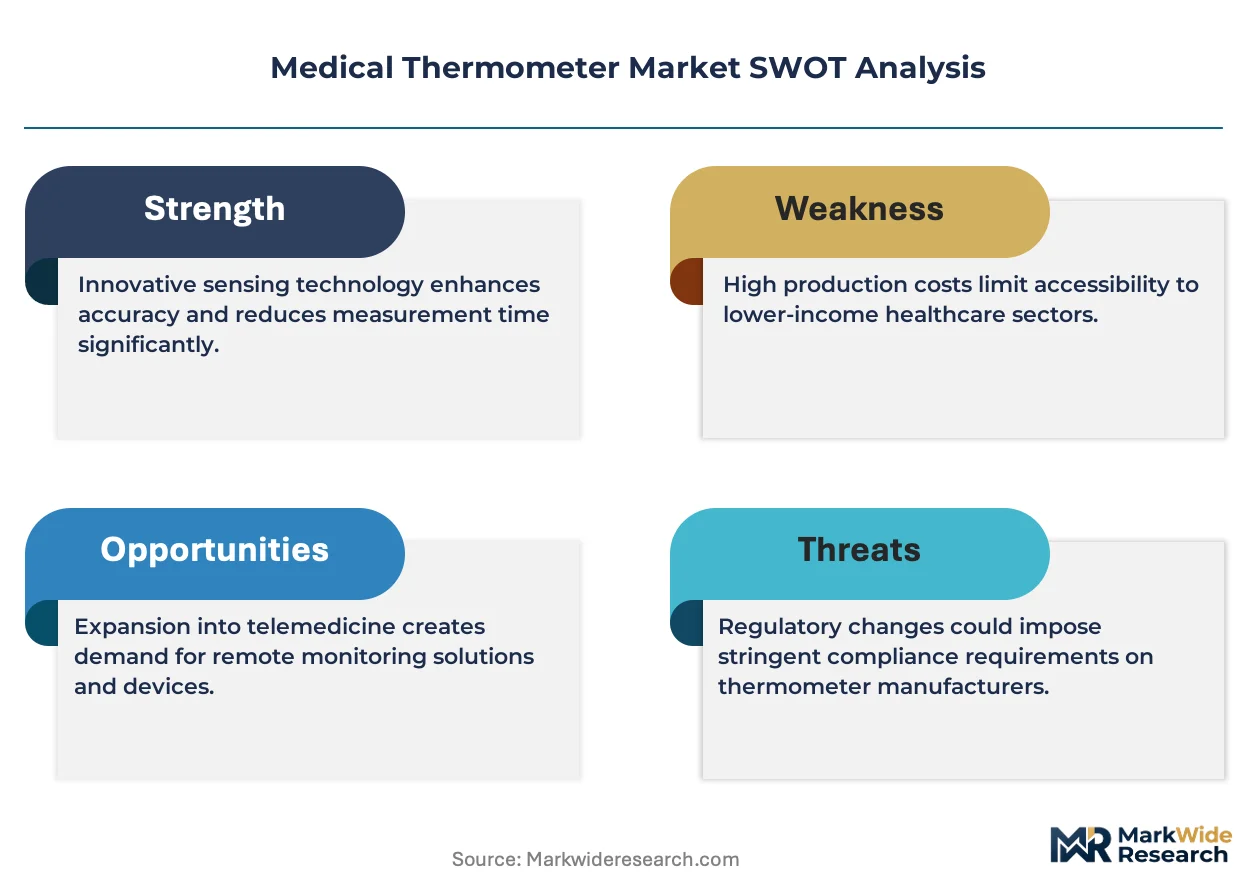
Regulatory frameworks from the US FDA, the European Union's MDR, and China's NMPA mandate stringent accuracy, material safety, and performance validation. These regulations directly influence device design, manufacturing processes, and global market access for all thermometer types. Future competitive advantage will depend on integrating smart connectivity features for telehealth platforms while navigating the complex and evolving compliance landscape.
Market Dynamics
The convergence of consumer and clinical device standards, driven by stringent quality management systems like ISO 13485, is the central force shaping the medical thermometer market. This harmonization elevates manufacturing and validation requirements for all market participants.
Growth Catalysts
- Home Healthcare Expansion:The integration of temperature monitoring into telehealth and remote patient management platforms stimulates demand for user-friendly, connected thermometers for at-home use.
- Regulatory Modernization:Upgraded frameworks, including the EU's Medical Device Regulation (MDR), mandate higher accuracy and safety, compelling healthcare providers to replace legacy devices with compliant models.
- Public Health Investment:Developing economies, particularly in Asia, are expanding public health surveillance and clinical infrastructure, creating sustained demand for diagnostic tools like medical thermometers.
Market Restraints
- Rising Compliance Costs:Adherence to stricter standards like ISO 13485 increases expenses related to documentation, clinical validation, and quality control, pressuring margins for all manufacturers.
- Component Supply Concentration:The supply of critical electronic components, such as thermopile sensors for infrared models, is heavily concentrated in East Asia, creating potential price volatility and supply chain risks.
- Low-End Substitution:In non-critical consumer applications, inexpensive alternatives like disposable fever indicator strips can serve as a substitute for basic digital thermometers, capping price points.
Strategic Opportunities
- Smart Device Integration:Embedding Bluetooth or Wi-Fi connectivity to link thermometers with digital health applications and electronic health records presents a significant value-add opportunity, especially for telehealth providers.
- Veterinary and Agnostic Applications:Non-contact infrared technology can be adapted for new verticals such as veterinary medicine and food safety inspection, where rapid, hygienic temperature checks are beneficial.
- Emerging Market Penetration:Healthcare systems across Africa and Latin America remain largely underpenetrated, offering long-term growth potential as primary care and hospital infrastructure develops.
Industry Challenges
- Multi-Jurisdictional Approvals:Navigating disparate and lengthy regulatory validation pathways simultaneously across the US FDA, EU MDR, and China's NMPA creates significant operational delays and costs for market entry.
- Data Security and Interoperability:For connected devices, ensuring data privacy in line with regulations like HIPAA and achieving seamless integration with fragmented electronic health record systems is a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Thermometer Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Infrared, Mercury, Disposable, Glass, Electronic Application: Clinical Diagnostics, Veterinary Medicine, Home Healthcare, Pharmaceutical Research, Occupational Health, Public Health Surveillance End User: Hospitals, Diagnostic Laboratories, Clinics, Veterinary Centers, Homecare Providers, Research Institutions Technology: Thermistor, Thermocouple, Infrared Sensor, Resistance Temperature Detector, Bi-metallic, Semiconductor Sensor |
| Companies Covered | Medtronic, Cardinal Health, McKesson Corporation, Terumo Corporation, Exergen Corporation, Microlife Corporation, American Diagnostic Corporation, Omron Healthcare, Braun GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Thermometer Market Strategic Shifts & Innovations
The evolution of medical thermometers is reshaping the device's role from a standalone diagnostic tool into an integrated data point within broader digital health ecosystems. This shift emphasizes connectivity, continuous monitoring capabilities, and adherence to higher regulatory benchmarks across all product tiers.
MEMS-based thermopile sensors provide the core technology for non-contact infrared temperature measurement. Home healthcare providers and wearable technology firms are rapidly incorporating these sensors for continuous monitoring applications. This technology is miniaturizing the essential sensing components, enabling their integration into discreet form factors like ear-worn devices and skin patches for passive, uninterrupted data collection.
The European Union's Medical Device Regulation (MDR) establishes more rigorous requirements for clinical evidence, risk management, and post-market surveillance. This policy effectively eliminates the distinction between consumer and professional devices sold in the EU, increasing the validation burden. The homecare segment is most affected, as manufacturers must now fund clinical-grade testing to maintain CE marking and market access.
A notable behavioral shift is underway as institutional buyers move from simple, one-off device purchases toward platform-centric procurement. Large hospital networks now favor thermometers that integrate with their existing remote patient monitoring and telehealth systems, displacing unconnected, standalone models. This trend is most pronounced in North American and European healthcare markets where value-based care initiatives are prevalent.
Medical Thermometer Market Segmentation
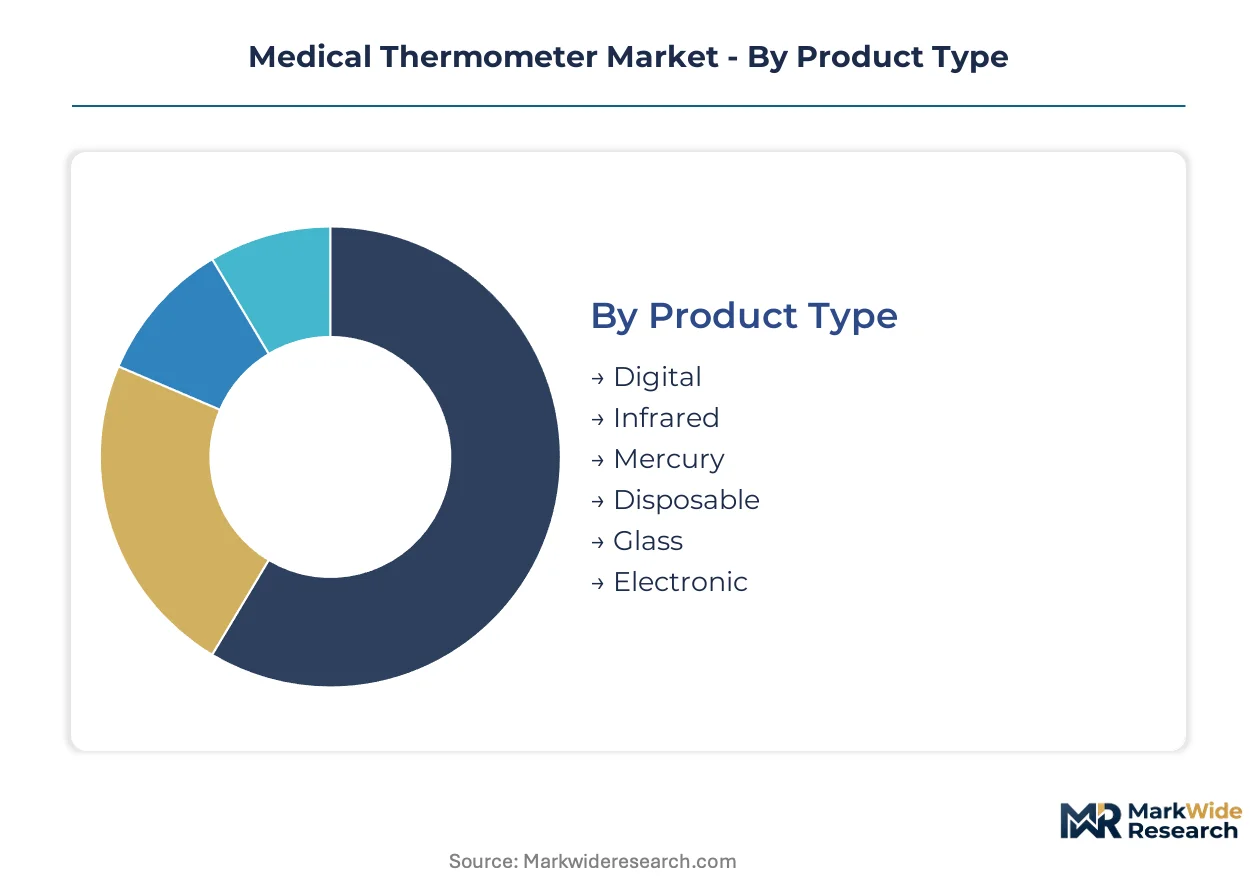
The medical thermometer market exhibits diverse characteristics across its various segments, reflecting the specialized requirements of clinical, home, and public health settings. Understanding these segment dynamics is crucial for manufacturers to align product development with regulatory standards and evolving end-user demands.
Product Type:
Regulatory distinctions, particularly around accuracy and material safety, heavily influence the design and market access for various medical thermometer product types.
- Digital:These electronic devices use thermistors to convert temperature changes into electrical signals, displaying readings on a digital screen; demand is widespread in both clinical and home settings due to their reliability and ease of use, particularly for routine fever monitoring.
- Infrared:Utilizing MEMS-based thermopile sensors, these thermometers measure thermal radiation emitted by the body, enabling non-contact temperature assessment; their rapid, hygienic operation is driving significant demand in public health surveillance and home healthcare applications in countries like India and China.
- Mercury:Traditional glass thermometers containing mercury, these devices are being phased out globally due to environmental and safety concerns, with regulatory bodies like the EU's MDR restricting their use.
- Disposable:Single-use thermometers, often plastic strips or patches, offer hygienic, low-cost options for infection control in clinical environments.
- Glass:Non-mercury glass thermometers, typically filled with gallium, provide a safe alternative to traditional mercury models, adhering to stricter environmental guidelines.
- Electronic:A broad category encompassing digital and infrared types, these devices leverage electronic components for precise and rapid temperature measurement.
Established volume favors Digital thermometers; emerging adoption favors Infrared models.
Application:
The varying needs of distinct user groups drive the specific application demands for medical thermometers across the healthcare spectrum.
- Home Healthcare:This segment includes devices used by individuals for personal health monitoring and remote patient management, with demand spurred by telehealth integration and the need for user-friendly, connected devices.
- Clinical Diagnostics:Encompasses the use of thermometers in hospitals and clinics for accurate patient assessment and diagnosis, forming the largest volume segment due to routine medical procedures.
- Public Health Surveillance:Involves large-scale temperature screening in public spaces and during health crises, utilizing non-contact infrared devices for rapid, efficient detection.
- Veterinary Medicine:Thermometers designed for animal temperature measurement, crucial for diagnosing illness and monitoring health in various animal species.
- Occupational Health:Used in workplaces to monitor employee health, especially in environments requiring strict health protocols or exposure to temperature extremes.
- Pharmaceutical Research:Employed in laboratories for precise temperature control and monitoring during drug development and testing processes.
The utility of medical thermometers spans from critical diagnostic support to proactive health monitoring, reflecting diverse application priorities.
End User:
The procurement scale and operational requirements of different end-user segments dictate the volume and specifications of medical thermometers acquired.
- Hospitals:Represent the largest end-user segment, acquiring high volumes of clinical-grade thermometers for inpatient care, emergency services, and surgical settings, often favoring integrated monitoring systems.
- Homecare Providers:This segment includes individuals and agencies providing care at home, driving demand for accessible, easy-to-use, and often connected thermometers for remote patient management.
- Diagnostic Laboratories:Utilize specialized thermometers for accurate temperature control in analytical processes and sample storage, ensuring test integrity.
- Clinics:Purchase thermometers for routine patient check-ups and minor procedures, prioritizing reliability and cost-effectiveness for outpatient services.
- Veterinary Centers:Acquire durable and accurate thermometers specifically designed for animal use, supporting diagnosis and health management in pets and livestock.
- Research Institutions:Employ highly precise thermometers for controlled experiments and scientific studies, often requiring specialized calibration and data logging capabilities.
While institutional settings remain primary purchasers, the shift towards decentralized care is reshaping demand patterns among end users.
Technology:
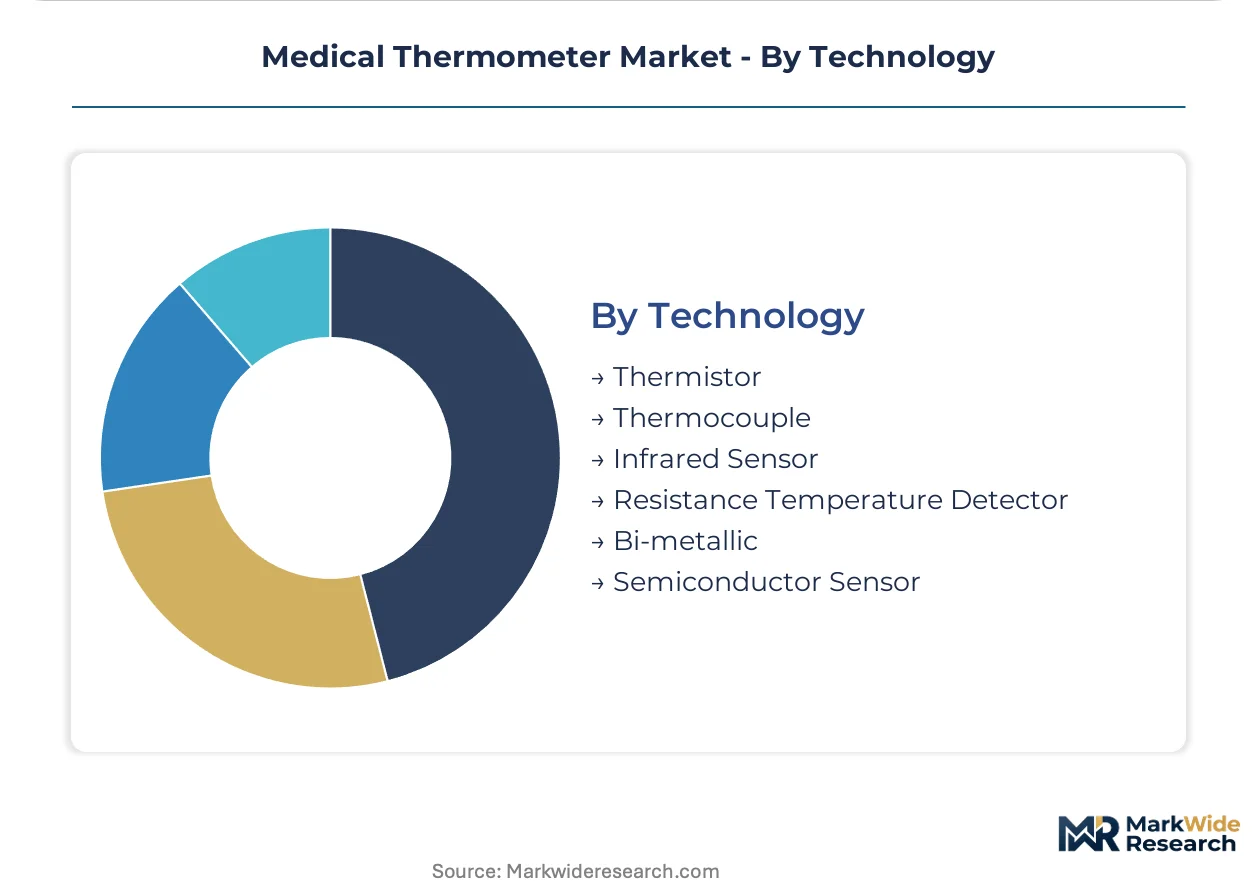
The underlying sensor technologies determine the precision, response time, and non-contact capabilities essential for modern temperature measurement devices.
- Infrared Sensor:This technology uses a thermopile to detect thermal radiation, enabling non-contact and rapid temperature measurement, which is critical for public health and home care in regions like China.
- Thermistor:A type of resistor whose resistance varies significantly with temperature, providing high accuracy and fast response times for digital thermometers, widely adopted in both clinical and consumer products.
- Thermocouple:Composed of two dissimilar metals, this sensor generates a voltage proportional to temperature differences, suitable for industrial and some medical applications requiring broad temperature ranges.
- Resistance Temperature Detector:RTDs measure temperature by correlating electrical resistance with temperature, offering high accuracy and stability, often used in laboratory and industrial settings.
- Bi-metallic:These sensors utilize two different metals bonded together that expand at different rates when heated, causing a mechanical movement; they are generally less precise for medical use but are robust.
- Semiconductor Sensor:Integrated circuit-based sensors that provide digital temperature outputs, offering good linearity and ease of integration into electronic devices.
Advancements in sensor technology are continually improving accuracy and enabling new form factors for medical thermometer applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upgraded regulatory frameworks globally are compelling healthcare providers to replace legacy devices, driving demand for compliant medical thermometers. This modernization effort aligns with public health investments in developing economies. Demand for diagnostic tools is expanding in key markets worldwide.
United States
Telehealth integration and remote patient management platforms drive significant demand for connected thermometers in the United States. The US FDA mandates stringent accuracy and performance validation, influencing device design and market access. Boston's biotech hub is seeing increased development of connected health devices for home healthcare applications.
Germany
Germany's high-quality medical infrastructure and aging population sustain a strong demand for advanced diagnostic tools. The EU's Medical Device Regulation (MDR) sets rigorous safety and performance criteria, affecting all thermometer manufacturers. The MedTech cluster in Tuttlingen focuses on precision manufacturing for clinical-grade instruments and components.
China
Public health infrastructure upgrades and the need for non-contact measurement fuel demand in China. China's NMPA mandates strict material safety and performance validation for all medical devices. Shenzhen's electronics manufacturing base is a key center for infrared thermometer production and innovation.
India
Expanding public health surveillance and the rapid adoption of home healthcare solutions stimulate demand in India. India's CDSCO is strengthening medical device regulations to ensure product quality and patient safety. The medical device parks in Andhra Pradesh are attracting investment for domestic manufacturing capabilities.
Japan
Precision diagnostics and advanced hospital settings drive consistent demand for high-accuracy thermometers in Japan. Japan's PMDA ensures high standards for medical device approval and post-market surveillance. Tokyo's research institutions collaborate on miniaturized sensor technologies for medical applications and wearables.
Medical Thermometer Market Key Industry Players
Player mix skews toward established medical device manufacturers and specialized diagnostics firms. The market exhibits a tiered structure, with premium clinical-grade offerings alongside more accessible home healthcare solutions. Strategic archetypes include high-precision innovators and volume-driven consumer brands. Portfolio diversification into connected health platforms and geographic expansion into developing markets are dominant competitive moves.
Within the high-precision clinical segment, Terumo Corporation represents a specialist in advanced digital thermometers for hospital settings, often commanding a premium. Microlife Corporation occupies a position as a volume-driven consumer brand, leveraging its established distribution for home healthcare and retail pharmacy channels. Japanese-based Omron Healthcare exemplifies a broader healthcare technology company, integrating temperature monitoring into comprehensive health management systems and connected health platforms. These companies anchor market activity across distinct segments, driving innovation in both clinical and consumer applications.
| Leading Market Players |
|---|
| Medtronic |
| Cardinal Health |
| McKesson Corporation |
| Terumo Corporation |
| Exergen Corporation |
| Microlife Corporation |
| American Diagnostic Corporation |
| Omron Healthcare |
| Braun GmbH |
| Others |
Cost & Logistics Intelligence
A typical 12-week lead time for specialized thermopile sensors from East Asia directly influences the pricing power of manufacturers, limiting their ability to rapidly adjust to demand spikes and creating a tiered cost structure for components that impacts final product prices.
Pricing Analysis
Certification level (ISO 13485, EU MDR compliance) creates the primary spread in medical thermometer pricing. The per-unit transactional model dominates market exchanges for both clinical and home-use devices. Brand premium, particularly for established names like Terumo Corporation in hospital settings, allows for higher price points. Pricing pressure stems from rising regulatory compliance costs, compelling manufacturers to invest heavily in validation and quality control. The home healthcare segment, often served by brands like Microlife Corporation, exhibits the highest price sensitivity, while hospitals prioritize accuracy and integration over cost.
Supply Chain Analysis
Component lead times for specialized thermopile sensors from East Asia anchor the entire supply chain for infrared thermometers. Geographic supply concentration for critical electronic components, such as MEMS-based thermopile sensors and microcontrollers, centers heavily in China and Japan. This concentration creates a structural risk of commodity price volatility and potential supply chain disruptions. Downstream distribution runs through a multi-channel model, encompassing direct sales to hospitals, partnerships with retail pharmacy networks, and online platforms for homecare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated connectivity expertise and regulatory navigation capabilities present a significant scarcity in this evolving market, limiting the ability of many players to capitalize on digital health trends.
For Market Incumbents:
Shield core clinical market share by deepening vertical integration into specialized sensor manufacturing. Acquire software firms specializing in telehealth integration to enhance platform offerings and data analytics. This directly counters the threat from new entrants focusing solely on smart connectivity. Invest in R&D for miniaturization and non-contact accuracy, ensuring compliance with evolving regulatory benchmarks like the EU MDR.
For New Entrants and Emerging Players:
A service-layer gap exists in accessible, connected temperature monitoring solutions for remote patient management. Target underpenetrated emerging markets in Africa and Latin America, where basic healthcare infrastructure is expanding. Focus on developing user-friendly, connected home healthcare devices that integrate with existing digital health ecosystems. Partnering with telehealth platforms offers a direct go-to-market angle for rapid adoption.
For Investors and Strategic Acquirers:
Long-term, this sits as a platform-enabler play because medical thermometers are transitioning from standalone devices to integrated data points within digital health ecosystems. Target specialized sensor manufacturers or software developers with strong health data integration capabilities. A key signal to watch for inflection is increasing reimbursement for remote patient monitoring services, validating the value of connected diagnostic tools.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Enhances data utility for remote patient monitoring and clinical decision-making across healthcare systems. |
| ISO 13485 Certification Upgrade | Ensures global market access and compliance with stringent medical device regulations from bodies like the FDA. |
| MEMS Sensor R&D Investment | Drives miniaturization and non-contact accuracy for next-generation devices, supporting public health surveillance. |
| Emerging Market Distribution Partnerships | Expands reach into underpenetrated healthcare systems in Asia and Africa, leveraging local networks. |
| Data Security Protocol Development | Builds trust and ensures compliance with patient privacy regulations like HIPAA for connected devices. |
Research Approach
A standing panel of clinicians, hospital purchasing managers, biomedical engineers, and telehealth providers provided ongoing calibration for market trends and validation of demand drivers. This primary input was combined with extensive secondary research, including EU MDR guidance documents, US FDA device approval records, and China NMPA regulations, to triangulate market dynamics and ensure comprehensive coverage.
Consistency checks against external benchmarks validated the analytical framework approach across the analysis window. Segmentation dimensions modeled included product type, application, end-user, technology, and regional regulatory environment. Compound annual growth rates were derived from historical trends and projected shifts in public health investment and telehealth adoption rates over the projection horizon.
Material uncertainties — unforeseen regulatory shifts, major supply chain disruptions, or rapid technological obsolescence — sit outside the modeled envelope. Forecasts reflect assumptions documented through the research process. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Defibrillators Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Asthma Spacers Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market