
 Global Gastrointestinal Devices Market | 2026-2036
Global Gastrointestinal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastrointestinal Devices Market Analysis
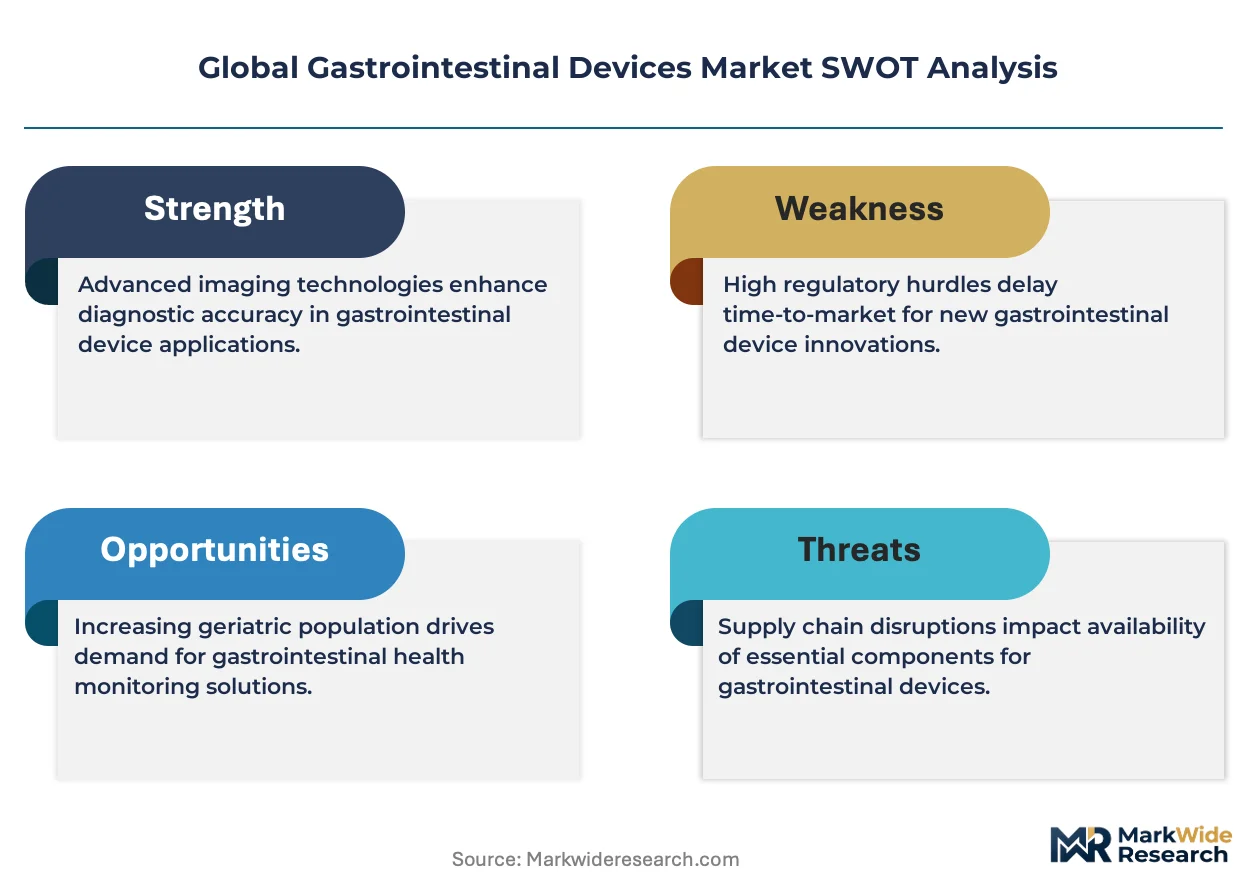
Aftermarket service revenue is tilting toward OEM-controlled refurbishment networks as hospitals seek to extend capital equipment life cycles. Olympus Corporation dominates factory-authorized endoscope repair programs across North America and Europe. Boston Scientific Corporation competes through proprietary sterilization validation protocols that lock in recurring service contracts.
Gastrointestinal devices encompass flexible endoscopes, electrosurgical instruments, and capsule-based imaging systems typically constructed from medical-grade polymers, fiber-optic bundles, and miniaturized sensor arrays designed for luminal visualization and tissue intervention. These instruments serve the primary commercial purpose of enabling minimally invasive diagnostic and therapeutic procedures within the esophageal, gastric, colonic, and biliary tracts. Endoscopes command the largest installed base and generate substantial recurring revenue through reprocessing consumables and repair cycles. Wireless capsule endography represents the fastest-expanding technology segment as patient preference shifts toward sedation-free examination protocols.
FDA 510(k) clearance requirements and EMA Medical Device Regulation standards govern biocompatibility, electrical safety, and reprocessing validation across all marketed devices. Japan's PMDA enforces additional sterilization efficacy benchmarks that shape product design specifications for Asia-Pacific distribution. Stakeholders must monitor evolving regulatory divergence between FDA and EU MDR reprocessing requirements when configuring global manufacturing and service footprints.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around single-source endoscope reprocessing contracts, compressing supplier margins while locking in decade-long service dependencies. This concentration dynamic favors OEMs with captive refurbishment networks over independent service organizations.
Growth Catalysts
- Aging Demographics:Japan's super-aged population and Germany's 65-plus cohort expansion drive procedural volume for colorectal screening and therapeutic interventions. Hospital systems in both countries are expanding endoscopy suite capacity.
- FDA Reprocessing Mandates:The FDA's enhanced surveillance of duodenoscope-related infection outbreaks has tightened sterilization validation requirements. This regulatory pressure accelerates capital replacement cycles for non-compliant equipment.
- Wireless Capsule Systems:Pill-based imaging platforms eliminate sedation risks and recovery room occupancy. Ambulatory surgery centers in the United States are prioritizing these devices to maximize throughput per clinical hour.
Market Restraints
- Polymer Supply Concentration:Medical-grade fluoropolymers for flexible endoscope sheathing concentrate among German and Japanese chemical suppliers. Disruptions propagate directly into OEM production schedules.
- EU MDR Transition Costs:The European Medical Device Regulation's expanded clinical evidence requirements impose substantial documentation burdens on legacy product lines. Smaller manufacturers face portfolio rationalization.
- Reusable Instrument Durability:Electrosurgical accessories degrade through repeated autoclave cycles, forcing premature retirement. This technical limitation inflates per-procedure supply costs beyond budgeted forecasts.
Strategic Opportunities
- India's Diagnostic Infrastructure:The country's national health mission is expanding endoscopy access to district hospitals. Manufacturers establishing local service partnerships capture first-mover positioning in an underpenetrated market.
- Artificial Intelligence Integration:Real-time polyp detection algorithms are converging with standard endoscope video processors. This technology pairing creates premium pricing tiers for computer-assisted diagnostic platforms.
- Direct-to-Hospital Distribution:Bypassing traditional medical device distributors through e-procurement portals reduces channel markups. Several United States health systems now mandate digital purchasing for consumable categories.
Industry Challenges
- Biomedical Technician Shortage:Complex endoscope repair demands specialized fiber-optic and electronic troubleshooting skills. Hospital in-house teams lack depth to handle precision refurbishment.
- Legacy System Interoperability:New wireless capsule platforms must integrate with existing PACS infrastructure. DICOM conformance testing extends product launch timelines by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastrointestinal Devices Market |
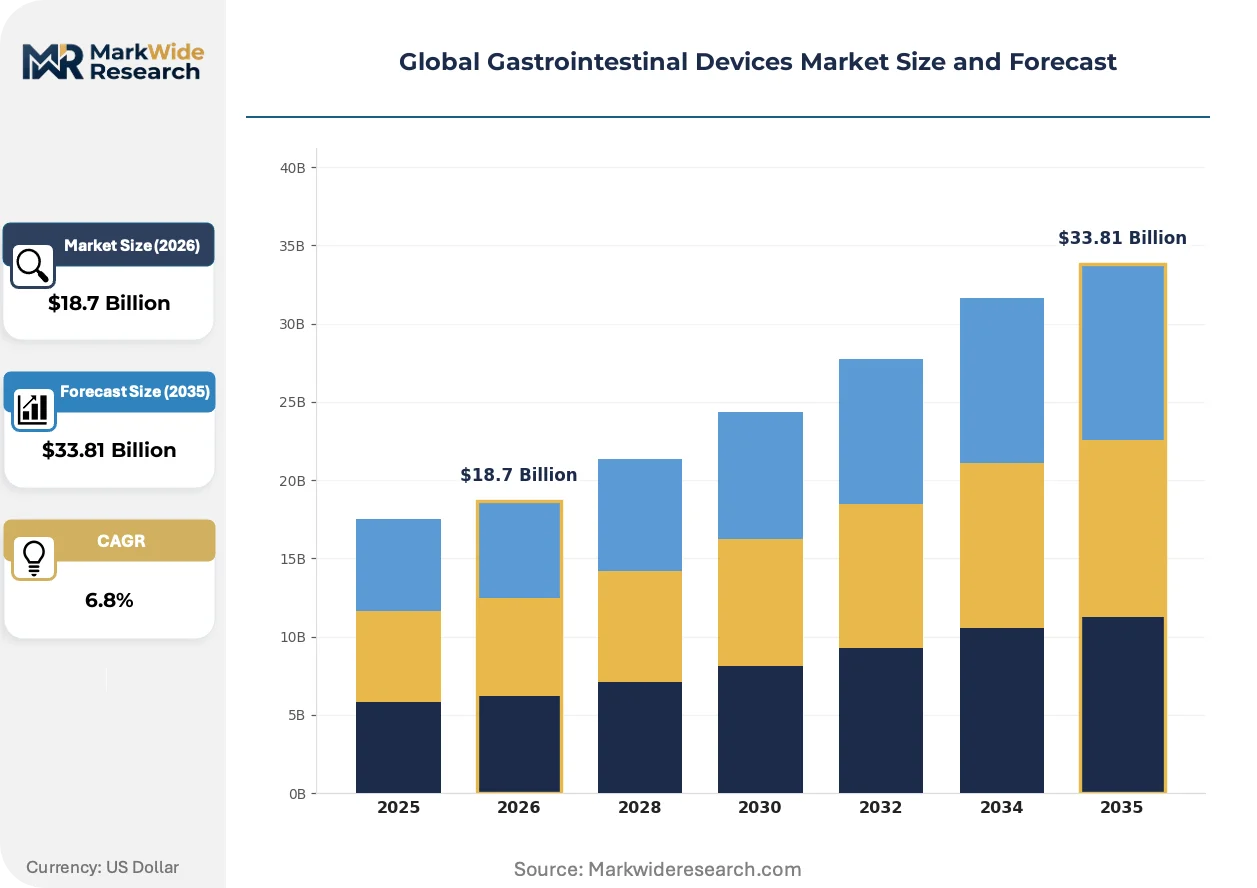
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Endoscopes, Electrosurgical Devices, Imaging Systems, Biopsy Forceps Application: Diagnostics, Surgery, Monitoring, Tumor Ablation End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Labs Technology: Robotic Surgery, Ultrasonography, Wireless Capsule Endoscopy, Assisted Navigation |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Fujifilm Holdings Corporation, Medtronic, Stryker Corporation, Johnson & Johnson, Hoya Corporation, Cook Group Incorporated, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastrointestinal Devices Market Emerging Trajectories
Digital pathology workflows and cloud-based image archiving are compressing the traditional hardware-centric business model toward software-recurring revenue structures. This shift reconfigures competitive advantage around data analytics capabilities rather than instrument precision alone.
Single-use duodenoscopes constructed from medical-grade polymers and miniaturized CMOS sensors are virtualizing the sterilization burden entirely. Academic medical centers in the United States are piloting these disposable platforms for high-risk patient populations. The technology is virtualizing capital equipment depreciation models into per-procedure consumable economics.
The European Medical Device Regulation's Unique Device Identification mandate is forcing serialization infrastructure investments across manufacturing footprints. Suppliers serving EU markets must retrofit production lines with laser marking and database integration capabilities. Smaller OEMs without compliance resources are exiting the European market entirely.
Hospital value-analysis committees now unbundle endoscope procurement from mandatory service contracts. This purchasing behavior shift fragments the traditional OEM lock-in model. The phenomenon is most visible in United States integrated delivery networks where procurement centralization empowers aggressive vendor negotiation.
Global Gastrointestinal Devices Market Segmentation
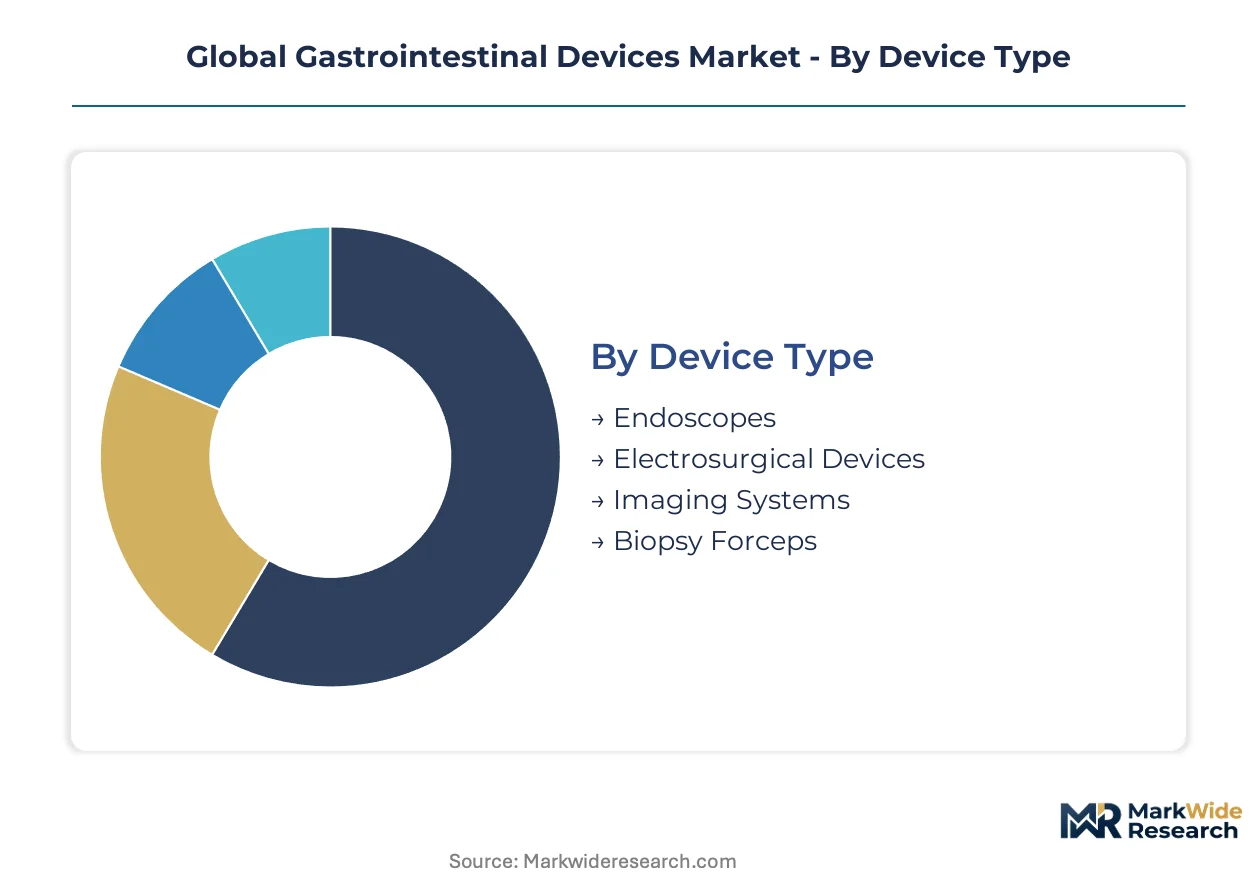
Segmentation reveals how procedural economics and regulatory pressure fragment purchasing authority across the gastrointestinal device value chain. Hospital procurement teams, ambulatory operators, and specialty clinicians each impose distinct technical specifications and service requirements on suppliers.
Device Type:
Mature capital equipment segments dominate installed base economics while emerging disposable formats reshape sterilization workflows.
- Endoscopes:Flexible fiber-optic and video endoscopes incorporate medical-grade fluoropolymer sheathing and CMOS imaging sensors for luminal visualization. Demand concentrates in Japanese and German hospital systems where aging demographics drive colorectal screening volumes and capital replacement cycles accelerate under tightened FDA reprocessing mandates.
- Electrosurgical Devices:These instruments deliver controlled thermal energy through monopolar or bipolar configurations for polypectomy and hemostasis. United States ambulatory surgical centers favor compact generator systems that minimize footprint in high-throughput endoscopy suites.
- Imaging Systems:High-definition video processors and digital capture platforms enable real-time tissue characterization.
- Biopsy Forceps:Single-use and reusable forceps extract tissue specimens for histopathological analysis.
Endoscopes handle the majority of throughput; electrosurgical devices are gaining share fastest as outpatient procedural volumes climb.
Application:
Diagnostic applications anchor revenue stability while therapeutic interventions command premium pricing tiers.
- Diagnostics:Screening colonoscopy, esophagogastroduodenoscopy, and capsule-based imaging detect neoplastic and inflammatory conditions. Japan's national cancer screening program and Germany's statutory health insurance reimbursement frameworks sustain procedural density in hospital endoscopy departments.
- Surgery:Minimally invasive interventions include endoscopic mucosal resection, submucosal dissection, and peroral endoscopic myotomy. Academic medical centers in the United States prioritize hybrid operating rooms integrating endoscopic and laparoscopic capabilities.
- Monitoring:Longitudinal surveillance of Barrett's esophagus and inflammatory bowel disease requires repeated endoscopic evaluation.
- Tumor Ablation:Radiofrequency and cryoablation modalities target unresectable hepatic and pancreatic malignancies.
Diagnostics commands the largest procedure volume; tumor ablation shows the steepest expansion trajectory as interventional oncology protocols proliferate.
End User:
Procurement centralization trends diverge sharply between consolidated hospital networks and fragmented outpatient operators.
- Hospitals:Integrated delivery networks negotiate enterprise-wide endoscope fleets with mandatory refurbishment contracts. United States health systems leverage volume commitments to unbundle capital purchases from captive service agreements.
- Specialty Clinics:Gastroenterology-focused practices prioritize compact, portable systems for office-based procedures. German outpatient clinics exploit favorable reimbursement differentials for screening colonoscopy performed outside hospital settings.
- Ambulatory Surgical Centers:These facilities maximize throughput per clinical hour with rapid-turnover sedation protocols.
- Diagnostic Labs:Pathology laboratories integrate with capsule endoscopy providers for remote image interpretation services.
Hospitals absorb the dominant share of capital expenditure; ambulatory surgical centers are climbing the fastest as site-of-service migration accelerates.
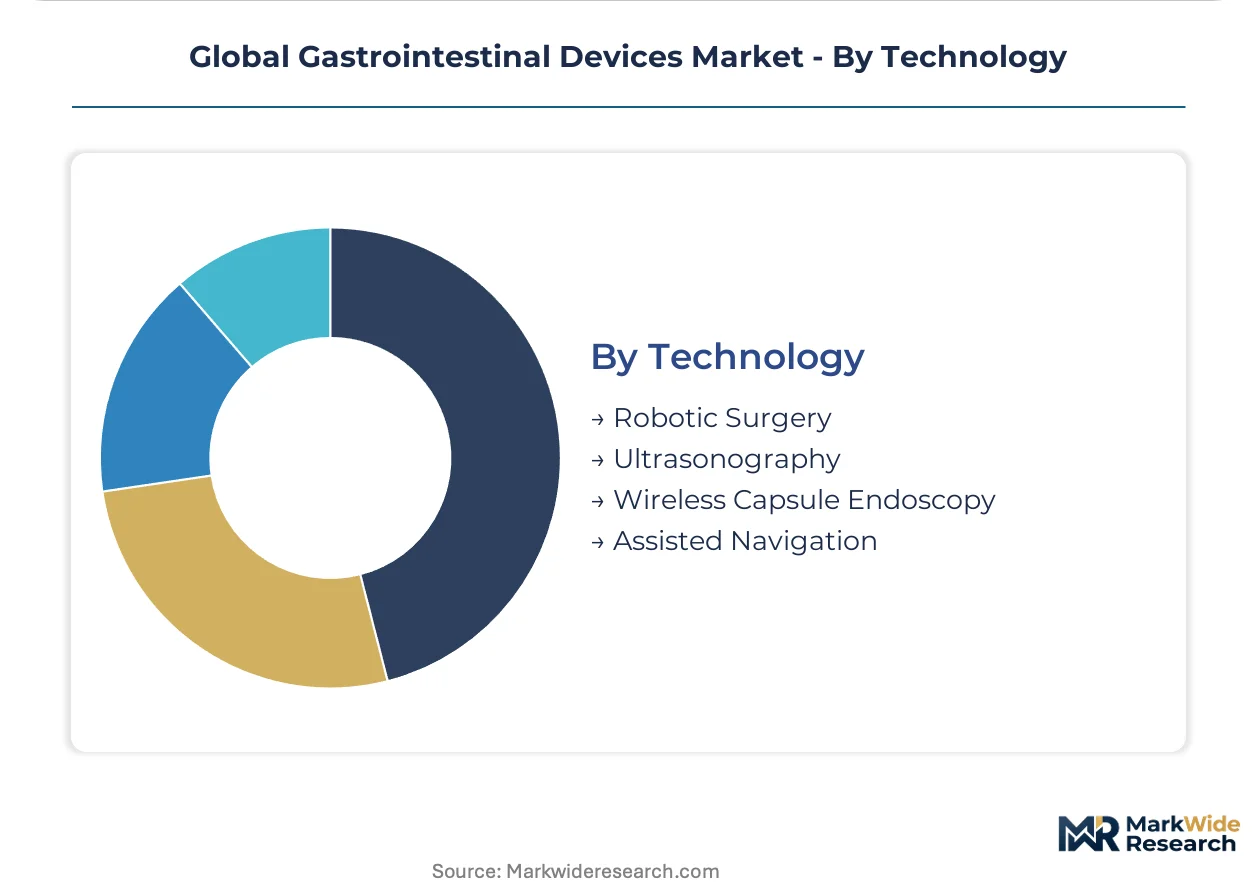
Technology:
Hardware-centric platforms face displacement from software-integrated and disposable alternatives.
- Robotic Surgery:Master-slave platforms enable precise tissue manipulation through flexible endoscopic instruments. Japanese academic centers evaluate robotic systems for complex endoscopic submucosal dissection procedures.
- Ultrasonography:Endoscopic ultrasound combines luminal imaging with transmural sonography for pancreaticobiliary assessment. United States tertiary centers deploy these systems for fine-needle aspiration of mediastinal and abdominal lymph nodes.
- Wireless Capsule Endoscopy:Pill-based CMOS cameras capture small bowel images without sedation or intubation.
- Assisted Navigation:Electromagnetic tracking and AI-enhanced path planning guide endoscope advancement through tortuous anatomy.
Wireless capsule endoscopy handles the majority of emerging technology investment; assisted navigation is expanding most quickly as computer vision capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature markets prioritizing capital replacement cycles and emerging systems building first-time installed base. Japan and Germany concentrate demand around high-throughput hospital endoscopy suites, while India and Brazil expand access through decentralized diagnostic networks.
United States
Ambulatory surgical centers drive procedural volume migration away from inpatient settings. FDA reprocessing mandates for duodenoscopes accelerate equipment replacement timelines. Texas and Florida health systems lead capital deployment for single-use endoscope pilot programs.
Germany
Statutory health insurance reimbursement differentials sustain outpatient colonoscopy density. EMA Medical Device Regulation compliance costs filter smaller manufacturers from the market. Bavarian university hospitals anchor advanced endoscopic submucosal dissection training networks.
Japan
Super-aged demographics sustain the world's highest per-capita endoscopy utilization rates. PMDA sterilization efficacy benchmarks exceed FDA requirements, shaping Asia-Pacific product specifications. Tokyo and Osaka metropolitan clusters concentrate precision refurbishment technician pools.
India
National health mission funding expands endoscopy access to district hospital tier. CDSCO device registration pathways streamline import authorization for multinational OEMs. Maharashtra and Karnataka state health systems prioritize public-private partnerships for equipment leasing.
Brazil
ANVISA regulatory harmonization with FDA standards accelerates product registration for multinational suppliers. São Paulo state concentrates private diagnostic imaging investment. Minas Gerais and Rio de Janeiro expand screening colonoscopy capacity through federal health system procurement.
Global Gastrointestinal Devices Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around a consolidated core of diversified medical technology conglomerates and a periphery of specialized endoscope fabricators. Strategic archetypes include full-stack platform vendors, component specialists, and regional service integrators. Dominant competitive moves encompass captive refurbishment network expansion and AI-enabled diagnostic software licensing.
Within the diversified conglomerate tier, Olympus Corporation and Boston Scientific Corporation occupy positions exemplifying the platform-plus-service bundling model. Fujifilm Holdings Corporation anchors the imaging-technology vector, representing archetypes that leverage optical and sensor expertise across medical and industrial applications. These three entities collectively illustrate how competitive positioning depends on controlling both instrument hardware and recurring revenue streams from consumables and maintenance.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson |
| Hoya Corporation |
| Cook Group Incorporated |
| CONMED Corporation |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors linking Japanese fluoropolymer plants to North American OEM assembly facilities transmit cost volatility directly into endoscope pricing tiers. These logistics dynamics amplify supply-side concentration effects while forcing hospital procurement teams to negotiate contract structures that buffer against raw material and shipping cost swings.
Pricing Analysis
Long-term offtake agreements dominate capital equipment procurement while consumables trade on spot-adjacent terms tied to volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated systems from CE-marked alternatives and basic clinical configurations. Price differentiation hinges on sterilization certification grade and bundled refurbishment service depth. Cost compression in mid-tier electrosurgical accessories is intensifying because German chemical suppliers have consolidated fluoropolymer output. Ambulatory surgical centers exhibit highest price sensitivity due to thin per-procedure margins, whereas Japanese academic medical centers prioritize technical specifications over unit economics.
Supply Chain Analysis
Contract manufacturing for CMOS imaging sensors concentrates among Taiwanese and South Korean foundries, with Japanese precision optics houses retaining captive production of fiber-optic bundles. Medical-grade fluoropolymers for flexible sheathing draw from German and Japanese chemical suppliers; miniaturized sensor arrays feed from semiconductor fabrication networks anchored in East Asia. Single-source vulnerability pervades the fluoropolymer tier, where two suppliers control medical-grade resin specifications. Distribution runs through authorized dealer networks for capital equipment and GPO-mediated channels for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a capital replacement supercycle triggered by FDA duodenoscope reprocessing mandates. Equipment refresh demand will moderate as compliance-driven upgrades complete, shifting competitive focus toward service contract retention and disposable technology migration.
For Market Incumbents: Pre-empt independent service organization encroachment by expanding factory-authorized refurbishment capacity in Texas and Bavaria. Lock hospital systems into decade-long reprocessing contracts before procurement centralization completes. Vertical integration into medical-grade fluoropolymer compounding reduces exposure to German supplier concentration.
For New Entrants and Emerging Players: Build out disposable duodenoscope manufacturing capacity targeting United States academic medical centers piloting single-use protocols. India's district hospital tier offers the most penetrable geography, with public-private partnerships providing equipment leasing pathways. Pursue CDSCO registration alongside FDA 510(k) submissions to accelerate market access.
For Investors and Strategic Acquirers: AI-enabled diagnostic software developers with FDA-cleared polyp detection algorithms represent the priority acquisition archetype. These assets command premium multiples as hardware margins compress toward service-recurring models. Watch for inflection when United States health systems begin unbundling endoscope procurement from mandatory service contracts in volume.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Olympus and Boston Scientific leverage enterprise fleet contracts to lock refurbishment revenue across United States integrated delivery networks. |
| Software Companion Development | Real-time polyp detection algorithms from Fujifilm create premium pricing tiers for computer-assisted diagnostic platforms. |
| CE Marking Pathway | EU MDR compliance investments filter smaller manufacturers, concentrating market share among diversified conglomerates with regulatory infrastructure. |
| Reimbursement Strategy | German outpatient clinics exploit statutory health insurance differentials to shift colonoscopy volume outside hospital settings. |
| FDA Submission | Single-use duodenoscope manufacturers pursue 510(k) clearance to virtualize sterilization burdens for high-risk patient populations. |
Methodological Framework
Desk research of FDA 510(k) filings, EMA Medical Device Regulation guidance documents, and hospital procurement databases preceded structured interviews with biomedical engineering directors, GPO contracts managers, and gastrointestinal clinicians. Primary fieldwork with Olympus and Fujifilm service technicians supplemented secondary validation through SEC 10-K disclosures and Japanese PMDA sterilization efficacy benchmarks. Bottom-up installed base modeling triangulated against top-down procedural volume estimates from CMS Medicare claims data.
Assumptions around FDA reprocessing mandate enforcement timelines and EU MDR transition completion held fixed across scenarios, while wireless capsule endoscopy adoption rates and India diagnostic infrastructure buildout varied. Segmentation dimensions spanned device type, application, end user, and technology platform. CAGRs derived from procedure volume elasticity to aging demographic projections and reimbursement rate stability. Forecast inputs incorporated PMDA sterilization benchmark evolution and ambulatory surgical center site-of-service migration patterns.
Sensitivities concentrate around fluoropolymer supply disruptions, FDA enforcement intensity for duodenoscope reprocessing, and EU MDR clinical evidence requirement interpretation. Quarterly review of hospital capital expenditure announcements, GPO contract awards, and CDSCO registration timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Global IVF Devices Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Airway Management Devices Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Chest Drainage System Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Pulmonology Devices Market
Medical Devices
US Clear Aligners Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Saudi Arabia Anesthesia Devices Market