
 Space Travel Market | 2026-2036
Space Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Space Travel Market Insights
Commercial tourism is recalibrating the end-use vertical mix as scientific research and satellite deployment cede headline growth to passenger flight demand. SpaceX leverages its Starship reusability program to compress launch economics. Blue Origin sustains suborbital tourism cadence through New Shepard operations. Virgin Galactic differentiates with air-launch architecture and spaceplane design heritage.
Space travel encompasses crewed and uncrewed vehicle operations beyond Earth's atmosphere, typically requiring propulsion systems achieving delta-v exceeding 9.3 km/s for low-Earth orbit insertion and thermal protection systems rated for atmospheric reentry above 1,650°C. Its primary purpose spans payload delivery, human transport, and extraterrestrial infrastructure emplacement. Reusable rockets command the vehicle type segment due to amortized cost-per-launch advantages, while spaceplanes attract tourism-focused investment. Chemical rockets dominate propulsion technology deployment, though ion thrusters gain traction for deep-space cargo trajectories where thrust efficiency outweighs impulse urgency.
FAA commercial space launch licensing governs U.S. operator certification, while NASA safety standards shape crewed mission requirements. The EU AI Act and REACH frameworks indirectly constrain autonomous flight systems and materials sourcing for European-registered entities. Stakeholders must monitor evolving orbital debris mitigation rules from the FCC and international coordination bodies, as congestion management protocols will determine access schedules and insurance cost structures.
Market Dynamics
Reusable rocket technology is compressing launch economics and redrawing competitive boundaries as propulsion systems achieve higher cycle counts per vehicle. This maturation is shifting capital allocation from expendable hardware toward refurbishment infrastructure and rapid-turnaround ground operations.
Growth Catalysts
- FAA Commercial Space Launch Licensing:Standardized certification pathways for crewed missions are reducing regulatory uncertainty for operators seeking passenger flight approvals.
- Ultra-High-Net-Worth Tourism Demand:Suborbital experience bookings from affluent individuals are creating predictable revenue streams independent of government contract cycles.
- Amortized Cost-Per-Launch Economics:Reusable first-stage recovery is converging with rapid refurbishment protocols to enable weekly launch cadences previously unattainable with expendable systems.
Market Restraints
- Specialized Alloy Supply Concentration:Domestic sourcing of Inconel and titanium superalloys for thermal protection systems remains concentrated among a limited supplier base.
- Propellant Cost Volatility:Liquid oxygen and refined kerosene price fluctuations directly impact per-mission operating margins for chemical rocket operators.
- Orbital Debris Liability Exposure:FCC congestion management protocols are tightening insurance requirements and access scheduling for low-Earth orbit insertions.
Strategic Opportunities
- In-Space Manufacturing Applications:Microgravity environments enable novel pharmaceutical crystal growth and fiber-optic production unavailable terrestrially.
- Point-to-Point Suborbital Transport:Earth-to-Earth ballistic trajectories are emerging as a premium cargo channel for time-critical logistics.
- EU Green Deal Alignment:REACH-compliant materials sourcing and carbon-neutral propellant development open procurement access for European-registered payloads.
Industry Challenges
- Aerospace-Grade Welding Talent Scarcity:Friction stir welding and electron beam expertise for cryogenic tank fabrication outpaces vocational training pipeline output.
- Crew-Rating Certification Timelines:NASA safety standard validation for human-rated vehicles extends development schedules and defers revenue recognition.
- Legacy Ground Infrastructure Integration:Range safety systems at established launch sites require costly modernization to support rapid-reuse turnaround protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Travel Market |
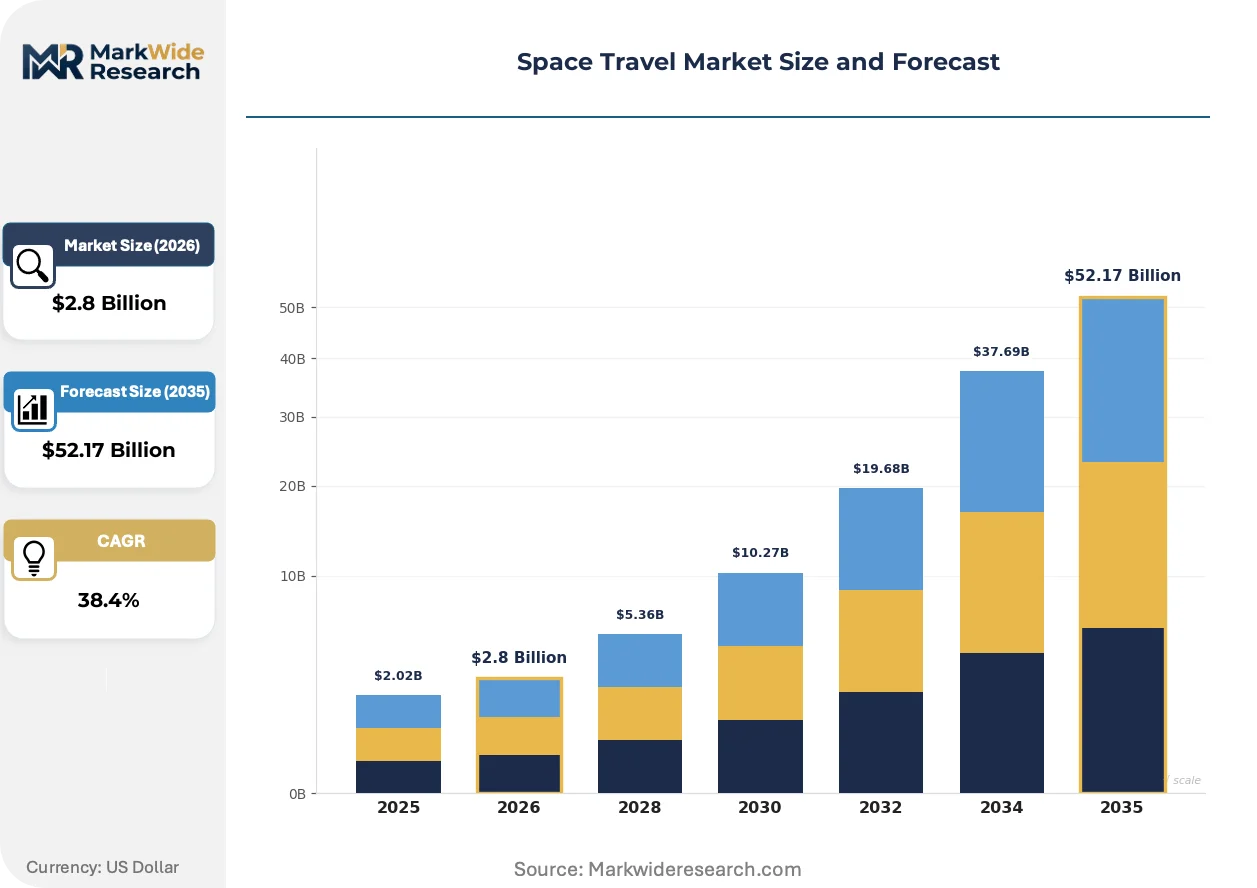
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $52.17 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Reusable Rockets, Spaceplanes, Orbital Capsules, Suborbital Vehicles, Lunar Rovers Propulsion Technology: Chemical Rockets, Ion Thrusters, Nuclear Thermal, Plasma Engines, Solar Sails Application: Tourism, Scientific Research, Satellite Deployment, Cargo Transport, Space Colonization End User: Private Aerospace Firms, Government Space Agencies, Research Institutes, Defense Contractors |
| Companies Covered | SpaceX, Virgin Galactic, Blue Origin, Space Adventures, Axiom Space, Boeing, Sierra Space, Bigelow Aerospace, Orbital Assembly Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Travel Market Trends and Innovations
Propulsion architecture is bifurcating as chemical systems optimize for launch while electric alternatives capture deep-space cargo economics. This divergence is forcing specialization across vehicle classes and reshaping supplier relationships.
Additive manufacturing is converging with topology optimization to produce single-piece thrust chamber assemblies that previously required dozens of welded joints. SpaceX and Blue Origin are deploying powder bed fusion for Inconel injector heads at production scale. This consolidation is compressing lead times from months to weeks while eliminating failure modes at braze interfaces.
FCC orbital debris mitigation rules are mandating post-mission disposal and collision avoidance protocols for all licensed U.S. operators. Satellite operators must now demonstrate five-year deorbit capabilities or active removal contracts. Small launch providers serving constellation deployers are absorbing compliance costs through modified upper-stage designs and dedicated deorbit burns.
Booking patterns among tourism participants are shifting from speculative deposits toward refundable reservation tiers with defined flight windows. Virgin Galactic and Blue Origin are unbundling training packages from base seat pricing to capture ancillary revenue. This behavioral evolution is most pronounced in U.S. markets where consumer protection expectations and competition for affluent leisure spending are highest.
Space Travel Market Segmentation
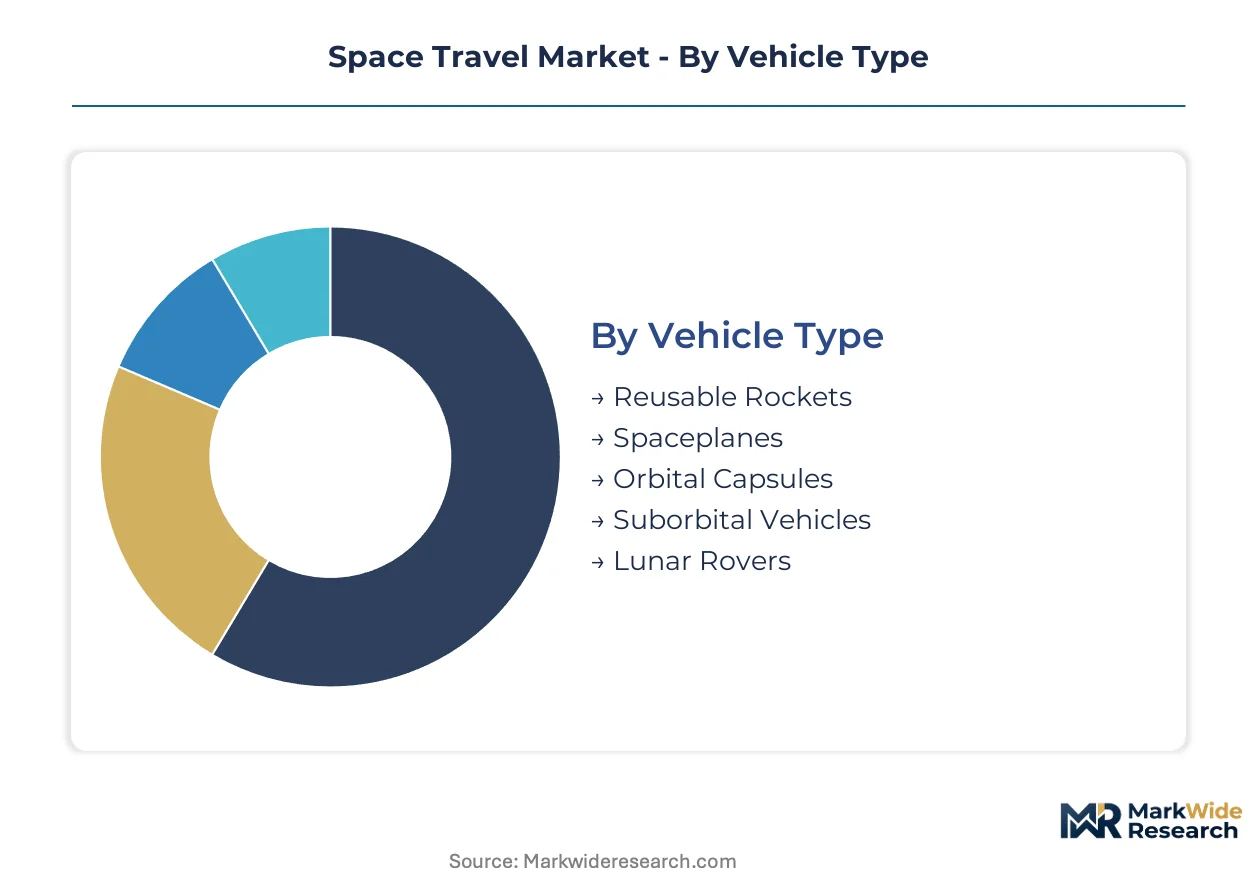
Segmentation in the space travel market reveals how capital allocation, regulatory pathways, and operational risk tolerance diverge across vehicle classes and customer profiles. Buyers select propulsion architectures and vehicle types based on mission duration, payload mass, and crew-safety requirements rather than unit cost alone.
Vehicle Type:
Purchase decisions here pivot on turnaround velocity versus mission flexibility, with operators trading refurbishment complexity against payload envelope.
- Reusable Rockets:First-stage recovery systems rated for multiple atmospheric reentries dominate launch cadence economics. Demand concentrates among constellation deployers and government resupply contractors seeking weekly launch windows.
- Spaceplanes:Horizontal takeoff and runway landing capability reduces range infrastructure dependency. Tourism operators favor this architecture for passenger experience differentiation and gradual g-force profiles.
- Orbital Capsules:Crew-rated ablative heat shields and parachute recovery systems serve ISS transport and deep-space exploration missions.
- Suborbital Vehicles:Ballistic trajectories below orbital velocity threshold enable brief microgravity exposure without full orbital insertion costs.
- Lunar Rovers:Pressurized mobility systems with regolith-rated drivetrains support Artemis program surface operations and future extraction logistics.
Reusable rockets lead on scale; suborbital vehicles lead on momentum.
Propulsion Technology:
Engine selection reflects thrust-to-weight priorities against specific impulse efficiency, with chemical systems dominating launch and electric alternatives capturing extended trajectory economics.
- Chemical Rockets:Liquid oxygen and kerosene or methane combustion achieves the thrust density required for Earth escape velocity. Commercial launch providers standardize on this technology for payload-to-orbit reliability.
- Ion Thrusters:Xenon or krypton ionization generates continuous low-thrust acceleration ideal for deep-space cargo and station-keeping maneuvers where transfer time is secondary to propellant mass efficiency.
- Nuclear Thermal:Hydrogen propellant heated through reactor cores offers doubled specific impulse over chemical alternatives, though regulatory approval timelines constrain near-term deployment.
- Plasma Engines:Electromagnetic acceleration of ionized propellant enables variable thrust modulation for precision orbital insertion and debris avoidance maneuvers.
- Solar Sails:Photon pressure propulsion eliminates onboard propellant requirements entirely, suiting long-duration scientific probes and asteroid rendezvous missions.
Chemical rockets anchor current revenue; ion thrusters are climbing the fastest.
Application:
Mission purpose determines vehicle specification, insurance structures, and crew-rating requirements more than any hardware attribute.
- Tourism:Suborbital experience packages and orbital stays generate recurring revenue independent of government procurement cycles. FAA crewed mission licensing shapes operational safety margins and booking liability frameworks.
- Scientific Research:Microgravity laboratories and astronomical observation platforms require precise attitude control and minimal vibration environments.
- Satellite Deployment:Constellation replenishment and geostationary insertion drive demand for standardized payload adapters and sun-synchronous orbit access.
- Cargo Transport:Pressurized and unpressurized logistics modules support ISS resupply and future lunar base construction material delivery.
- Space Colonization:Long-duration life support systems and in-situ resource utilization equipment development precedes permanent habitation infrastructure.
Tourism shows steepest expansion trajectory; satellite deployment maintains volume concentration.
End User:
Contracting authority and funding stability separate customer segments more than technical requirements.
- Private Aerospace Firms:Venture-backed and publicly traded operators pursue reusable vehicle development and commercial tourism verticals with private capital risk tolerance.
- Government Space Agencies:NASA and international counterparts anchor demand for crew-rated systems and deep-space exploration architectures through multi-year appropriations.
- Research Institutes:University consortia and national laboratories fund specialized microgravity experiments and technology demonstration missions.
- Defense Contractors:National security payload integration and responsive space access requirements drive classified mission demand with distinct security clearance protocols.
Government space agencies lead on contract value; private aerospace firms lead on transaction velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting launch infrastructure investment toward jurisdictions with streamlined commercial space licensing, as operators seek to minimize compliance timelines and insurance overhead. The United States, China, and select European economies are consolidating distinct competitive advantages through divergent safety and environmental frameworks.
United States
FAA commercial space launch licensing anchors operational legitimacy for crewed missions, with standardized certification pathways reducing approval uncertainty. Cape Canaveral and the Mojave Desert host concentrated launch infrastructure serving tourism and constellation deployment demand. SpaceX, Blue Origin, and Virgin Galactic maintain integrated manufacturing and test facilities across Texas, Florida, and California.
China
National space program budgets and state-backed commercial spinoffs are accelerating reusable rocket development under MIIT industrial policy guidance. GB standards and dual carbon goals shape propellant sourcing and materials compliance for domestic operators. Hainan Province's Wenchang Satellite Launch Center anchors civil space activity with equatorial launch advantages.
United Kingdom
Scotland's SaxaVord and Sutherland spaceports are attracting small launch providers seeking polar orbit access with streamlined national space legislation. The UK Space Agency's regulatory framework differentiates from EU REACH post-Brexit, creating materials sourcing flexibility. Cornwall's horizontal launch infrastructure leverages existing aviation assets for air-launch tourism vehicles.
Germany
ESA procurement through the Ariane program sustains Munich and Bremen industrial clusters for propulsion and satellite manufacturing. KBA-adjacent aerospace certification expertise supports crew-rating documentation for European human spaceflight initiatives. Baden-Württemberg's precision engineering base supplies cryogenic valve and sensor components to launcher integrators.
Japan
METI space industry promotion funds and JAXA technology transfer programs are commercializing H3 rocket derivatives for regional launch demand. Tanegashima and Uchinoura space centers maintain government-controlled range safety systems with limited commercial access. Nagoya's aerospace manufacturing corridor produces Inconel superalloy components for thermal protection systems.
Space Travel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operators capturing tourism revenue while component suppliers serve diversified launcher programs. The vendor base concentrates around three strategic tiers: vertically integrated prime contractors controlling end-to-end mission capability, specialized subsystem houses dominating thermal protection and propulsion niches, and emerging venture-backed entrants pursuing rapid-reuse architectures. Competitive dynamics revolve around M&A activity consolidating propulsion expertise and strategic partnerships securing launch site access.
Within the prime contractor tier, SpaceX and Blue Origin exemplify divergent pathways to scale—one through full-stack vertical integration, the other through focused suborbital tourism cadence. Virgin Galactic occupies a position emphasizing air-launch differentiation and passenger experience design. These three anchors demonstrate how regulatory timing, capital intensity, and architectural choices segment competitive positioning across the reusable vehicle landscape.
| Leading Market Players |
|---|
| SpaceX |
| Virgin Galactic |
| Blue Origin |
| Space Adventures |
| Axiom Space |
| Boeing |
| Sierra Space |
| Bigelow Aerospace |
| Orbital Assembly Corporation |
| Others |
Pricing and Supply Chain Analysis
Additive manufacturing adoption is compressing fabrication timelines for Inconel thrust chambers while simultaneously concentrating qualified powder suppliers in the United States and Germany. This production-method transition enables rapid-turnaround economics but creates procurement bottlenecks as FAA-certified suppliers remain limited.
Pricing Analysis
Direct-to-operator contracting eliminates distributor margins for reusable rocket operators, while tourism intermediaries retain 15-25% booking commissions. Three-tier pricing structure across premium, standard, and economy levels separates fully-refundable reservation tiers from speculative deposit tranches. Cost compression in suborbital tourism is intensifying because Virgin Galactic and Blue Origin are unbundling training packages from base seat pricing. Government space agencies exhibit lowest price sensitivity due to multi-year appropriation stability, while venture-backed constellation deployers negotiate aggressively on per-kilogram rates.
Supply Chain Analysis
Domestic-content mandates under FAA commercial space launch licensing are reshaping sourcing patterns for crew-rated thermal protection systems. Inconel superalloy supply concentrates in the United States, Japan, and Germany, with cryogenic valve fabrication anchored in Baden-Württemberg's precision engineering corridor. Liquid oxygen and refined kerosene propellant sourcing draws from regional petrochemical clusters, creating exposure to energy price volatility. Distribution runs through vertically integrated prime contractors controlling end-to-end mission capability rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Space travel has entered a late-cycle quality phase where passenger safety certification and rapid-reuse reliability now filter capital allocation ahead of raw technical ambition. Ultra-high-net-worth tourism demand is shifting toward refundable booking tiers with defined flight windows, elevating operational credibility over speculative promise.
For Market Incumbents: Hedge against propellant cost volatility through long-term offtake agreements with regional oxygen and kerosene suppliers. Consolidate friction stir welding talent pools through acquisition of specialized vocational training programs, as aerospace-grade fabrication expertise outpaces pipeline output. Vertical integration into thermal protection system manufacturing mitigates Inconel supply concentration risk.
For New Entrants and Emerging Players: Capture white-space in point-to-point suborbital cargo transport for time-critical logistics, where regulatory pathways remain less congested than passenger certification. Scotland's SaxaVord and Cornwall's horizontal launch infrastructure offer penetrable geographic entry points with streamlined national space legislation. Pursue ESA procurement alignment as a go-to-market anchor for European-registered payload demand.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized subsystem houses dominating cryogenic valve and sensor niches, as prime contractor multiples reflect tourism revenue visibility. Long-term viability hinges on demonstration of weekly launch cadence economics and five-year orbital debris compliance. Monitor FCC congestion management protocol evolution as the signal indicating insurance cost inflection and access schedule tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusable First-Stage Recovery Scale-Up | Amortized cost-per-launch economics enable weekly cadences previously unattainable with expendable systems. |
| FAA Crew-Rating Certification Investment | Standardized pathways reduce regulatory uncertainty for operators seeking passenger flight approvals. |
| In-Space Manufacturing Partnership | Microgravity pharmaceutical crystal growth opens procurement access for European-registered payloads under EU Green Deal. |
| Additive Manufacturing Talent Acquisition | Powder bed fusion expertise for Inconel injector heads compresses lead times from months to weeks. |
| Orbital Debris Compliance Integration | Five-year deorbit capabilities satisfy FCC mitigation rules and determine insurance cost structures. |
Research Methodology
Coverage spans the United States, China, United Kingdom, Germany, and Japan, with primary inputs from each jurisdiction's regulatory and industrial clusters. Primary interviews with launch operators, propulsion engineers, FAA certification specialists, and tourism booking platform executives combined with secondary validation from FAA commercial space launch licensing records, ESA procurement disclosures, METI space industry promotion filings, and SEC filings from publicly traded aerospace firms. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition across vehicle type, propulsion technology, application, and end user dimensions structured the analytical framework over the projection horizon. CAGRs were derived from trajectory modeling incorporating reusable rocket cycle-count improvements, tourism booking pattern evolution, and constellation deployment schedules. Industry-specific forecast inputs included propellant cost indices and crew-rating certification timeline distributions.
Regulatory timeline delays, propellant price volatility, and orbital debris liability framework evolution are the dominant revision risks that could compress or extend the analysis window. Forecasts reflect documented assumptions regarding FAA licensing efficiency and reusable vehicle turnaround velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Lander and Rover Market
Space
Space Debris Monitoring Market
Space
Space Robots Market
Space
France Space Electronics Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
UK Space Propulsion System Market
Space
Spain Space Electronics Market
Space
Europe Space Logistics Market
Space
Orbital Spaceflight Market
Space
Space-Based Smart Sensors Market
Space
Space Ground Station Equipment Market
Space
Private Space Travel Market
Space
Space Frame Market
Space
Mexico Space Electronics Market
Space
Rocket Launchpad Market
Space
Asia-Pacific Space Logistics Market