
 Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market Foresight
The capital-intensity divergence between converter station specialists and component suppliers is rotating competitive advantage toward integrated system architects. Siemens Energy leverages its turnkey project portfolio to anchor large-scale interconnection bids across the Gulf. Hitachi Energy Ltd differentiates through voltage source converter technology leadership in renewable integration schemes. ABB sustains its historical presence in line-commutated converter retrofits while extending service capabilities into hybrid HVDC configurations.
High-voltage direct current transmission systems employ power electronic converters to transmit bulk electricity across distances exceeding 600 kilometers with losses below 3% per 1,000 km, primarily serving interregional grid interconnection and offshore renewable export. Voltage source converter technology is capturing share from line-commutated converter installations as operators demand reactive power control and black-start capability for desert solar complexes. Converter stations command the dominant margin pool within product type segmentation due to semiconductor and cooling system complexity, while protection equipment competes on volume across retrofit programs.
Saudi Arabia's national electricity regulator and the UAE's federal energy standards authority shape equipment certification and interconnection codes across Gulf Cooperation Council markets. The Saudi Electricity Company mandates IEC 62501-compliant valve testing for all new HVDC links, while Emirates Water and Electricity Company enforces specific harmonic emission limits at converter terminals. Stakeholders must monitor how Gulf standardization bodies reconcile European IEC frameworks with emerging national technical specifications before committing to platform architectures.
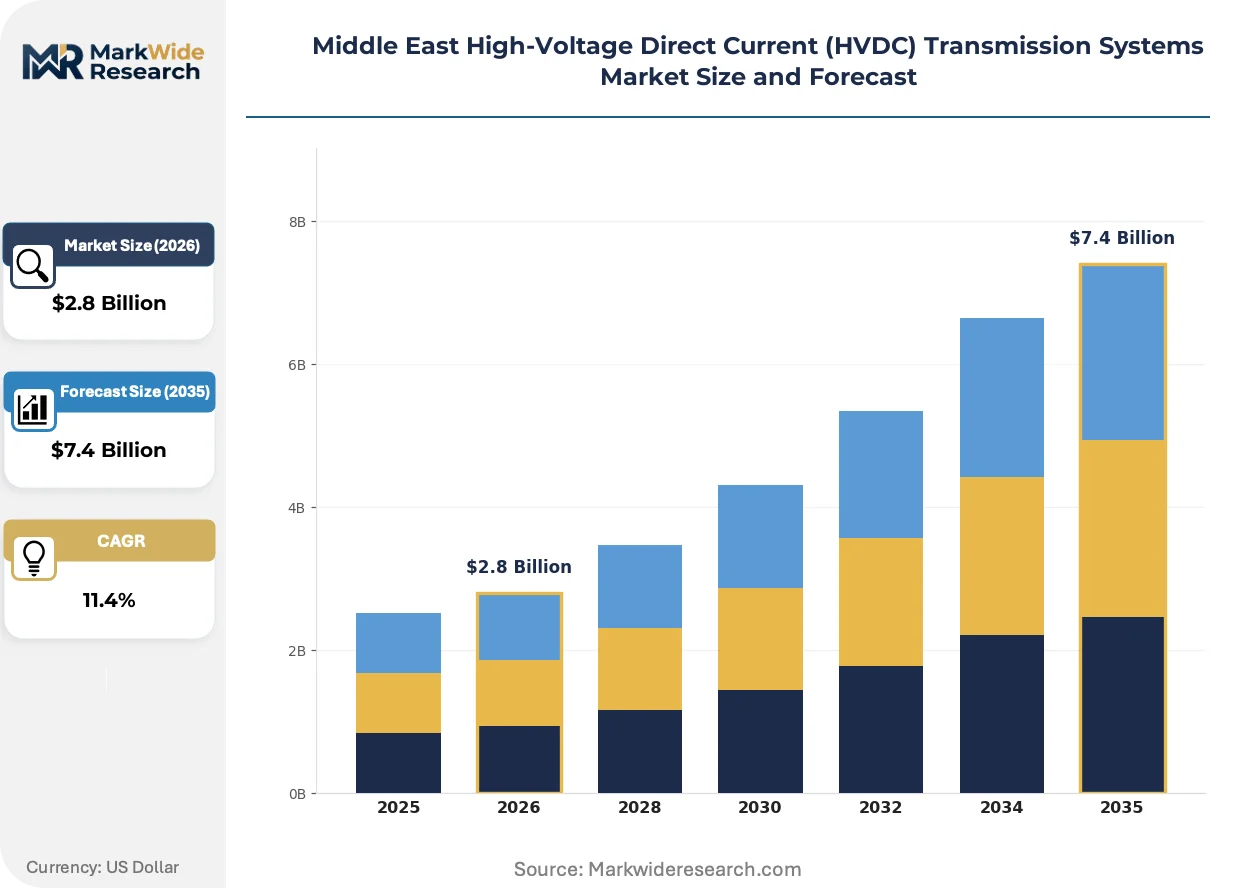
Market Dynamics
Voltage source converter technology is bifurcating procurement patterns across Gulf utilities, as Saudi Electricity Company and Emirates Water and Electricity Company prioritize bidirectional power flow for solar export schemes. This semiconductor-driven transition concentrates supplier relationships around integrated system architects capable of turnkey converter station delivery.
Growth Catalysts
- Desert Solar Integration:Saudi Arabia's renewable export mandates require HVDC links to transmit photovoltaic output from remote generation clusters to coastal demand centers.
- IEC 62501 Valve Testing:Saudi Electricity Company mandates this standard for all new converter installations, accelerating equipment replacement cycles and certification-driven procurement.
- Interconnection Infrastructure:Gulf Cooperation Council grid harmonization initiatives channel investment toward cross-border transmission corridors linking UAE, Saudi Arabia, and Qatar load centers.
Market Restraints
- Semiconductor Supply Concentration:IGBT and SiC module fabrication concentrates in East Asian foundries, exposing converter station lead times to geopolitical disruption.
- Desert Climate Degradation:Thermal cycling and sand abrasion accelerate insulation system failure in outdoor valve halls, compressing maintenance intervals below European baselines.
- Specialized Labor Scarcity:Gulf utilities face acute shortages of power electronics engineers qualified for voltage source converter commissioning and protection tuning.
Strategic Opportunities
- Oman and Kuwait Grid Modernization:These markets lag Saudi Arabia and UAE in HVDC deployment, presenting first-mover positioning for converter station specialists.
- Hybrid AC-DC Substation Retrofits:Existing 380 kV corridors in the UAE accommodate voltage source converter overlays without full right-of-way replacement.
- Black-Start Capability Contracts:Emirates Water and Electricity Company procurement frameworks now specify grid-forming converter requirements for islanded operation during transmission contingencies.
Industry Challenges
- Protection Coordination Complexity:Voltage source converter fault response differs fundamentally from line-commutated systems, forcing redesign of relay settings across interconnected Gulf networks.
- Harmonic Emission Compliance:Emirates Water and Electricity Company terminal limits demand customized filter bank configurations that extend engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Line Commutated Converter, Voltage Source Converter, Hybrid HVDC, Others Application: Renewable Integration, Grid Interconnections, Power Supply Stabilization, Industrial Power End User: Utility Providers, Independent Power Producers, Government Entities, Industrial Corporations Product Type: Transmission Systems, Converter Stations, Protection Equipment, Control Systems |
| Companies Covered | Hitachi Energy Ltd, Toshiba Corporation, Siemens Energy, Hyundai Heavy Industries, Mitsubishi Electric Corporation, ABB, Schneider Electric, Hyosung Group, General Electric, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market Shifts & Advancements
Modular multilevel converter architectures are compressing station footprints while enabling higher voltage ratings for long-distance desert transmission. Gulf utilities now specify these platforms as baseline requirements for renewable export tenders.
Silicon carbide power semiconductors are bifurcating thermal management strategies in converter valve design. Saudi Electricity Company evaluates SiC-based stations for 500 kV links from Al-Faisaliah solar complexes, citing reduced cooling load and station auxiliary power draw. This transition compresses competitive differentiation around semiconductor sourcing relationships and junction temperature modeling capabilities.
Emirates Water and Electricity Company harmonized its harmonic emission framework with IEC 62786 grid connection standards, tightening terminal distortion limits for new converter installations. Industrial consequence includes mandatory active filter integration in station designs. Manufacturers serving UAE tenders now embed real-time waveform compensation as standard rather than optional specification.
Engineering-procurement-construction contracting is consolidating vendor relationships around single-source accountability for converter stations. Saudi Electricity Company favors turnkey arrangements over component-separated procurement, compressing supplier margins while extending contract durations. This concentration is most visible in Riyadh and Jeddah corridor projects where utility risk transfer demands dominate bid evaluation criteria.
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
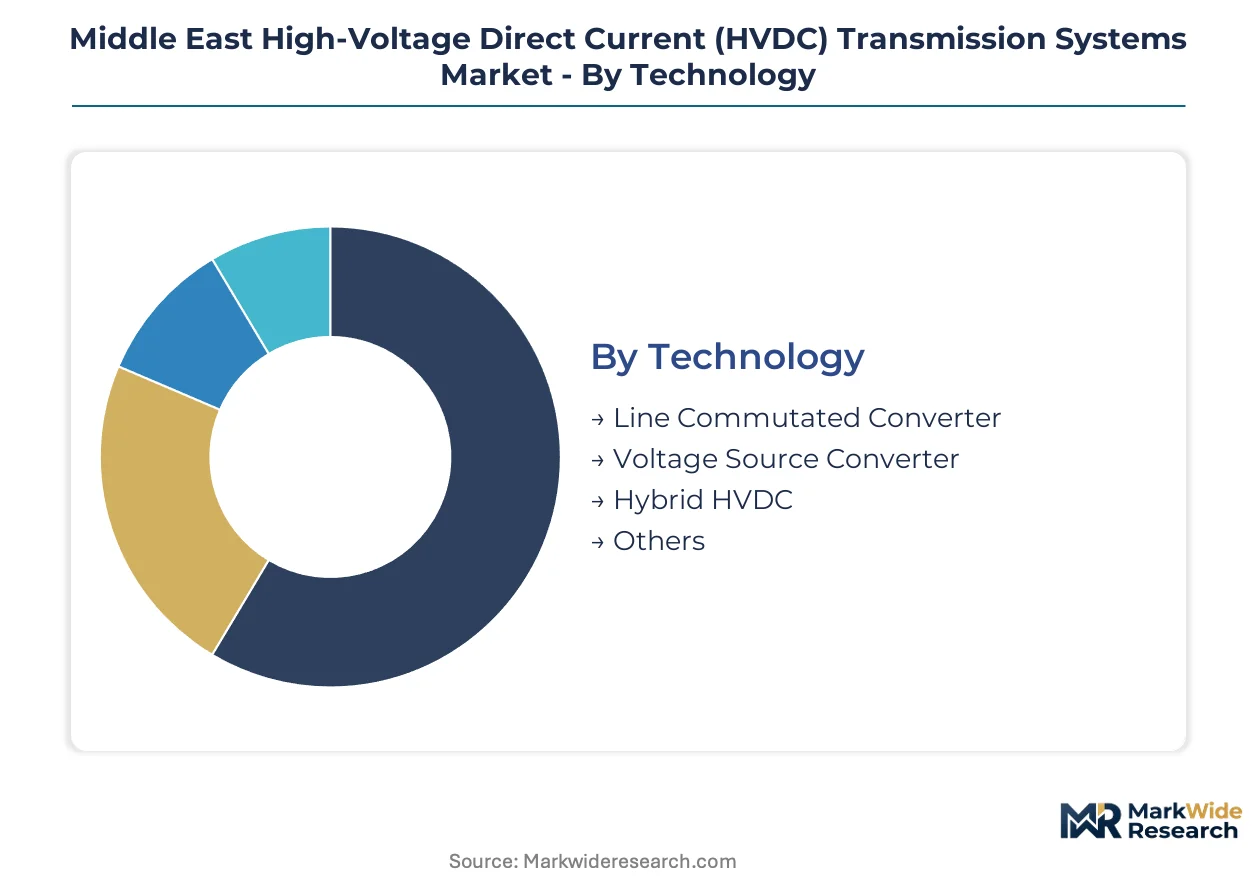
HVDC procurement patterns across the Middle East diverge sharply by application context and technology maturity. Saudi Electricity Company and Emirates Water and Electricity Company specifications reshape how segments combine in tender packages.
Technology:
Converter station vendors route legacy and advanced technologies through distinct contracting channels depending on grid operator technical specifications.
- Voltage Source Converter:Semiconductor-based platforms enable bidirectional power flow and black-start capability essential for Saudi Arabia's desert solar export corridors. Procurement concentrates through turnkey engineering-procurement-construction contracts where Siemens Energy and Hitachi Energy Ltd anchor bids.
- Line Commutated Converter:Thyristor-based systems dominate existing installed capacity across Gulf interconnection links built before renewable integration mandates. Retrofit demand persists where Saudi Electricity Company mandates IEC 62501 valve testing for life extension programs.
- Hybrid HVDC:Configurations blend converter topologies for staged grid upgrades.
- Others:Emerging topologies including capacitor-commutated designs for specialized industrial links.
Line Commutated Converter dominates installed base. Voltage Source Converter is where expansion concentrates.
Application:
Cost tier stratification separates high-investment interconnection projects from modular renewable integration schemes.
- Renewable Integration:HVDC links transmit photovoltaic output from remote Saudi generation clusters to coastal demand centers. Emirates Water and Electricity Company specifies grid-forming converter requirements for islanded operation during transmission contingencies.
- Grid Interconnections:Cross-border corridors linking UAE, Saudi Arabia, and Qatar load centers command premium capital allocation through Gulf Cooperation Council harmonization initiatives.
- Power Supply Stabilization:Frequency regulation services for industrial zones near Dubai and Riyadh.
- Industrial Power:Dedicated supply for aluminum smelters and desalination complexes requiring voltage stability.
Grid Interconnections absorb the largest project values. Renewable Integration is climbing the fastest as solar export mandates harden.
End User:
Customer type determines procurement sophistication and contract risk allocation structures.
- Utility Providers:Saudi Electricity Company and Emirates Water and Electricity Company mandate turnkey accountability, compressing supplier margins while extending contract durations across Riyadh and Jeddah corridor projects.
- Independent Power Producers:Developers of Saudi solar complexes procure HVDC export capacity through long-term offtake-linked tenders.
- Government Entities:Direct commissioning for strategic interconnection infrastructure.
- Industrial Corporations:Captive transmission for energy-intensive manufacturing facilities.
Utility Providers control project origination. Independent Power Producers represent the emerging procurement channel.
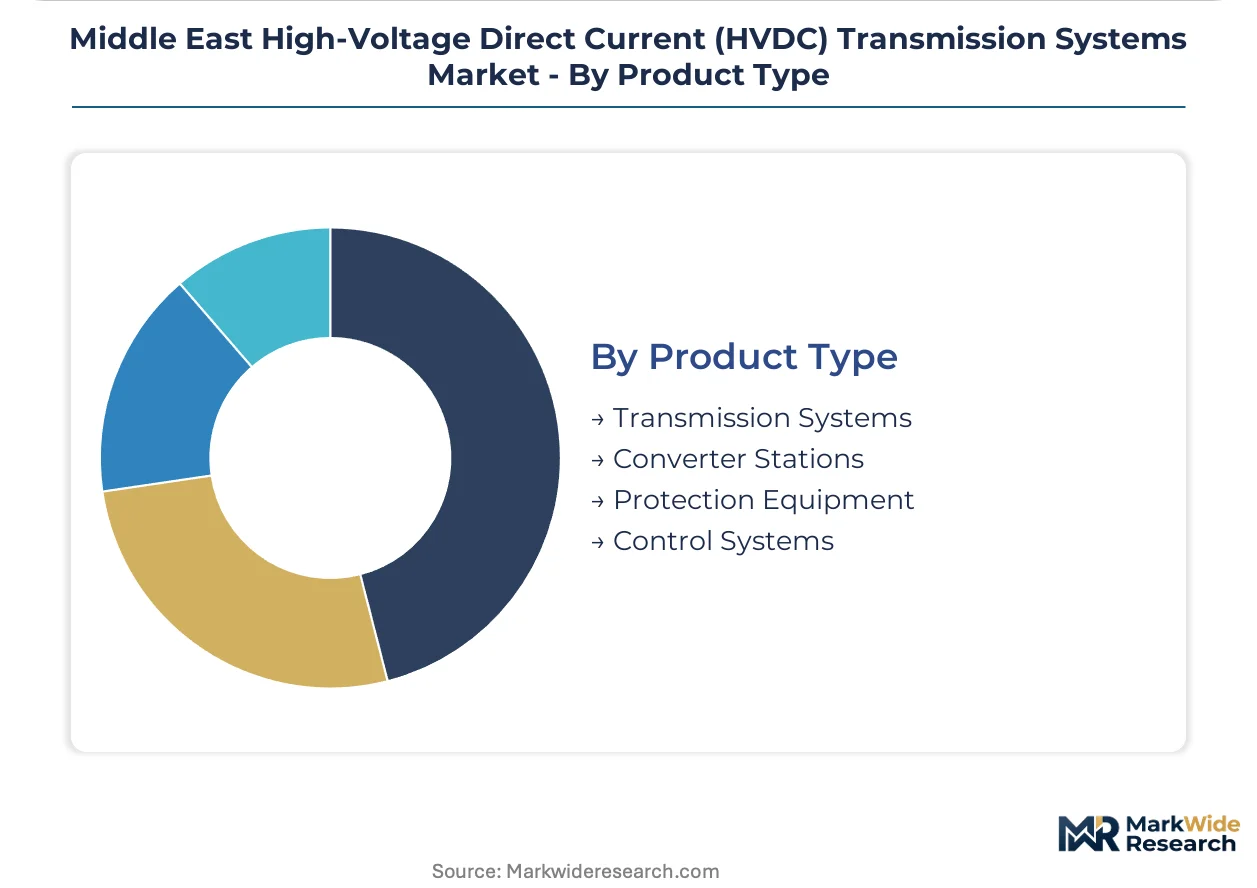
Product Type:
Margin concentration pools in semiconductor-intensive subsystems while volume competition characterizes standardized components.
- Converter Stations:Valve halls containing IGBT and silicon carbide modules command dominant margin pools due to cooling system complexity and junction temperature modeling requirements. Saudi Electricity Company evaluates SiC-based stations for 500 kV links from Al-Faisaliah solar complexes.
- Transmission Systems:Overhead lines and submarine cables for cross-border Gulf corridors face thermal cycling and sand abrasion challenges that compress maintenance intervals below European baselines.
- Protection Equipment:Relay systems compete on volume across retrofit programs as voltage source converter fault response forces redesign of settings across interconnected networks.
- Control Systems:Real-time waveform compensation platforms now embed as standard rather than optional specification under Emirates Water and Electricity Company harmonic emission frameworks.
Converter Stations capture value concentration. Protection Equipment scales through retrofit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE deploy HVDC infrastructure for desert solar export corridors, while Qatar and Kuwait prioritize grid interconnection stability. Oman represents an emerging procurement frontier with minimal installed base.
Saudi Arabia
Al-Faisaliah solar complexes drive 500 kV converter station demand for coastal power transmission. The Saudi Electricity Company mandates IEC 62501-compliant valve testing for all new installations. Riyadh and Jeddah corridor projects concentrate turnkey engineering-procurement-construction contracting.
United Arab Emirates
Emirates Water and Electricity Company procurement specifies grid-forming converter requirements for islanded operation during contingencies. Federal harmonic emission frameworks align with IEC 62786 standards for terminal distortion limits. Dubai and Abu Dhabi load centers anchor cross-border interconnection investment through Gulf Cooperation Council initiatives.
Qatar
Grid synchronization with Saudi and UAE networks requires bidirectional power flow capability at converter terminals. The country's national electricity regulator enforces equipment certification protocols for Gulf interconnection compatibility. Industrial zones near Doha demand frequency regulation services through dedicated HVDC links.
Kuwait
Minimal existing HVDC infrastructure creates first-mover positioning for voltage source converter specialists. The Ministry of Electricity and Water oversees technical specifications for planned grid modernization programs. Planned corridors to Saudi load centers await final regulatory approval for capital allocation.
Oman
Renewable export mandates for remote solar and wind clusters necessitate long-distance transmission infrastructure. The Authority for Electricity Regulation develops interconnection codes for future UAE grid links. Dhofar and Al Wusta governorates host preliminary site assessments for converter station placement.
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Middle East HVDC procurement. Turnkey system architects capture premium contract values through single-source accountability structures. Component suppliers and regional fabricators occupy adjacent positions in station construction and maintenance services. Consolidation pressure intensifies as Gulf utilities favor extended contract durations with fewer vendor relationships.
Among integrated system architects, Siemens Energy, Hitachi Energy Ltd, and ABB occupy positions defined by converter technology portfolios and regional project footprints. Siemens Energy exemplifies the turnkey delivery archetype through engineering-procurement-construction bundling. Hitachi Energy Ltd represents voltage source converter specialization for renewable integration schemes. ABB anchors the hybrid configuration segment bridging legacy line-commutated retrofits with advanced semiconductor platforms.
| Leading Market Players |
|---|
| Hitachi Energy Ltd |
| Toshiba Corporation |
| Siemens Energy |
| Hyundai Heavy Industries |
| Mitsubishi Electric Corporation |
| ABB |
| Schneider Electric |
| Hyosung Group |
| General Electric |
| Others |
Supply & Pricing Matrix
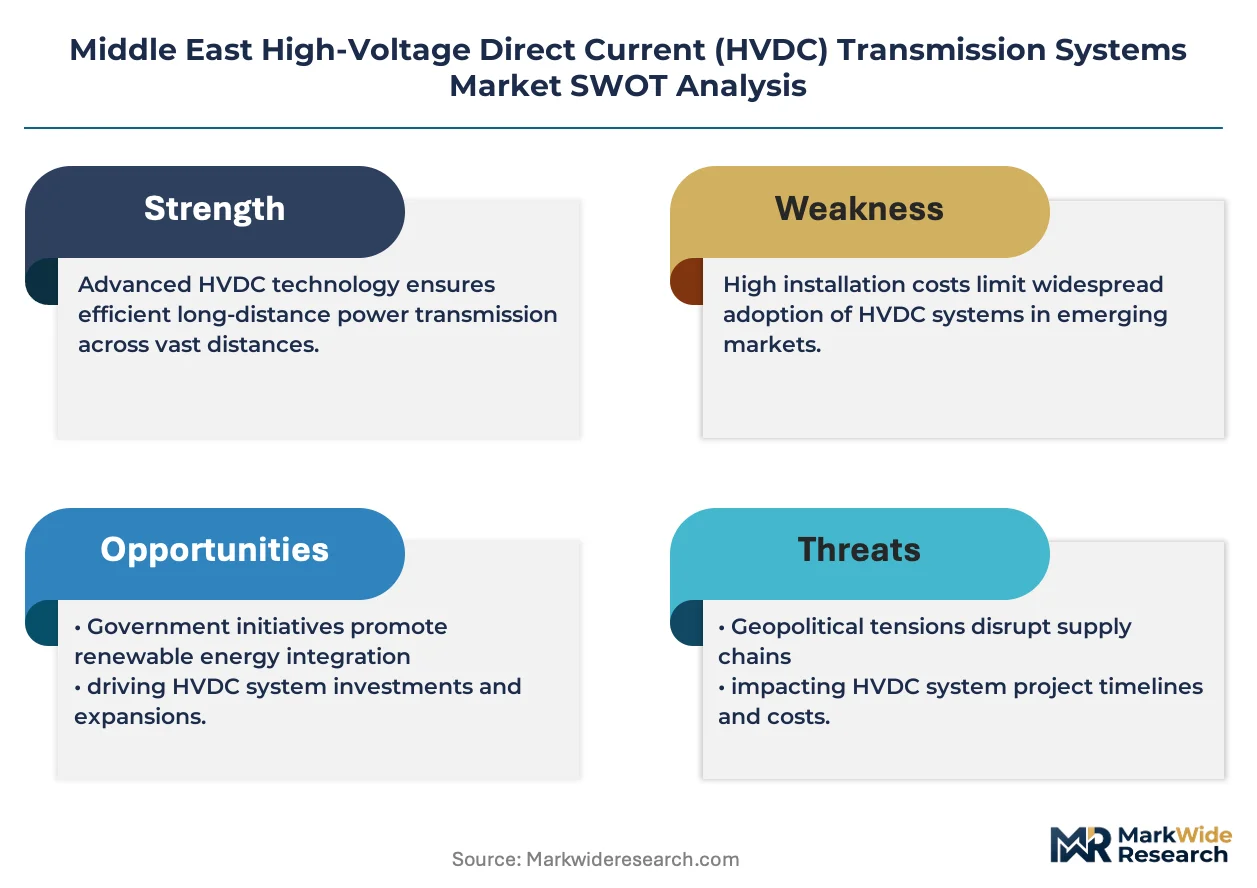
Converter station scale economies at 500 kV and above compress unit costs for integrated system architects while erecting price floors for component-only suppliers. Saudi Electricity Company turnkey mandates concentrate procurement around vendors with captive valve manufacturing, forcing tier-two competitors toward aftermarket service margins.
Pricing Analysis
After-sales revenue from valve maintenance contracts and IEC 62501 recertification services drives lifetime value for incumbent suppliers. Project-based pricing dominates converter station awards, with differentiation anchored in semiconductor junction temperature ratings and cooling system redundancy tiers. Cost compression in line-commutated converter retrofits intensifies as ABB and regional specialists compete on replacement valve volume. Independent Power Producers exhibit acute price sensitivity on export link tenders, while Utility Providers absorb premium bids for black-start capability specifications.
Supply Chain Analysis
IGBT and silicon carbide module inventories at six-to-nine month lead times expose Gulf project schedules to East Asian foundry utilization swings. Semiconductor fabrication concentrates in Japan, Germany, and South Korea, with Saudi Electricity Company evaluating SiC sourcing from multiple qualified vendors. Critical dependencies include high-purity copper busbar, ceramic substrate materials, and synthetic cooling fluids. Single-source vulnerability in advanced SiC wafer supply threatens 500 kV station delivery schedules. Distribution runs through engineering-procurement-construction contractors with single-source accountability to Saudi Electricity Company and Emirates Water and Electricity Company.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East HVDC market is recovering from a cyclical trough as renewable export mandates across Saudi Arabia and the UAE reactivate capital allocation. Saudi Electricity Company procurement volumes serve as the primary cyclical indicator.
For Market Incumbents: Consolidate valve testing and certification capabilities to capture IEC 62501-mandated replacement cycles. Deepen relationships with Emirates Water and Electricity Company through grid-forming converter demonstration projects. Threat substitution from modular multilevel converter architectures demands accelerated SiC platform investment. Backward integration into cooling system manufacturing defends margin pools against component suppliers. For New Entrants and Emerging Players: Anchor in Oman's preliminary site assessments at Dhofar and Al Wusta governorates where Authority for Electricity Regulation interconnection codes remain under development. Kuwait's Ministry of Electricity and Water planned corridors to Saudi load centers represent the most penetrable geography with minimal incumbent presence. Target hybrid AC-DC substation retrofit specifications in the UAE where 380 kV corridor overlays avoid full right-of-way replacement costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converter station specialists with captive service contracts across Saudi Electricity Company and Emirates Water and Electricity Company installed bases. Long-term viability over the next decade rests on semiconductor technology transition execution and Gulf utility relationship depth. Acquisition targets should demonstrate valve hall commissioning capabilities and IEC 62501 testing infrastructure. The signal to watch is Saudi Electricity Company tender volume for Al-Faisaliah solar complex export links.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Platform Transition | Reduces cooling load for Saudi Electricity Company 500 kV desert links. |
| Turnkey EPC Consolidation | Compresses supplier margins while extending contract durations with Gulf utilities. |
| Black-Start Certification | Opens grid-forming converter awards under Emirates Water and Electricity Company frameworks. |
| Oman Market Entry | Captures first-mover positioning before Authority for Electricity Regulation finalizes codes. |
| Active Filter Integration | Meets mandatory IEC 62786 harmonic compliance for UAE terminal installations. |
Research Methodology
Cross-validation between primary interviews with converter station project managers and secondary analysis of Saudi Electricity Company tender documentation anchors the qualitative findings. Utility planning officers at Emirates Water and Electricity Company, EPC contractors active in Riyadh corridor projects, and power electronics engineers qualified for voltage source converter commissioning provided operational perspective. Secondary sources include IEC standards documentation, Gulf Cooperation Council grid harmonization initiative filings, and customs records for semiconductor module imports. Bottom-up project pipeline aggregation triangulates against top-down utility capital expenditure disclosures.
Sensitivity analysis across semiconductor cost trajectories and desert climate degradation assumptions tests forecast robustness. The analytical framework segments by converter technology topology, application context, and end-user procurement sophistication across the projection horizon. Technology transition velocity from line-commutated to voltage source converter platforms, renewable export mandate enforcement intensity, and Gulf utility staffing constraints for specialized commissioning labor inform modeled outcomes. CAGRs derive from utility disclosed project timelines and equipment replacement cycle mandates.
Decision-makers should treat outputs as directional under sustained Saudi renewable export policy commitment and stable East Asian semiconductor supply; material deviation would warrant model refresh. Specific risks include regulatory delay in Kuwait corridor approvals and accelerated thermal cycling failure rates exceeding European baselines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
DC Distribution Network Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Natural Gas Refueling Infrastructure Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Gas Insulated Transmission Lines Market