
 Transmission Towers Market | 2026-2036
Transmission Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Towers Market Analysis
The gap between premium high-voltage steel towers and commodity low-voltage wooden structures is restructuring procurement patterns across global utilities. KEC International Ltd. leverages integrated manufacturing from galvanizing to final assembly, sustaining cost advantages on large cross-border contracts. Tata Power Company Limited anchors captive demand through its utility arm while competing for third-party EPC work, and Skipper Limited specializes in monopole and tubular designs for constrained urban corridors.
Transmission towers are lattice or pole structures fabricated from galvanized steel, concrete, or engineered wood composites, designed to carry overhead power conductors at specified mechanical loads and electrical clearances. Steel towers dominate intercity high-voltage corridors due to span capability exceeding 400 meters and tensile strength above 350 MPa. Smart Grid Technology segments are expanding fastest as utilities embed sensors and dynamic line rating systems, while Concrete Towers command premium margins in coastal and seismic zones where corrosion and fatigue resistance override first-cost considerations. Hybrid Towers occupy a niche at the intersection of aesthetic constraints and structural performance, particularly in European urban installations where visual impact regulations tighten.
FERC Order 1920 in the United States mandates long-term transmission planning with cost-socialization mechanisms, directly expanding the addressable market for extra-high-voltage infrastructure. The EU Green Deal and REPowerEU framework accelerate cross-border corridor approvals, while India's CEA technical standards enforce progressively higher wind-load and seismic specifications on tower designs. Stakeholders must monitor how divergent national certification regimes affect modular tower platform economics and supplier qualification timelines.
Market Dynamics
Grid interconnection mandates are forcing utilities to upgrade from 220 kV to 765 kV corridors, compressing procurement cycles and favoring suppliers with integrated galvanizing and structural testing capabilities.
Growth Catalysts
- REPowerEU corridor approvals:Cross-border transmission projects between Germany, Spain, and Portugal accelerate demand for extra-high-voltage steel lattice designs with 400-meter span capability.
- India's national grid expansion:State utilities under CEA technical standards are procuring 765 kV double-circuit towers for renewable evacuation zones in Rajasthan and Gujarat.
- Dynamic line rating systems:Smart sensors embedded in conductor hardware allow real-time thermal monitoring, enabling utilities to defer reconductoring investments.
Market Restraints
- Zinc price volatility:Hot-dip galvanizing accounts for 12-18% of tower material cost, and LME zinc fluctuations compress fabricator margins on fixed-price EPC contracts.
- Specialized steel supply concentration:High-strength structural angles above 350 MPa tensile strength source primarily from Chinese and Indian integrated mills, creating geographic concentration risk.
- Right-of-way constraints:Urban densification in Mumbai, São Paulo, and Jakarta forces route deviations that increase foundation costs and extend project timelines.
Strategic Opportunities
- Vietnam and Philippines grid buildout:Both markets lack domestic tower fabrication capacity above 500 kV, creating import substitution openings for Indian and Chinese suppliers with ASEAN logistics networks.
- Offshore wind export cables:Submarine HVAC and HVDC platforms require specialized jacket foundations and transition piece towers, a category distinct from onshore lattice structures.
- FERC Order 1920 cost-socialization:US regional transmission organizations now aggregate benefits across multiple states, expanding the addressable market for merchant transmission developers.
Industry Challenges
- Weld inspector certification bottlenecks:AWS D1.1 structural welding codes require specialized inspectors, and training program capacity lags tower fabrication expansion in India and Southeast Asia.
- Type-test documentation timelines:IEC 60652 full-scale tower testing protocols demand 12-18 months for new 765 kV designs, delaying qualification for urgent procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Towers Market |
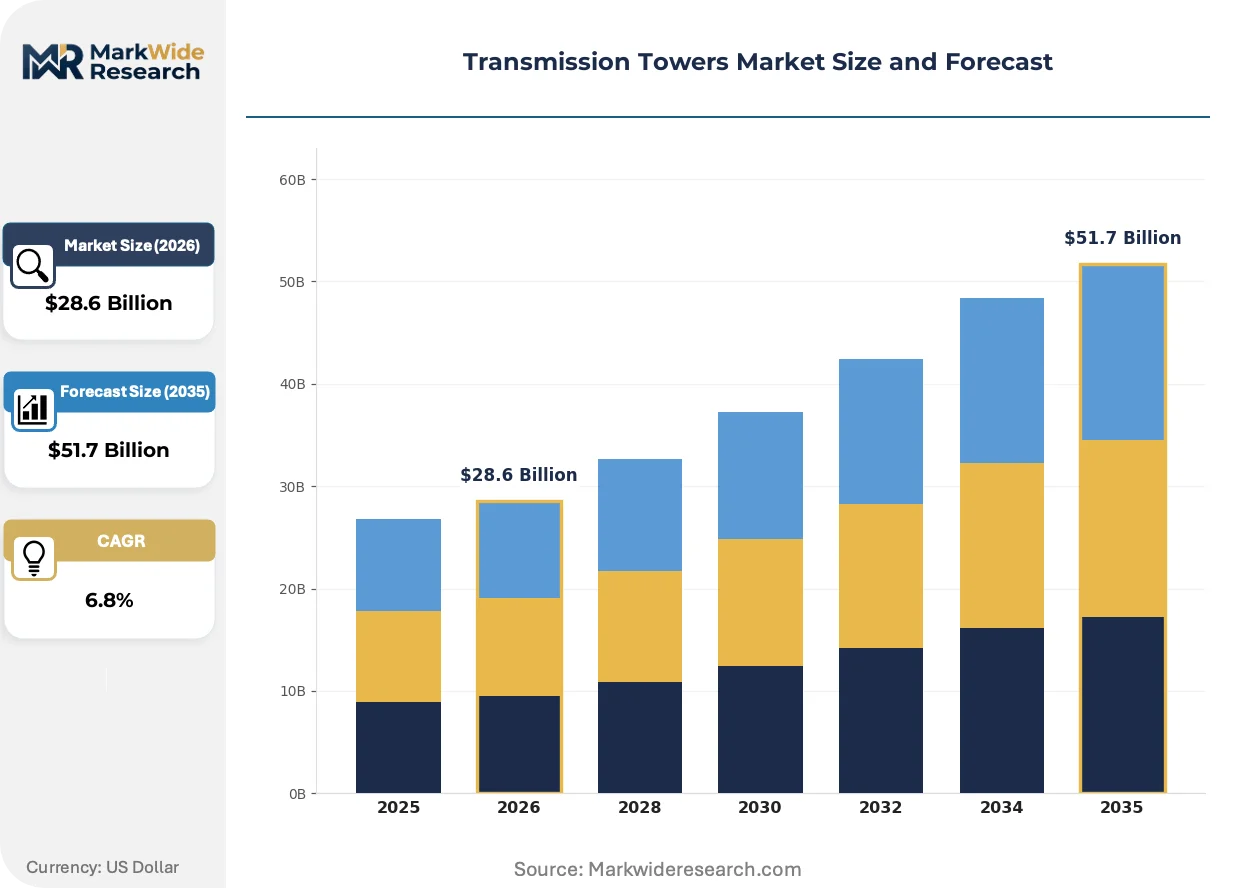
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Towers, Wooden Towers, Concrete Towers, Hybrid Towers Technology: High Voltage Transmission, Medium Voltage Transmission, Low Voltage Transmission, Smart Grid Technology Installation Type: Onshore, Offshore, Urban, Rural End User: Utilities, Independent Power Producers, Industrial, Commercial |
| Companies Covered | KEC International Ltd., Utkarsh India Limited, Jyoti Structures Limited, Quanta Services, Valard Construction, Burns & McDonnell, Skipper Limited, Tata Power Company Limited, MasTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Towers Market Emerging Trajectories
Material substitution and embedded intelligence are redefining tower lifecycle economics. Fabricators now compete on total cost of ownership rather than steel tonnage pricing.
Corrosion-resistant weathering steel grades are expanding into coastal transmission corridors where hot-dip galvanizing alone proves insufficient. Spanish and Portuguese utilities operating near Atlantic salt spray deploy these alloys to extend service intervals. The technology is expanding into North Sea offshore substation platforms where maintenance access requires helicopter or vessel mobilization.
The EU Green Deal's embodied carbon disclosure requirements under CSRD are forcing tower fabricators to document Scope 3 emissions from ore extraction through galvanizing. German transmission system operators now weight carbon intensity at 15-20% in technical bid evaluation criteria. This regulatory pressure is compressing market share for mills without electric arc furnace capability or renewable energy-powered galvanizing lines.
Utility procurement departments are consolidating tower purchases into multi-year framework agreements with price adjustment clauses tied to steel scrap and zinc indices. Brazilian federal utility Eletrobras shifted from project-specific tenders to five-year supply contracts in 2023, requiring fabricators to maintain buffer stock at regional marshalling yards. This behavioral shift concentrates volume with suppliers possessing integrated logistics and working capital depth.
Transmission Towers Market Segmentation
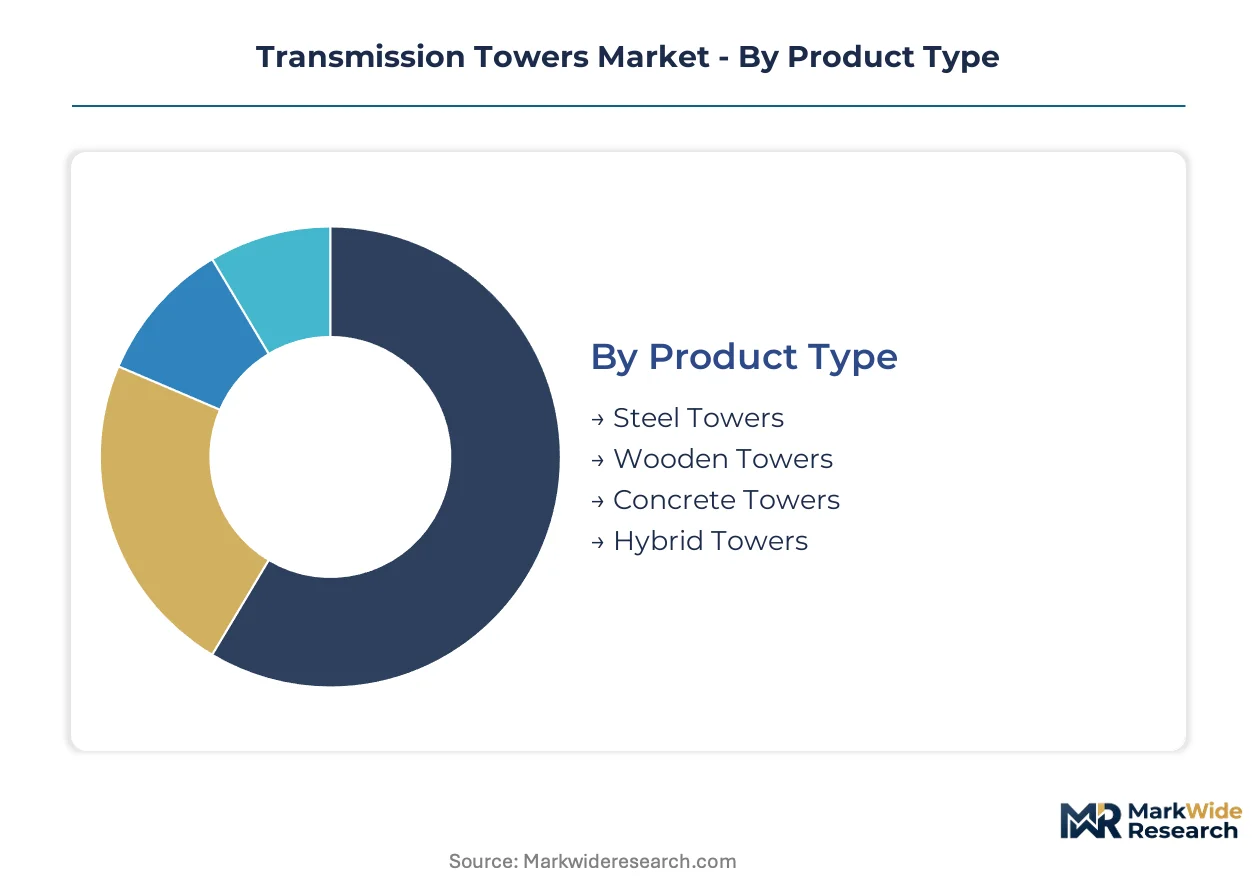
Tower material selection and voltage rating specifications determine procurement economics across transmission infrastructure programs. Segment boundaries reflect divergent fabrication capabilities, regulatory certification requirements, and lifecycle cost structures that reshape supplier qualification criteria.
Product Type:
Supply concentration in galvanizing capacity and structural steel rolling mills favors fabricators with integrated upstream control over angle production and corrosion protection.
- Steel Towers:Fabricated from galvanized structural angles with tensile strength exceeding 350 MPa, these lattice designs dominate intercity corridors requiring spans above 400 meters. Demand concentrates in India's renewable evacuation zones under CEA technical standards, where state utilities procure 765 kV double-circuit configurations for Rajasthan and Gujarat solar parks. Zinc price volatility on LME contracts compresses fabricator margins on fixed-price EPC agreements.
- Concrete Towers:Prestressed spun concrete or cast-in-place designs command premium positioning in coastal and seismic zones where fatigue resistance overrides first-cost considerations. Portuguese and Spanish utilities operating near Atlantic salt spray deploy these alloys to extend service intervals where maintenance access requires vessel mobilization. EU Green Deal embodied carbon disclosure requirements under CSRD force documentation of Scope 3 emissions from ore extraction through curing.
- Wooden Towers:Laminated timber and engineered wood composites serve low-voltage distribution networks with span requirements below 100 meters and aesthetic constraints in protected landscapes.
- Hybrid Towers:Steel-concrete composite or steel-timber configurations occupy niche positioning at the intersection of structural performance and visual impact regulations tightening across European urban installations.
Steel towers absorb the bulk of installed capacity; hybrid configurations are expanding most quickly as visual impact regulations tighten.
Technology:
Voltage tier segmentation tracks grid interconnection mandates forcing upgrades from legacy 220 kV corridors to extra-high-voltage infrastructure.
- Smart Grid Technology:Sensor-embedded conductor hardware enables dynamic line rating systems with real-time thermal monitoring, allowing utilities to defer reconductoring investments. REPowerEU corridor approvals between Germany, Spain, and Portugal accelerate procurement of instrumented towers with 400-meter span capability and embedded fiber-optic pathways. FERC Order 1920 cost-socialization mechanisms expand addressable market for merchant transmission developers deploying these systems.
- High Voltage Transmission:Extra-high-voltage corridors at 400 kV and above require lattice designs with specialized foundation engineering for load ratings exceeding 60 tons. Procurement cycles compress as utilities accelerate renewable evacuation timelines.
- Medium Voltage Transmission:66-220 kV configurations balance material efficiency against span capability for regional interconnection.
- Low Voltage Transmission:Distribution-level structures below 66 kV prioritize cost minimization over structural redundancy for last-mile connectivity.
High voltage transmission holds the largest installed base; smart grid technology is climbing the fastest as embedded intelligence redefines lifecycle economics.
Installation Type:
Site constraints and foundation costs create divergent margin structures across terrain categories, with offshore and urban installations commanding specialized engineering premiums.
- Onshore:Conventional lattice towers on drilled pier or pad foundations dominate volume, with standardization enabling modular platform economics across multiple procurement cycles.
- Offshore:Jacket foundations and transition piece towers for submarine HVAC and HVDC platforms require marine-grade corrosion protection and specialized welding protocols. North Sea substation platforms deploy weathering steel grades where helicopter or vessel mobilization constrains maintenance access.
- Urban:Right-of-way constraints in Mumbai, São Paulo, and Jakarta force route deviations that increase foundation costs and extend project timelines. Monopole and tubular designs from specialists like Skipper Limited serve constrained corridors.
- Rural:Lower land acquisition costs and simpler permitting enable standardized lattice designs with minimal aesthetic modification.
Onshore installations retain the dominant share; offshore configurations are gaining share fastest as wind export cable buildouts accelerate.
End User:
Procurement consolidation into multi-year framework agreements concentrates volume with fabricators possessing integrated logistics and working capital depth.
- Utilities:State and federal transmission system operators anchor demand through national grid expansion mandates. Brazilian federal utility Eletrobras shifted from project-specific tenders to five-year supply contracts requiring buffer stock at regional marshalling yards.
- Independent Power Producers:Merchant renewable developers require rapid tower delivery for solar and wind evacuation timelines, favoring suppliers with qualified designs and regional fabrication capacity.
- Industrial:Captive power and private transmission infrastructure for mining, steel, and petrochemical complexes.
- Commercial:Data center and large facility interconnection drives demand for dedicated medium-voltage infrastructure.
Utilities command the predominant procurement volume; independent power producers are expanding most quickly behind renewable buildout acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raipur anchors India's transmission tower manufacturing corridor, with KEC International and Skipper Limited operating integrated facilities that supply 765 kV infrastructure for renewable evacuation zones.
United States
FERC Order 1920 mandates long-term transmission planning with cost-socialization mechanisms, expanding procurement for extra-high-voltage steel lattice designs. Regional transmission organizations now aggregate benefits across multiple states, creating larger addressable markets for merchant transmission developers. Texas and California utilities lead procurement volume for 345 kV and 500 kV corridors serving wind and solar zones.
Germany
REPowerEU corridor approvals accelerate cross-border projects linking renewable generation in northern regions to industrial load centers in Bavaria and Baden-Württemberg. The EU Green Deal's embodied carbon disclosure requirements under CSRD force fabricators to document Scope 3 emissions. German transmission system operators weight carbon intensity at 15-20% in technical bid evaluations, favoring mills with electric arc furnace capability.
India
State utilities under CEA technical standards procure 765 kV double-circuit towers for solar parks in Rajasthan and Gujarat. KEC International leverages integrated manufacturing from galvanizing to final assembly for cost advantages on large contracts. Skipper Limited specializes in monopole and tubular designs for constrained urban corridors in Mumbai and Delhi-NCR.
Brazil
Eletrobras shifted from project-specific tenders to five-year supply contracts in 2023, requiring fabricators to maintain buffer stock at regional marshalling yards. The national grid expansion prioritizes 500 kV corridors connecting Amazon hydropower to southeastern industrial zones. São Paulo's urban densification forces route deviations that increase foundation costs and extend timelines.
China
High-strength structural angles above 350 MPa tensile strength source primarily from domestic integrated mills serving both national grid expansion and export markets. The dual carbon goals framework accelerates deployment of ultra-high-voltage direct current corridors spanning 2,000+ kilometers from western generation bases to eastern load centers. Jiangsu and Shandong provinces concentrate fabrication capacity for galvanized steel lattice designs.
Transmission Towers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the transmission tower sector. Integrated fabricators with captive galvanizing and structural testing capabilities capture premium positioning on large cross-border contracts. Three archetypes dominate: integrated steel-angle producers with backward control over rolling mills, specialized monopole designers for urban constraints, and utility-captive manufacturers serving internal procurement. Consolidation pressure intensifies through multi-year framework agreements and working capital requirements for buffer stock maintenance.
Among India-based fabricators, KEC International Ltd., Skipper Limited, and Tata Power Company Limited exemplify distinct strategic positions within the competitive hierarchy. KEC International occupies the integrated-manufacturer archetype with control over galvanizing through final assembly. Skipper Limited represents the urban-specialist vector with technical focus on constrained corridor solutions. Tata Power Company Limited anchors the utility-captive model through internal demand from its transmission arm while competing selectively for third-party EPC work.
| Leading Market Players |
|---|
| KEC International Ltd. |
| Utkarsh India Limited |
| Jyoti Structures Limited |
| Quanta Services |
| Valard Construction |
| Burns & McDonnell |
| Skipper Limited |
| Tata Power Company Limited |
| MasTec |
| Others |
Supply Flow & Price Mechanics
LME zinc futures volatility cascades through hot-dip galvanizing costs into three distinct pricing tiers for transmission tower procurement, with integrated fabricators capturing margin buffers that commodity converters cannot replicate.
Pricing Analysis
Throughput-based pricing anchors long-term framework agreements, where utilities index payments to installed circuit-kilometers rather than steel tonnage. Certification grade under FERC Order 1920 and CEA technical standards separates premium qualified suppliers from standard-tier fabricators lacking full-scale test documentation. Price erosion runs through the economy tier as Chinese angle mills absorb zinc cost spikes through government-backed raw material subsidies. Merchant transmission developers show lowest price sensitivity, while state utilities under fiscal consolidation pressure drive hardest bargain on unit rates.
Supply Chain Analysis
Direct-to-utility channels handle national grid procurement volume, while EPC contractors intermediate merchant and industrial demand. High-strength structural angles above 350 MPa tensile strength concentrate in Chinese and Indian integrated mills. Raw material flows draw from zinc concentrate smelters in Australia and Peru, galvanized coil processors in Jiangsu and Shandong, and structural angle rolling mills in Raipur and Kolkata. Single-source vulnerability in specialized weld inspector certification creates qualification bottlenecks that extend supplier onboarding timelines. Distribution runs through regional marshalling yards maintained under multi-year buffer stock obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as multi-year framework agreements concentrate procurement volume with fabricators possessing integrated galvanizing and working capital depth, forcing sub-scale competitors toward exit or acquisition.
For Market Incumbents: Deepen backward integration into structural angle production to insulate margin from LME zinc volatility and Chinese mill pricing power. Secure AWS D1.1 inspector training partnerships to remove certification bottlenecks that delay qualification for urgent 765 kV procurement cycles. Reinforce positioning through captive galvanizing capacity that commodity converters cannot replicate. For New Entrants and Emerging Players: Launch via specialized monopole and tubular designs for constrained urban corridors in Mumbai, São Paulo, and Jakarta where right-of-way restrictions exclude conventional lattice competitors. Target Vietnam and Philippines grid buildout markets lacking domestic fabrication capacity above 500 kV. Prioritize ASEAN logistics partnerships over greenfield mill investment to compress market entry timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated manufacturers with captive galvanizing lines in India and China, where working capital requirements for buffer stock maintenance strain sub-scale competitors. Monitor IEC 60652 type-test documentation timelines as inflection indicator—accelerated qualification cycles signal procurement urgency that favors prepared suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Structural Angle Production | Captive supply of 350 MPa tensile strength steel insulates margin from Chinese mill pricing power and LME volatility. |
| AWS D1.1 Inspector Training Partnerships | Qualified weld inspectors remove certification bottlenecks that delay 765 kV design qualification under CEA standards. |
| Multi-Year Framework Agreement Conversion | Eletrobras-style five-year contracts with buffer stock obligations lock out competitors lacking working capital depth. |
| Urban Monopole Specialization | Skipper Limited's tubular designs for constrained corridors command engineering premiums that lattice fabricators cannot match. |
| CSRD Embodied Carbon Documentation | German TSO bid evaluations weighting carbon intensity at 15-20% favor electric arc furnace-equipped mills. |
Methodological Framework
Independent corroboration across utility procurement officers, EPC contractor project directors, and structural steel mill executives underwrites the qualitative findings. Primary fieldwork encompassed transmission system operator planning staff, tower fabrication plant managers, and galvanizing line operators across India, China, Germany, and Brazil. Secondary validation drew from FERC Order 1920 dockets, CEA technical standards circulars, EU Green Deal corridor approval documents, and customs data on structural angle trade flows. Bottom-up project pipeline aggregation triangulates against top-down grid investment forecasts from national regulator filings.
Rate-of-change decomposition separates volume drivers—circuit-kilometer additions across voltage tiers—from value drivers including smart grid sensor integration and corrosion-resistant alloy premiums. Segmentation modeling spans material type, voltage rating, installation terrain, and end-user procurement consolidation status. CAGRs derive from regression against historical grid investment cycles and renewable evacuation mandates. Forecast inputs incorporate REPowerEU corridor approval timelines, India's national solar park buildout schedules, and FERC cost-socialization implementation progress across regional transmission organizations.
The model assumes a particular technology adoption path; alternative pathways for dynamic line rating sensor deployment or weathering steel substitution would alter the outlook. Forecasts reflect base-case assumptions regarding zinc price stabilization and weld inspector training program expansion. Regulatory acceleration or delay in cross-border corridor approvals represents primary forecast revision risk. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
High Voltage Transmission Substation Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Electrical Substation Management Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Substation Grounding System Market