
 North America High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
North America High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America High-Voltage Direct Current (HVDC) Transmission Systems Market Analytics
Software-defined grid control services is restructuring how HVDC projects are monetized beyond hardware delivery. Siemens Energy leverages its digital twin platforms to extend recurring revenue streams across installed converter stations. Hitachi Energy anchors its North American position through specialized maintenance contracts for aging LCC infrastructure. GE Vernova competes by integrating predictive analytics into its VSC offering, differentiating on outage reduction guarantees.
High-Voltage Direct Current transmission systems employ power electronic converters to transmit bulk electricity across distances exceeding 600 kilometers with losses below 3% per 1,000 km, primarily serving asynchronous grid interconnection and remote renewable resource evacuation. Voltage Source Converter technology leads new project awards due to superior black-start capability and compact footprint, while Line Commutated Converter installations retain dominance in legacy high-capacity corridors where retrofit economics favor component replacement over full technology swaps. Modular Multilevel Converter architectures command premium pricing in offshore wind collector applications where harmonic performance requirements are most stringent.
FERC Order 2023 interconnection reforms and NERC reliability standards are compressing project timelines while raising cybersecurity mandates for control system procurement. The EPA's greenhouse gas performance standards for power sector infrastructure are directing utility capital toward zero-emission transmission corridors that HVDC uniquely enables. Stakeholders must monitor how state-level renewable portfolio standards in California, Texas, and New York reshape interregional transmission planning priorities against evolving federal cost allocation frameworks.
Market Dynamics
The US Inflation Reduction Act tax credits are compressing utility investment timelines and redirecting capital toward zero-emission transmission corridors that HVDC uniquely enables across asynchronous grid zones.
Growth Catalysts
- Offshore wind procurement:Atlantic coast developers are expanding submarine cable link orders to connect lease areas to onshore substations. This creates dedicated demand for Modular Multilevel Converter architectures with stringent harmonic performance requirements.
- FERC Order 2023:Interconnection reforms are accelerating queue processing for bulk transmission projects while mandating cybersecurity hardening in control system procurement specifications.
- California renewable portfolio standards:State-level mandates are reshaping interregional transmission planning priorities toward long-distance delivery from desert solar zones to coastal load centers.
Market Restraints
- Copper and rare earth input volatility:Converter station manufacturing depends on concentrated supply of neodymium and dysprosium for magnetic components, with pricing swings compressing project EPC margins.
- LCC infrastructure lock-in:Legacy Line Commutated Converter corridors in the US Midwest retain economic dominance where retrofit economics favor component replacement over full VSC technology swaps.
- NERC reliability compliance friction:Cybersecurity mandates for control systems are extending procurement cycles and raising qualification barriers for non-incumbent suppliers.
Strategic Opportunities
- Texas ERCOT interconnection:The isolated grid's renewable buildout creates unserved demand for asynchronous ties to Eastern and Western interconnections through back-to-back converter stations.
- Software-defined grid services:Digital twin platforms and predictive analytics are opening recurring revenue streams beyond hardware delivery across installed converter station bases.
- EPA greenhouse gas performance standards:Power sector infrastructure rules are directing utility capital toward transmission corridors that enable coal retirement and remote renewable evacuation.
Industry Challenges
- Power electronics specialist scarcity:VSC converter design and commissioning requires rare expertise in semiconductor switching and harmonic filtering that utilities and EPCs struggle to staff.
- Multi-vendor integration complexity:Projects combining submarine cable suppliers with converter OEMs face interface risk between mechanical and electrical subsystems during offshore commissioning.
- State-federal cost allocation misalignment:Interregional projects spanning multiple RTOs face prolonged stakeholder negotiation over beneficiary-pays versus socialized rate-base treatment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America High-Voltage Direct Current (HVDC) Transmission Systems Market |
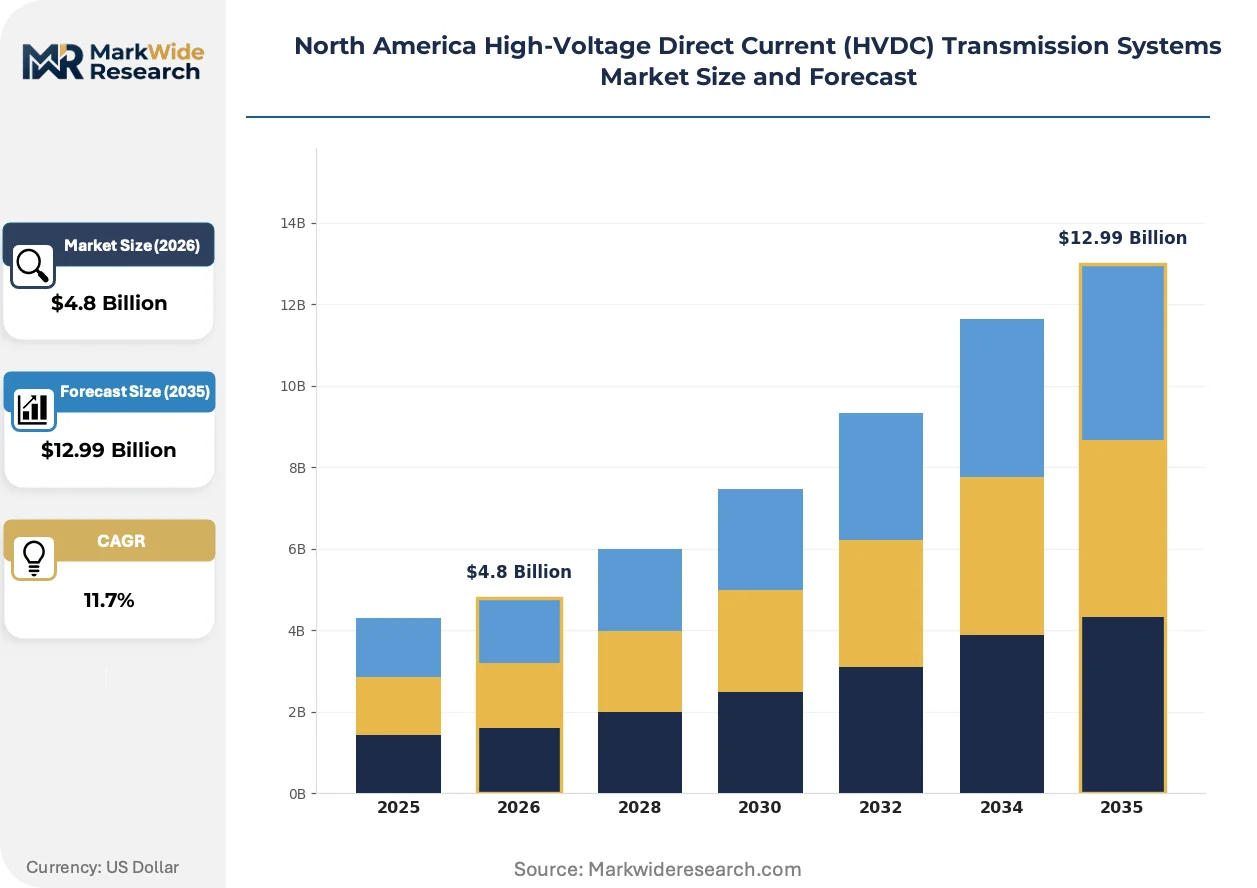
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LCC, VSC, MMC, Control Systems Application: Grid Interconnection, Renewable Integration, Long-Distance Transmission, Power Quality Improvement Component: Converter Stations, Transformers, Switching Equipment, Cables End User: Utilities, Industrial, Commercial, Renewable Energy Providers |
| Companies Covered | Siemens Energy, ABB Ltd., GE Vernova, Hitachi Energy, Toshiba Energy Systems & Solutions, Mitsubishi Electric Corporation, Prysmian Group, NKT A/S, LS Electric, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America High-Voltage Direct Current (HVDC) Transmission Systems Market Evolving Landscape
Technology convergence and procurement model evolution are restructuring how HVDC value is captured, with hardware margins compressing while software and service layers expand.
Modular Multilevel Converter technology is unifying the functional requirements of offshore wind collector platforms and long-distance land transmission. Developers from Massachusetts to Virginia are specifying MMC architectures for Atlantic lease areas to meet harmonic performance standards. This unifying trend collapses the distinction between inter-array and export cable converter functions, reducing offshore platform count.
FERC Order 2023 interconnection reforms are mandating standardized study processes and firm queue deadlines for transmission projects. The rules compress timeline uncertainty that previously discouraged HVDC investment in favor of lower-voltage AC alternatives. Texas and California utilities are restructuring internal project development teams to exploit the accelerated schedule.
Service contract unbundling is displacing traditional EPC wrap arrangements in converter station procurement. Texas municipal utilities and California IOUs are negotiating separate maintenance agreements with specialized providers rather than accepting OEM-captive service terms. This shift is most visible in aging LCC corridor retrofits where incumbent suppliers face independent challengers for long-term O&M scope.
North America High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
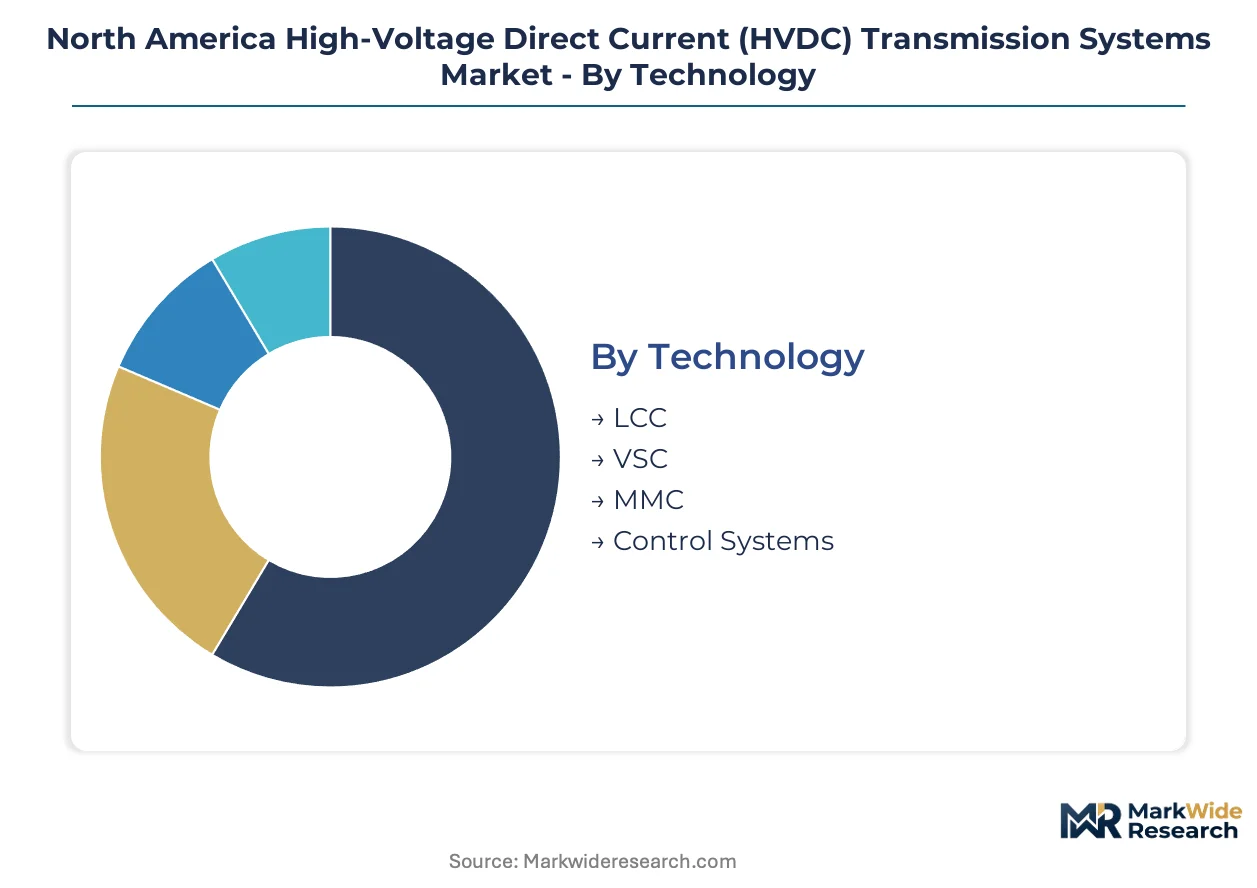
HVDC procurement decisions cascade through multiple technical and commercial dimensions. Converter technology selection locks in decades of operational characteristics. Application context determines voltage class and control architecture requirements.
Technology:
Converter station supply concentrates among power electronics specialists with captive semiconductor switching expertise.
- LCC:Thyristor-based converters handle the highest power ratings through mature commutation topologies. Demand concentrates in legacy US Midwest corridors where component replacement economics favor retrofit over full technology migration.
- VSC:IGBT-based Voltage Source Converters enable black-start capability and compact station footprints. Texas and California utilities specify VSC for new asynchronous ties to exploit superior grid-forming characteristics.
- MMC:Modular Multilevel Converter architectures stack submodules for harmonic performance. Atlantic offshore wind developers mandate MMC for collector platforms to meet stringent waveform standards.
- Control Systems:Software-defined protection and power flow management layers. FERC Order 2023 cybersecurity mandates are extending procurement cycles for control system qualification.
LCC absorbs the bulk of installed capacity; MMC is expanding most quickly.
Application:
Project economics diverge sharply based on whether transmission serves bulk power movement or grid stability functions.
- Grid Interconnection:Back-to-back converter stations link asynchronous zones without DC line infrastructure. ERCOT isolation creates unserved demand for ties to Eastern and Western interconnections.
- Renewable Integration:Collector systems aggregate remote wind and solar for long-distance evacuation. California desert solar zones and Texas Panhandle wind require dedicated converter capacity.
- Long-Distance Transmission:Overhead and submarine lines exceeding 600 kilometers exploit HVDC loss advantages. Atlantic coast lease areas drive submarine cable procurement.
- Power Quality Improvement:STATCOM and active filtering functions stabilize weak AC networks. Industrial load centers in Texas specify integrated quality services.
Renewable Integration commands the largest share of new project awards; Grid Interconnection shows the steepest expansion trajectory.
Component:
Converter station margins exceed cable and switching equipment due to power electronics complexity.
- Converter Stations:Valve halls containing series-connected semiconductor stacks represent the dominant cost center. Texas municipal utilities negotiate separate maintenance agreements to unbundle from OEM-captive terms.
- Transformers:Converter transformers interface between AC grid and valve bridge DC terminals. California IOUs specify dry-type designs for coastal corrosion environments.
- Switching Equipment:DC circuit breakers and disconnectors manage fault isolation in multi-terminal systems. Offshore platforms demand compact gas-insulated designs.
- Cables:Extruded XLPE submarine and land cables carry bipolar power flows. Atlantic lease procurement is compressing lead times for specialized cable-lay vessels.
Converter Stations capture the majority of project capital; Cables are climbing the fastest as offshore wind accelerates.
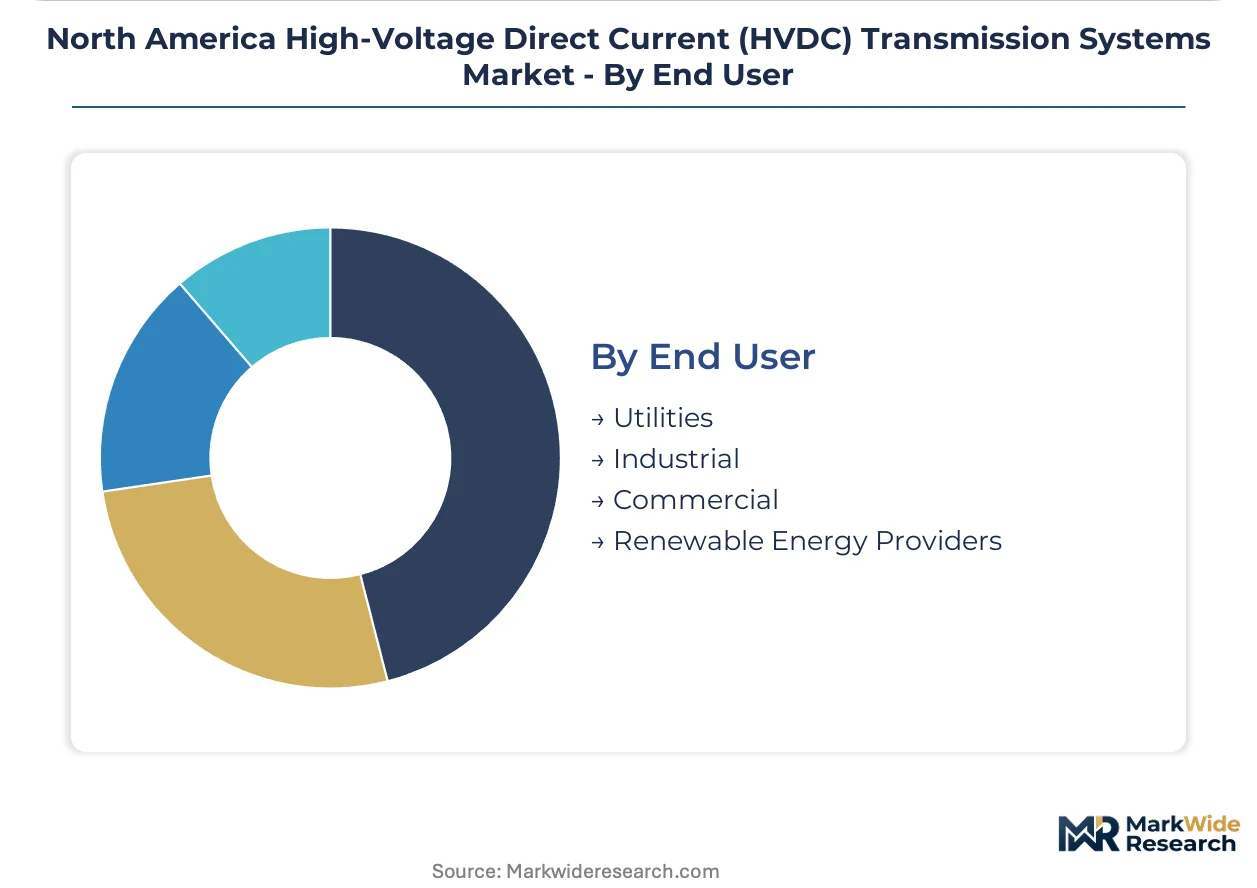
End User:
Utility procurement patterns diverge between regulated rate-base treatment and merchant development structures.
- Utilities:Investor-owned and public power entities dominate transmission ownership. California and Texas utilities restructure development teams to exploit FERC Order 2023 timeline compression.
- Industrial:Mining and petrochemical facilities procure dedicated interconnections for reliability. Texas Gulf Coast chemical clusters specify private HVDC links.
- Commercial:Data center and hyperscale cloud operators negotiate direct transmission access. Northern Virginia load growth is driving interconnection queue pressure.
- Renewable Energy Providers:Offshore wind developers and utility-scale solar IPPs procure collector and export infrastructure. Massachusetts-to-Virginia lease holders specify integrated converter platforms.
Utilities retain dominant procurement volume; Renewable Energy Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter station manufacturing concentrates in the United States while Canadian cable fabrication and Mexican component assembly round out the North American supply base. Texas and California utilities drive procurement volume through renewable integration mandates. Atlantic offshore wind lease areas from Massachusetts to Virginia anchor submarine cable demand.
United States
FERC Order 2023 interconnection reforms and IRA tax credits compress utility investment timelines across asynchronous grid zones. The EPA's greenhouse gas performance standards direct capital toward zero-emission transmission corridors. California desert solar zones and Texas Panhandle wind fields require dedicated converter capacity for coastal load center delivery.
Canada
Provincial crown corporations and hydroelectric exporters drive procurement of back-to-back converter stations for US interconnection. Natural Resources Canada programs support transmission infrastructure modernization. Quebec and Manitoba hydro corridors supply voltage-stabilized bulk power to Northeast US markets through dedicated DC links.
Mexico
Comisión Federal de Electricidad procurement prioritizes grid reinforcement for industrial load centers in Nuevo León and Baja California. Energy sector liberalization opens private participation in transmission infrastructure. Northern border states develop converter capacity to facilitate cross-border renewable export to Texas ERCOT.
Atlantic Coast States
Offshore wind lease holders from Massachusetts to Virginia specify Modular Multilevel Converter architectures for collector platforms. Bureau of Ocean Energy Management lease rounds accelerate submarine cable procurement timelines. Port infrastructure investments in New Bedford and Hampton Roads support cable-lay vessel mobilization.
Texas
ERCOT isolation creates unserved demand for asynchronous ties to Eastern and Western interconnections through back-to-back converter stations. Panhandle wind buildout and Permian solar zones require long-distance evacuation infrastructure. Gulf Coast chemical clusters specify private HVDC links for reliability-critical industrial loads.
North America High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
Top-tier vendors anchor converter station supply, while specialized cable fabricators and regional system integrators occupy supporting positions. The vendor base stratifies across three tiers: power electronics specialists with captive semiconductor expertise, full-line electrical equipment conglomerates, and niche submarine cable producers. Two strategic archetypes dominate: integrated platform providers bundling converter and cable scope, and unbundled specialists capturing maintenance and upgrade cycles. Competitive moves concentrate on digital service layer expansion and offshore wind platform integration partnerships.
Within the integrated platform tier, Siemens Energy and Hitachi Energy exemplify archetypes combining converter manufacturing with lifecycle service capture. GE Vernova occupies a position bridging power electronics and grid analytics. Among cable specialists, Prysmian Group and NKT A/S represent European-anchored fabricators with North American project execution capability. These five entities illustrate the competitive structure: two diversified industrial conglomerates, two cable-centric specialists, and one analytics-integrated challenger.
| Leading Market Players |
|---|
| Siemens Energy |
| ABB Ltd. |
| GE Vernova |
| Hitachi Energy |
| Toshiba Energy Systems & Solutions |
| Mitsubishi Electric Corporation |
| Prysmian Group |
| NKT A/S |
| LS Electric |
| Others |
Value Network & Pricing Analysis
Power electronics specialist scarcity in Texas and California widens pricing-tier spreads between premium MMC converter stations and standard VSC alternatives, as labor-cost differentials for semiconductor switching expertise compress margins on mid-tier offerings.
Pricing Analysis
Margin tightening in mid-tier VSC converter stations reflects copper and rare earth input volatility, with neodymium and dysprosium pricing swings compressing project EPC margins. Three-tier pricing structure across premium MMC, standard VSC, and economy LCC retrofit levels stratifies by harmonic performance certification and black-start capability. California IOUs and Texas municipal utilities show divergent price sensitivity, with merchant offshore wind developers least sensitive due to IRA tax credit absorption of capital premiums.
Supply Chain Analysis
NERC reliability compliance and FERC Order 2023 cybersecurity mandates gate qualification for control system suppliers, extending procurement cycles for non-incumbent vendors. Converter station manufacturing draws from concentrated semiconductor fabrication in the United States, Germany, and Japan, with cable fabrication anchored in Canada and European-anchored specialists. Neodymium and dysprosium dependencies for magnetic components create single-source vulnerability from concentrated rare earth processing. Distribution runs through EPC contractors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FERC Order 2023 cybersecurity mandates and NERC reliability standards erect barrier-to-entry moats for converter station suppliers with qualified control system platforms.
For Market Incumbents: Cement market position by capturing software-defined grid service revenue through digital twin platform deployment across installed converter bases. Deepen backward integration into semiconductor switching component supply to defend against rare earth price volatility. Prioritize certification maintenance for NERC reliability compliance to exclude non-qualified challengers from maintenance contract unbundling opportunities.
For New Entrants and Emerging Players: Enter via specialized maintenance contracts for aging LCC infrastructure in the US Midwest, where retrofit economics favor component replacement over full technology swaps. Target Texas ERCOT asynchronous interconnection demand as the most penetrable geography given isolated grid renewable buildout. Pursue joint development structures with Atlantic offshore wind lease holders to bypass incumbent converter OEM capture.
For Investors and Strategic Acquirers: Re-rating potential sits with power electronics specialists possessing captive semiconductor expertise given EPA greenhouse gas performance standards accelerating zero-emission transmission corridor investment. Long-term viability favors vendors with integrated platform capabilities spanning converter manufacturing and lifecycle service capture. Monitor FERC cost allocation framework evolution as the signal indicating interregional project financeability inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Siemens Energy extends recurring revenue streams beyond hardware delivery through predictive analytics integration. |
| Backward Integration into Semiconductors | Captive IGBT switching expertise insulates margins against rare earth price volatility in magnetic components. |
| Offshore Wind Platform Partnership | Integrated converter-cable scope reduces interface risk during Atlantic lease area commissioning. |
| LCC Retrofit Service Unbundling | Independent maintenance providers capture long-term O&M scope from OEM-captive terms in aging Midwest corridors. |
| ERCOT Interconnection Development | Back-to-back converter stations address unserved demand for asynchronous ties to Eastern and Western interconnections. |
Research Methodology
EIA power flow databases, FERC interconnection queue filings, and IEA transmission investment reports formed the secondary backbone, cross-referenced with primary interviews of utility planning officers, EPC contractors, IPP project developers, and grid operators. Bottom-up project pipeline aggregation and top-down regulatory impact assessment enabled triangulation across data sources.
Historical trendline analysis of converter station awards and cable procurement volumes established baseline growth patterns across the projection horizon. Segmentation modeling incorporated converter technology tier, application context, component category, and end-user procurement structure. CAGRs derived from capacity-weighted project timelines and investment cycle compression effects under IRA tax credit acceleration.
Revisions become necessary when FERC cost allocation rulings, NERC cybersecurity mandate enforcement intensity, or rare earth supply disruption materialize. Forecasts reflect assumptions of sustained renewable portfolio standard compliance trajectories in California, Texas, and New York. A model refresh is warranted upon material change in Atlantic offshore wind lease round timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Natural Gas Refueling Infrastructure Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Electrical Substation Management Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Electricity Transmission Infrastructure Market