
 Leadless Cardiac Pacemaker Market | 2026-2036
Leadless Cardiac Pacemaker Market Size, Share, and Industry Trends Forecast 2026-2036
Leadless Cardiac Pacemaker Market Outlook
Hospital procurement channels for leadless pacemakers is tilting toward value-based contracting and bundled payment models. Abbott Laboratories leverages its electrophysiology portfolio to sustain integrated cath-lab offerings. Medtronic plc anchors North American volume through extensive physician training networks. Boston Scientific Corporation competes on dual-chamber technology development and European regulatory momentum.
A leadless cardiac pacemaker is a self-contained, catheter-delivered device that eliminates transvenous leads and generator pockets, typically operating at 2.5–3.0 V with lithium carbon monofluoride batteries and fixation mechanisms such as tines or screws. It treats bradyarrhythmia by sensing and pacing directly from the right ventricle or atrium without vascular hardware. Wireless technology leads current adoption due to real-time remote monitoring integration, while dual chamber systems represent the fastest-growing product type as manufacturers solve atrioventricular synchronization challenges. Single chamber devices occupy the mature volume tier, though margin pools increasingly favor custom solutions for complex anatomies.
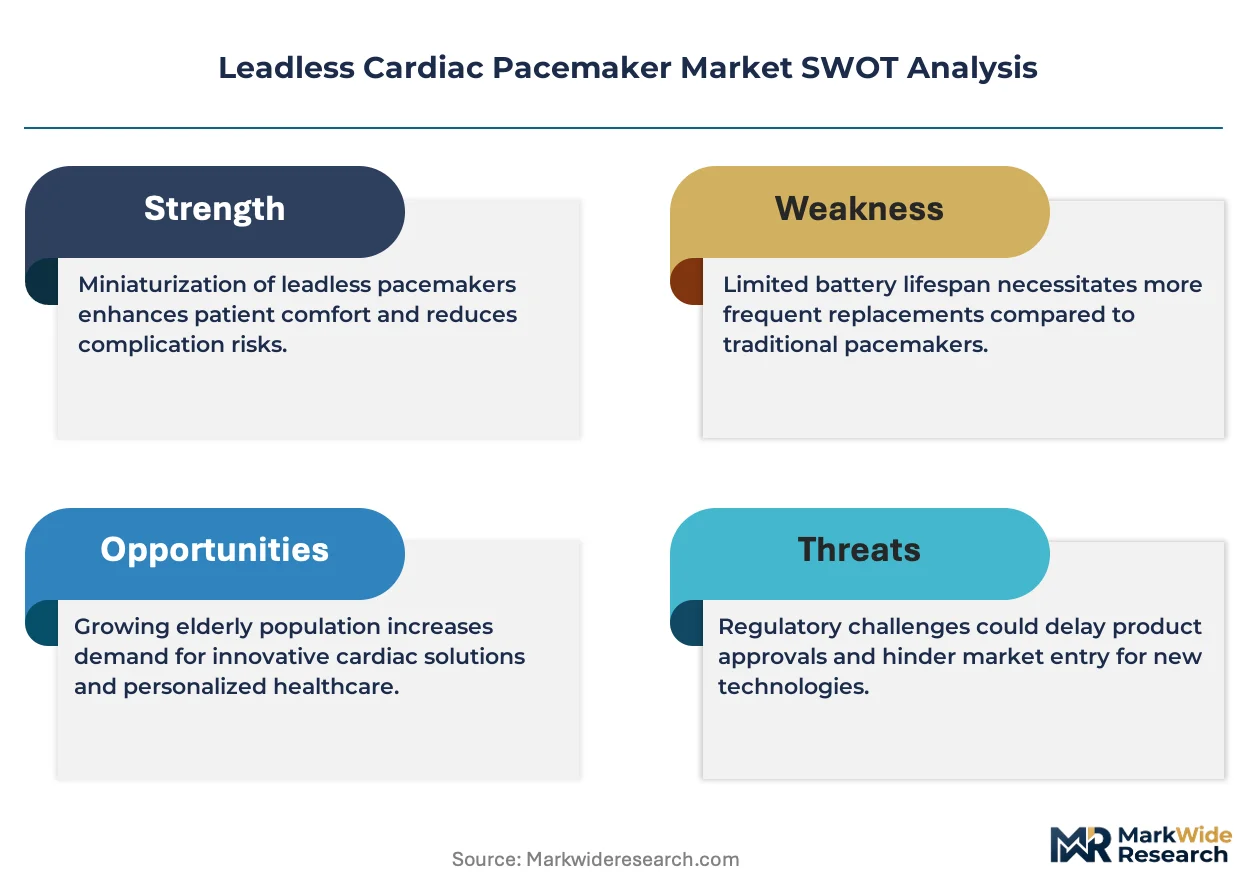
FDA premarket approval and EU MDR conformity assessment shape product development timelines and clinical trial investment for manufacturers. Japan's PMDA and China's NMPA impose distinct localization requirements that filter market access. Stakeholders must monitor evolving reimbursement decisions for outpatient catheterization procedures and anticipate how battery-less energy harvesting technologies will alter device lifecycle economics.
Market Dynamics
The transition from single-chamber to dual-chamber leadless systems is compressing product lifecycles and forcing manufacturers to solve atrioventricular synchronization without transvenous bridging. Battery longevity limitations and retrieval complexity are simultaneously extending clinical trial timelines and tightening FDA premarket approval evidence requirements.
Growth Catalysts
- Aging demographics in developed economies:Germany, Japan, and the United States face expanding elderly populations with elevated bradyarrhythmia incidence, creating procedural demand that catheterization labs are scaling to accommodate.
- EU MDR conformity pathways:The Medical Device Regulation's tightened clinical evidence standards, while stringent, are accelerating differentiation toward manufacturers with robust trial infrastructure and post-market surveillance capabilities.
- Catheter-delivered fixation mechanisms:Advances in tine and screw-based anchoring systems are reducing dislodgment rates and enabling broader anatomical candidacy for leadless implantation.
Market Restraints
- Lithium carbon monofluoride battery chemistry:Finite energy density limits device longevity to approximately 12-16 years, creating replacement burden and lifecycle cost accumulation for health systems.
- Retrieval complexity:Chronic implantation leads to fibrotic encapsulation, complicating device extraction and elevating referral concentration to specialized extraction centers in major metropolitan clusters.
- Reimbursement heterogeneity:Outpatient catheterization procedure coding varies across United States Medicare Administrative Contractors, creating access friction and volume concentration in favorable jurisdictions.
Strategic Opportunities
- Battery-less energy harvesting:Piezoelectric and thermoelectric systems that convert cardiac mechanical energy or body heat into electrical pacing stimulus represent a fundamental disruption to device lifecycle economics.
- Japan's PMDA Sakigake designation:Expedited review pathways for breakthrough devices create first-mover advantage windows for dual-chamber systems addressing unmet synchronization needs.
- Remote monitoring integration:Wireless telemetry infrastructure enables predictive replacement scheduling and reduces emergency department utilization, aligning with United States value-based care incentives.
Industry Challenges
- Electrophysiologist training bandwidth:Leadless implantation requires specialized catheter skills distinct from transvenous techniques, constraining procedural scaling to centers with dedicated fellowship pipelines.
- Long-term retrieval protocol standardization:Absence of consensus guidelines for device management at battery end-of-life creates liability exposure and complicates informed consent processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leadless Cardiac Pacemaker Market |
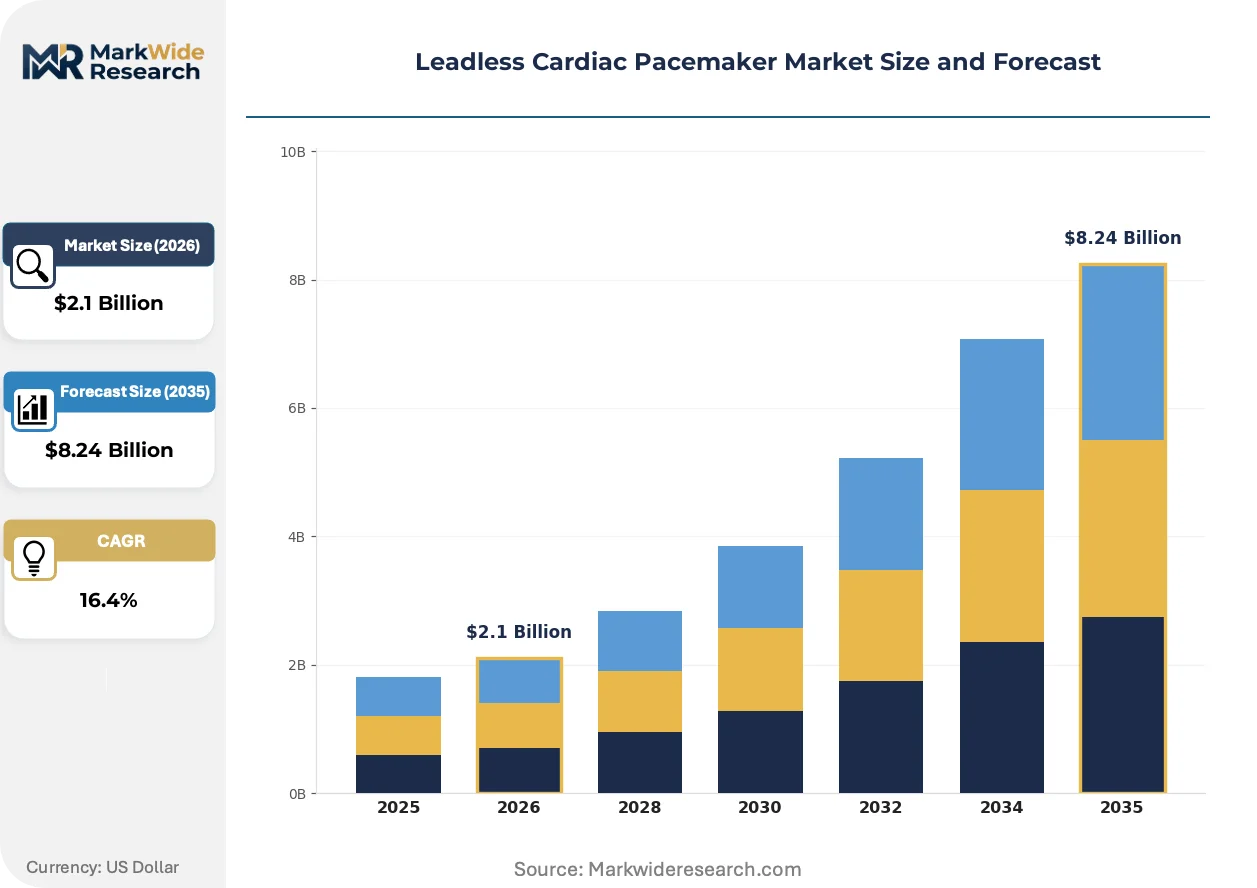
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.24 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wireless, Implantable, Remote Monitoring, Battery-less End User: Cardiology Clinics, Hospitals, Research Institutions, Home Care Product Type: Single Chamber, Dual Chamber, Multi-site, Custom Solutions Application: Arrhythmia Management, Heart Rate Regulation, Cardiac Resynchronization, Others |
| Companies Covered | BIOTRONIK SE & Co. KG, MicroPort Scientific Corporation, Abbott Laboratories, LivaNova plc, AtriCure, Inc., Medtronic plc, EBR Systems, Inc., CAIRDAC, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leadless Cardiac Pacemaker Market Strategic Shifts
Convergence between leadless pacing and advanced cardiac monitoring is redefining device value propositions, while regulatory frameworks on both sides of the Atlantic are accelerating evidence-generation requirements.
Dual-chamber leadless technology is hybridizing cardiac rhythm management by enabling atrioventricular sequential pacing without transvenous leads. Major electrophysiology centers in Germany and the United States are adopting these systems for patients with atrioventricular block who previously required conventional pacemakers. This convergence is compressing the addressable market for single-chamber devices while expanding procedural eligibility criteria.
The FDA's premarket approval pathway for novel pacing modalities is intensifying clinical trial investment requirements. Manufacturers must now demonstrate not only acute safety but long-term retrieval feasibility and battery performance under real-world conditions. Dual-chamber submissions are experiencing the most scrutiny, with the agency demanding extended follow-up periods that delay commercialization timelines.
Hospital cath-lab procurement is consolidating around bundled payment models that encompass device, procedure, and follow-up monitoring. Integrated delivery networks in the United States are displacing traditional fee-for-service purchasing through multi-year contracts tied to outcome metrics. This restructuring concentrates volume among manufacturers with comprehensive electrophysiology portfolios and remote monitoring infrastructure.
Leadless Cardiac Pacemaker Market Segmentation
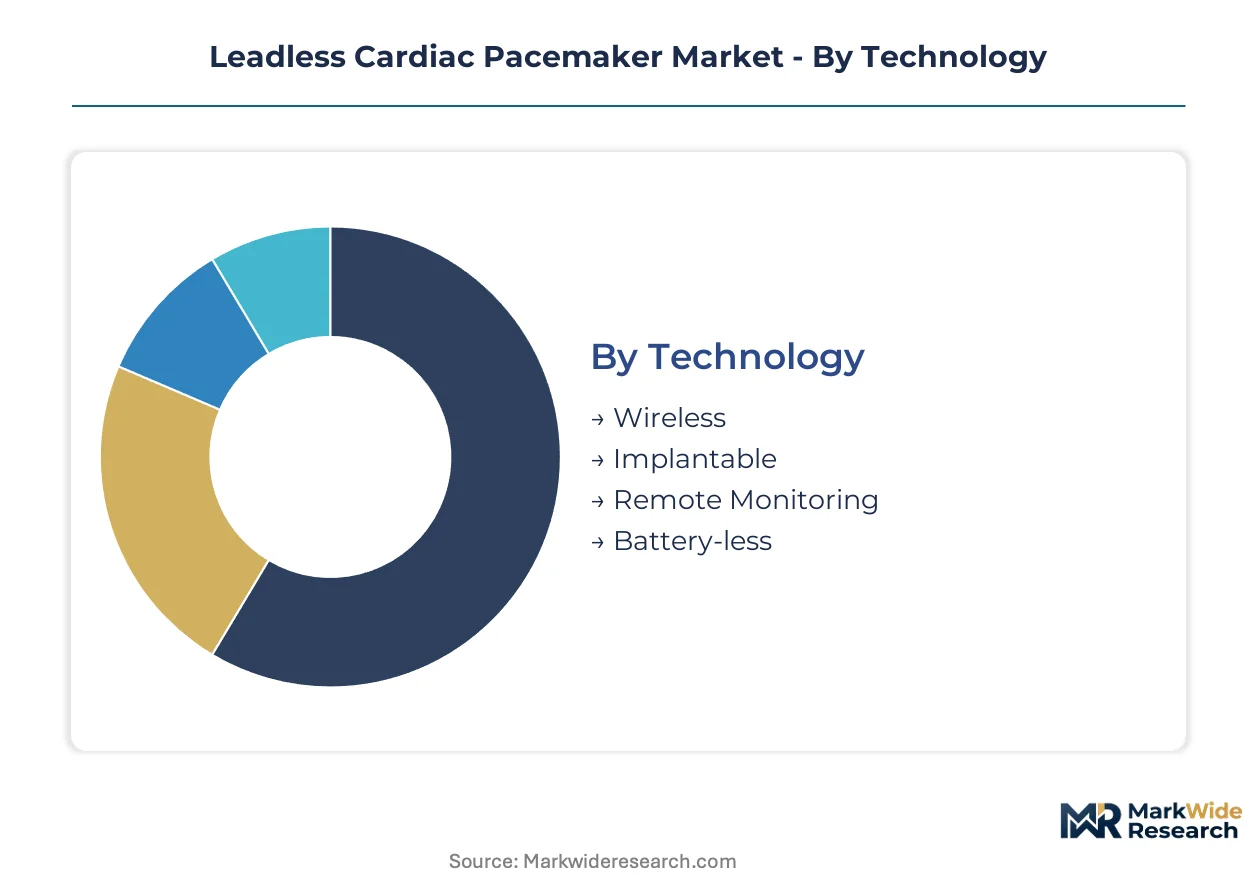
Leadless pacemaker segmentation reveals how technology maturity, clinical setting economics, and procedural complexity intersect to shape manufacturer R&D allocation and hospital procurement priorities across distinct patient anatomies and care pathways.
Technology:
Mature wireless systems anchor current volume, while emerging energy-harvesting architectures promise to disrupt device lifecycle economics entirely.
- Wireless:Radiofrequency telemetry enables real-time data transmission to cloud-based monitoring platforms. Demand concentrates in United States integrated delivery networks where remote patient management aligns with Medicare value-based care incentives.
- Implantable:Self-contained catheter-delivered devices with tine or screw fixation mechanisms eliminate transvenous leads and generator pockets. German electrophysiology centers are scaling implantable volumes as catheterization lab capacity expands for minimally invasive procedures.
- Remote Monitoring:Cloud-connected telemetry infrastructure enables predictive battery replacement scheduling and reduces emergency department utilization.
- Battery-less:Piezoelectric and thermoelectric systems convert cardiac mechanical energy or body heat into electrical pacing stimulus.
Wireless retains volume leadership; battery-less holds the steepest expansion curve.
End User:
Cost tier stratification separates high-acuity institutional settings from emerging ambulatory channels.
- Hospitals:Catheterization labs with dedicated electrophysiology suites perform the majority of implantations, with bundled payment models encompassing device, procedure, and follow-up monitoring. United States Medicare Administrative Contractors with favorable outpatient procedure coding are driving volume concentration.
- Cardiology Clinics:Specialized ambulatory facilities handle pre-implant screening and post-procedure follow-up, reducing hospital-based care costs.
- Research Institutions:Academic medical centers conduct pivotal clinical trials for FDA premarket approval and EU MDR conformity assessment.
- Home Care:Emerging channel for remote monitoring data collection and patient compliance management.
Hospitals retain volume leadership; cardiology clinics hold the steepest expansion curve.
Product Type:
Application complexity determines margin structure, with multi-chamber synchronization commanding premium pricing over single-chamber commodity volumes.
- Dual Chamber:Atrioventricular sequential pacing without transvenous leads addresses unmet synchronization needs in patients with AV block. Japan's PMDA Sakigake designation creates first-mover advantage windows for manufacturers solving atrioventricular timing challenges.
- Single Chamber:Right ventricular pacing for bradyarrhythmia represents the established volume tier with compressed margins and mature reimbursement pathways.
- Multi-site:Simultaneous pacing from multiple cardiac locations for complex resynchronization.
- Custom Solutions:Patient-specific devices for complex anatomies and congenital heart conditions.
Single chamber retains volume leadership; dual chamber holds the steepest expansion curve.
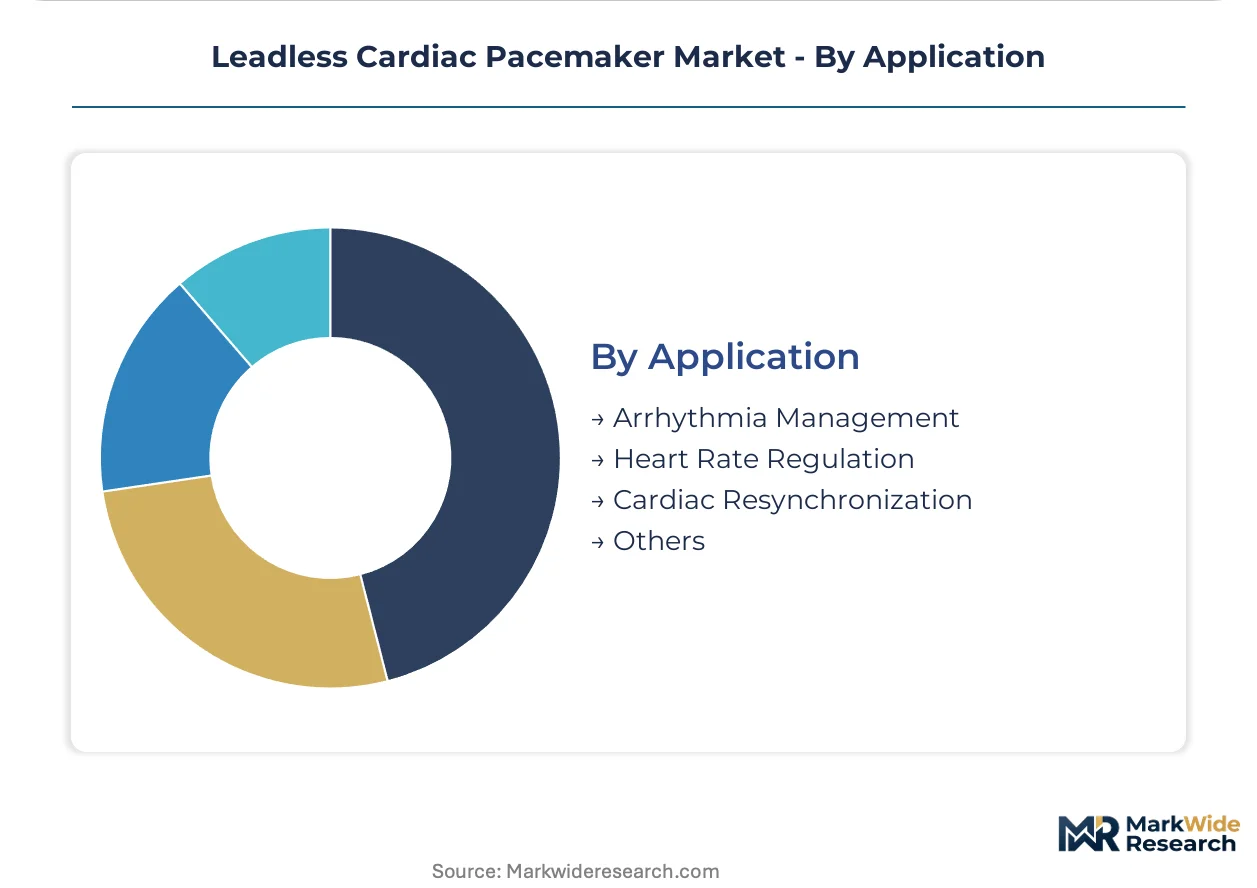
Application:
Customer type segmentation reflects how disease severity and comorbidity burden determine procedural setting and device specification requirements.
- Arrhythmia Management:Bradyarrhythmia and tachyarrhythmia pacing therapies represent the core clinical indication with established FDA premarket approval pathways and CPT reimbursement codes.
- Heart Rate Regulation:Chronotropic incompetence and sinus node dysfunction pacing for exercise intolerance.
- Cardiac Resynchronization:Biventricular pacing coordination for heart failure with reduced ejection fraction.
- Others:Emerging indications including hypertrophic cardiomyopathy and pediatric congenital conditions.
Arrhythmia management retains volume leadership; cardiac resynchronization holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic catheterization lab network underwrites the United States' procedural capacity leadership, while Japan's PMDA Sakigake designation accelerates dual-chamber approval timelines for manufacturers targeting aging populations.
United States
Medicare Administrative Contractors with favorable outpatient procedure coding concentrate implant volumes in Texas and Florida metropolitan clusters. The FDA's premarket approval pathway for novel pacing modalities demands extended follow-up periods that delay commercialization timelines. Major integrated delivery networks in California and New York are consolidating procurement around bundled payment models encompassing device, procedure, and remote monitoring infrastructure.
Germany
Expanding catheterization lab capacity in Bavaria and North Rhine-Westphalia accommodates procedural demand from elderly populations with elevated bradyarrhythmia incidence. EU MDR conformity assessment requirements under the Medical Device Regulation filter market access toward manufacturers with robust post-market surveillance capabilities. The Berlin-Brandenburg academic medical center cluster conducts pivotal clinical trials for CE marking of next-generation fixation mechanisms.
Japan
Aging demographics in the Kanto and Kansai regions generate concentrated demand for minimally invasive cardiac interventions. The PMDA Sakigake designation creates expedited review windows for breakthrough dual-chamber systems addressing unmet atrioventricular synchronization needs. Tokyo metropolitan hospitals are scaling physician training pipelines for leadless implantation techniques distinct from conventional transvenous approaches.
China
Rising cardiovascular disease burden in the Yangtze River Delta and Pearl River Delta drives catheterization lab expansion in Shanghai and Guangzhou. The NMPA imposes distinct localization requirements that filter market access for imported devices. Domestic manufacturers in Beijing-Tianjin-Hebei are developing tine-based fixation systems to reduce dislodgment rates and broaden anatomical candidacy.
Switzerland
Swissmedic's streamlined conformity assessment procedures attract manufacturers seeking European market entry through the mutual recognition procedure. Geneva and Zurich academic medical centers specialize in complex retrieval procedures for fibrotically encapsulated devices. The Basel pharmaceutical-electronics industrial cluster supports battery chemistry research addressing lithium carbon monofluoride longevity limitations.
Leadless Cardiac Pacemaker Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying fixation mechanisms, battery cells, and telemetry modules. The vendor base concentrates around electrophysiology portfolio holders with integrated cath-lab offerings and dedicated physician training networks. Three archetypes dominate: diversified medical technology conglomerates with rhythm management divisions, pure-play cardiac device specialists, and emerging energy-harvesting technology developers. Competitive dynamics center on dual-chamber regulatory submissions and multi-year bundled procurement contracts with United States integrated delivery networks.
Among diversified conglomerates, Abbott Laboratories and Medtronic plc exemplify platform integrators leveraging extensive electrophysiology portfolios to sustain cath-lab system sales. Boston Scientific Corporation occupies a position within the cardiac rhythm specialist tier, competing on dual-chamber technology development and European regulatory momentum. These three manufacturers anchor competitive positioning through differentiated approaches to atrioventricular synchronization challenges and remote monitoring infrastructure deployment.
| Leading Market Players |
|---|
| BIOTRONIK SE & Co. KG |
| MicroPort Scientific Corporation |
| Abbott Laboratories |
| LivaNova plc |
| AtriCure, Inc. |
| Medtronic plc |
| EBR Systems, Inc. |
| CAIRDAC |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on lithium carbon monofluoride battery cells from Japanese suppliers determines both tiered pricing spreads and supply chain configuration for leadless pacemaker manufacturers. FDA premarket approval timelines and EU MDR conformity costs compress margins at the standard tier while premium dual-chamber systems command wider spreads through extended warranty bundling and remote monitoring subscriptions.
Pricing Analysis
Volume-discount tiering structures separate premium dual-chamber systems with integrated telemetry from standard single-chamber devices and economy-tier legacy wireless models. Price differentiation rests on FDA approval tier, dual-chamber synchronization capability, and bundled cath-lab training packages. Cost compression in the standard tier intensifies as Medicare Administrative Contractors tighten outpatient procedure reimbursement. Academic medical centers exhibit lowest price sensitivity due to bundled payment model insulation, while community hospitals in competitive metropolitan clusters face acute procurement pressure.
Supply Chain Analysis
Extended payment terms from integrated delivery networks in the United States force suppliers to access supply-chain finance facilities, compressing working capital cycles for component manufacturers. Manufacturing concentrates in Ireland, Switzerland, and Singapore for final assembly, with lithium carbon monofluoride cells and telemetry modules drawing from Japan and South Korea. Single-source vulnerability in battery chemistry creates exposure to raw material volatility. Distribution runs through GPO contracts and direct hospital procurement channels with multi-year bundled agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leadless cardiac pacemaker penetration sits at early-cycle expansion with dual-chamber technology unlocking previously ineligible patient populations. Catheterization lab capacity buildout across aging demographics sustains procedural volume tailwinds.
For Market Incumbents: Pre-empt retrieval protocol standardization by investing in extraction center partnerships before FDA mandates chronic implant management guidelines. Secure backward integration into battery cell manufacturing to reduce lithium carbon monofluoride supply exposure and defend margin position against emerging energy-harvesting disruptors. Anchor cath-lab system sales through multi-year remote monitoring infrastructure contracts. For New Entrants and Emerging Players: Mid-tier community hospitals in the United States Southeast represent the most penetrable entry point, as favorable Medicare Administrative Contractor coding concentrates volume without incumbent training network saturation. Japan's PMDA Sakigake designation pathway offers regulatory fast-track differentiation for breakthrough dual-chamber submissions. Partner with electrophysiology fellowship programs to bypass incumbent physician training bottlenecks. For Investors and Strategic Acquirers: EU MDR conformity assessment tightening reshapes the acquisition landscape toward targets with robust post-market surveillance infrastructure and Berlin-Brandenburg clinical trial capabilities. Five-to-ten year viability favors manufacturers solving atrioventricular synchronization without transvenous bridging. Watch FDA dual-chamber premarket approval decisions as inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Dual-Chamber Submission | Premarket approval for atrioventricular synchronization unlocks premium pricing tiers and expands addressable patient populations. |
| CE Marking Pathway | EU MDR conformity assessment filters market access toward manufacturers with robust post-market surveillance capabilities. |
| Hospital System Partnership | Multi-year bundled contracts with Cleveland Clinic and Texas Medical Center networks concentrate volume and lock out competitors. |
| Software Companion Development | Cloud-based remote monitoring platforms enable predictive battery replacement and reduce emergency department utilization. |
| Reimbursement Strategy | Favorable Medicare Administrative Contractor coding in Florida and Texas metropolitan clusters drives procedural volume concentration. |
Study Parameters
Initial hypotheses were tested against primary input from electrophysiologists, catheterization lab directors, hospital purchasing committee members, and GPO contracts managers and refined through secondary validation. Sources included FDA premarket approval filings, EU MDR technical documentation, CMS Medicare procedure databases, and hospital procurement records. Bottom-up implant volume modeling triangulated against top-down market sizing across technology and product type segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include chamber configuration, fixation mechanism type, end-user facility tier, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to cath-lab capacity expansion and reimbursement pathway evolution. Forecast inputs incorporated battery longevity assumptions and retrieval protocol adoption curves.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates or EU MDR enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding procedural adoption and technology substitution. Regulatory, reimbursement, or battery chemistry breakthrough deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Knee Walkers Market
Medical Devices
Implantable Port Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Extremity Reconstruction Market