
 Gel Implants Market | 2026-2036
Gel Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Implants Market Foresight
Cosmetic clinics is restructuring demand patterns across the gel implants landscape as outpatient aesthetic procedures displace traditional hospital-based surgeries. Allergan Aesthetics leverages its direct-to-physician channel infrastructure to sustain premium positioning in breast augmentation. Mentor Worldwide LLC anchors North American supply through vertically controlled manufacturing campuses. Establishment Labs Holdings Inc. differentiates via proprietary silicone matrix technologies that command specialist surgeon loyalty.
Gel implants are medical devices comprising biocompatible polymer matrices—typically cross-linked silicone elastomers or structured saline solutions—encapsulated within silicone shells and engineered to mimic native tissue compliance and dimensional stability. Their primary commercial purpose spans aesthetic volume restoration and post-mastectomy reconstructive reconstruction. Cohesive gel formulations now lead procedural preference due to reduced capsular contracture rates and superior shape retention. Breast reconstruction applications represent the fastest-growing segment as oncologic reconstruction protocols expand. Cosmetic clinics channel direct sales capture the deepest margin pools by eliminating distributor markups.
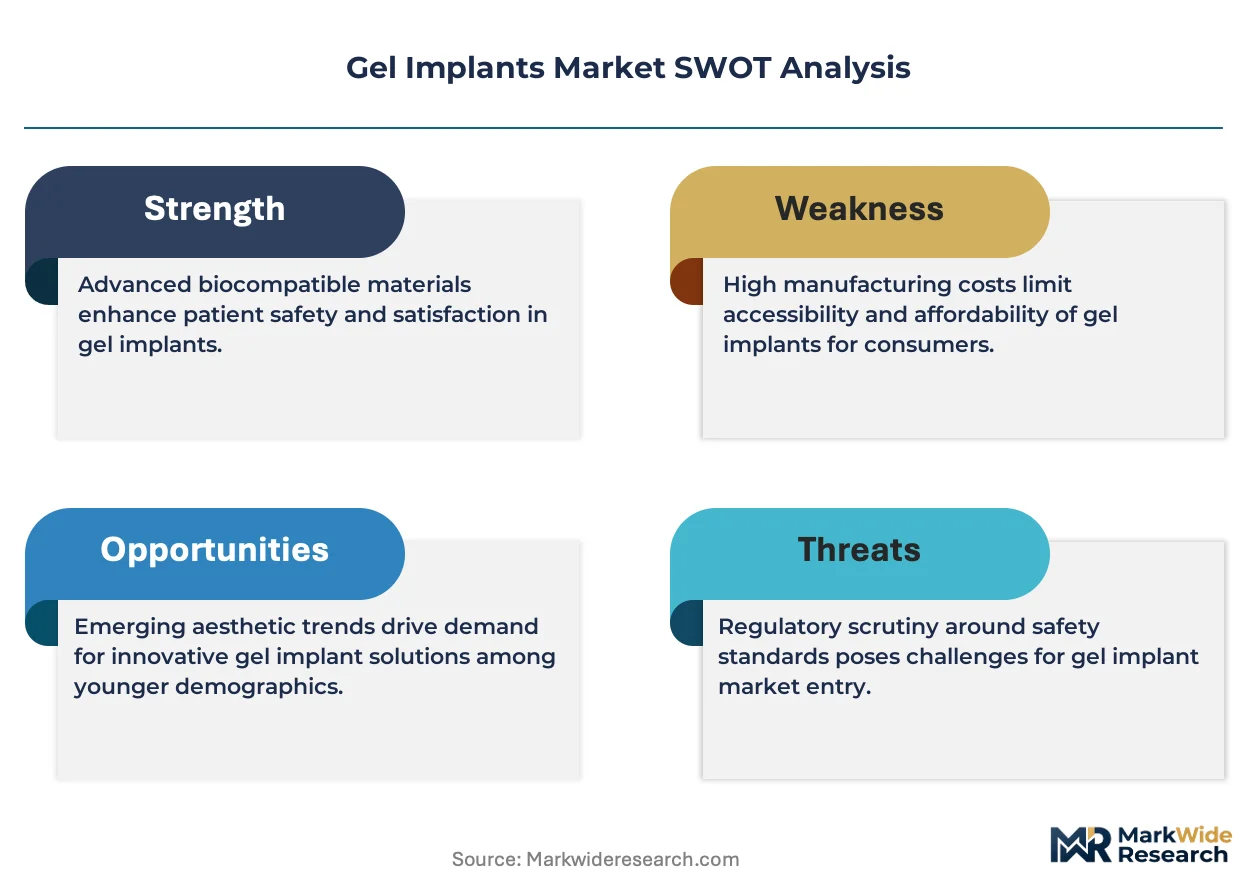
The FDA governs silicone gel implant premarket approval through stringent clinical trial mandates, while the EU Medical Device Regulation imposes enhanced post-market surveillance obligations across European member states. Brazil's ANVISA maintains parallel vigilance requirements that shape import eligibility for multinational manufacturers. Stakeholders must monitor evolving regulatory divergence between jurisdictions to optimize product registration sequencing and avoid market access delays.
Market Dynamics
The FDA's updated premarket approval requirements for silicone-based devices are forcing manufacturers to restructure clinical trial investments and compliance architectures, compressing margin structures while elevating barriers to new entrants.
Growth Catalysts
- Breast reconstruction protocols:Oncologic reconstruction applications are expanding procedural volumes as cancer survivorship programs integrate aesthetic restoration into standard care pathways.
- EU Medical Device Regulation post-market surveillance:Enhanced vigilance obligations are creating competitive separation between established manufacturers with robust traceability systems and smaller competitors.
- Cosmetic clinic channel expansion:Outpatient aesthetic facilities are displacing hospital-based surgeries, capturing margin pools through direct-to-physician sales models.
Market Restraints
- Silicone raw material concentration:Supply of medical-grade silicone elastomers concentrates among a limited set of specialty chemical producers, exposing manufacturers to input cost volatility and allocation risk.
- Extended FDA PMA timelines:Stringent clinical trial mandates for new cohesive gel formulations create 3-5 year approval windows that freeze product pipeline velocity.
- Structured saline substitution:Saline-based alternatives retain preference in specific patient segments concerned with silicone-related complications, capping addressable market expansion.
Strategic Opportunities
- Brazil's ANVISA import pathway:Regulatory harmonization initiatives are streamlining market access for manufacturers already holding FDA or EU MDR approvals.
- 3D imaging and personalized implant design:Convergence of computed tomography planning with additive manufacturing tooling is enabling patient-specific dimensional matching.
- Telemedicine consultation channels:Virtual pre-operative assessment platforms are reducing geographic friction in patient acquisition for specialized aesthetic practices.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993-compliant toxicology evaluation slots face 12-18 month backlogs at certified laboratories, compressing development timelines.
- Legacy ERP integration:EU MDR Unique Device Identification requirements demand traceability system overhauls that conflict with decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Implants Market |
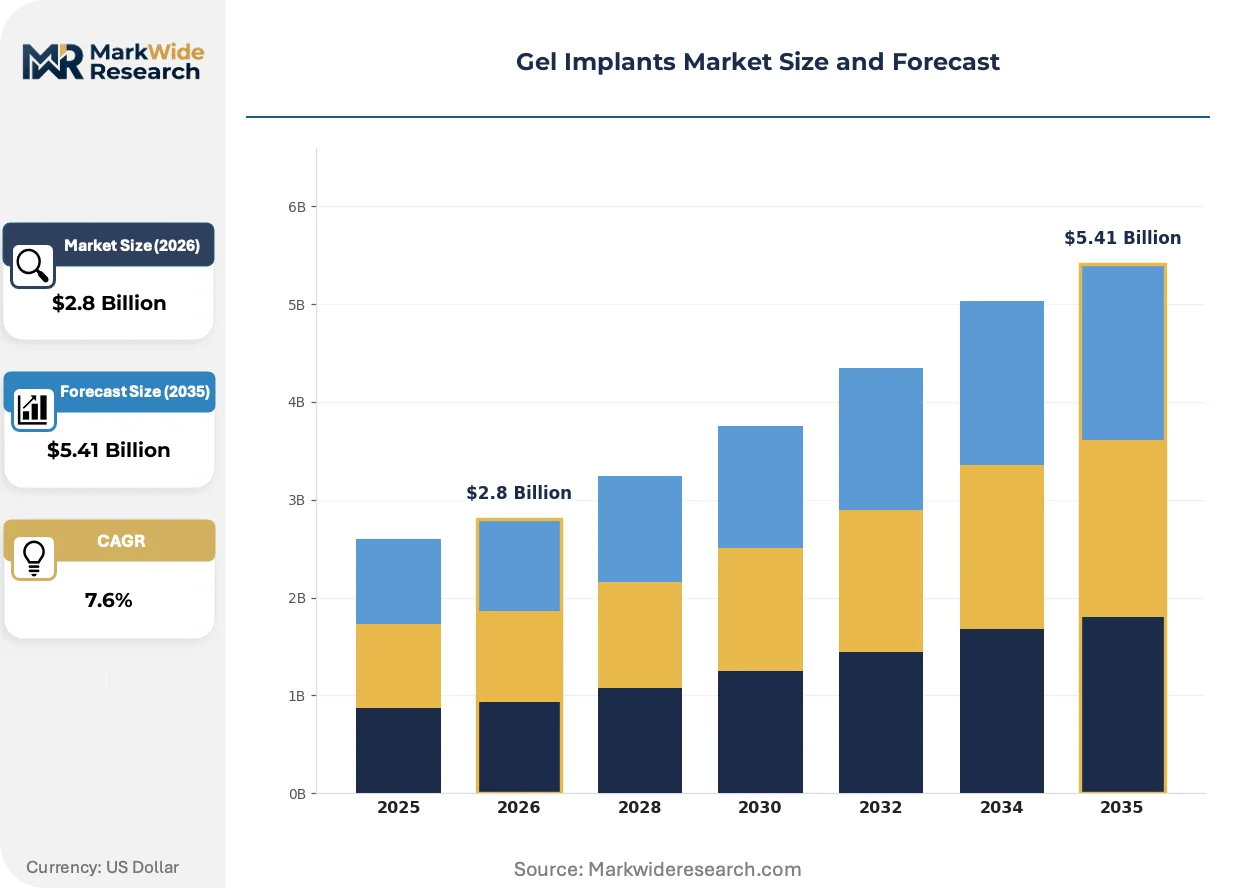
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Gel, Saline, Cohesive Gel, Structured Gel Application: Breast Augmentation, Breast Reconstruction, Facial Fillers, Body Contouring End User: Hospitals, Surgical Centers, Cosmetic Clinics, Ambulatory Care Distribution Channel: Online Retail, Medical Distributors, Direct Sales, Third-Party Retail |
| Companies Covered | Allergan Aesthetics, Mentor Worldwide LLC, Sientra, Inc., Establishment Labs Holdings Inc., GC Aesthetics, Ideal Implant Incorporated, Polytech Health & Aesthetics, Groupe Sebbin, Cereplas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Implants Market Shifts & Advancements
Cohesive gel formulations are absorbing market preference as surgeons prioritize capsular contracture reduction and dimensional stability over legacy implant architectures.
Highly cross-linked silicone elastomer matrices are absorbing procedural preference in breast augmentation and reconstruction. Specialist surgeons in the United States and South Korea are adopting these formulations at accelerating rates. This absorption is compressing demand for traditional moderate-cohesion devices and reshaping manufacturer R&D allocation toward advanced polymer engineering.
REACH substance restrictions on cyclic siloxanes are compelling reformulation of silicone raw materials across European supply chains. Manufacturers must demonstrate D4/D5/D6 content below 0.1% weight thresholds in finished devices. German and French notified bodies are enforcing these limits most stringently, driving substitution toward low-volatility silicone precursors.
Patients are compressing decision cycles through social media-facilitated surgeon discovery and peer outcome visualization. Instagram and TikTok channels are displacing traditional referral networks in initial provider selection. This behavioral shift concentrates demand among cosmetic clinics with sophisticated digital presence management, particularly visible in Miami, Los Angeles, and São Paulo aesthetic markets.
Gel Implants Market Segmentation
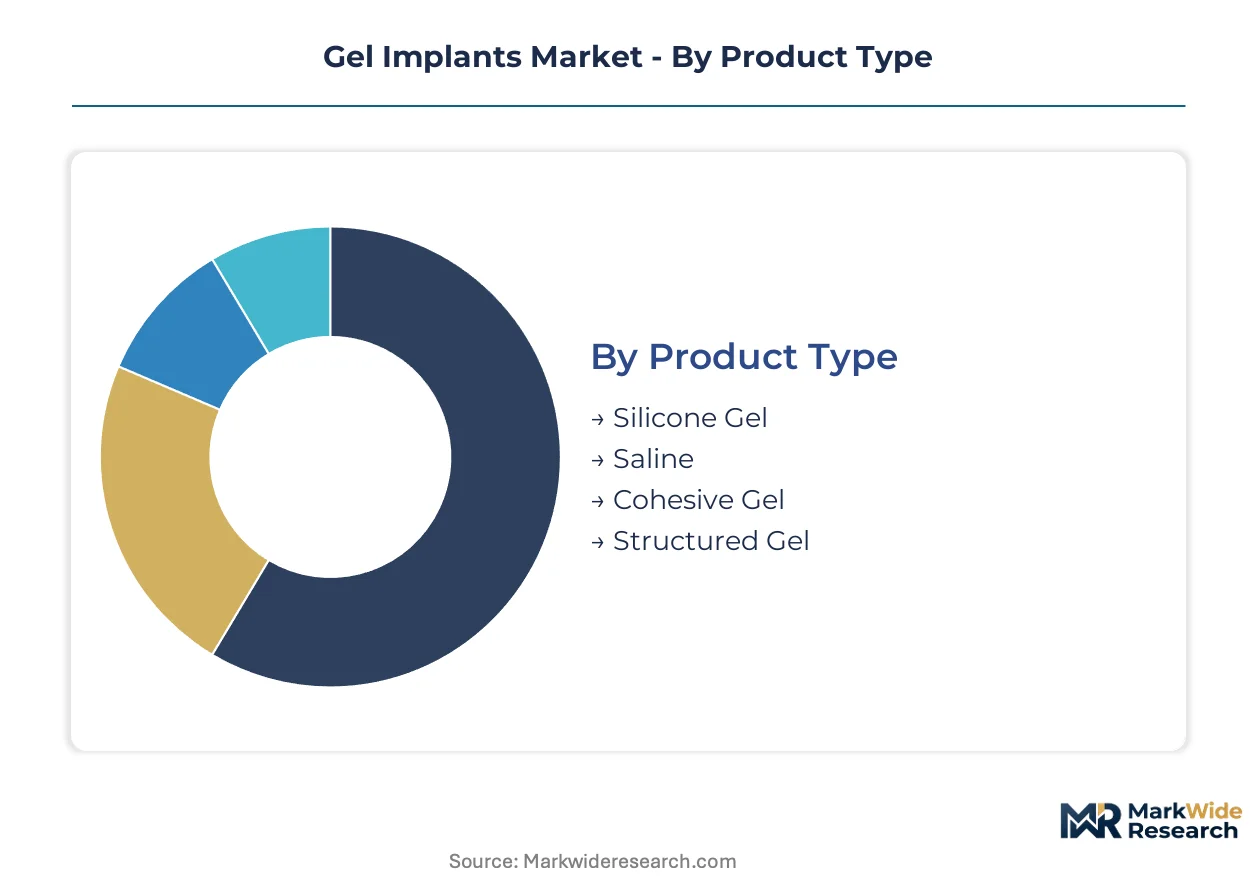
Segmentation in gel implants reveals how formulation chemistry, procedural setting, and channel economics partition margin capture across the value chain. Manufacturers must align product architecture with specific end-user infrastructure to optimize commercial traction.
Product Type:
Formulation cross-link density and elastomer matrix structure define performance profiles and regulatory classification pathways.
- Silicone Gel:Standard cross-linked polydimethylsiloxane matrices with moderate viscosity. Demand concentrates in US cosmetic clinics where FDA PMA grandfathering sustains procedural familiarity among established surgeons.
- Cohesive Gel:Highly cross-linked silicone elastomer with form-stable properties reducing capsular contracture incidence. South Korean and Brazilian specialist practices are adopting these formulations fastest, driven by superior shape retention in anatomical positioning.
- Saline:Sterile sodium chloride solution within silicone shells. Preference persists among specific patient segments in US hospital systems concerned with silicone-related complication profiles.
- Structured Gel:Intermediate viscosity formulations with internal baffle architecture. Emerging positioning in European reconstructive protocols under EU MDR enhanced surveillance frameworks.
Mature deployment sits with Silicone Gel. Newer deployment is concentrated in Cohesive Gel.
Application:
Procedural purpose determines reimbursement architecture, regulatory scrutiny intensity, and surgeon specialization requirements.
- Breast Reconstruction:Post-mastectomy volume restoration integrated into oncologic care pathways. US cancer centers and Brazilian public health reconstruction programs are expanding procedural volumes fastest as survivorship protocols standardize aesthetic restoration.
- Breast Augmentation:Primary aesthetic volume enhancement. Miami, Los Angeles, and São Paulo cosmetic clinics capture deepest margins through direct-to-physician channel structures eliminating distributor markups.
- Facial Fillers:Subcutaneous soft tissue augmentation using micro-droplet gel deposition. Korean dermatology clinics are driving adoption of specialized low-viscosity formulations.
- Body Contouring:Calf, pectoral, and gluteal enhancement applications. Niche positioning in Brazilian and US male aesthetic markets with specialized surgeon training requirements.
Volume concentration remains with Breast Augmentation. Steepest expansion trajectory belongs to Breast Reconstruction.
End User:
Facility infrastructure determines inventory management protocols, capital equipment requirements, and purchasing authority distribution.
- Cosmetic Clinics:Outpatient aesthetic facilities with dedicated procedure suites. These channels are displacing hospital-based surgeries in Miami and São Paulo, capturing margin pools through streamlined patient acquisition.
- Hospitals:Integrated health systems with reconstructive surgery departments. US and Brazilian oncologic centers anchor demand for complex revision and post-radiation reconstruction cases.
- Surgical Centers:Ambulatory facilities specializing in same-day procedures. Intermediate positioning between hospital infrastructure and cosmetic clinic agility.
- Ambulatory Care:General outpatient settings with limited aesthetic specialization. Peripheral positioning for standard augmentation procedures in secondary markets.
Purchasing authority is consolidating in Cosmetic Clinics. Procurement fragmentation persists in Ambulatory Care.
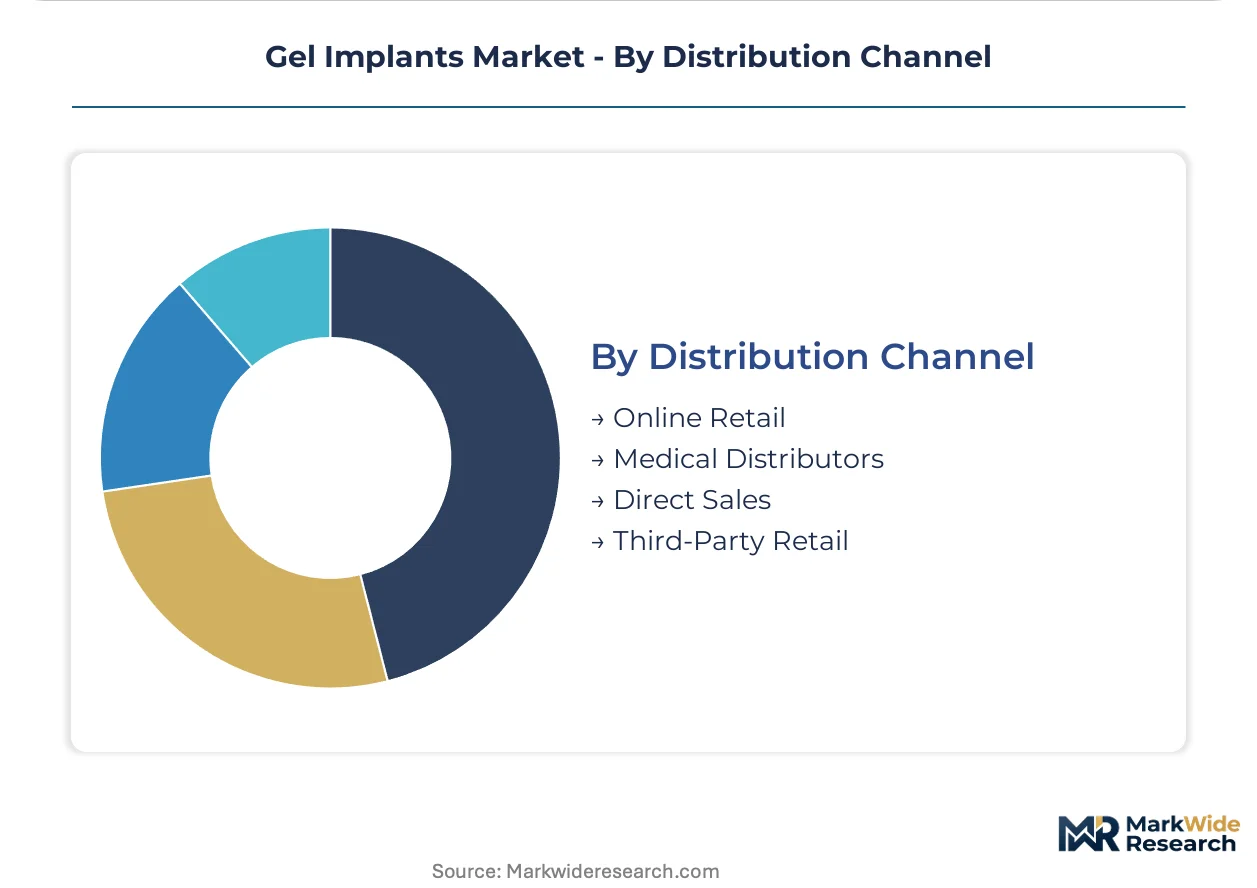
Distribution Channel:
Channel selection determines margin retention, traceability compliance burden, and geographic reach constraints.
- Direct Sales:Manufacturer-to-physician relationships bypassing intermediaries. Allergan Aesthetics and Mentor Worldwide leverage this channel to sustain premium positioning and capture deepest margin pools in US and Brazilian markets.
- Medical Distributors:Specialized aesthetic device wholesalers with regional logistics networks. Dominant pathway for European and Asian market access where regulatory registration complexity favors local intermediary expertise.
- Online Retail:Digital procurement platforms with limited traction due to device prescription requirements and cold chain logistics constraints.
- Third-Party Retail:General medical supply retailers with minimal aesthetic specialization. Marginal positioning for saline implant procurement in price-sensitive segments.
Margin optimization centers on Direct Sales. Regulatory compliance burden favors Medical Distributors in multi-jurisdiction deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone tax incentives concentrate import processing for silicone medical devices, redirecting regional distribution flows toward South American markets.
United States
Miami and Los Angeles cosmetic clinic clusters drive procedural volume concentration. FDA premarket approval requirements for cohesive gel formulations extend development timelines while elevating compliance costs. Specialist surgeon practices in Beverly Hills and South Beach capture premium patient flows through direct-to-physician channel structures.
Brazil
Post-mastectomy reconstruction protocols in São Paulo public health systems expand procedural access. ANVISA vigilance requirements for silicone devices shape import eligibility and registration sequencing. The Jardins aesthetic district anchors private clinic concentration with direct manufacturer relationships.
South Korea
Gangnam district dermatology clinics accelerate adoption of low-viscosity facial gel formulations. MFDS medical device regulations enforce stringent biocompatibility documentation for silicone elastomer imports. Seoul's Apgujeong corridor concentrates specialist surgeon practices with advanced polymer preference.
Germany
REACH substance restrictions on cyclic siloxanes compel silicone precursor reformulation across European supply chains. Notified bodies in Berlin and Munich enforce D4/D5/D6 content thresholds most stringently. The Rhine-Ruhr medical technology cluster hosts manufacturing execution platform overhauls for EU MDR traceability compliance.
France
Breast reconstruction integration into oncologic survivorship programs drives hospital-based procedural growth. ANSM post-market surveillance obligations mandate enhanced adverse event reporting from Parisian aesthetic centers. The Île-de-France region concentrates notified body certification activity for cohesive gel device registrations.
Gel Implants Market Competitive Landscape
Top-tier vendors anchor premium positioning through direct-to-physician channel control, while mid-scale specialists compete on polymer engineering differentiation. The vendor base stratifies across three archetypes: integrated aesthetics conglomerates with captive manufacturing, pure-play implant specialists with proprietary silicone matrices, and regional fabricators serving price-sensitive segments. Dominant competitive moves include backward integration into medical-grade silicone supply and strategic partnerships with specialist surgeon training programs.
Within the integrated conglomerate tier, Allergan Aesthetics and Mentor Worldwide LLC exemplify channel infrastructure scale. Establishment Labs Holdings Inc. occupies a position among polymer engineering specialists with proprietary technology positioning. These three entities represent the competitive archetype distribution: direct sales dominance, manufacturing verticality, and silicone matrix innovation respectively.
| Leading Market Players |
|---|
| Allergan Aesthetics |
| Mentor Worldwide LLC |
| Sientra, Inc. |
| Establishment Labs Holdings Inc. |
| GC Aesthetics |
| Ideal Implant Incorporated |
| Polytech Health & Aesthetics |
| Groupe Sebbin |
| Cereplas |
| Others |
Supply & Pricing Matrix
Cohesive gel formulation transitions toward highly cross-linked silicone elastomer matrices are simultaneously elevating raw material purity requirements and compressing the supplier base capable of meeting medical-grade specifications. This dual shift concentrates procurement leverage among specialty chemical producers while forcing implant manufacturers to absorb premium feedstock costs or cede margin.
Pricing Analysis
Short lead-time premiums for medical-grade silicone elastomers command substantial markups over standard industrial grades, while spot inventory of FDA-validated cohesive gel formulations trades at discounts only when manufacturers clear aged stock. Three-tier pricing structure across premium cohesive gel, standard silicone gel, and economy saline tiers separates specialist surgeon practices from hospital procurement and price-sensitive ambulatory channels. Pricing pressure stems from REACH-compliant silicone precursor scarcity, which tightens margins on European-bound production. Hospital systems exhibit highest price sensitivity due to bundled reimbursement constraints, whereas Beverly Hills and Gangnam cosmetic clinics absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Direct-to-physician channels handle hyperscale demand from Miami and São Paulo cosmetic clinic clusters, bypassing distributor markups while imposing cold-chain logistics complexity. Geographic supply concentration centers on Germany, Japan, and the United States for medical-grade silicone elastomer precursors. Raw material dependencies rest on high-purity D4/D5/D6 siloxane monomers, platinum catalyst systems, and specialized silicone shell polymers. Single-source vulnerability pervades the medical-grade silicone precursor tier, where FDA and EU MDR validation requirements lock manufacturers into qualified supplier relationships. Distribution runs through vertically controlled manufacturer campuses for North American volume, with regional distributors managing European and Asian regulatory complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA premarket approval requirements for silicone-based devices erect formidable barrier-to-entry moats that protect incumbents with amortized clinical trial infrastructure.
For Market Incumbents: Anchor premium positioning through backward integration into medical-grade silicone supply chains, securing captive feedstock access as REACH restrictions tighten precursor availability. Defend against structured saline substitution threats by accelerating cohesive gel innovation cycles and deepening specialist surgeon training partnerships. Capacity addition in Brazil's Manaus Free Trade Zone captures South American demand growth while optimizing import duty structures.
For New Entrants and Emerging Players: The price-point gap between premium cohesive gel and economy saline tiers offers white-space opportunity for intermediate structured gel formulations targeting European reconstructive protocols. Brazilian post-mastectomy reconstruction programs present the most penetrable application segment given public health system volume expansion and ANVISA regulatory harmonization with FDA pathways. Go-to-market execution should prioritize telemedicine-enabled cosmetic clinic partnerships to reduce geographic friction in patient acquisition.
For Investors and Strategic Acquirers: Re-rating potential sits with polymer engineering specialists possessing proprietary silicone matrix technologies given EU MDR traceability compliance differentiation. Long-term viability across the projection horizon favors manufacturers with vertically controlled manufacturing campuses and direct-to-physician channel infrastructure. Acquisition target archetypes include mid-scale specialists with ANVISA or MFDS registrations pending FDA approval. The signal to watch is biocompatibility testing laboratory capacity expansion, which would decompress ISO 10993 evaluation backlogs and accelerate product pipeline velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Stringent clinical trial mandates compress development timelines while elevating compliance barriers for new cohesive gel entrants. |
| EU MDR Traceability Compliance | Unique Device Identification requirements force ERP system overhauls that separate established manufacturers from resource-constrained competitors. |
| Cosmetic Clinic Partnership | Direct-to-physician channel structures in Miami and São Paulo eliminate distributor markups and capture deepest margin pools. |
| Backward Integration into Silicone Supply | Captive medical-grade elastomer production insulates against REACH-compliant precursor scarcity and allocation risk. |
| 3D Imaging Integration | Computed tomography planning convergence enables patient-specific dimensional matching and specialist surgeon loyalty. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with aesthetic surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from FDA PMA submissions, ANVISA import registrations, EU MDR notified body certifications, and REACH compliance documentation. Bottom-up procedural volume estimates from cosmetic clinics and hospital systems were triangulated against top-down manufacturer shipment data.
Data-stream reconciliation across unit shipment databases, pricing benchmarks, and regulatory approval timelines informed the analytical framework. Segmentation dimensions modeled include gel formulation chemistry, procedural application, end-user facility type, and distribution channel structure. CAGRs were derived from trend extrapolation of procedural volumes, adjusted for regulatory approval velocity and raw material cost trajectories. Forecast inputs incorporated biocompatibility testing backlog durations and silicone precursor supply concentration metrics.
Inputs from FDA, ANVISA, and EU notified bodies were available through the study window; gaps in real-time cosmetic clinic procedural reporting introduce uncertainty bands around volume estimates. Forecasts reflect assumptions regarding regulatory harmonization progress and REACH enforcement consistency. Periodic stress-testing of base assumptions is recommended, particularly around silicone raw material substitution timelines and telemedicine consultation adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
General Surgery Devices Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Digital Impression System Market
Medical Devices
Walking Aids Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Gel Stent Market
Medical Devices
Surgical Display Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Smart Syringe Pumps Market