
 Methyl Silicone Resins Market | 2026-2036
Methyl Silicone Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Silicone Resins Market Analytics
Automotive OEMs is redrawing procurement patterns for methyl silicone resins as electric vehicle manufacturers prioritize thermal interface materials and battery potting compounds over traditional gasket applications. Wacker Chemie AG leverages its integrated siloxane backbone production to sustain cost leadership across European and Asian supply corridors. Dow Inc. anchors its position through captive chlorosilane capacity and direct sales relationships with tier-one automotive suppliers. Shin-Etsu Chemical Co., Ltd differentiates via ultra-high-purity solid resin grades that dominate semiconductor encapsulation protocols in East Asia.
Methyl silicone resins are organosilicon polymers built on a siloxane backbone with methyl substituents, typically cured through condensation or addition reactions to form thermoset networks with service temperatures exceeding 200°C and dielectric strengths above 15 kV/mm; they function primarily as binders, protective coatings, and insulation matrices in harsh-environment applications. Solid resins command the dominant share of margin pools in electronics and aerospace specifications where thermal stability and low outgassing are non-negotiable. Liquid resins and emulsions are gaining fastest in automotive sealant and personal care formulations where processing latitude and film-forming efficiency matter most. Coatings applications across the automotive and construction end user segments absorb the largest volume throughput, though adhesives and sealants are narrowing the gap as building energy codes tighten.
EPA VOC regulations and REACH restrictions on solvent-borne formulations are forcing reformulation toward waterborne emulsions and 100% solids systems, while China's GB standards on industrial emissions are reshaping manufacturing process investments for suppliers serving the Asia-Pacific electronics cluster. The EU Green Deal and associated CSRD disclosure requirements are adding lifecycle transparency obligations that extend from raw siloxane feedstock through cured resin performance. Stakeholders must monitor how tightening carbon border adjustments intersect with regional purity specifications to determine where capacity additions and qualification investments will yield durable competitive position.
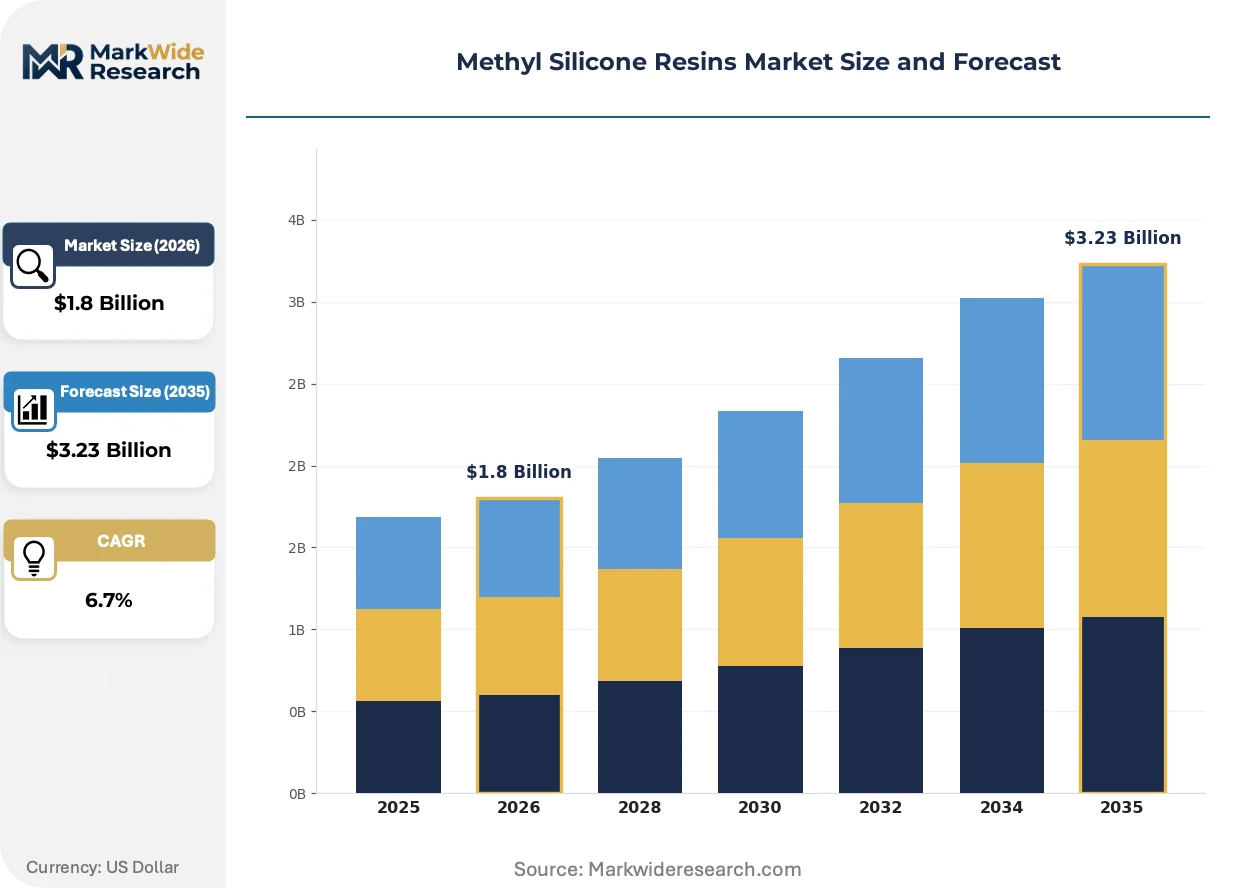
Market Dynamics
Automotive electrification is compressing qualification cycles for thermal management materials, forcing resin suppliers to synchronize R&D roadmaps with OEM platform launches rather than traditional specification-by-specification approval processes.
Growth Catalysts
- EV Battery Encapsulation Mandates:Automakers in Germany and China are specifying silicone potting compounds for lithium-ion cell protection, creating specification pull for high-purity methyl silicone resins with dielectric stability above 15 kV/mm.
- REACH Solvent Restrictions:ECHA's tightening VOC thresholds for industrial coatings are accelerating waterborne emulsion adoption in European construction and automotive refinishing applications.
- Semiconductor Fabrication Expansion:Taiwan and South Korea's advanced packaging facilities are absorbing ultra-high-purity solid resin volumes for wafer-level encapsulation and thermal interface bonding.
Market Restraints
- Chlorosilane Feedstock Concentration:Four integrated chemical conglomerates control over 70% of siloxane monomer supply, creating price volatility transmission when energy costs spike at German and Chinese production hubs.
- Cure Chemistry Limitations:Condensation-cured systems release methanol during network formation, complicating workplace safety compliance under OSHA and Germany's TRGS technical rules for hazardous substances.
- Fluoropolymer Substitution Threat:PTFE and FEP materials are displacing silicone resins in aerospace wire insulation where outgassing specifications below 1% total mass loss are mandatory.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and mobile device production are creating first-mover advantage for resin suppliers establishing local compounding operations ahead of domestic supply chain maturation.
- Building-Integrated Photovoltaics:Junction box sealing and frame bonding applications for solar facades represent unpenetrated volume for UV-stable silicone encapsulants with 25-year service life ratings.
- EU Carbon Border Adjustment:CBAM phase-in for chemical imports is creating competitive opening for European producers with verified low-carbon siloxane feedstock against Asian exporters facing emissions documentation burdens.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in siloxane polymerization kinetics and cure system optimization is concentrating at retiring technical specialists, constraining product development velocity at mid-tier compounders.
- Multi-Standard Certification Overlap:Simultaneous qualification to UL 94 flammability, MIL-PRF-23586 aerospace, and AEC-Q200 automotive standards extends approval timelines by 18-24 months for cross-sector suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Silicone Resins Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Resins, Liquid Resins, Emulsions, Powders Application: Coatings, Adhesives, Sealants, Personal Care End User: Automotive, Construction, Electronics, Healthcare Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Wacker Chemie AG, Dow Inc., Evonik Industries AG, Shin-Etsu Chemical Co., Ltd, Momentive, Elkem ASA, Kaneka Corporation, Genesee Polymers Corporation, Supreme Silicones India Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Silicone Resins Market Evolving Landscape
Formulation science is pivoting from incremental performance gains toward radical processing simplification, with 100% solids systems and ambient cure chemistries displacing energy-intensive thermal processing across multiple end-use verticals.
Addition-cure platinum catalysis is miniaturizing thermal management components in power electronics modules. Automotive inverter manufacturers are specifying ultra-thin bond lines below 50 microns for silicon carbide dies, compressing thermal interface material volumes while demanding higher thermal conductivity per unit mass. This is miniaturizing the addressable resin volume per vehicle even as EV production scales expand.
ECHA's 2023 restriction proposal on cyclic siloxanes (D4, D5, D6) in wash-off cosmetics is rippling into industrial resin feedstock specifications. European personal care and electronics resin suppliers are accelerating linear siloxane purification investments to maintain market access. Solid resin grades with sub-100 ppm cyclic content are commanding qualification priority in German and French cosmetic and medical device supply chains.
Specification authority is migrating from compounders to OEM material engineering departments. Tier-one automotive suppliers in Japan and Germany are bypassing traditional distributor channels to negotiate direct resin supply agreements with siloxane backbone producers, compressing margin pools for intermediate blenders. This consolidation of buying power is most visible in battery pack assembly, where CATL and BYD have established captive silicone formulation capabilities in China.
Methyl Silicone Resins Market Segmentation
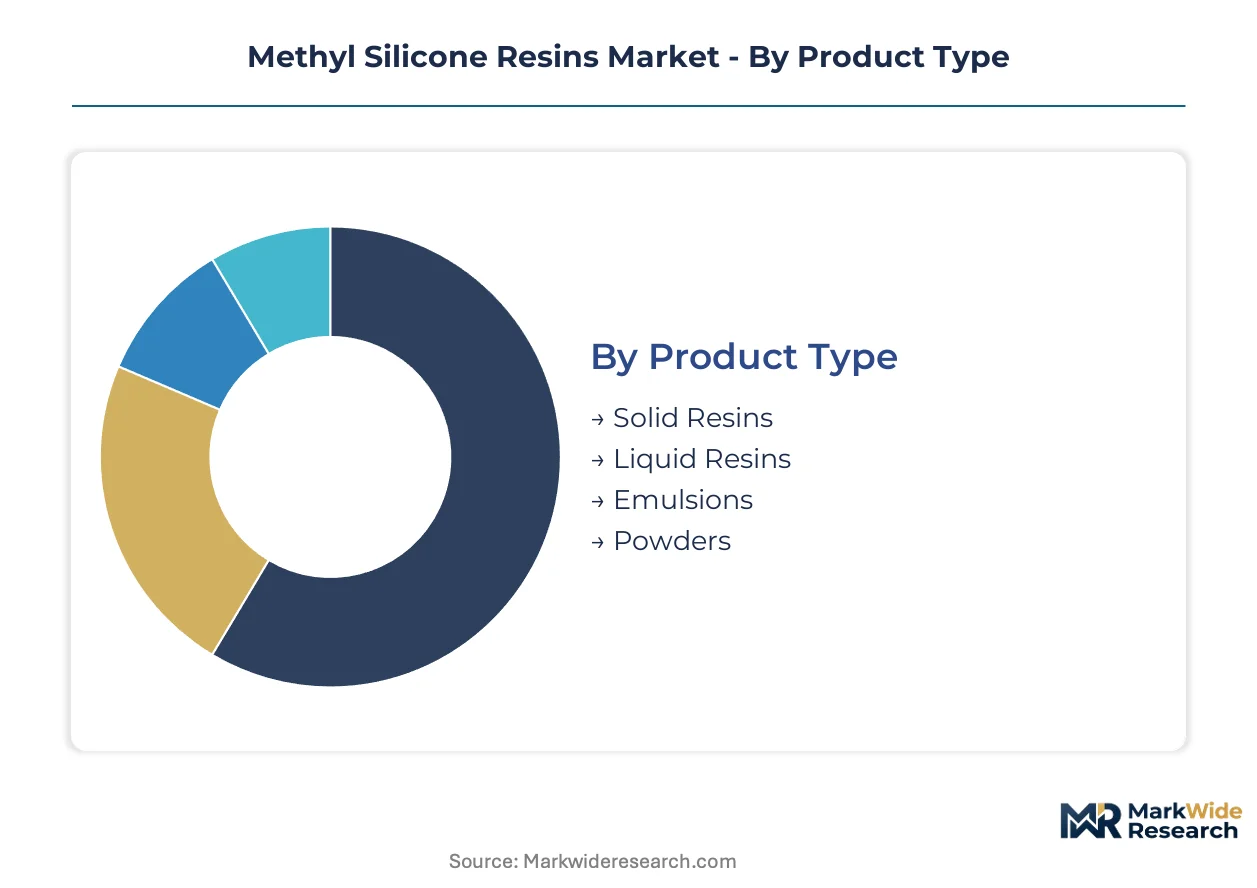
Segmentation in methyl silicone resins reveals where formulation flexibility commands premium positioning versus where commodity substitution threatens margin erosion. Each dimension exposes distinct vulnerability to fluoropolymer displacement, regulatory reformulation costs, or captive supply integration by downstream OEMs.
Product Type:
PTFE and FEP materials pose the most acute substitution threat to solid resin grades in aerospace wire insulation, while liquid resins and emulsions face waterborne acrylic competition in architectural coatings.
- Solid Resins:Thermoset organosilicon polymers with methyl-substituted siloxane backbones cure through condensation or addition reactions to networks exceeding 200°C service temperature and 15 kV/mm dielectric strength. Demand concentrates in Taiwan and South Korea semiconductor packaging facilities for wafer-level encapsulation where ultra-high-purity specifications and low outgassing are mandatory; ECHA's cyclic siloxane restrictions are accelerating linear siloxane purification investments to maintain European cosmetics and medical device market access.
- Liquid Resins:Low-viscosity prepolymers enable ambient or thermal cure with processing latitude for thin-film applications and complex geometries. Automotive OEMs in Germany and China are specifying these for EV battery potting compounds and thermal interface materials, compressing traditional gasket applications while demanding dielectric stability above 15 kV/mm; platinum-catalyzed addition cure systems are displacing condensation chemistry to eliminate methanol release during network formation.
- Emulsions:Aqueous dispersions serving waterborne coating formulations under tightening EPA VOC and REACH solvent restrictions.
- Powders:Free-flowing solid grades for powder coating and dry-blend compounding applications requiring solvent-free processing.
Solid resins retain volume leadership; liquid resins hold the steepest expansion curve.
Application:
Margin concentration follows thermal stress severity, with segments exposed to continuous high-temperature service capturing disproportionate value pools relative to ambient-condition alternatives.
- Coatings:Protective films for automotive under-the-hood components, industrial equipment, and architectural substrates demanding weathering resistance and thermal stability. Construction activity in China and infrastructure refurbishment across Germany absorb substantial volumes; REACH solvent restrictions and EPA VOC standards are forcing reformulation toward 100% solids and waterborne systems that alter resin selection criteria and curing infrastructure investments.
- Adhesives:Structural bonding systems combining flexibility with high-temperature resistance for dissimilar substrate joining. Electronics manufacturing in East Asia and automotive lightweighting initiatives are concentrating specification authority with OEM material engineering departments who negotiate direct supply agreements with siloxane backbone producers.
- Sealants:Elastic joint fillers for building envelopes, automotive assemblies, and photovoltaic frame bonding. Building energy codes tightening across multiple geographies are narrowing the volume gap with coatings as junction box sealing and solar facade applications create 25-year service life specifications for UV-stable encapsulants.
- Personal Care:Film-forming agents and conditioning additives in cosmetics subject to ECHA's 2023 cyclic siloxane restriction proposal; sub-100 ppm D4/D5/D6 content is becoming mandatory for European market access.
Coatings retain volume leadership; sealants hold the steepest expansion curve.
End User:
Procurement centralization intensity varies sharply, with automotive and electronics sectors consolidating buying power through direct supplier relationships while construction and healthcare maintain fragmented distributor-mediated channels.
- Automotive:OEMs and tier-one suppliers specifying thermal management materials, battery encapsulants, and under-the-hood coatings. CATL and BYD have established captive silicone formulation capabilities in China, compressing margin pools for intermediate compounders; qualification cycles are compressing from specification-by-specification approval to synchronized R&D roadmaps with platform launches.
- Electronics:Semiconductor fabricators and advanced packaging facilities requiring ultra-high-purity solid resins. Taiwan and South Korea facilities dominate absorption for wafer-level encapsulation and thermal interface bonding; miniaturization of power electronics is compressing bond line thickness below 50 microns while demanding higher thermal conductivity per unit mass.
- Construction:Architectural coatings, sealants, and waterproofing applications serving infrastructure and commercial building markets.
- Healthcare:Medical device encapsulation and pharmaceutical processing equipment coatings subject to biocompatibility and extractables testing protocols.
Automotive retains volume leadership; electronics holds the steepest expansion curve.
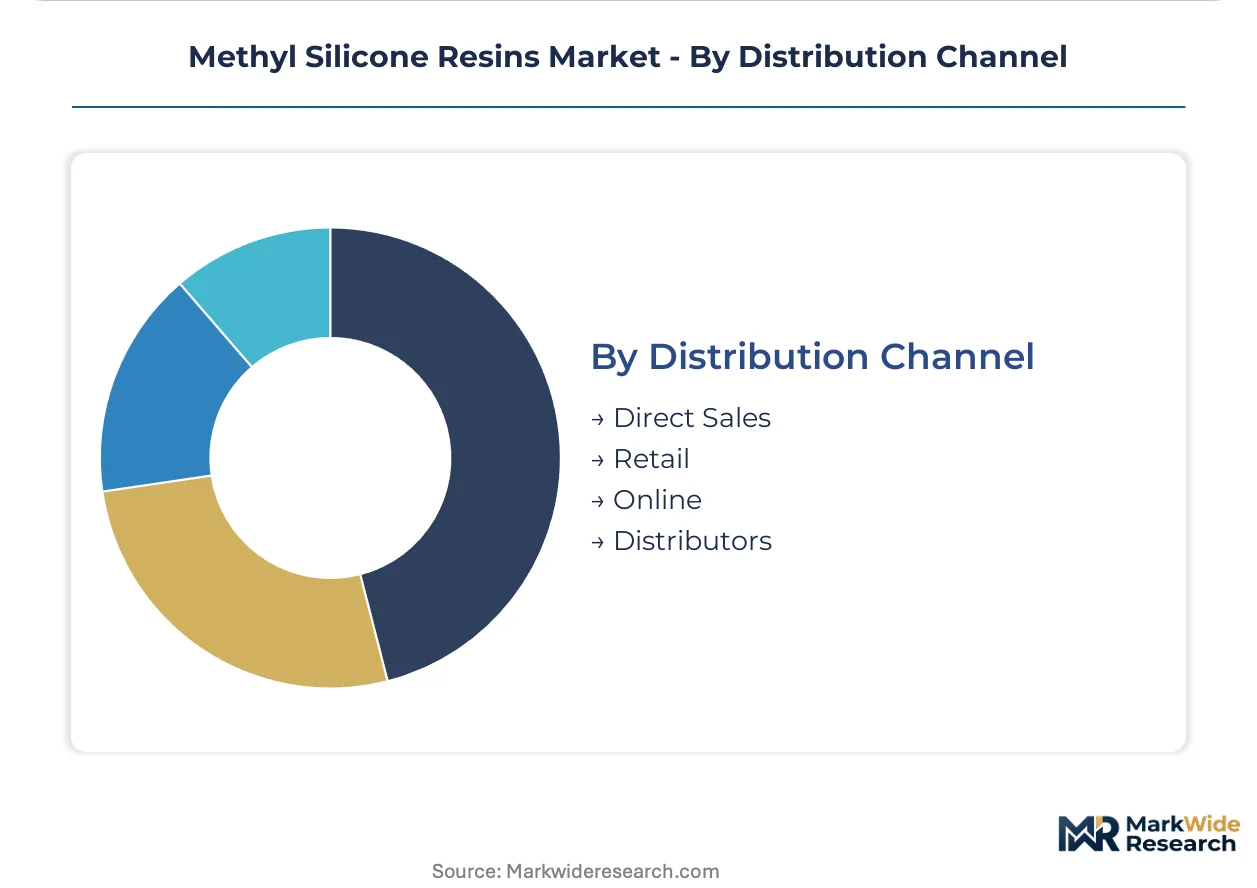
Distribution Channel:
Channel selection reflects technical complexity and volume scale, with sophisticated formulations bypassing intermediaries while standardized grades flow through multi-tier distribution.
- Direct Sales:Backbone-to-OEM relationships for high-volume, technically specified applications. Tier-one automotive suppliers in Japan and Germany are bypassing traditional distributor channels to negotiate direct resin supply agreements with siloxane producers; this consolidation of buying power is most visible in battery pack assembly where material engineering departments control specification authority.
- Distributors:Regional stocking and technical service for mid-tier compounders and smaller formulation houses.
- Retail:Small-package sales to maintenance, repair, and professional contractor segments.
- Online:Emerging channel for standardized grades and technical documentation access, particularly for geographic markets with underdeveloped distributor infrastructure.
Direct sales retain volume leadership; online holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German siloxane producers supply high-purity methyl silicone resin precursors to battery manufacturers in China and semiconductor fabricators in Taiwan, creating a transcontinental trade corridor that channels European chemical expertise into Asian electronics assembly.
China
CATL and BYD operate captive silicone formulation facilities in Fujian and Guangdong provinces for lithium-ion battery potting compounds. GB standards on industrial emissions issued by MEE are forcing domestic resin producers to upgrade condensation-cure processes. The Yangtze River Delta electronics cluster around Shanghai and Suzhou absorbs rising volumes of ultra-high-purity solid resins for advanced packaging applications.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify silicone thermal interface materials for electric drivetrain assemblies. REACH solvent restrictions enforced by ECHA are accelerating waterborne emulsion adoption in automotive refinishing operations. The Leverkusen-Ludwigshafen chemical corridor maintains integrated siloxane backbone production serving European coating and electronics markets.
United States
EPA VOC standards are tightening formulation requirements for construction coatings and automotive sealants across Michigan and Ohio manufacturing hubs. Dow Inc. anchors chlorosilane production along the Gulf Coast petrochemical corridor. Silicon Valley semiconductor packaging facilities source high-purity solid resins for wafer-level encapsulation despite fluoropolymer competition in aerospace wire insulation.
South Korea
Samsung and SK Hynix advanced packaging facilities in Gyeonggi Province consume ultra-high-purity solid resin volumes for thermal interface bonding. The country's national chemical regulator enforces alignment with REACH-equivalent substance restrictions. The Busan-Ulsan industrial belt hosts compounding operations supplying automotive battery encapsulants to domestic EV manufacturers.
Japan
Tier-one automotive suppliers in Aichi Prefecture negotiate direct resin supply agreements with siloxane backbone producers, bypassing traditional distributor channels. METI technical standards govern silicone resin specifications for power electronics modules. The Osaka-Kobe chemical cluster maintains specialty resin production for semiconductor and medical device applications.
Methyl Silicone Resins Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates controlling upstream siloxane monomer supply, with mid-tier compounders occupying formulation niches and regional specialists serving distributor-mediated construction markets. The vendor base stratifies across three archetypes: captive chlorosilane producers with backward integration into feedstock, ultra-high-purity specialists serving semiconductor qualification protocols, and emulsion compounders pivoting toward waterborne systems. Dominant competitive moves include direct supply agreements between backbone producers and OEM material engineering departments, plus geographic expansion into India electronics manufacturing corridors ahead of PLI scheme maturation.
Among German chemical conglomerates, Wacker Chemie AG and Evonik Industries AG exemplify the integrated siloxane producer archetype, leveraging captive feedstock capacity to sustain cost positioning across European and Asian supply corridors. Dow Inc. anchors the North American competitive structure through Gulf Coast chlorosilane production and direct sales relationships with tier-one automotive suppliers. Shin-Etsu Chemical Co., Ltd occupies a specialist position representing ultra-high-purity solid resin capabilities for East Asian semiconductor encapsulation protocols.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Dow Inc. |
| Evonik Industries AG |
| Shin-Etsu Chemical Co., Ltd |
| Momentive |
| Elkem ASA |
| Kaneka Corporation |
| Genesee Polymers Corporation |
| Supreme Silicones India Pvt Ltd |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day siloxane precursor lead times in European supply corridors concentrate pricing power with integrated chlorosilane producers while compressing margin buffers for mid-tier compounders dependent on spot market purchases. This inventory-to-pricing linkage intensifies whenever energy costs spike at German and Chinese production hubs, transmitting volatility downstream through contract renegotiation clauses.
Pricing Analysis
Condensation-cure versus addition-cure versus next-generation platinum-catalyzed systems define the technology-generation pricing gap in methyl silicone resins. Three-tier pricing structure across aerospace-specification, automotive-grade, and construction-commodity levels tracks certification burden and purity thresholds. Price differentiation hinges on REACH compliance documentation and volume-scale procurement commitments. Cost compression in construction-grade emulsions is intensifying because waterborne acrylic competitors are capturing specification share in architectural coatings. Automotive OEMs exhibit lowest price sensitivity due to thermal management performance requirements, while regional construction distributors face acute margin pressure.
Supply Chain Analysis
China and Germany anchor siloxane monomer production, with South Korea and Japan contributing specialty resin compounding capacity. The methyl silicone resins supply chain draws from chlorosilane feedstock, platinum catalyst systems, and high-purity methanol for condensation cure chemistry. Single-source vulnerability concentrates in siloxane backbone supply, where four integrated conglomerates control upstream monomer production. Distribution runs through direct backbone-to-OEM channels for high-volume automotive and electronics applications, with regional distributors serving fragmented construction and personal care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Methyl silicone resins function as a defensive-moat market because REACH and EPA regulatory entrenchment creates decade-long requalification barriers for substitute chemistries.
For Market Incumbents: Shield formulation expertise concentration by accelerating linear siloxane purification investments ahead of ECHA's cyclic siloxane restrictions. Deepen captive chlorosilane capacity in the Leverkusen-Ludwigshafen corridor to offset feedstock price volatility. Consolidate channel control through direct supply agreements with CATL and BYD material engineering departments, compressing margin pools for intermediate blenders threatened by captive OEM formulation capabilities. For New Entrants and Emerging Players: Lead with India electronics manufacturing corridors ahead of PLI scheme supply chain maturation, where domestic compounding infrastructure remains underdeveloped. Target building-integrated photovoltaics junction box sealing specifications, an unpenetrated volume for UV-stable encapsulants with 25-year service life ratings. Pursue qualification partnerships with tier-one automotive suppliers in Germany seeking alternative backbone sources for thermal interface materials. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because semiconductor fabrication expansion in Taiwan and South Korea sustains ultra-high-purity solid resin demand regardless of automotive cyclicality. Acquisition targets should emphasize backward-integrated siloxane producers with verified low-carbon feedstock credentials for EU Carbon Border Adjustment advantage. Monitor ECHA restriction implementation timelines as the inflection signal for linear siloxane purification capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstock | Wacker Chemie AG and Dow Inc. sustain cost leadership through captive siloxane monomer production. |
| Linear Siloxane Purification Investment | European suppliers maintain cosmetics and medical device market access under ECHA cyclic siloxane restrictions. |
| Direct Supply Agreement with OEM Material Engineering | Tier-one automotive suppliers in Japan and Germany bypass distributors to negotiate backbone-to-OEM relationships. |
| Geographic Expansion into India Electronics Manufacturing | PLI scheme incentives create first-mover advantage for resin suppliers establishing local compounding operations. |
| Waterborne Emulsion Formulation Development | REACH solvent restrictions and EPA VOC standards accelerate adoption in European construction coatings. |
Research Methodology
A standing panel of silicone resin plant managers, procurement leads at automotive OEMs and semiconductor fabricators, distribution channel partners, and technical R&D directors provided ongoing calibration across the study period. Primary interview intelligence combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and GB standards documentation from China's MEE. Bottom-up volume modeling triangulated against top-down value estimates derived from siloxane monomer production disclosures.
Consistency checks validated volume and value outputs against external benchmarks including chlorosilane capacity utilization rates and regional coating production indices. The analytical framework segmented demand across product type, application, end user, and distribution channel dimensions, with additional modeling of purity-grade tiers and cure-chemistry specifications. CAGRs were derived from slope-intercept fitting of annualized demand trajectories, incorporating EV battery production forecasts and semiconductor packaging capacity expansion timelines as industry-specific inputs.
Forecasts assume regulatory continuity in REACH, EPA VOC standards, and China's GB industrial emissions regimes; material policy shifts would require re-modeling of reformulation cost burdens and qualification timeline assumptions. Supply concentration risk in chlorosilane feedstock and fluoropolymer substitution pressure in aerospace applications represent specific revision triggers. Recalibration cycles align with material shifts in ECHA restriction implementation, automotive platform launch schedules, and carbon border adjustment phase-in timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
PET Foam Market
Polymers & Resins
Middle East and Africa Poly Vinyl Chloride (PVC) Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Agar Resin Market