
 Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market | 2026-2036
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market Foresight
Polycarbonate is hardening its position as the incumbent transparent engineering polymer that MABS must displace on cost and chemical-resistance metrics. Toray Industries leverages captive acrylonitrile supply chains to anchor transparent-grade production in Asia. LG Chem competes through backward integration into butadiene rubber, sustaining margin control across cyclical feedstock swings. Chi Mei Corporation dominates general-purpose grades for consumer electronics, where optical clarity and processability command premium positioning.
Methyl methacrylate acrylonitrile butadiene styrene is a terpolymer alloy combining polymethyl methacrylate surface layers with an acrylonitrile-butadiene-styrene core, typically processed via coextrusion or injection molding at melt temperatures between 220 and 260 degrees Celsius to achieve glass-like transparency with ABS toughness. The material serves applications requiring both aesthetic clarity and mechanical durability, notably medical device housings, automotive interior trim, and high-end consumer electronics bezels. Transparent grade captures the dominant value share as medical and automotive OEMs specify certified optical clarity for fluid monitoring and illuminated controls. Specialty grade represents the fastest-expanding segment, driven by custom formulations for gamma-stable medical devices and chemically resistant laboratory equipment. General purpose grade occupies a mature volume position in consumer electronics, where margin pools have compressed amid commoditization and Asian supply expansion.
REACH restricts phthalate-based plasticizers and mandates SVHC disclosure for MABS compounds sold into European medical and automotive channels, elevating formulation costs for non-compliant suppliers. FDA biocompatibility testing under ISO 10993 governs US medical device applications, creating multi-year qualification barriers that favor incumbent compounders with established regulatory dossiers. China's GB standards and NMPA medical device classifications impose parallel testing requirements that fragment global product portfolios. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as anticipated MABS additive bans could force reformulation of specialty grades across all major jurisdictions.
Market Dynamics
Medical device OEMs are consolidating transparent-grade MABS specifications around gamma-stable formulations, forcing compounders to rebuild product portfolios around ISO 10993 biocompatibility dossiers rather than legacy optical-grade certifications.
Growth Catalysts
- EU MDR compliance deadlines:European medical device manufacturers are accelerating material qualification cycles ahead of notified body audits, pulling forward demand for certified transparent grades.
- Automotive illuminated controls:Cabin electronics designers specify MABS for backlit switch housings where PMMA lacks impact resistance and polycarbonate yellows under UV exposure.
- Precision molding clusters in Germany:Concentrated toolmaking and injection molding infrastructure around Stuttgart and Munich reduces qualification friction for medical OEMs.
Market Restraints
- Methyl methacrylate feedstock volatility:Acetone cyanohydrin route economics swing with propylene and ammonia input costs, compressing compounder margins during upstream tightness.
- Polycarbonate substitution defense:Covestro and SABIC are reformulating PC grades with improved chemical resistance to defend automotive and medical share.
- REACH SVHC disclosure burdens:ECHA's expanding candidate list forces reformulation of legacy MABS additives, elevating compliance costs for European market access.
Strategic Opportunities
- Gamma-stable laboratory equipment:Sterilization-resistant formulations for reusable diagnostic devices open pricing premiums beyond commodity transparent grades.
- India's CDSCO medical device rules:Import substitution mandates and local manufacturing incentives create first-mover advantages for compounders establishing domestic compounding.
- Consumer electronics re-shoring:Brand OEMs in Mexico and Vietnam seek regional MABS supply to reduce China concentration risk in bezel and housing supply chains.
Industry Challenges
- Multi-jurisdiction regulatory dossier maintenance:Parallel FDA 510(k), EU MDR technical documentation, and NMPA registration requirements strain quality assurance bandwidth.
- Specialty grade formulation IP:Proprietary stabilizer packages and processing aids face increasing patent thickets, complicating new entrant product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market |
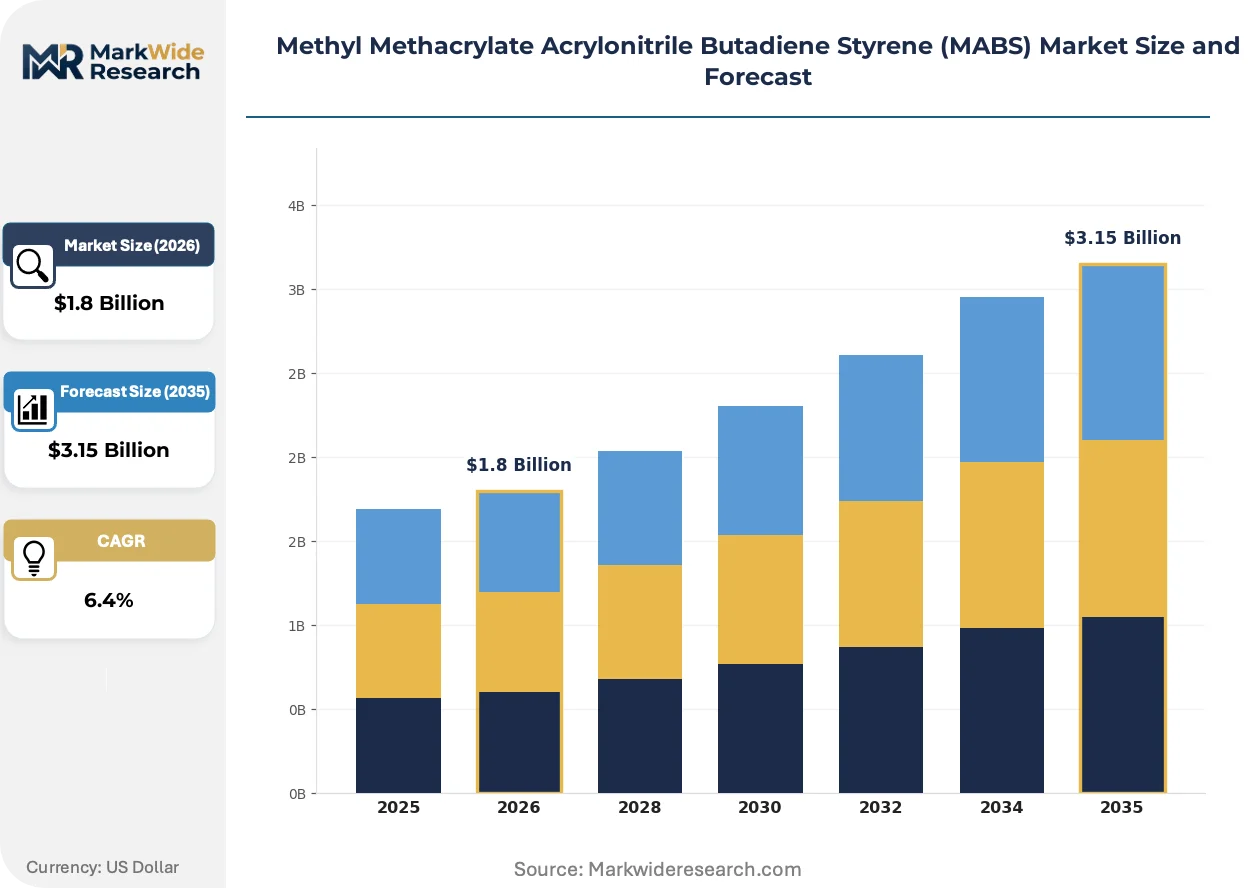
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Modifier, Transparent Grade, General Purpose, Specialty Grade Application: Automotive Parts, Consumer Electronics, Medical Devices, Construction Materials End User: Manufacturers, OEMs, Retailers, Distributors Form: Pellets, Sheets, Film, Liquid |
| Companies Covered | Toray Industries Inc., LG Chem, Chi Mei Corporation, Ruifeng Chemical, Formosa Plastics Group, INEOS Styrolution Group GmbH, Denka Company Limited, Kaneka, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market Shifts & Advancements
Coextrusion process control and additive stabilization chemistry are converging to enable thinner-wall medical device housings with maintained optical clarity, reshaping specification standards across diagnostic equipment categories.
Multi-layer coextrusion technology is modularizing MABS production by allowing discrete optimization of PMMA surface layers for scratch resistance and ABS core layers for impact performance. Medical device molders in Germany and Switzerland are adopting these lines to reduce material waste in high-cavity tooling. The technology is compressing minimum order quantities for custom optical grades, enabling mid-volume OEMs to access formulation flexibility previously reserved for automotive-scale buyers.
REACH restrictions on per- and polyfluoroalkyl substances are forcing additive package redesigns across European medical and automotive channels. ECHA's proposed PFAS ban threatens lubricant and processing aid formulations embedded in specialty MABS grades, requiring compounders to validate replacement chemistries through multi-year stability testing. Medical device segments with 10-15 year product lifecycles face the steepest requalification burdens.
Direct compounder-OEM technical partnerships are displacing traditional distributor channels for certified medical grades. Device manufacturers in the US and Germany now require batch-level traceability and regulatory documentation that distributors cannot provision, consolidating procurement relationships around Toray, LG Chem, and Chi Mei technical service teams. This channel compression is most advanced in Class II diagnostic housing applications where ISO 10993 master files are mandatory.
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market Segmentation
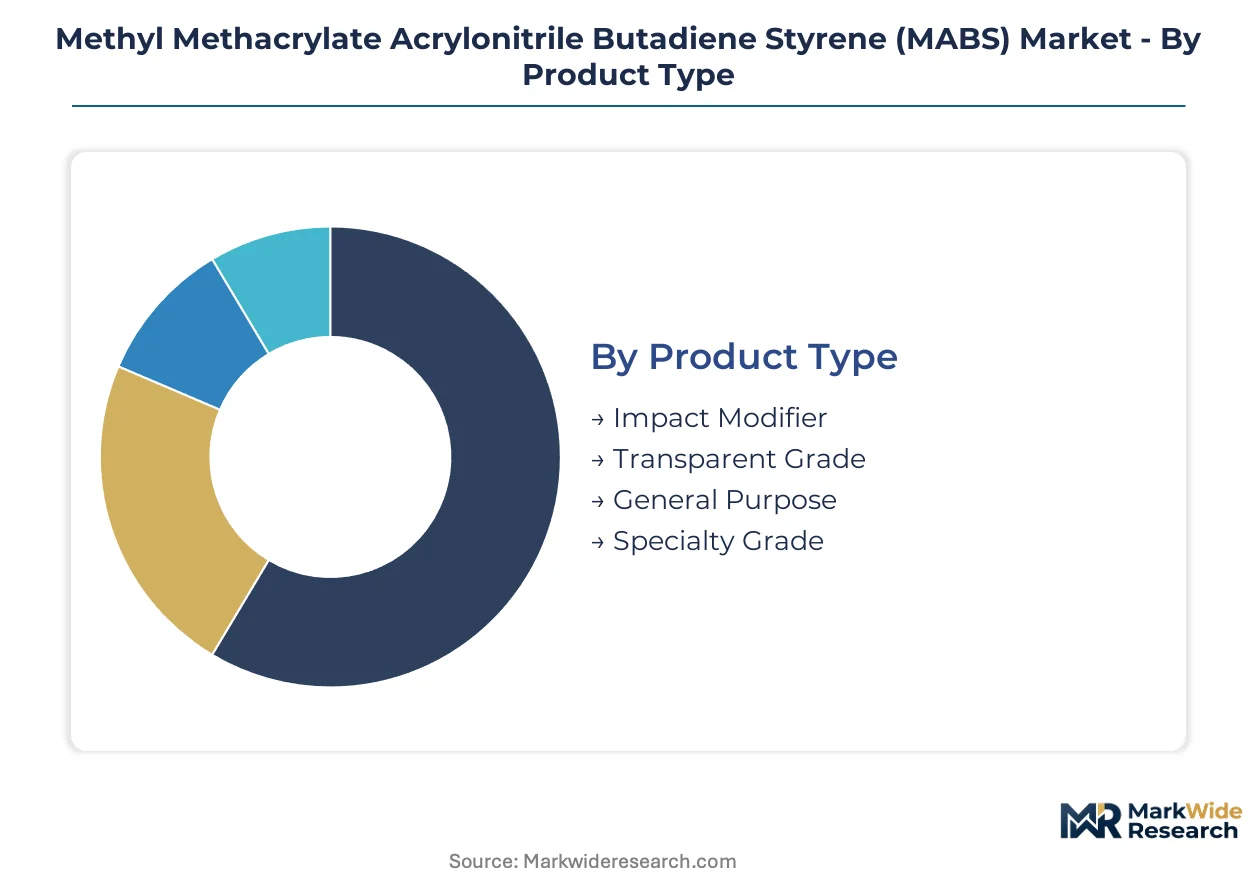
MABS segmentation reveals how material specifications fragment across standalone transparent housings versus embedded structural components. Product grades diverge sharply in regulatory burden and margin structure, while application verticals impose incompatible certification timelines that reshape supplier-customer relationships.
Product Type:
Integration depth varies dramatically across grades, with some formulated for discrete optical components and others engineered for structural reinforcement within composite assemblies.
- Transparent Grade:Optical clarity specifications exceeding 90% light transmission dominate medical device housings and automotive illuminated controls. German precision molders concentrate demand for ISO 10993-certified batches ahead of EU MDR enforcement deadlines.
- Specialty Grade:Gamma-stable formulations and chemically resistant variants command formulation premiums for reusable diagnostic equipment and laboratory vessels. Custom stabilizer packages face REACH SVHC disclosure pressures that elevate European market entry costs.
- Impact Modifier:Core-shell rubber additives enhance ABS toughness in structural automotive interior components.
- General Purpose:Commodity optical grades serve consumer electronics bezels where margin compression from Asian supply expansion limits pricing power.
Volume placements concentrate in General Purpose; the faster expansion belongs to Specialty Grade.
Application:
End-use cost tiers stratify around certification intensity, with medical and automotive channels absorbing premium pricing for documented traceability while construction and electronics compete on unit economics.
- Medical Devices:Fluid-contact housings and diagnostic equipment frames require batch-level biocompatibility dossiers under FDA and EU MDR parallel tracks. German and Swiss molders dominate procurement relationships for Class II device applications.
- Automotive Parts:Backlit switch housings and interior trim exploit MABS UV stability versus polycarbonate yellowing. Stuttgart-area OEMs specify transparent grades for cabin electronics where PMMA impact resistance proves inadequate.
- Consumer Electronics:High-end bezel applications demand glass-like aesthetics with ABS drop resistance.
- Construction Materials:Glazing and decorative panels utilize sheet and film forms for architectural applications.
Medical Devices absorb the steepest pricing premiums; Consumer Electronics delivers the highest unit volumes.
End User:
Customer type determines channel structure, with direct technical partnerships displacing distributor intermediaries where regulatory documentation requirements intensify.
- OEMs:Medical and automotive original equipment manufacturers mandate compounder-direct relationships for master file access and batch traceability. Toray and LG Chem technical service teams consolidate procurement around gamma-stable and transparent-grade qualifications.
- Manufacturers:Tier suppliers and contract molders purchase certified grades for component production.
- Distributors:General-purpose electronics grades still flow through traditional channels where documentation burdens remain lighter.
- Retailers:Small-volume construction and DIY applications source through regional distribution.
Procurement consolidation favors OEMs; Manufacturers retain fragmented sourcing patterns.
Form:
Physical form dictates processing infrastructure requirements, with pellet feedstock dominating injection molding while sheet and film serve thermoforming and lamination workflows.
- Pellets:Injection molding feedstock for medical device housings and automotive components. German precision molding clusters around Stuttgart and Munich standardize pellet specifications to reduce qualification friction.
- Sheets:Thermoformed medical equipment panels and construction glazing applications.
- Film:Lamination and decorative surface layers for consumer electronics.
- Liquid:Specialized coating and adhesive formulations.
Pellets command the broadest application base; Film exhibits the narrowest end-use concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in German precision molding clusters and Asian electronics manufacturing corridors, with regulatory divergence across FDA, EU MDR, and NMPA jurisdictions fragmenting product portfolios.
Germany
Automotive illuminated controls and medical device housings absorb premium transparent-grade volumes. EU MDR enforcement deadlines pull forward qualification cycles for ISO 10993-certified batches. Stuttgart and Munich precision molding clusters consolidate procurement relationships for Class II diagnostic applications.
United States
Medical device OEMs mandate direct compounder partnerships for FDA 510(k) master file access. Gamma-stable formulations for reusable diagnostic equipment command pricing premiums beyond commodity grades. Boston and Minneapolis medical technology corridors standardize batch-level traceability requirements.
China
Consumer electronics bezel production and NMPA medical device classifications drive parallel demand tracks. GB standards and import substitution mandates reshape local compounding requirements. Yangtze River Delta electronics assemblers source general-purpose grades amid margin compression from supply expansion.
Japan
PMDA medical device regulations and automotive interior specifications sustain specialty-grade demand. METI industrial standards govern optical clarity benchmarks for cabin electronics. Nagoya automotive supplier networks specify UV-stable formulations for backlit switch housings.
India
CDSCO medical device rules and local manufacturing incentives create first-mover openings for domestic compounding. Maharashtra and Gujarat pharmaceutical packaging corridors absorb imported transparent grades for diagnostic housings. Import substitution mandates accelerate qualification timelines for regional supply.
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement relationships in medical channels and fragmented sourcing in consumer electronics. Three archetypes dominate: integrated petrochemical groups with captive feedstock control, regional compounders serving distributor channels, and medical-grade specialists maintaining regulatory dossiers. Capacity expansion and backward integration into butadiene rubber or acrylonitrile supply chains constitute the primary competitive moves.
Among Asian integrated producers, Toray Industries, LG Chem, and Chi Mei Corporation exemplify distinct strategic positions. Toray leverages captive acrylonitrile infrastructure to anchor transparent-grade production. LG Chem sustains margin control through in-house production of butadiene rubber feedstock. Chi Mei Corporation occupies a position in general-purpose electronics grades where optical clarity and processability command premium positioning against commoditized supply.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| LG Chem |
| Chi Mei Corporation |
| Ruifeng Chemical |
| Formosa Plastics Group |
| INEOS Styrolution Group GmbH |
| Denka Company Limited |
| Kaneka |
| BASF SE |
| Others |
Supply & Pricing Matrix
EU MDR compliance deadlines for Class II diagnostic devices are compressing procurement timelines and forcing compounders to pre-qualify ISO 10993-certified batches, which elevates pricing power for dossier-holding suppliers while squeezing margin pools for distributor-dependent competitors.
Pricing Analysis
Volume placements concentrate in general-purpose electronics grades where Asian supply expansion has eroded margin; premium pricing accrues to gamma-stable medical formulations with documented biocompatibility. Price differentiation separates ISO 10993-certified transparent grades from commodity optical variants, with certification tier and geographic delivery cost as primary levers. Cost compression in consumer electronics feedstock is intensifying because of butadiene rubber oversupply from Chinese petrochemical expansions. Medical device OEMs exhibit the lowest price sensitivity due to requalification barriers; consumer electronics contract manufacturers remain most price-sensitive.
Supply Chain Analysis
Workforce availability constraints in precision molding clusters around Stuttgart and Munich are forcing German medical device OEMs to qualify secondary supply sources in Switzerland and Austria, fragmenting procurement relationships. Manufacturing concentrates in Germany, China, and Japan, with raw material dependencies on methyl methacrylate monomer, butadiene rubber, and acrylonitrile feedstocks. Single-source vulnerability from acetone cyanohydrin route concentration exposes compounders to propylene and ammonia price volatility. Distribution runs through direct technical partnerships for certified medical grades; general-purpose electronics flow through regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
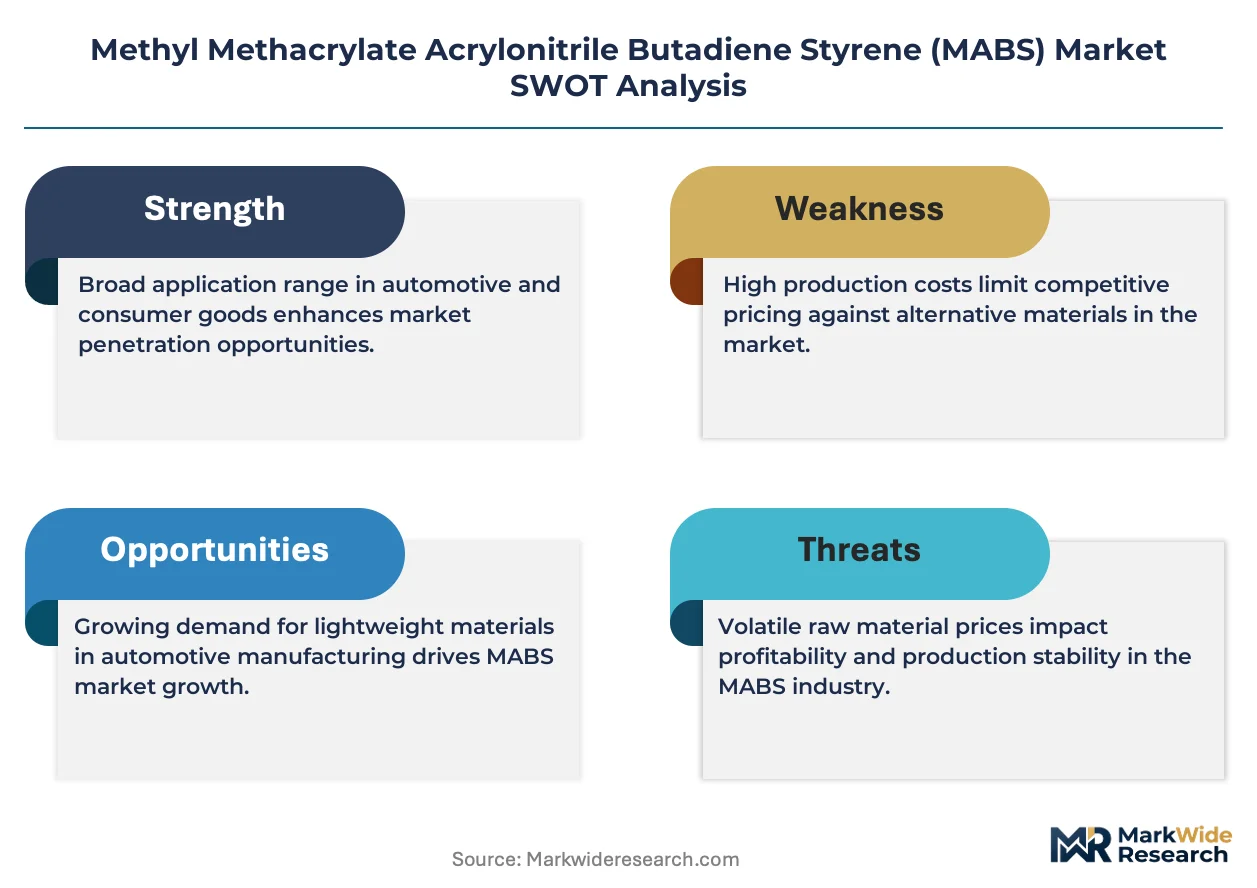
REACH SVHC disclosure requirements and EU MDR technical documentation mandates have erected a cost-of-compliance barrier that favors incumbent compounders with established regulatory dossiers and multi-year stability testing investments.
For Market Incumbents: Hedge against polycarbonate substitution defense by Covestro and SABIC through captive acrylonitrile supply chains and backward integration into butadiene rubber production. Deepen ISO 10993 master file investments to extend qualification moats around gamma-stable formulations, while expanding technical service teams in Germany to consolidate direct OEM procurement relationships. For New Entrants and Emerging Players: Capture India's CDSCO medical device import substitution opportunity by establishing domestic compounding capacity in Maharashtra or Gujarat pharmaceutical corridors. Target gamma-stable laboratory equipment as the most penetrable white-space segment, where sterilization-resistant pricing premiums exceed commodity transparent grades by substantial margins and regulatory barriers remain lower than Class II device applications. For Investors and Strategic Acquirers: The window for entry favors compounders with existing ISO 10993 dossiers and established automotive OEM relationships before EU MDR enforcement fully consolidates procurement around incumbents. Acquisition targets should demonstrate dual-track FDA and EMA regulatory capabilities. Watch ECHA PFAS restriction timelines as the critical inflection signal, since anticipated additive bans would force multi-year reformulation cycles that strain smaller compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Rubber | LG Chem's captive feedstock control insulates margins from cyclical price swings. |
| ISO 10993 Master File Investment | Toray Industries leverages biocompatibility dossiers to secure Class II device procurement. |
| Multi-layer Coextrusion Capacity Expansion | German precision molders reduce material waste while enabling thinner-wall medical housings. |
| Gamma-stable Formulation Development | Sterilization-resistant grades command pricing premiums for reusable diagnostic equipment. |
| Direct OEM Technical Partnership | Batch-level traceability requirements displace distributors in certified medical channels. |
Research Methodology
Document review covered trade customs data, SEC 10-K filings from petrochemical groups, and ECHA regulatory submissions, complemented by interviews with medical device procurement managers, automotive Tier 1 supplier quality directors, and compounder technical service leads. Secondary validation drew from FDA 510(k) databases, EU MDR notified body audit records, and NMPA medical device classification filings. Bottom-up demand modeling across injection molding clusters was triangulated against top-down feedstock consumption estimates.
Segment-level value outputs were derived through cross-referencing grade-specific pricing with volume placements across medical, automotive, and electronics channels over the projection horizon. The analytical framework modeled transparent grade, specialty grade, and general-purpose tier segmentation alongside form factor and end-user channel dimensions. CAGRs were computed from fitted growth curves incorporating methyl methacrylate feedstock volatility and regulatory qualification cycle lengths as primary inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA PFAS restriction implementation timelines and NMPA import substitution enforcement intensity. Projections reflect assumptions around sustained EU MDR compliance deadlines and stable acetone cyanohydrin route economics. Material deviation in REACH SVHC candidate list expansion or propylene price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Filled Fluoropolymer Market