
 Polyphthalamide (PPA) Resin Market | 2026-2036
Polyphthalamide (PPA) Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphthalamide (PPA) Resin Market Analysis
Modularization of resin supply bundles is rebalancing procurement patterns across tier-one automotive suppliers. DuPont de Nemours anchors its position through backward integration into adipic acid precursors. BASF SE differentiates via specialized glass-filled grades for electric motor housings. Evonik Industries competes on high-purity unfilled formulations targeting medical device OEMs.
Polyphthalamide resin is a semi-aromatic polyamide engineered from terephthalic acid and aliphatic diamines, delivering continuous service temperatures above 150°C with resistance to automotive fluids and hydrolysis. Its primary purpose is metal replacement in thermally and chemically aggressive environments across transportation and industrial equipment. Glass-filled formulations command the dominant volume position due to structural load requirements in powertrain components. Unfilled grades represent the fastest-expanding margin pool as electronics miniaturization demands precision moldability. Flame-retardant variants remain a specialty niche constrained by halogen-free certification timelines.
EPA tailpipe regulations and REACH substance restrictions are elevating thermal stability benchmarks for under-hood plastics, directly shaping PPA grade qualification protocols. FDA device material standards and IEC electrical safety frameworks extend compliance burdens into healthcare and electronics end uses. Stakeholders must monitor evolving battery pack thermal runaway standards as these will determine whether mineral-filled or glass-filled PPA architectures achieve design-in status for next-generation EV platforms.
Market Dynamics
Automotive electrification is compressing qualification cycles for high-heat thermoplastics as OEMs redesign thermal management architectures around battery pack geometries. This force is reallocating R&D budgets toward materials capable of withstanding thermal runaway events while maintaining dimensional stability across wider temperature ranges.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening limits on halogenated flame retardants are accelerating design-in of inherently heat-resistant PPA grades for European automotive wiring.
- EV battery thermal management:Chinese domestic processors are qualifying mineral-filled PPA variants for cell-to-pack housings as local EV production scales beyond internal combustion platforms.
- Metal substitution in powertrain:Glass-reinforced PPA is displacing aluminum in charge air coolers and water pumps to achieve weight reduction targets in light-duty trucks.
Market Restraints
- Adipic acid price volatility:Feedstock costs for PPA precursors fluctuate with cyclohexane supply disruptions, compressing compounder margins during energy price spikes.
- Specialty resin supply concentration:High-purity unfilled grades depend on a limited number of European and North American polymerization facilities with constrained expansion timelines.
- Polyetherimide substitution threat:PEI resins compete for high-temperature electronics applications where dielectric stability exceeds PPA performance thresholds.
Strategic Opportunities
- Medical device miniaturization:Unfilled PPA grades offer precision moldability for surgical instrument housings requiring sterilization resistance beyond polycarbonate limits.
- India automotive localization:PLI scheme incentives for component manufacturing are drawing compounder investment toward Pune and Chennai processing hubs.
- Halogen-free IEC 60695 certification:Flame-retardant PPA variants meeting glow-wire ignition standards are capturing socket and connector applications in appliance controls.
Industry Challenges
- Multi-grade qualification backlog:Tier-one suppliers face 18-24 month validation cycles for each PPA variant across OEM thermal aging protocols.
- Compounding technician scarcity:Glass fiber handling expertise and moisture-controlled processing knowledge are concentrated among aging workforces in European and Japanese facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphthalamide (PPA) Resin Market |
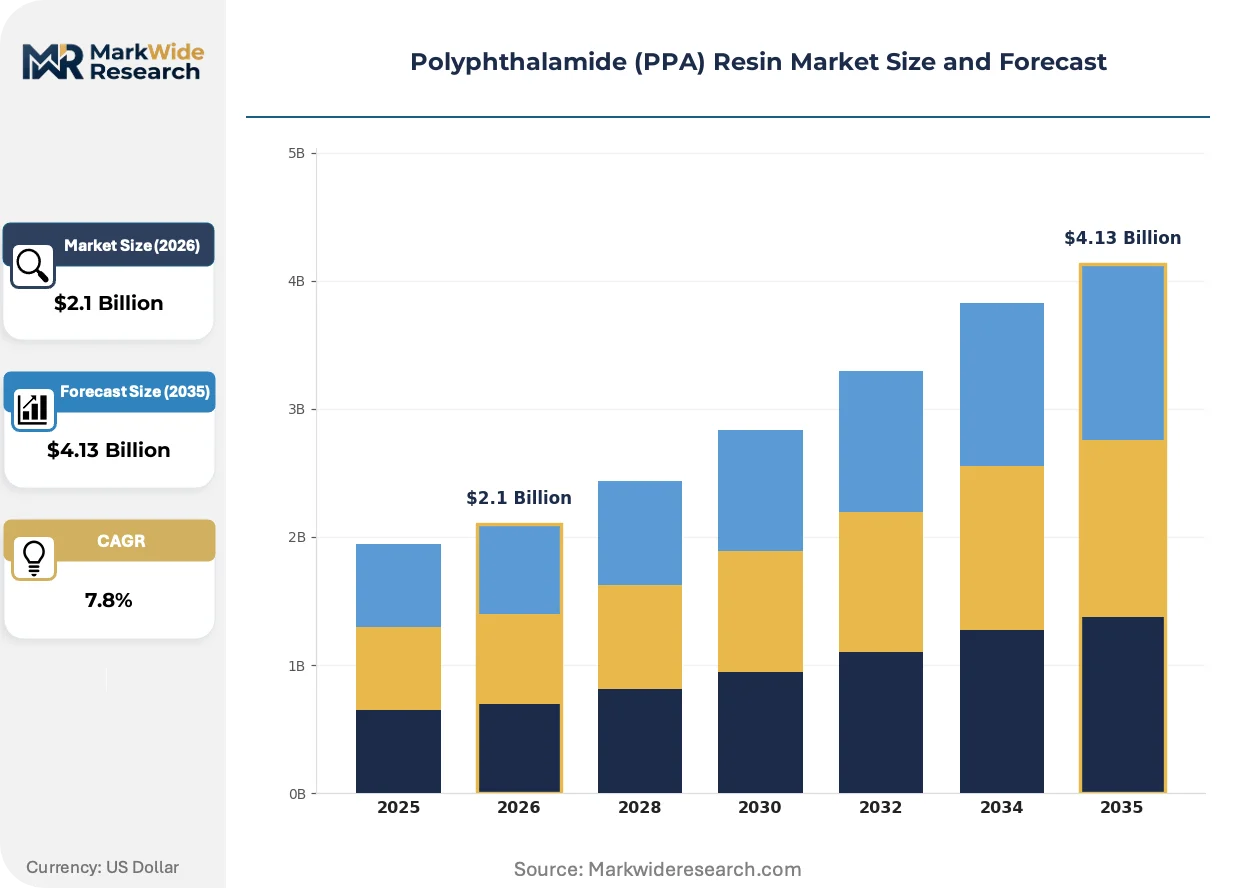
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfilled, Glass-Filled, Mineral-Filled, Flame Retardant Application: Automotive Components, Electrical Insulators, Industrial Equipment, Consumer Goods End User: Automotive, Electronics, Aerospace, Healthcare Form: Granules, Pellets, Powder, Sheets |
| Companies Covered | Evonik Industries, DuPont de Nemours, BASF SE, SABIC, EMS-Chemie, Solvay, Akro-Plastic, Celanese Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphthalamide (PPA) Resin Market Emerging Trajectories
Material science advances are converging with regulatory pressure to redefine performance benchmarks across transportation, healthcare, and industrial equipment sectors. This convergence is compressing development timelines while expanding the addressable application set for semi-aromatic polyamides.
Long-fiber thermoplastic PPA compounds are expanding into structural automotive components previously reserved for short-fiber or metal assemblies. Tier-one suppliers in Germany and the United States are adopting these materials for front-end modules and underbody shields where impact resistance must coexist with thermal stability. The technology is expanding into load-bearing applications by enabling thinner-wall designs that reduce mass without sacrificing stiffness.
EPA tailpipe standards and California Air Resources Board mandates are elevating thermal durability requirements for under-hood plastics exposed to elevated engine bay temperatures. These regulations are forcing compounders to reformulate stabilizer packages and accelerate hydrolysis resistance testing protocols. Powertrain engineers in Detroit and Stuttgart are responding by specifying PPA grades with continuous service ratings above 170°C for turbocharger ducts.
Consolidated procurement frameworks are displacing spot purchasing as automotive OEMs negotiate multi-year resin bundles with volume commitments and technical service attachments. Tier-one molders in Mexico and Eastern Europe are adapting to fixed-price arrangements that transfer inventory risk upstream to compounders. This behavioral shift is most pronounced among German luxury vehicle manufacturers seeking supply security for electrification platforms.
Polyphthalamide (PPA) Resin Market Segmentation
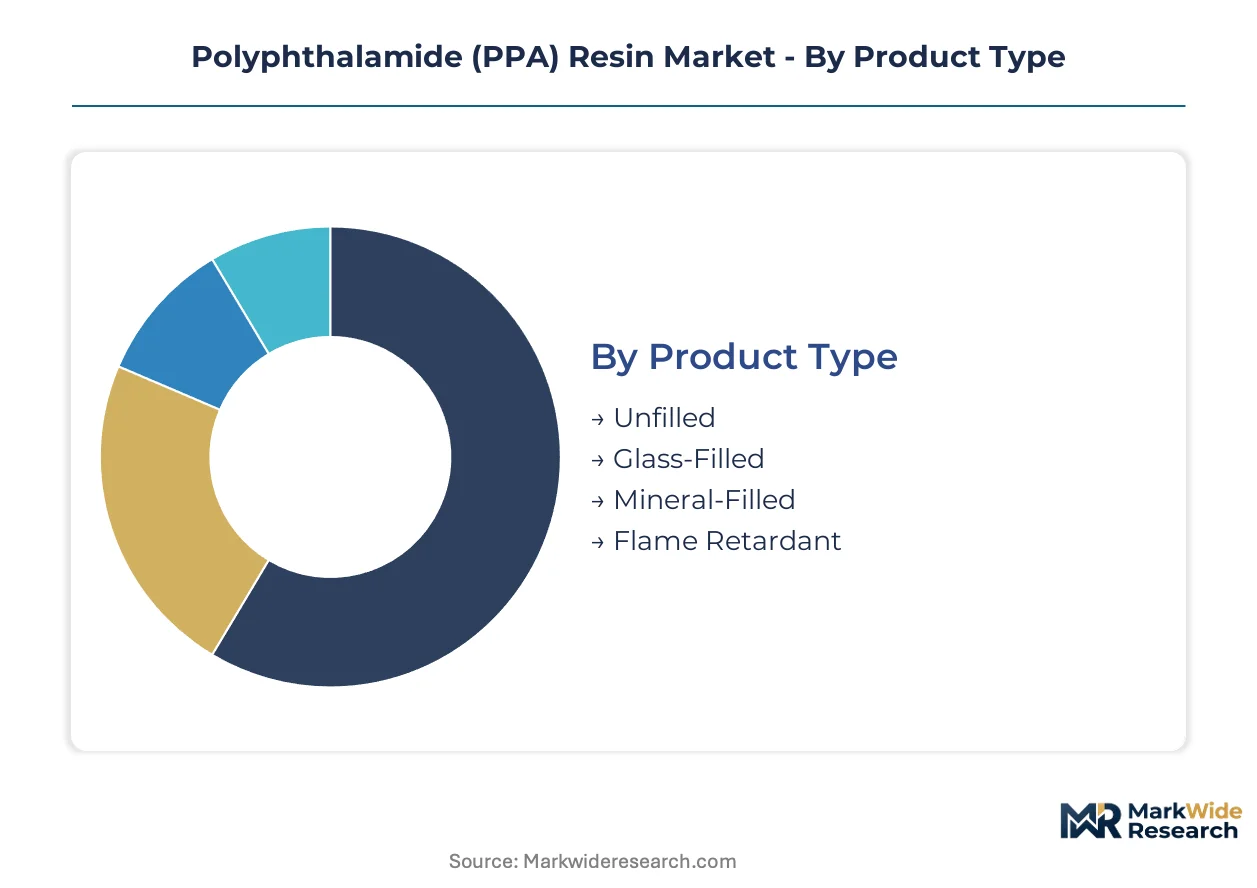
PPA resin segmentation reflects divergent technical requirements across metal replacement and precision molding applications. Compounders calibrate fiber loading, flame retardancy, and form factors to match thermal aging protocols in automotive powertrains and sterilization cycles in medical devices.
Product Type:
Customization intensity varies sharply across this category, from commodity glass-filled grades to specialized unfilled formulations requiring tight viscosity control.
- Glass-Filled:Short and long glass fiber reinforcements (30-50% loading) deliver structural rigidity for load-bearing powertrain components. Demand concentrates in Detroit and Stuttgart as OEMs substitute aluminum in charge air coolers and water pump housings to meet light-duty truck weight targets.
- Unfilled:High-purity polymer matrices engineered for precision moldability in thin-wall electronics housings and surgical instruments. Electronics miniaturization in South Korea and medical device clusters in Switzerland are expanding specifications for low-warpage grades with tight dimensional tolerances.
- Mineral-Filled:Talc or wollastonite loadings balance cost with dimensional stability for battery thermal management housings.
- Flame Retardant:Halogen-free formulations targeting IEC 60695 glow-wire ignition standards for appliance connectors and electrical sockets.
Most installed capacity flows through Glass-Filled. Expansion is steepest in Unfilled.
Application:
Volume distribution tracks the intensity of metal substitution pressure across transportation and industrial end uses.
- Automotive Components:Under-hood applications dominate consumption, with PPA replacing metals in turbocharger ducts, thermostat housings, and transmission components exposed to continuous service temperatures above 150°C. EPA tailpipe regulations and ECHA REACH substance restrictions are accelerating qualification of hydrolysis-resistant grades.
- Electrical Insulators:High dielectric strength formulations serve electric motor housings, busbar supports, and battery module separators in electrified powertrains. Chinese domestic EV producers are qualifying mineral-filled variants for cell-to-pack architectures as local production scales.
- Industrial Equipment:Pump housings, valve bodies, and compressor components in chemical processing environments.
- Consumer Goods:Premium appliance components and power tool housings requiring thermal stability.
Automotive Components commands the largest share of compounding output. Electrical Insulators is gaining share fastest.
End User:
Procurement sophistication separates automotive tier-one suppliers from specialized medical device OEMs.
- Automotive:Tier-one molders negotiate multi-year resin bundles with technical service attachments and volume commitments. German luxury vehicle manufacturers are consolidating procurement frameworks to secure supply for electrification platforms.
- Electronics:Connector and socket manufacturers specify halogen-free flame-retardant grades meeting IEC safety frameworks.
- Aerospace:Interior component applications requiring FST (fire, smoke, toxicity) compliance.
- Healthcare:Surgical instrument and device housing manufacturers demand FDA-compliant unfilled grades with sterilization resistance beyond polycarbonate limits.
Automotive channels the majority of resin volume. Healthcare is expanding most quickly.
Form:
Processing method determines form selection, with injection molding favoring flow-optimized pellets and compression applications using powders.
- Pellets:Cylindrical extrudates optimized for twin-screw compounding and injection molding with consistent melt flow indices. Automotive tier-one suppliers in Mexico and Eastern Europe specify pelletized grades for high-volume powertrain component production.
- Granules:Irregular particles for extrusion and blow molding applications in industrial pipe and sheet production.
- Powder:Fine particle sizes for rotational molding, coating, and sintering processes in specialized industrial applications.
- Sheets:Compression-molded or extruded flat stock for thermoforming and CNC machining of prototype components.
Pellets dominate processing throughput. Powder is climbing the fastest as additive manufacturing applications emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyphthalamide resin production scaled initially across German chemical corridors before dispersing to North American automotive clusters and East Asian electronics manufacturing zones. Today's demand geography tracks electrification investments and regulatory tightening across three continents.
China
Domestic EV battery production and cell-to-pack thermal management architectures are consuming mineral-filled PPA grades at unprecedented rates. MIIT's dual carbon goals and GB standards for electric vehicle safety are accelerating qualification timelines for high-heat thermoplastics. Processing hubs in Jiangsu and Zhejiang provinces are expanding compounding capacity to serve BYD and CATL supply chains.
Germany
Luxury automotive OEMs in Stuttgart and Munich are consolidating multi-year resin procurement bundles with technical service attachments. ECHA REACH substance restrictions on halogenated flame retardants are forcing reformulation of wiring harness compounds. The KBA maintains stringent thermal aging protocols that extend qualification cycles to 24 months for under-hood applications.
United States
EPA tailpipe regulations and California Air Resources Board mandates are elevating continuous service temperature requirements for powertrain plastics. Detroit-based tier-one suppliers are substituting glass-reinforced PPA for aluminum in light-duty truck charge air coolers. Southeastern compounding facilities in Tennessee and South Carolina are adding moisture-controlled processing lines.
Japan
Precision electronics miniaturization in Osaka and Nagoya industrial corridors is driving specifications for low-warpage unfilled grades. METI's industrial decarbonization roadmap is pressuring compounders to reduce energy intensity in polymerization. Long-fiber thermoplastic PPA compounds are penetrating front-end module applications previously reserved for metals.
India
PLI scheme incentives for automotive component manufacturing are drawing compounder investment toward Pune and Chennai processing clusters. BIS standards for vehicle safety are tightening material traceability requirements. Domestic EV startups are qualifying PPA grades for motor housings as local electrification platforms scale production.
Polyphthalamide (PPA) Resin Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth. The vendor base organizes into three tiers: integrated petrochemical majors with captive adipic acid supply, specialized compounders with glass fiber handling expertise, and regional processors serving price-sensitive industrial accounts. Dominant competitive moves include backward integration into precursor chemicals and long-term supply agreements with automotive OEMs.
Within the integrated majors tier, DuPont de Nemours, BASF SE, and Evonik Industries exemplify divergent specialization strategies. DuPont anchors its position through in-house production of adipic acid precursors. BASF occupies a position defined by glass-filled grades for electrified powertrains. Evonik sits within the high-purity unfilled segment targeting medical device OEMs with sterilization-resistant formulations.
| Leading Market Players |
|---|
| Evonik Industries |
| DuPont de Nemours |
| BASF SE |
| SABIC |
| EMS-Chemie |
| Solvay |
| Akro-Plastic |
| Celanese Corporation |
| Arkema |
| Others |
Supply Flow & Price Mechanics
Automotive OEM consolidation of procurement into multi-year resin bundles with volume commitments and technical service attachments is forcing compounders to absorb inventory risk and invest in dedicated moisture-controlled processing lines, compressing margins in spot markets while securing offtake stability for integrated majors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified automotive grades meeting KBA thermal aging protocols from uncertified industrial formulations and commodity spot purchases. Price differentiation hinges on REACH compliance depth and glass fiber loading precision. Cost compression in standard-tier formulations is intensifying because adipic acid feedstock volatility feeds directly into compounder margins. Tier-one automotive suppliers exhibit lowest price sensitivity due to qualification lock-in effects, while regional industrial processors in Eastern Europe and India drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns that feed compounding facilities clustered in Germany, the United States, and China. Raw material sourcing draws from cyclohexane-derived adipic acid streams, glass fiber rovings concentrated in Japanese and European suppliers, and mineral fillers from Chinese wollastonite deposits. Single-source vulnerability sits with high-purity unfilled grades polymerized at limited European facilities. Distribution runs through direct mill-to-molder arrangements for automotive tier-ones and distributor networks serving fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH substance restrictions in Europe tighten faster than EPA timelines in the United States, creating cost-advantaged qualification windows for North American compounders serving export automotive platforms.
For Market Incumbents: To counter polyetherimide substitution threats in high-temperature electronics sockets, DuPont de Nemours and BASF SE should deepen backward integration into adipic acid precursors while accelerating halogen-free flame-retardant certification cycles. Captive precursor supply and IEC 60695 glow-wire ignition compliance form dual moats against specialty resin competitors.
For New Entrants and Emerging Players: Medical device OEMs in Switzerland and South Korea represent the most penetrable white-space target, as aging European workforces concentrate glass fiber handling expertise that new entrants can replicate with automated moisture-controlled processing investments. A precision-molding technical service partnership model unlocks surgical instrument housing specifications beyond polycarbonate thermal limits.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap compounders possessing automotive qualification credentials but lacking adipic acid backward integration, as feedstock volatility creates distressed acquisition opportunities. Watch MIIT dual carbon goal acceleration and GB standard tightening for electric vehicle battery thermal management as the inflection signal determining mineral-filled PPA grade demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Captive precursor supply insulates DuPont de Nemours from cyclohexane price volatility affecting compounder margins. |
| Long-term Supply Agreement | Multi-year resin bundles with technical service attachments secure offtake from German luxury vehicle electrification platforms. |
| Capacity Expansion | Moisture-controlled processing lines in Tennessee and South Carolina serve Detroit tier-one substitution of aluminum in charge air coolers. |
| Joint Venture | Pune and Chennai processing hubs under PLI scheme incentives capture India automotive localization for motor housing qualifications. |
| Green Manufacturing Transition | METI industrial decarbonization roadmap compliance reduces polymerization energy intensity for Japanese electronics miniaturization grades. |
Methodological Framework
Multiple input streams — primary interviews with polymerization plant managers, automotive tier-one procurement leads, and medical device regulatory affairs directors; secondary validation through ECHA REACH substance restriction filings, EPA tailpipe regulation dockets, and SEC 10-K disclosures from integrated petrochemical majors — were reconciled through bottom-up grade-volume aggregation and top-down end-use demand estimation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including fiber loading tier, end-use industry vertical, flame-retardant certification status, and regional production hub concentration. CAGRs were derived from regression analysis against automotive production forecasts and electrification platform ramp schedules, with explicit modeling of Chinese EV battery thermal management adoption curves and European wiring harness reformulation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to adipic acid feedstock disruption patterns and evolving battery pack thermal runaway standards that could redirect mineral-filled versus glass-filled grade specifications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Polyamide 11 & 12 Market