
 Polystyrene Market | 2026-2036
Polystyrene Market Size, Share, and Industry Trends Forecast 2026-2036
Polystyrene Market Analysis
The gap between premium and commodity tiers is broadening as high-impact and expanded grades command technical specifications that general-purpose resin cannot match. BASF SE leverages its integrated styrenics chain to sustain margin capture in specialty copolymers. Alpek SAB de CV anchors its position through backward integration into styrene monomer production on the US Gulf Coast. INEOS Styrolution Group GmbH differentiates via recycling technology leadership in post-consumer polystyrene depolymerization.
Polystyrene is a synthetic aromatic hydrocarbon polymer derived from styrene monomer, typically polymerized through bulk, suspension, or emulsion processes to achieve molecular weights between 100,000 and 400,000 g/mol, serving primarily as a rigid, cost-effective thermoplastic for molded and foamed applications. Expanded polystyrene dominates insulation and protective packaging due to its closed-cell structure and thermal resistance, though high-impact polystyrene captures higher value in durable goods. Injection molding technology leads volume throughput in consumer electronics housings, while thermoforming competes aggressively in disposable food-service trays where cycle economics determine supplier selection.
The US EPA oversees volatile organic compound emissions from styrene production facilities, while REACH in Europe restricts residual monomer content in food-contact articles. China's MEE enforces stricter wastewater discharge standards around petrochemical complexes, elevating capital requirements for new polystyrene capacity. Stakeholders must monitor regulatory divergence on recycled-content mandates, as divergent certification schemes between jurisdictions threaten to fragment supply chain compliance costs.
Market Dynamics
Recycled-content mandates across the EU, China, and North America are forcing polystyrene producers to reconfigure feedstock sourcing and certification systems at unprecedented speed. This regulatory compression is reshaping capital allocation toward depolymerization and mechanical recycling infrastructure.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon blowing agents accelerates demand for CO2-expanded polystyrene in thermal insulation applications.
- E-commerce logistics:Protective packaging volumes from fulfillment centers absorb expanded polystyrene at rates outpacing traditional retail channels.
- Appliance manufacturing clusters:Concentrated production in China's Yangtze River Delta and Pearl River Delta sustains high-impact polystyrene offtake for refrigerator liners and air conditioner housings.
Market Restraints
- Styrene monomer volatility:Benzene-ethylene feedstock cost swings compress margins for non-integrated producers lacking captive aromatics supply.
- Single-use plastic directives:France's AGEC law and similar measures in Italy and Spain restrict disposable food-service applications regardless of recyclability claims.
- Polypropylene substitution:Random copolymer PP captures share in thin-wall packaging where clarity requirements have relaxed.
Strategic Opportunities
- India packaging conversion:Food delivery platform expansion in Mumbai, Bangalore, and Delhi creates first-mover openings for thermoformed tray suppliers.
- Chemical recycling scale-up:Pyrolysis and dissolution technologies unlock food-contact approval pathways unavailable to mechanically recycled grades.
- Building energy codes:Stricter U-value requirements in Germany's EnEV and comparable standards elevate specified insulation thicknesses.
Industry Challenges
- Sortation infrastructure gaps:Contamination rates in post-consumer polystyrene waste streams exceed mechanical recycling tolerances, requiring expensive pre-processing investments.
- Food-contact certification timelines:EFSA and FDA evaluations for recycled-content grades extend 18-36 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polystyrene Market |
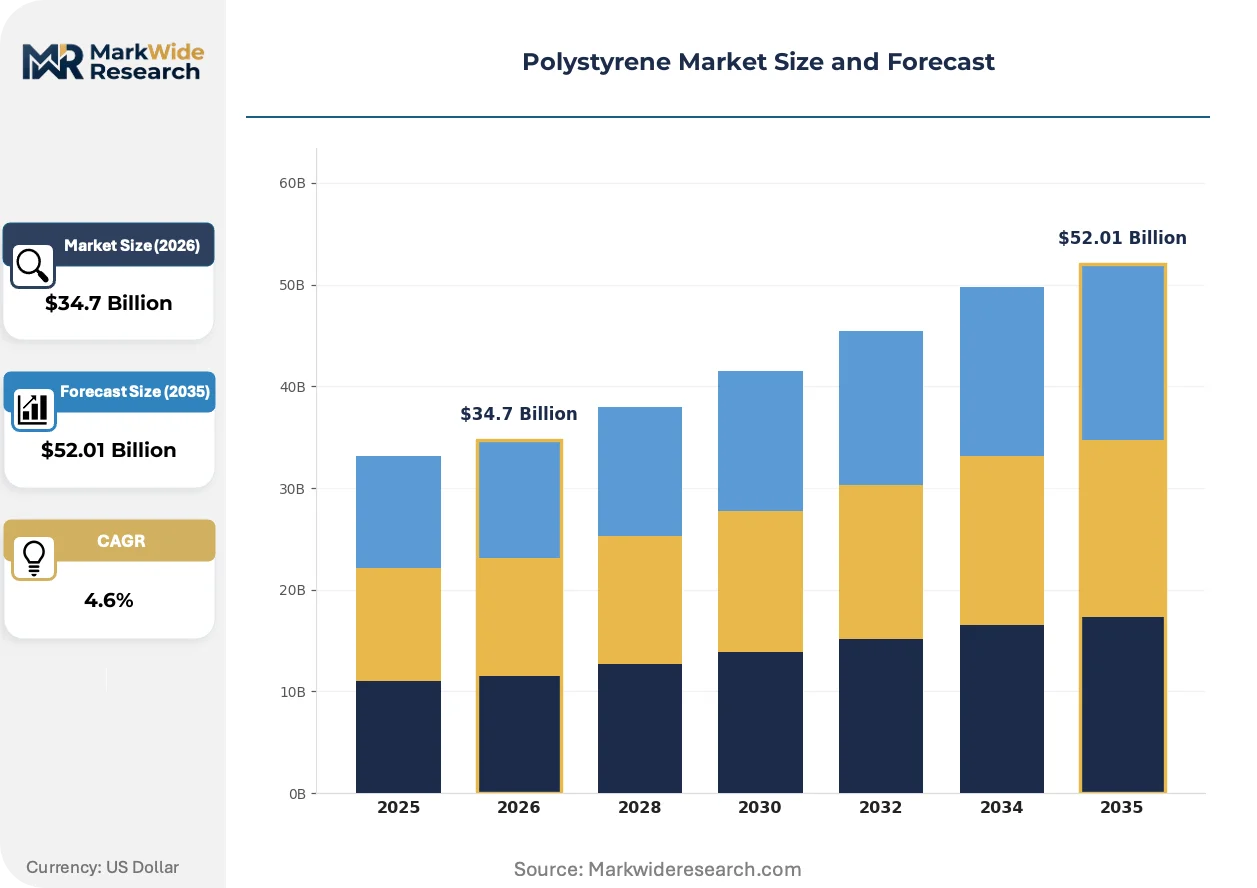
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $52.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose Polystyrene, High Impact Polystyrene, Expanded Polystyrene, Extruded Polystyrene End Use Industry: Packaging, Electronics, Construction, Consumer Goods Form: Sheets, Blocks, Granules, Films Technology: Injection Molding, Blow Molding, Extrusion, Thermoforming |
| Companies Covered | Trinseo PLC, Alpek SAB de CV, BASF SE, SABIC, Formosa Chemicals & Fibre Corporation, TotalEnergies SE, Synthos SA, Chi Mei Corporation, INEOS Styrolution Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polystyrene Market Emerging Trajectories
Digital process control and closed-loop material tracking are converging to transform how polystyrene producers demonstrate compliance and optimize yield. These capabilities are becoming prerequisites for supplier qualification in regulated end-uses.
Advanced extrusion systems with real-time density monitoring are automating quality adjustments in expanded polystyrene bead production. Appliance manufacturers in South Korea and Mexico are adopting these lines to reduce scrap rates. The technology is automating the shift from statistical process control to predictive intervention, compressing specification drift windows.
REACH restrictions on residual styrene monomer in food-contact articles are tightening testing protocols for thermoformed trays and disposable cutlery. European converters face elevated analytical costs and batch rejection risks. Small-format packaging producers in Poland and Romania are consolidating to share testing laboratory access.
Direct-to-mold pellet delivery from polymer producers is displacing distributor intermediaries in high-volume packaging accounts. Brand owners in Germany's discount retail sector now specify this channel to secure lot traceability for EUDR compliance. The model concentrates procurement leverage with resin producers possessing integrated logistics networks.
Polystyrene Market Segmentation
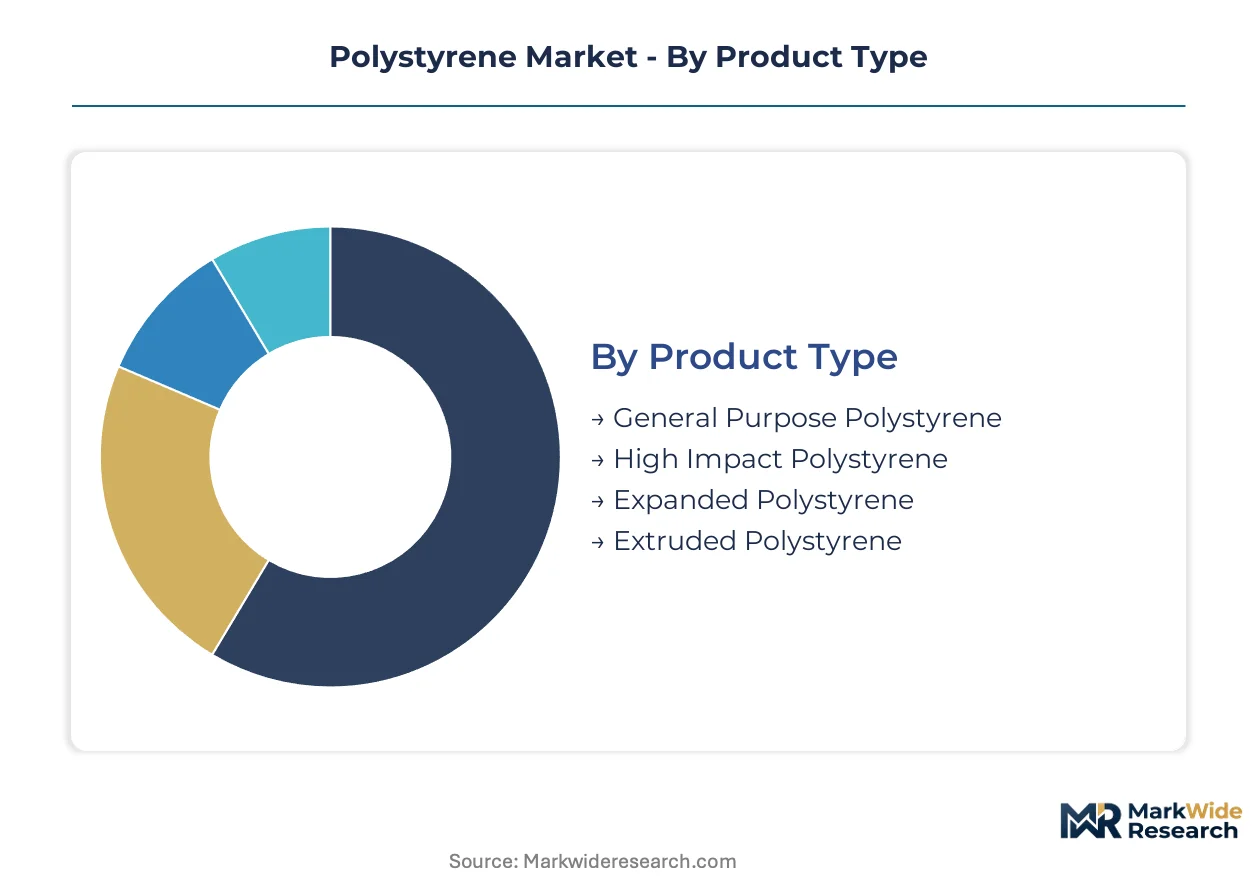
Polystyrene grades exhibit sharply divergent margin profiles and regulatory exposure. Understanding segment boundaries helps buyers align specification requirements with supplier capabilities and certification status.
Product Type:
Upgrade cycles from commodity to performance grades accelerate as appliance OEMs tighten impact specifications and building codes elevate thermal resistance requirements.
- General Purpose Polystyrene:Virgin homopolymer resin with crystal clarity and 90-95% light transmission serves optical display applications and low-cost disposable cutlery. China's Yangtze River Delta injection molders absorb volumes for electronics housings where cost minimization overrides durability requirements; REACH residual monomer limits tighten testing burdens for food-contact converters.
- High Impact Polystyrene:Polybutadiene rubber modification at 5-15% loading delivers Izod impact resistance above 100 J/m for refrigerator liners and appliance housings. Mexico's Monterrey appliance cluster specifies HIPS grades from US Gulf Coast suppliers; rubber content variability creates lot-to-lot color consistency challenges that prequalification protocols must address.
- Expanded Polystyrene:Bead foaming with pentane or CO2 blowing agents yields closed-cell structures with thermal conductivity below 0.040 W/m·K for insulation boards. Germany's EnEV building energy codes drive specified thickness increases; F-Gas Regulation phaseout redirects specification toward CO2-expanded grades.
- Extruded Polystyrene:Continuous extrusion with hydrofluorocarbon or hydrocarbon blowing produces rigid foam boards with compressive strength above 200 kPa for below-grade waterproofing. Foundation and inverted roof assemblies in South Korea's commercial construction sector absorb premium-grade volumes.
Volume placements concentrate in General Purpose Polystyrene; the faster expansion belongs to High Impact Polystyrene.
End Use Industry:
Application cost tiers separate specification-grade demand from commodity offtake, with certification requirements and volume scale determining supplier selection criteria.
- Packaging:Thermoformed trays, clamshells, and protective foam absorb expanded and general-purpose grades across e-commerce fulfillment and food-service channels. India's Mumbai and Bangalore food delivery platforms generate first-mover demand for disposable tray suppliers; France's AGEC law restricts single-use applications regardless of recyclability claims.
- Electronics:Housings for televisions, monitors, and small appliances require high-impact grades with flame-retardant additives meeting UL 94 specifications. China's Pearl River Delta contract manufacturers specify lot-traceable resin for EUDR compliance; injection molding dominates volume throughput.
- Construction:Thermal insulation boards, geofoam fill, and concrete formwork consume expanded and extruded grades. Germany and South Korea building energy codes elevate U-value requirements; below-grade waterproofing specifications favor extruded polystyrene compressive strength.
- Consumer Goods:Toys, furniture components, and household organizers utilize general-purpose and high-impact grades where durability requirements vary widely. Price-sensitive substitution toward polypropylene captures share in non-critical applications.
Packaging commands the greatest volume throughput; Construction exhibits the steepest specification upgrade trajectory.
Form:
Supply chain configuration favors direct-to-mold pellet delivery for high-volume accounts, while sheet and block intermediates serve fragmented converter bases.
- Sheets:Extruded or thermoformed flat stock serves thermoforming feedstock for trays, lids, and display packaging. European converters face elevated analytical costs from REACH residual monomer testing protocols.
- Blocks:Molded or cut billet forms enable CNC machining of prototypes, architectural models, and specialty packaging inserts. Germany's discount retail sector specifies lot traceability for EUDR compliance.
- Granules:Virgin or recycled pellet form dominates injection molding and extrusion feedstock. Direct delivery from polymer producers displaces distributor intermediaries in high-volume packaging accounts.
- Films:Thin-gauge oriented or cast films serve limited specialty applications where clarity and printability requirements apply. Biaxial orientation lines concentrate in Japan and South Korea.
Granules capture procurement leverage consolidation; Films remain the most constrained supply channel.
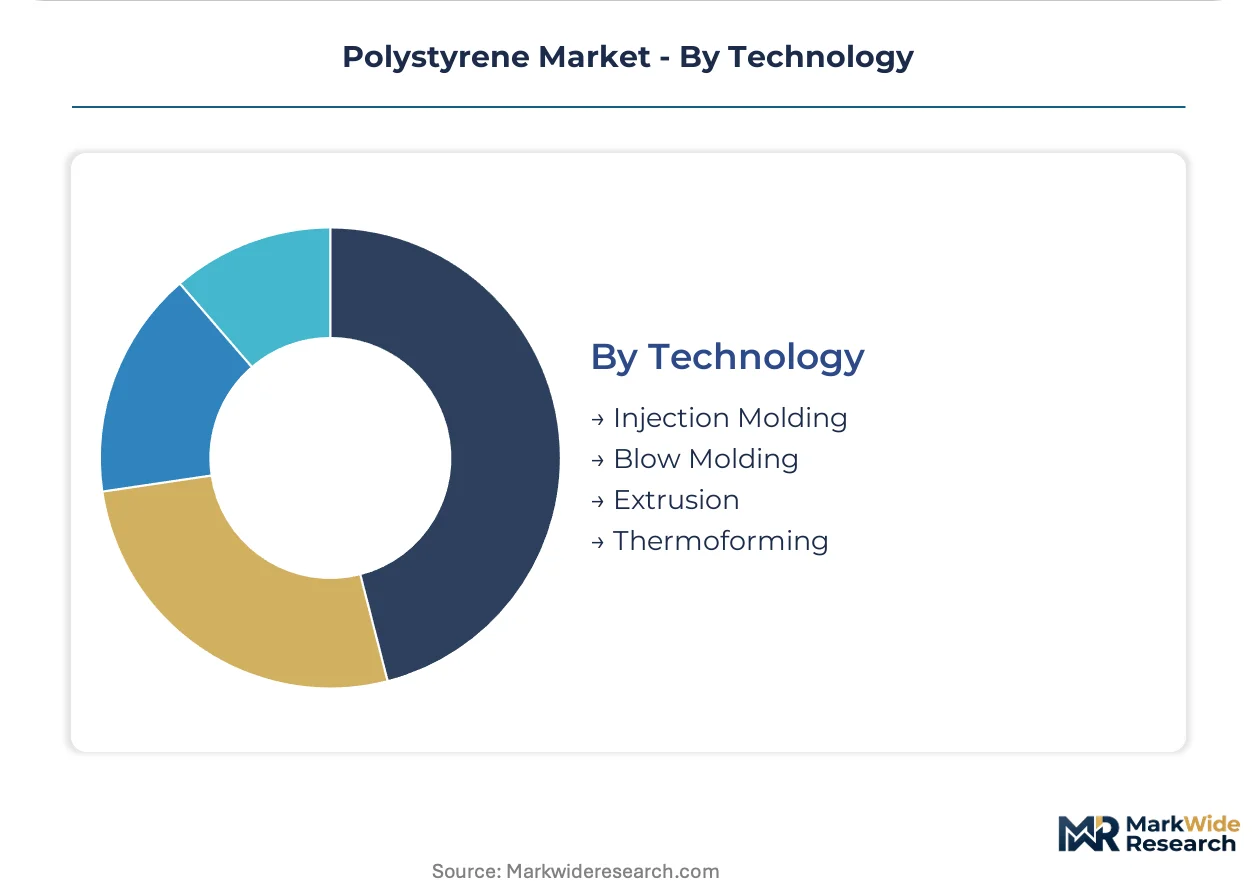
Technology:
Process selection hinges on part geometry complexity, cycle economics, and surface finish requirements, with automation investments compressing specification drift windows.
- Injection Molding:High-pressure melt injection into precision tooling yields complex geometries with tight dimensional tolerances for electronics housings and appliance components. South Korean and Mexican appliance manufacturers adopt real-time process control systems to reduce scrap rates.
- Blow Molding:Extrusion or injection blow forming produces hollow articles including bottles and containers where polystyrene clarity advantages apply. Limited penetration due to polyethylene cost competitiveness.
- Extrusion:Continuous melt shaping generates sheet, profile, and foam board outputs. Advanced systems with real-time density monitoring automate quality adjustments in expanded polystyrene bead production.
- Thermoforming:Vacuum or pressure forming of pre-extruded sheet dominates disposable food-service tray production. Cycle economics determine supplier selection; small-format producers in Poland and Romania consolidate to share testing laboratory access.
Injection Molding maintains the highest capital intensity per line; Thermoforming spreads across the most fragmented converter base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta polystyrene consumption corridor absorbs volumes for electronics housings and appliance components at rates exceeding other Chinese manufacturing clusters.
China
Appliance OEMs in the Pearl River Delta specify high-impact grades for refrigerator liners and air conditioner housings. China's MEE enforces stricter wastewater discharge standards around petrochemical complexes. Yangtze River Delta injection molders consume general-purpose resin for cost-sensitive electronics applications.
United States
US Gulf Coast styrene monomer production anchors backward-integrated supply for domestic polystyrene converters. The EPA oversees volatile organic compound emissions from production facilities. Monterrey appliance manufacturers across the southern border specify US-sourced high-impact grades.
Germany
EnEV building energy codes drive specified thickness increases for expanded polystyrene insulation boards. REACH restrictions tighten testing protocols for residual styrene monomer in food-contact articles. Discount retail sector brand owners specify direct-to-mold pellet delivery for EUDR compliance.
India
Food delivery platform expansion in Mumbai, Bangalore, and Delhi generates thermoformed tray demand. BIS standards govern material specifications for food-contact applications. Western Maharashtra packaging converters consolidate to share testing laboratory access.
South Korea
Appliance manufacturers adopt real-time process control systems to reduce injection molding scrap rates. MFDS regulates food-contact material safety approvals. Seoul Capital Area electronics contract manufacturers specify lot-traceable resin for export compliance.
Polystyrene Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integrated styrenics chain control and recycling technology differentiation. The vendor base concentrates around petrochemical conglomerates with captive aromatics supply and regional specialists with thermoforming scale. Three archetypes dominate: integrated petrochemical majors, regional packaging converters, and recycling technology developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers reconfigure for recycled-content mandates.
Among Germany-based integrated producers, BASF SE exemplifies the petrochemical major archetype through its styrenics chain position. Alpek SAB de CV anchors the North American supply structure with Gulf Coast monomer integration. INEOS Styrolution Group GmbH occupies a position representing recycling technology leadership in post-consumer polystyrene processing.
| Leading Market Players |
|---|
| Trinseo PLC |
| Alpek SAB de CV |
| BASF SE |
| SABIC |
| Formosa Chemicals & Fibre Corporation |
| TotalEnergies SE |
| Synthos SA |
| Chi Mei Corporation |
| INEOS Styrolution Group GmbH |
| Others |
Supply Flow & Price Mechanics
Benzene price volatility on the US Gulf Coast cascades through styrene monomer contracts into three distinct polystyrene pricing tiers: virgin homopolymer resin trades on spot-indexed formulas, high-impact grades command rubber-content premiums, and recycled-content grades absorb certification cost pass-throughs that widen spreads against commodity benchmarks.
Pricing Analysis
Yield-based pricing anchors premium tiers where appliance OEMs pay for lot-to-lot color consistency and impact specification compliance. Three-tier pricing structure across premium, standard, and economy levels separates EUDR-traceable resin from general-purpose commodity grades. Cost compression in standard-tier general-purpose polystyrene is intensifying because polypropylene substitution captures thin-wall packaging share. Discount retail procurement teams in Germany exhibit highest price sensitivity; appliance manufacturers in Mexico's Monterrey cluster prioritize specification stability over unit cost.
Supply Chain Analysis
Container freight rates from the US Gulf Coast to China's Yangtze River Delta determine landed cost competitiveness for non-integrated converters. Geographic supply concentration centers on the United States, China, and Germany where integrated petrochemical complexes control aromatics feedstock. Raw material dependencies draw from benzene-ethylene crackers, polybutadiene rubber for impact modification, and pentane or CO2 blowing agents for expanded grades. Single-source vulnerability around styrene monomer supply exposes non-integrated processors to margin compression. Distribution runs through direct-to-mold pellet delivery for high-volume packaging accounts and distributor networks for fragmented thermoforming converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH residual monomer restrictions and EU F-Gas Regulation compliance costs erect capital barriers that favor incumbent producers with integrated testing laboratories and captive recycling infrastructure.
For Market Incumbents: Anticipate styrene monomer volatility by securing backward integration into aromatics supply or long-term offtake agreements with Gulf Coast crackers. Invest in depolymerization certification capacity before EFSA and FDA food-contact approval timelines extend competitive moats. Defend against polypropylene substitution by emphasizing HIPS impact performance in appliance specifications where durability requirements are non-negotiable. For New Entrants and Emerging Players: Launch via regional packaging converter partnerships in India's Mumbai-Bangalore-Delhi corridor where food delivery platform expansion outpaces local thermoforming capacity. Target white-space in CO2-expanded polystyrene insulation boards as Germany's EnEV codes elevate specified thickness requirements. Pursue mechanical recycling pre-processing contracts to capture sortation infrastructure gaps that incumbent producers have left unfilled. For Investors and Strategic Acquirers: Distressed-cycle entries favor recycling technology developers with proven depolymerization yields in post-consumer waste streams. Long-term viability hinges on food-contact certification pathways that unlock premium pricing unavailable to mechanical recyclers. Monitor EFSA approval timelines as the inflection signal: accelerated clearances indicate regulatory acceptance of chemical recycling routes that reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | Captive aromatics supply insulates margin capture against benzene-ethylene volatility on the US Gulf Coast. |
| Chemical Recycling Scale-Up | Pyrolysis and dissolution technologies unlock EFSA food-contact approvals unavailable to mechanically recycled grades. |
| Direct-to-Mold Pellet Delivery | Lot traceability for EUDR compliance concentrates procurement leverage with integrated logistics networks in Germany. |
| Real-Time Process Control Deployment | South Korean appliance manufacturers reduce injection molding scrap rates through automated density monitoring systems. |
| Regional Converter Consolidation | Shared testing laboratory access defrays REACH analytical costs for small-format thermoforming producers in Poland and Romania. |
Methodological Framework
Independent corroboration across plant managers at integrated petrochemical complexes, procurement leads at appliance OEMs, and distribution channel partners underwrites the qualitative findings. Primary interviews with technical R&D directors at recycling technology developers and thermoforming converter operations heads were validated against secondary sources including customs and trade data, SEC 10-K filings from listed petrochemical majors, and Cefic industry reports. Bottom-up volume estimates from grade-level production data were reconciled with top-down demand assessments across end-use industries.
Comparable-period anchoring to historical production and consumption patterns established baseline trajectories for the projection horizon. The analytical framework models segmentation across grade tier, end-use industry, regional production hub, and certification status. CAGRs were derived from trend extrapolation adjusted for regulatory intervention effects and substitution elasticity parameters. Forecast inputs incorporated appliance manufacturing cluster output indices and building energy code adoption timelines.
Styrene monomer price volatility, regulatory divergence on recycled-content mandates, and sortation infrastructure investment delays are the dominant revision risks. Forecasts reflect assumptions about certification timeline durations and substitution thresholds that could shift if polypropylene clarity specifications advance. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market