
 Paper Processing Resins Market | 2026-2036
Paper Processing Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Processing Resins Market Analytics
ISO 14001 environmental management certification is reorganizing supplier qualification protocols across the paper processing resins value chain, forcing reformulation investments before mills approve vendor lists. Chang Chun Group leverages its integrated phenol-to-resin manufacturing footprint to sustain cost advantages in Asian coating applications. Dow Chemical Company anchors North American supply through direct mill relationships, while BASF SE differentiates via specialty epoxy grades for food-contact packaging barriers.
Paper processing resins comprise thermosetting and thermoplastic polymers—typically phenol-formaldehyde, urea-formaldehyde, or epoxy-based systems with curing temperatures between 120°C and 180°C—applied to impart wet strength, printability, and dimensional stability to cellulose substrates. Phenolic resins retain dominance in moisture-resistant packaging liners where bond durability under humid conditions determines performance grades, while epoxy resins capture premium share in decorative paper laminates requiring thermal resistance and surface clarity. Polyvinyl acetate competes aggressively in stationery adhesives where cost sensitivity and ease of water cleanup outweigh extreme durability demands.
REACH restrictions on formaldehyde emissions in Europe and China's MEE enforcement of GB standards for VOC content in paper products are tightening permissible chemical footprints, redirecting R&D spending toward low-free-formaldehyde and bio-based binder chemistries. The US EPA's Toxic Substances Control Act reporting requirements for imported resin precursors add compliance layers that favor domestic producers with established regulatory infrastructure. Stakeholders must monitor evolving substance restriction schedules and pre-qualify alternative chemistries before existing formulations face market exclusion.
Market Dynamics
Formaldehyde emission regulations across China, Europe, and North America are forcing simultaneous resin reformulation and supplier requalification, compressing approval timelines while elevating R&D burn rates for compliant low-VOC alternatives.
Growth Catalysts
- E-commerce fulfillment standards:Asia-Pacific packaging converters are expanding water-resistant coating orders as moisture barrier specifications tighten for corrugated shipping containers.
- REACH formaldehyde restrictions:European regulatory pressure is redirecting mill procurement toward low-free-formaldehyde phenolic systems certified for food-contact applications.
- India corrugated capacity expansion:Domestic board production additions require consistent resin supply for moisture barrier treatments in monsoon-exposed distribution networks.
Market Restraints
- Phenol feedstock volatility:Benzene-propylene pricing spreads directly compress phenolic resin margins, forcing either formula dilution or price pass-through resistance.
- Specialized curing equipment:Thermosetting resin systems require 120°C to 180°C application infrastructure that smaller Asian converters lack capital to install.
- Epoxy substitution in premium laminates:Decorative paper manufacturers are migrating toward epoxy systems for thermal resistance, eroding phenolic share in high-margin segments.
Strategic Opportunities
- GB standard compliance services:Chinese mills need technical partnership for MEE enforcement navigation, creating advisory revenue streams beyond commodity resin sales.
- Bio-based binder development:Lignin-derived and tannin-formaldehyde systems qualify for EU Green Deal procurement preferences in public-sector packaging contracts.
- Direct mill technical integration:Resin suppliers embedding application engineers at converter sites capture specification influence before procurement tenders release.
Industry Challenges
- ISO 14001 certification timelines:Environmental management pre-qualification now requires 12 to 18 months for supplier list inclusion, delaying new entrant revenue recognition.
- Legacy phenolic inventory stranding:Mills holding conventional high-formaldehyde stocks face write-downs as GB and REACH thresholds ratchet downward without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Processing Resins Market |
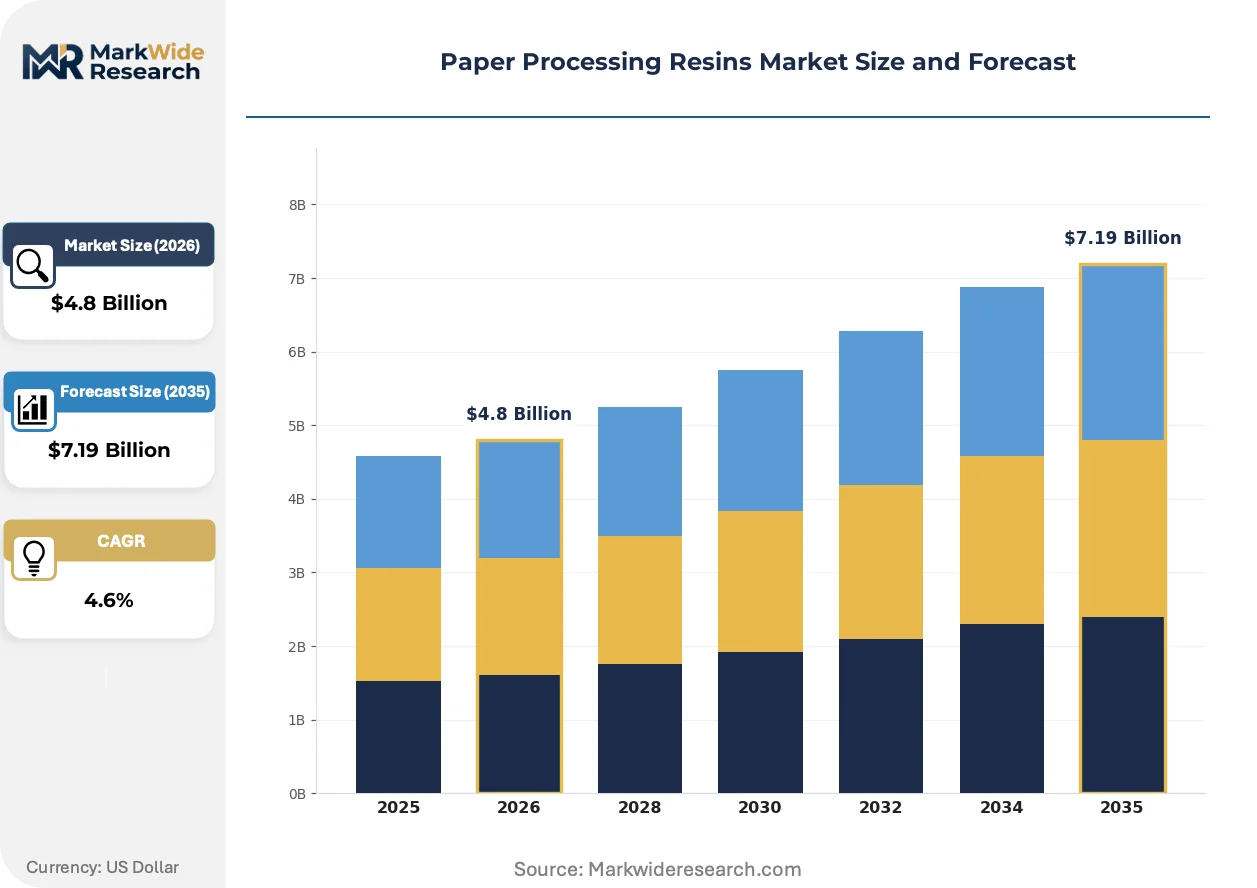
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Resins, Phenolic Resins, Urea-Formaldehyde, Polyvinyl Acetate End User: Publishing, Packaging, Stationery, Decorative Paper Application: Coatings, Adhesives, Laminates, Ink Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Chang Chun Group, Vertex Chem Private Limited, DIC Corporation, Wacker Chemie AG, Royal DSM, Dow Chemical Company, Nissin Chemical Industry Co., Ltd., Mitsui Chemicals, Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Processing Resins Market Evolving Landscape
Water-based resin dispersion technologies are displacing solvent-borne systems across Asian packaging corridors, while regulatory chemistry mandates in Europe and China accelerate bio-based binder pilot programs.
Low-temperature curing phenolic formulations are miniaturizing energy requirements for moisture-resistant coatings. Indian and Vietnamese corrugated converters lacking steam infrastructure are adopting these systems for ambient-pressure application lines. This technology is miniaturizing the capital barrier for moisture barrier adoption among mid-tier packaging producers.
China's MEE enforcement of GB standards for VOC content in paper products is eliminating grandfathered formulations from mill approval lists. Domestic phenolic producers must demonstrate sub-threshold free-formaldehyde content through third-party testing before contract renewal. Food-contact packaging segments in coastal provinces face the steepest compliance timelines.
Specification authority is migrating from procurement departments to mill technical teams responsible for coating line performance. Direct resin supplier engagement with application engineers now precedes formal tender participation in India and Southeast Asia. This shift concentrates vendor selection power among specialists offering on-site formulation adjustment capabilities.
Paper Processing Resins Market Segmentation
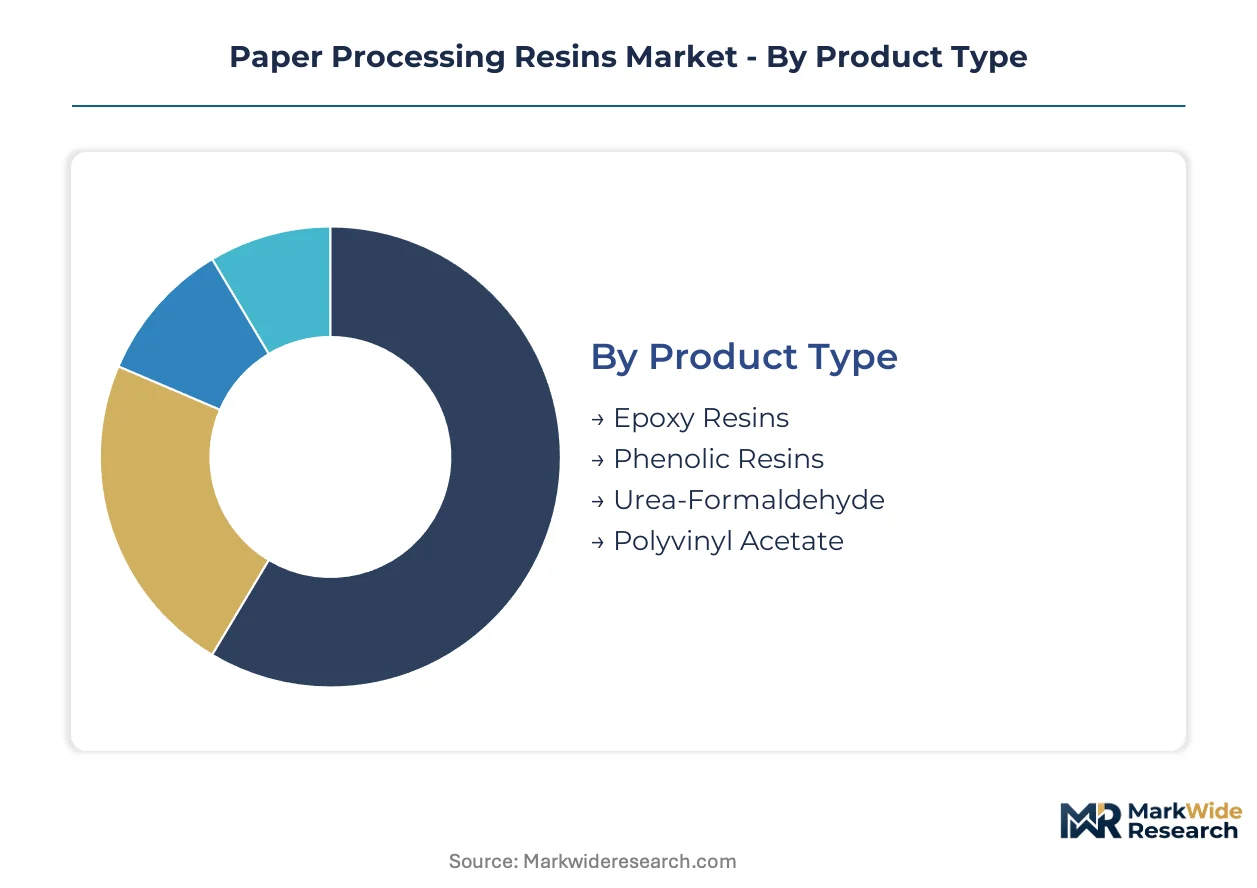
Segmentation in paper processing resins reveals how formulation chemistry, end-use durability requirements, and procurement channel preferences intersect. Distinct performance specifications across packaging, publishing, and decorative applications create specialized supply relationships that resist commoditization.
Product Type:
Channel mix varies sharply by resin chemistry—phenolic and urea-formaldehyde systems flow predominantly through direct mill relationships, while polyvinyl acetate and specialty epoxies reach smaller converters via distributor networks.
- Phenolic Resins:Thermosetting polymers derived from phenol-formaldehyde condensation cure between 120°C and 180°C to deliver wet strength and dimensional stability. Demand concentrates in India's corrugated packaging sector where monsoon-exposed distribution networks require moisture barrier performance. GB standard enforcement on formaldehyde emissions is forcing reformulation toward low-free-formaldehyde grades before mills renew supplier contracts.
- Epoxy Resins:Bisphenol-A or novolac-based systems offering superior thermal resistance and surface clarity for premium applications. Decorative paper laminators in coastal China are specifying epoxy grades for kitchen countertop and furniture overlay production. REACH restrictions on food-contact applications are redirecting procurement toward certified low-migration formulations.
- Urea-Formaldehyde:Cost-competitive thermosetting binders for interior-grade paper products with moderate moisture resistance. Stationery and notebook manufacturers in Vietnam favor these systems for spiral-bound product lines where extreme durability is secondary to cost control.
- Polyvinyl Acetate:Water-dispersible thermoplastic adhesives requiring no elevated curing infrastructure. Small-scale packaging converters across Indonesia purchase through wholesale channels for carton sealing and label attachment applications.
By volume, phenolic resins lead across Asia-Pacific board production. By growth pace, epoxy systems for decorative laminates are expanding most quickly as furniture and construction sectors upgrade surface performance specifications.
End User:
Cost tier stratification separates specification-grade resin procurement in premium packaging and decorative segments from price-sensitive purchasing in mass-market stationery.
- Packaging:Corrugated containerboard and folding carton producers represent the dominant volume sink, with moisture-resistant coating specifications tightening across e-commerce fulfillment supply chains. Water-based phenolic dispersions are displacing solvent-borne alternatives in Chinese coastal mills.
- Decorative Paper:Laminate-facing and furniture overlay manufacturers command premium resin grades for thermal resistance and surface aesthetics. Epoxy penetration is accelerating in this segment as phenolic systems face performance ceilings.
- Publishing:Magazine and catalog printers require sizing agents for printability and dimensional stability. This segment exhibits stable but slow-growing demand as digital substitution compresses print volumes.
- Stationery:Notebook, envelope, and office product manufacturers prioritize cost minimization over extreme performance. Polyvinyl acetate and diluted urea-formaldehyde systems dominate through wholesale procurement channels.
Packaging commands the largest share of resin tonnage. Decorative paper generates the steepest margin expansion as epoxy substitution elevates average selling prices.
Application:
Application-driven formulation requirements determine whether resin suppliers embed technical staff at converter sites or transact through arm's-length distribution.
- Coatings:Surface sizing and barrier treatments for moisture resistance represent the most technically demanding application category. Direct supplier-mill technical partnerships are standard for coating line optimization.
- Adhesives:Bonding systems for corrugated board manufacture and carton assembly. Volume concentrates in high-speed production lines where open time and tack development are critical.
- Laminates:Multi-layer decorative and industrial paper composites requiring thermal and chemical resistance. Specification authority resides with application engineers rather than procurement departments.
- Ink:Resin binders for printing ink vehicles, representing a specialized niche with distinct formulation requirements from structural paper treatments.
Coatings absorb the greatest resin volume. Laminates are climbing the fastest as construction and furniture sectors expand decorative surface consumption.
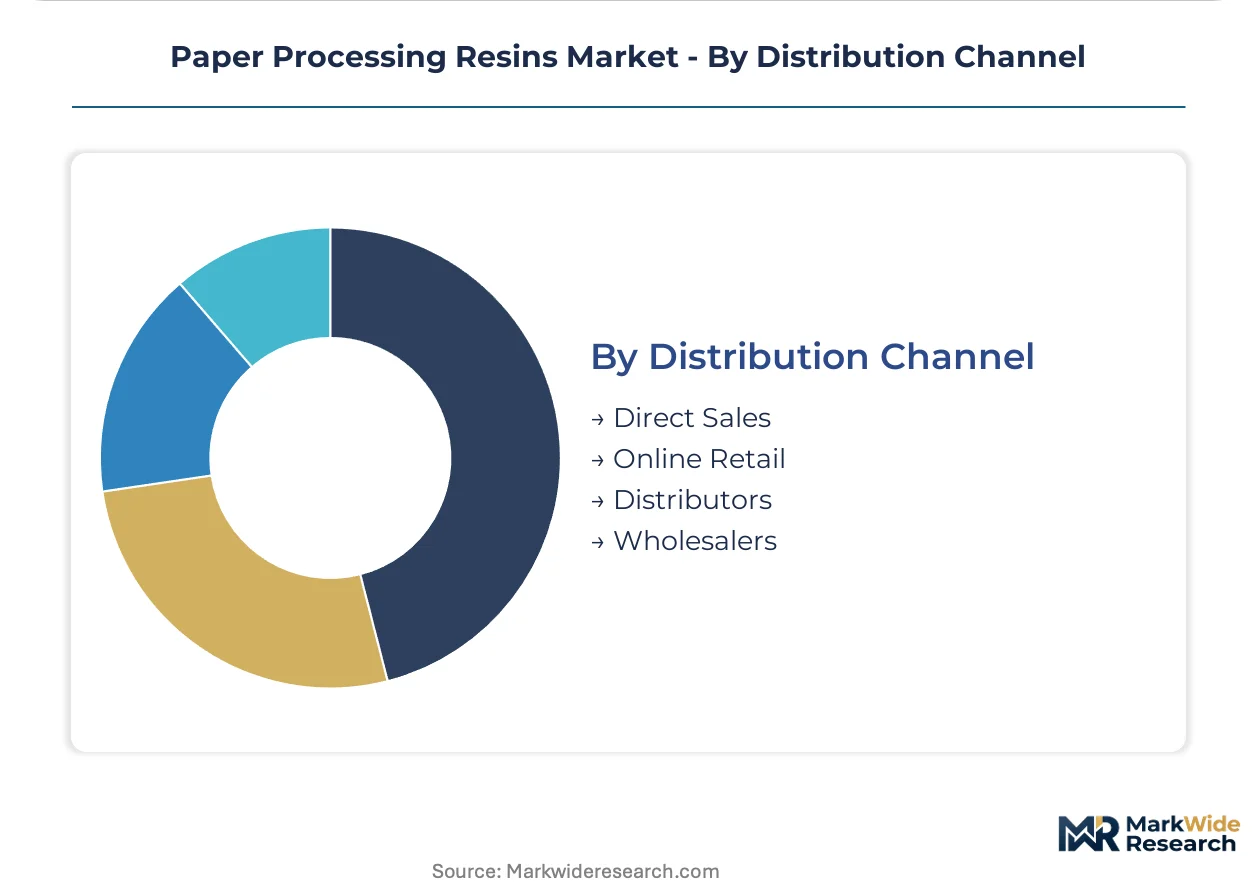
Distribution Channel:
Customer scale and technical complexity determine channel selection—largest converters negotiate direct supply agreements while mid-tier and small producers rely on intermediaries for inventory management and technical support.
- Direct Sales:Mill-specific contracts with embedded technical service for coating line integration and formulation adjustment. Dominates phenolic and epoxy procurement among top-tier packaging and laminate producers.
- Distributors:Regional inventory stocking with application support for mid-scale converters. Critical for urea-formaldehyde and polyvinyl acetate penetration among second-tier packaging operations.
- Wholesalers:Price-focused bulk supply without technical service for smallest converters and trading companies. Primary channel for standardized adhesive grades in fragmented stationery markets.
- Online Retail:Emerging channel for sample procurement and small-batch specialty grades, particularly among R&D laboratories and prototype development shops.
Direct sales channels move the largest resin volumes. Online retail is gaining share fastest as digital procurement platforms expand in Asian packaging corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters in Asia-Pacific dominate procurement volumes, with moisture-resistant coating specifications tightening across e-commerce fulfillment networks. European mills navigate REACH formaldehyde thresholds while Indian board producers expand monsoon-exposed distribution infrastructure.
China
Corrugated containerboard producers in coastal provinces are expanding water-based phenolic dispersion capacity as MEE enforcement eliminates grandfathered formulations from mill approval lists. GB standards for VOC content in paper products now require third-party testing certification before contract renewal. The Yangtze River Delta clustering around Shanghai anchors the highest concentration of food-contact packaging resin qualification activity.
India
Domestic corrugated capacity additions in Maharashtra and Gujarat require consistent resin supply for moisture barrier applications during monsoon distribution cycles. BIS certification timelines for imported phenolic precursors are extending supplier pre-qualification windows. The Mumbai-Pune industrial corridor hosts the densest concentration of technical service partnerships between resin suppliers and converter application engineers.
United States
EPA Toxic Substances Control Act reporting requirements for imported resin precursors are adding compliance layers that favor domestic producers with established regulatory infrastructure. Folding carton manufacturers in the Midwest are consolidating procurement around direct mill relationships with embedded technical service. The Ohio River Valley paperboard clustering is witnessing accelerated qualification of low-free-formaldehyde phenolic alternatives ahead of potential state-level emission restrictions.
Germany
Decorative paper laminators in Bavaria and North Rhine-Westphalia are specifying epoxy grades for kitchen countertop and furniture overlay production as phenolic systems face thermal resistance ceilings. REACH restrictions on food-contact applications are redirecting procurement toward certified low-migration formulations. The Baden-Württemberg industrial region is piloting lignin-derived binder systems qualifying for EU Green Deal procurement preferences.
Japan
Specialty epoxy producers serving the premium decorative laminate segment are expanding technical integration with furniture manufacturers in the Chubu region around Nagoya. METI guidance on chemical substance management is accelerating mill migration toward ISO 14001-certified resin suppliers. The Kanto clustering east of Tokyo concentrates the highest density of R&D partnerships for bio-based phenolic alternatives.
Paper Processing Resins Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive phenol supply and specialized resin formulators serving regional packaging corridors. The supplier base organizes around three archetypes: integrated phenol-to-resin manufacturers leveraging feedstock cost advantages, specialty epoxy producers capturing premium decorative laminate share, and regional distributors bridging technical service gaps for mid-tier converters. Competitive dynamics center on M&A activity consolidating regional formulation capabilities and strategic partnerships embedding application engineers at mill sites.
Within the integrated manufacturing tier, Chang Chun Group exemplifies the phenol-to-resin footprint sustaining cost advantages in Asian coating applications. Dow Chemical Company anchors North American supply relationships through direct mill technical integration. BASF SE occupies a position among specialty chemical producers differentiating via certified grades for food-contact packaging barriers.
| Leading Market Players |
|---|
| Chang Chun Group |
| Vertex Chem Private Limited |
| DIC Corporation |
| Wacker Chemie AG |
| Royal DSM |
| Dow Chemical Company |
| Nissin Chemical Industry Co., Ltd. |
| Mitsui Chemicals, Inc. |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Water-based phenolic dispersions displacing solvent-borne systems across Asian packaging corridors are simultaneously redrawing procurement geography and compressing margin structures for legacy formulation suppliers. This substitution dynamic concentrates purchasing power among coastal Chinese mills with MEE-compliant infrastructure while fragmenting supplier relationships across inland converters lacking capital for aqueous coating line retrofits.
Pricing Analysis
Cost-plus contracts indexed to benzene-propylene spreads dominate phenolic resin procurement, with quarterly price adjustments passing through feedstock volatility to converters. Price differentiation separates ISO 14001-certified low-VOC grades from conventional formulations, while volume scale and embedded technical service determine contract tiers. Pricing pressure stems from epoxy substitution in decorative laminates, where thermal resistance specifications command premium positioning. Small-scale Vietnamese and Indonesian converters exhibit highest price sensitivity, sourcing through wholesale channels without formulation support.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and container availability constraints on Asia-Europe trade lanes are elevating landed costs for European decorative paper laminators sourcing Chinese epoxy intermediates. Phenol feedstock draws from integrated crackers in China, South Korea, and Thailand, with formaldehyde supply anchored in regional methanol-to-derivatives capacity. Single-source vulnerability concentrates in specialty novolac epoxy hardeners produced at limited Asian sites. Distribution runs through direct mill technical partnerships for coating applications and regional distributors for standardized adhesive grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as e-commerce fulfillment standards tighten moisture barrier specifications across Asia-Pacific corrugated networks, creating durable specification upgrade demand.
For Market Incumbents: Compound technical integration advantages by embedding application engineers at Indian and Vietnamese converter sites before procurement tender releases. Capture backward integration into captive phenol supply through offtake agreements with Yangtze River Delta crackers. Defend against epoxy substitution in decorative laminates by accelerating low-temperature curing phenolic pilot programs with Bavarian furniture overlay manufacturers. For New Entrants and Emerging Players: ISO 14001 certification fast-track services for Chinese mills navigating MEE enforcement create advisory revenue streams beyond commodity resin sales. Target mid-tier Indonesian packaging converters lacking steam infrastructure with ambient-pressure phenolic systems. Penetrate through distributor partnerships offering inventory management plus basic formulation adjustment, avoiding direct competition with integrated phenol-to-resin manufacturers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors in Southeast Asia holding established mill relationships but lacking technical service depth. Five-to-ten year viability hinges on successful navigation of REACH and GB standard convergence toward unified low-VOC specifications. Monitor BIS certification timeline extensions for imported phenolic precursors as inflection indicator for Indian market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Supply | Chang Chun Group's integrated footprint sustains cost advantages in Asian coating applications. |
| Low-Temperature Curing Formulation Development | Miniaturized energy requirements unlock mid-tier converter adoption in steam-constrained Vietnamese facilities. |
| ISO 14001 Certification Investment | Twelve-to-eighteen month pre-qualification timelines now gate supplier list inclusion across European and Asian mills. |
| Direct Mill Technical Partnership | Application engineer embedding at converter sites captures specification influence before formal tender participation. |
| Bio-Based Binder Pilot Programs | Lignin-derived systems qualify for EU Green Deal procurement preferences in Baden-Württemberg public-sector packaging contracts. |
Research Methodology
Cross-validation between primary interviews with resin plant managers, procurement leads at downstream packaging converters, distribution channel partners, and technical R&D directors and secondary validation through customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and GB standards documentation anchors the qualitative findings. Bottom-up triangulation from individual converter procurement volumes and top-down reconciliation against regional board production capacity estimates structure the analytical framework.
Sensitivity analysis around benzene-propylene price spreads, MEE enforcement timelines, and epoxy substitution rates in decorative laminates informs scenario boundaries across the analysis window. Segmentation dimensions modeled include resin chemistry tier, end-use industry application, distribution channel structure, and regional regulatory cluster. CAGRs derive from weighted average growth assumptions applied to segment-level base values, with e-commerce fulfillment standard adoption curves and corrugated capacity expansion pipelines serving as primary demand-side inputs.
Decision-makers should treat outputs as directional under assumptions of sustained GB and REACH formaldehyde threshold convergence; material deviation through regulatory grandfathering or feedstock price collapse would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Co-Polymer Resin Market