
 Methyl Silicone Market | 2026-2036
Methyl Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Silicone Market Analytics
Medical-grade and high-purity specification tiers is redrawing competitive boundaries in methyl silicone supply. Dow leverages backward integration into siloxane monomers to sustain cost discipline across sealant and coating grades. Wacker Chemie AG anchors European demand through specialized emulsion capacity serving personal care and electronics customers. Shin-Etsu Chemical Co., Ltd dominates Asia-Pacific supply of ultra-high-purity methyl silicones for semiconductor encapsulation.
Methyl silicone denotes polydimethylsiloxane-based materials synthesized via hydrolysis and condensation of dimethyldichlorosilane, yielding viscosities from 0.65 cSt to millions of cSt depending on chain length and crosslink density; these materials function primarily as dielectric insulators, waterproofing agents, and thermally stable lubricants across industrial systems. Sealants and coatings command the deepest margin pools within product type segmentation, driven by construction durability standards and automotive lightweighting needs. Electronics applications in adhesives and insulators represent the fastest-expanding demand vector, fueled by electric vehicle power electronics and 5G infrastructure thermal management requirements.
REACH registration mandates in Europe and evolving GB standards under China's SAMR framework are elevating analytical certification burdens for imported and domestic silicone formulations alike. FDA oversight of medical-device-grade silicones in the United States restricts market entry to suppliers with validated cleanroom production and extractables testing protocols. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer to emerging purity regimes elsewhere.
Market Dynamics
East Asian electronics manufacturers are consolidating methyl silicone procurement around thermal management specifications, while REACH and GB standards simultaneously tighten purity thresholds, forcing suppliers to choose between certification investments and market exit.
Growth Catalysts
- Electric vehicle power electronics:Thermal interface materials in battery modules and inverters are pulling high-viscosity methyl silicones into automotive supply chains at volumes previously reserved for industrial applications.
- REACH registration mandates:ECHA compliance requirements for siloxane monomers are filtering out informal suppliers, concentrating volume among registrants with validated analytical protocols.
- 5G base station deployment:Dielectric encapsulation for millimeter-wave antennas is creating specification tiers that reward suppliers with semiconductor-grade purification capabilities.
Market Restraints
- Dimethyldichlorosilane feedstock volatility:Chlorosilane supply interruptions in China's Jiangsu province transmit directly to methyl silicone pricing instability for non-integrated processors.
- Ultra-high-purity concentration:Semiconductor-grade supply chains cluster around Shin-Etsu's Nagano facilities and Dow's Midland complex, creating single-source vulnerability for 99.999%+ specifications.
- Fluorosilicone substitution:Fuel-system and aerospace applications requiring solvent resistance are migrating to fluorinated alternatives where temperature extremes exceed methyl silicone operational windows.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device assembly are creating first-mover openings for methyl silicone suppliers with BIS-certified emulsion capacity.
- Medical device extrudables:FDA-validated cleanroom production for implantable-grade silicones commands 3-4x standard pricing multiples and locks in decade-long supply agreements.
- Digital formulation platforms:AI-driven viscosity prediction tools are compressing R&D cycles for custom sealant grades, enabling faster response to automotive OEM specification changes.
Industry Challenges
- Cross-contamination control:Medical-grade certification requires dedicated reactor trains and analytical segregation protocols that idle capacity during standard-grade production campaigns.
- Extractables testing backlog:USP Class VI and ISO 10993 validation timelines now stretch 18-24 months, delaying market entry for new medical silicone formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Silicone Market |
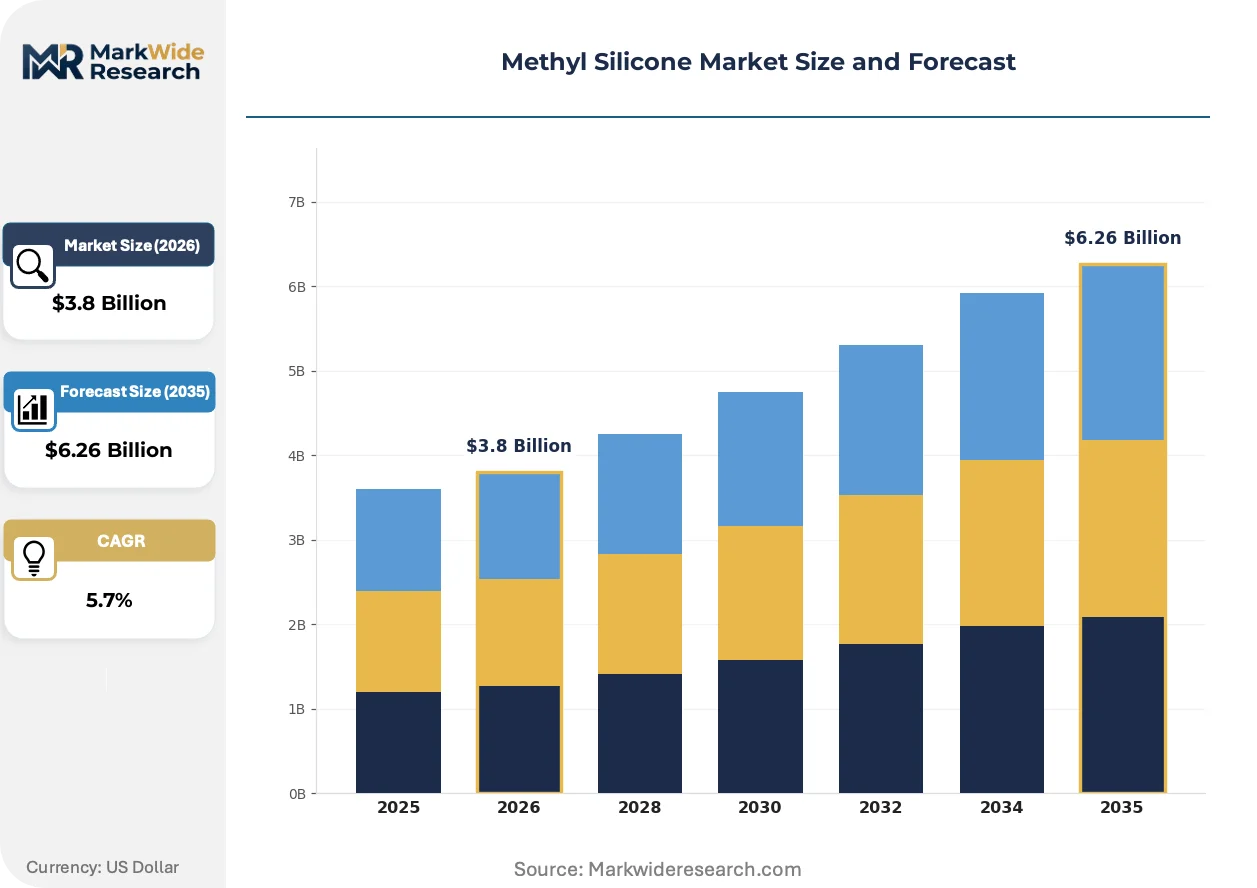
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Sealants, Coatings, Greases End Use Industry: Construction, Automotive, Electronics, Personal Care Form: Liquid, Solid, Gel, Paste Application: Adhesives, Insulators, Lubricants, Surfactants |
| Companies Covered | Wacker Chemie AG, Dow, Momentive, Shin-Etsu Chemical Co., Ltd, Elkem ASA, Evonik Industries AG, Kaneka Corporation, KCC Corporation, Siltech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Silicone Market Evolving Landscape
Advanced thermal management requirements in electrified transport and telecommunications infrastructure are compressing silicone specification cycles and rewarding suppliers with integrated purification and formulation capabilities.
Low-volatility methyl silicone fluids formulated for vacuum deposition are displacing traditional potting compounds in automotive inverter assemblies. Tier-1 suppliers in Germany and Japan specify these materials for direct-chip cooling architectures. The shift is displacing legacy epoxy-based thermal interface materials from power module designs above 150°C continuous operation.
China's SAMR framework for GB standards on siloxane emissions in personal care products is forcing reformulation of cosmetic-grade emulsions. Domestic brands now require volatility certificates from third-party laboratories. The regulation most affects Jiangsu-based emulsion producers serving shampoo and skincare OEMs, who are accelerating migration to low-D4/D5 formulations ahead of enforcement deadlines.
Automotive OEMs in South Korea and Germany now bundle silicone procurement with thermal simulation services, requiring suppliers to co-develop material-property datasets for finite-element analysis. This integration of materials supply with engineering support is displacing traditional distributor relationships in high-value segments. The pattern is most visible in battery pack assembly contracts where thermal runaway modeling determines silicone selection.
Methyl Silicone Market Segmentation
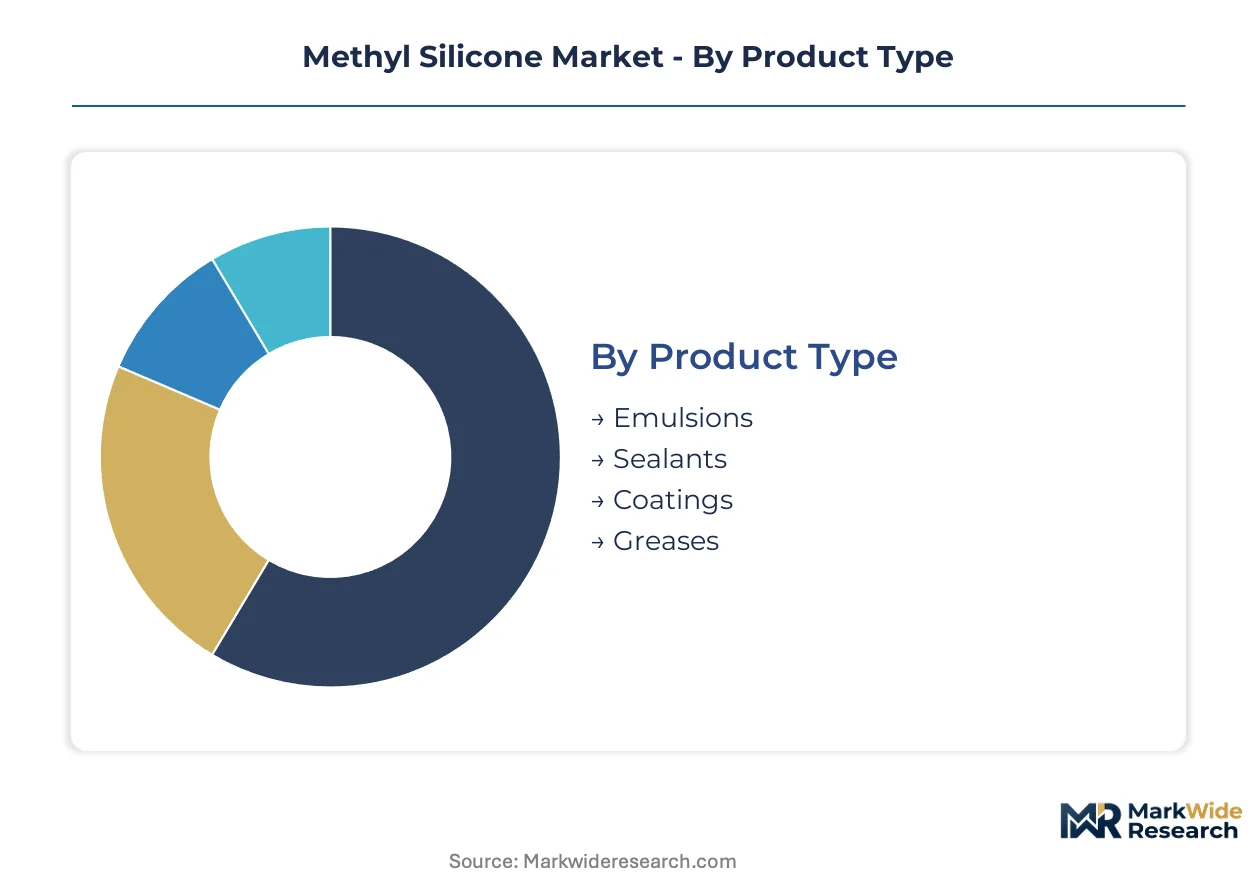
Methyl silicone procurement patterns diverge sharply across product grades and regional regulatory regimes. Specification tiers for thermal management, medical implantation, and construction durability create distinct margin pools that reward targeted manufacturing investments.
Product Type:
Domestic production in China and Germany supplies construction-grade emulsions and sealants, while ultra-high-purity coatings and specialized greases move through export-oriented supply chains serving semiconductor and aerospace OEMs.
- Emulsions:Water-based dispersions with 30-60% silicone content serve cosmetic and textile finishing applications. Jiangsu province manufacturers supply domestic personal care brands under tightening SAMR volatility regulations.
- Sealants:Crosslinked polydimethylsiloxane formulations cure through moisture or heat activation. Construction durability standards in Germany and Japan pull high-modulus grades into structural glazing and automotive assembly applications.
- Coatings:Solvent-based and solventless systems protect electronics substrates from moisture and thermal cycling.
- Greases:Thickened silicone fluids lubricate bearings and seals across extreme temperature ranges.
Sealants command the established base. The steepest expansion runs through coatings formulated for power electronics thermal management.
End Use Industry:
Volume concentration tilts toward construction and automotive in domestic markets, while electronics and personal care segments drive premium pricing through purity-certified supply chains.
- Construction:Structural glazing, weatherproofing, and expansion joint applications consume medium-viscosity sealants. German and Japanese building codes specify 25-year durability warranties that lock in approved supplier lists.
- Automotive:Battery module encapsulation, inverter potting, and gasket sealing pull high-purity methyl silicones into EV supply chains. South Korean OEMs now bundle silicone procurement with thermal simulation co-development.
- Electronics:Semiconductor encapsulation and 5G antenna dielectrics require 99.999%+ purity grades.
- Personal Care:Hair conditioning and skin emollient applications face reformulation pressure under evolving GB standards on siloxane emissions.
Construction anchors volume throughput. Electronics applications are climbing the fastest as thermal interface specifications tighten.
Form:
Processing economics favor liquid and gel formulations in high-throughput manufacturing, while solids and pastes serve specialized repair and assembly operations with lower volume but higher per-kilogram margins.
- Liquid:Low-viscosity fluids from 0.65 cSt to 1000 cSt serve dielectric cooling and cosmetic applications. Shin-Etsu's Nagano facilities and Dow's Midland complex concentrate semiconductor-grade liquid supply.
- Gel:Soft, conformable materials cushion delicate components against vibration and thermal shock. Automotive battery pack designers in South Korea specify gel-based thermal interface materials for cell-to-cell spacing.
- Solid:Cured elastomers and resins machine into seals and insulators.
- Paste:Thixotropic formulations fill gaps in irregular assemblies.
Liquid forms dominate production scale. Gel formulations are gaining share fastest through EV battery thermal management adoption.
Application:
Adhesive and insulator specifications fragment across customer tiers, with automotive and electronics OEMs demanding validated analytical protocols that informal suppliers cannot satisfy.
- Adhesives:Pressure-sensitive and structural bonding grades attach dissimilar substrates in electronics and medical device assembly. FDA-validated cleanroom production for implantable-grade adhesives commands premium pricing multiples.
- Insulators:Dielectric materials separate conductive elements in high-voltage equipment. 5G base station deployment in East Asia pulls low-dielectric-constant silicones into millimeter-wave antenna designs.
- Lubricants:Thermally stable fluids reduce friction across extreme temperature ranges.
- Surfactants:Silicone polyethers modify surface tension in coatings and personal care.
Insulators hold the mature demand position. Adhesives for medical and electronics assembly show the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports high-purity methyl silicone formulations to South Korean battery manufacturers, while Chinese Jiangsu-based producers supply construction-grade emulsions across Southeast Asian construction markets.
China
Jiangsu and Zhejiang provinces host downstream silicone clusters serving automotive and electronics OEMs with thermal interface materials. SAMR's evolving GB standards on siloxane emissions are forcing reformulation of cosmetic-grade emulsions ahead of enforcement deadlines. Nantong and Zhangjiagang chemical parks concentrate dimethyldichlorosilane hydrolysis capacity for domestic sealant and coating supply chains.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify 25-year durability warranties for structural glazing sealants that lock in approved supplier lists. ECHA REACH registration mandates for siloxane monomers filter out informal suppliers, concentrating volume among registrants with validated analytical protocols. Leverkusen and Burghausen industrial corridors anchor European emulsion and high-purity coating production.
United States
FDA oversight of medical-device-grade silicones restricts market entry to suppliers with validated cleanroom production and extractables testing protocols. EPA and OSHA frameworks govern chlorosilane handling at Texas and Michigan production sites. Midland, Michigan hosts integrated siloxane monomer capacity serving semiconductor encapsulation specifications.
Japan
METI guidelines on chemical substance management align with semiconductor-grade purity requirements for 5G antenna dielectrics. Nagano prefecture facilities concentrate ultra-high-purity methyl silicone supply for chip encapsulation. Osaka and Tokyo electronics clusters pull low-dielectric-constant silicones into millimeter-wave infrastructure deployment.
South Korea
Battery pack assembly contracts in Gyeonggi and Chungnam provinces bundle silicone procurement with thermal runaway modeling services. MFDS regulations on medical device materials parallel FDA validation timelines for implantable-grade formulations. Busan-Ulsan industrial zones drive gel-based thermal interface material adoption for cell-to-cell spacing in EV modules.
Methyl Silicone Market Competitive Landscape
Listed leaders compete with private specialists across purity certification tiers, creating a bifurcated structure where integrated chemical conglomerates hold scale advantages and focused specialists capture medical-grade premiums. Dow and Wacker Chemie AG anchor the upper tier through backward integration into siloxane monomers, while mid-scale emulsion producers compete on formulation speed for construction and personal care segments. Three archetypes dominate: integrated petrochemical giants with captive feedstock, regional emulsion specialists serving domestic construction codes, and ultra-high-purity purifiers targeting semiconductor encapsulation. Competitive moves concentrate on capacity expansion in Jiangsu province and strategic partnerships bundling materials supply with thermal simulation services.
Within the integrated petrochemical tier, Dow represents North American backward integration into siloxane monomers, while Wacker Chemie AG exemplifies European specialized emulsion capacity. Shin-Etsu Chemical Co., Ltd occupies the ultra-high-purity anchor position for Asia-Pacific semiconductor supply chains.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Dow |
| Momentive |
| Shin-Etsu Chemical Co., Ltd |
| Elkem ASA |
| Evonik Industries AG |
| Kaneka Corporation |
| KCC Corporation |
| Siltech Corporation |
| Others |
Value Network & Pricing Analysis
Low-D4/D5 cosmetic-grade silicone substitution for legacy emulsion formulations is simultaneously redrawing Jiangsu province's supply geography and compressing pricing economics for standard-grade producers unable to absorb reformulation costs under tightening SAMR volatility mandates.
Pricing Analysis
Semiconductor-grade versus construction-grade versus emerging medical-grade pricing gaps now structure methyl silicone procurement negotiations across buyer tiers. Three-tier pricing structure across medical-certified, industrial-standard, and construction-economy levels anchors transactional dynamics, with FDA-validated cleanroom production and ISO 10993 extractables testing commanding substantial premiums over commodity sealant grades. Cost compression in construction-grade emulsions is intensifying because Jiangsu-based producers compete for shrinking personal care volumes under GB standard reformulation deadlines. Automotive OEM procurement teams exhibit lowest price sensitivity due to thermal simulation service bundling, while Southeast Asian construction distributors face acute margin pressure from spot-market volatility.
Supply Chain Analysis
Strait of Malacca transit routes underpin dimethyldichlorosilane feedstock flows from Jiangsu hydrolysis facilities to Southeast Asian emulsion processors. Supply concentrates in China, Germany, and Japan, with Nagano prefecture and Midland, Michigan anchoring ultra-high-purity liquid production for semiconductor encapsulation. Raw material dependencies center on chlorosilane monomers, methyl chloride, and copper catalyst systems. Single-source vulnerability around Shin-Etsu's Nagano facilities for 99.999%+ specifications creates concentration risk for advanced electronics supply chains. Distribution runs through authorized distributor networks serving construction and personal care segments, while direct OEM relationships dominate automotive and electronics thermal management procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal simulation service bundling now expands faster than base silicone volumes, creating recurring-revenue attach opportunities that decouple supplier economics from commodity resin pricing cycles.
For Market Incumbents: Compound defensive positioning through backward integration into siloxane monomers and dedicated reactor trains for medical-grade certification. Fluorosilicone substitution in fuel-system applications threatens methyl silicone share in aerospace segments; capacity addition in India's PLI-subsidized electronics corridors offers geographic hedge against Chinese feedstock volatility. For New Entrants and Emerging Players: Differentiate on BIS-certified emulsion capacity serving India's semiconductor assembly incentives. Medical device extrudables present the most penetrable white space, with 18-24 month USP Class VI validation timelines creating barrier-protected niche for patient capital. Co-development partnerships with South Korean battery pack designers offer fastest path to thermal interface material qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional emulsion specialists in Jiangsu and Zhejiang provinces holding SAMR-compliant volatility certificates but lacking thermal management formulation expertise. Long-term viability hinges on five-to-ten year electrification capex cycles in automotive and telecommunications infrastructure. Monitor ECHA REACH registration renewal timelines for siloxane monomers as inflection indicator for competitive filtration among non-integrated processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomers | Dow's Midland complex demonstrates cost discipline across sealant and coating grades. |
| Medical-Grade Cleanroom Certification | FDA-validated production locks in decade-long supply agreements at 3-4x standard pricing. |
| Thermal Simulation Service Bundling | South Korean OEMs now require co-developed material-property datasets for finite-element analysis. |
| Low-D4/D5 Formulation Migration | Jiangsu emulsion producers accelerate reformulation ahead of SAMR enforcement deadlines. |
| India PLI Scheme Capacity Positioning | BIS-certified emulsion capacity creates first-mover openings for semiconductor and mobile device assembly. |
Research Methodology
Cross-validation between procurement director interviews at East Asian electronics manufacturers and customs trade data anchors the qualitative findings on methyl silicone specification tier migration. Primary engagement with thermal management engineers at South Korean battery OEMs, sealant formulators at German construction chemical firms, and regulatory affairs leads at Jiangsu emulsion producers combined with secondary validation through ECHA REACH registration databases, SAMR GB standard drafts, and SEC 10-K chemical segment disclosures. Bottom-up volume builds from application-level consumption models triangulate against top-down industry association aggregates.
Sensitivity analysis around chlorosilane feedstock price scenarios and regulatory enforcement timing variations shapes the projection framework. Segmentation dimensions span viscosity grade, end-use industry, purity certification tier, and regional production hub across the modeling period. CAGRs derive from compounding annual application growth rates weighted by segment margin contributions. Electric vehicle power electronics thermal interface specifications and 5G base station deployment curves constitute key industry-specific forecast inputs.
Forecasts assume regulatory continuity in ECHA REACH and SAMR GB frameworks; material policy shifts would require re-modeling purity threshold trajectories and compliance cost burdens. Practitioners should keep alternative scenarios live as semiconductor-grade concentration risk and fluorosilicone substitution thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Conductive Plastics Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Global Cellulose Acetate Market