
 Agar Resin Market | 2026-2036
Agar Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Agar Resin Market Analysis
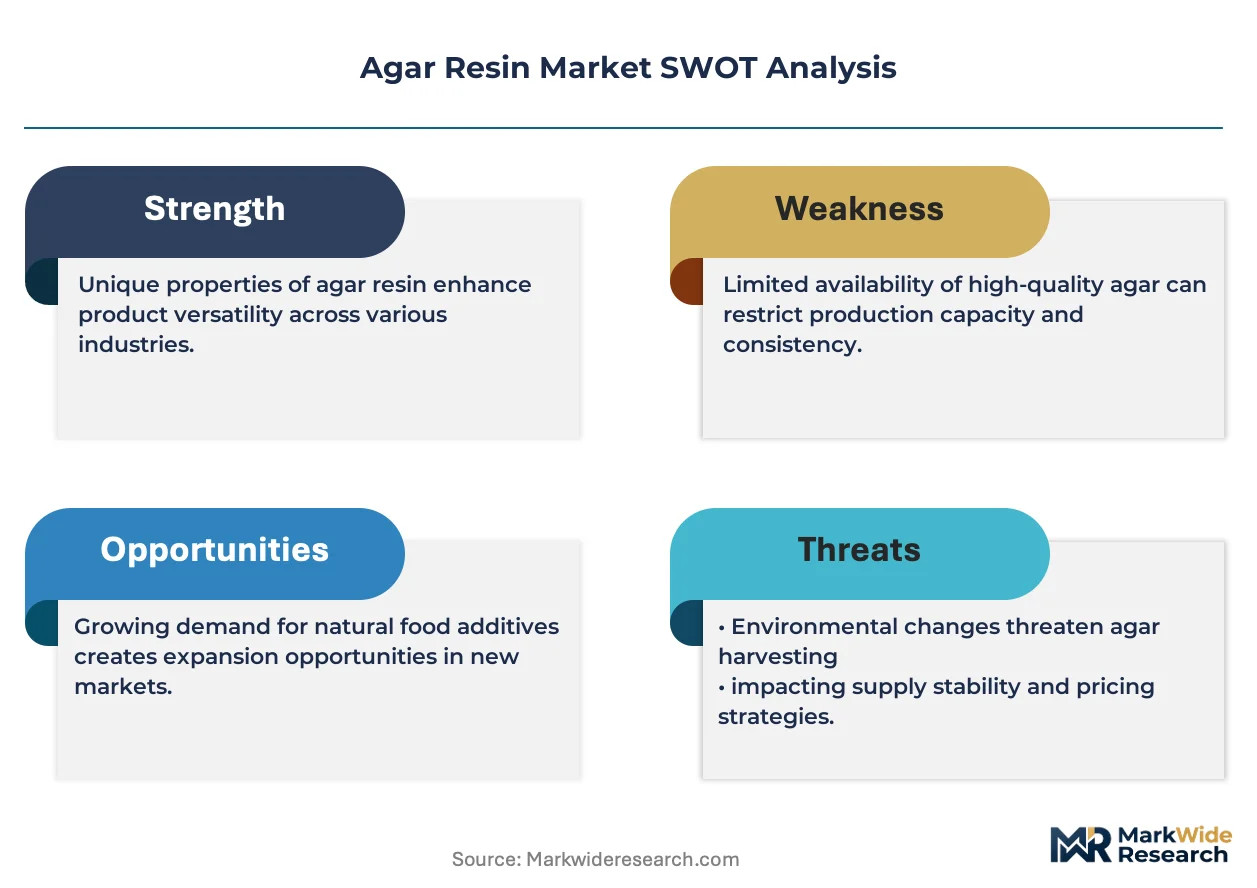
Maintenance-grade purification and certification services are consolidating around premium agar resin supply, shifting buyer relationships from spot purchasing to multi-year quality agreements. Gelymar leverages its Chilean seaweed sourcing network to sustain consistent feedstock access. Nippon Epoxy Resin Manufacturing Co., Ltd. anchors Japanese pharmaceutical-grade output through tight process control. PolyLabs Ltd. competes on laboratory-use specifications across European research channels.
Agar resin is a polysaccharide hydrocolloid extracted primarily from red algae (Rhodophyta) through hot-water processing, yielding gelling fractions with typical gel strengths ranging from 300 to 1,200 g/cm² depending on extraction protocol and seaweed species. It functions as a thermoreversible gelling agent, stabilizer, and thickener across food, pharmaceutical, and microbiological applications. Food Grade product type dominates volume flows given entrenched demand from confectionery and dairy processors, while Pharmaceutical Grade commands concentrated margin pools due to stringent endotoxin and microbial limits. Laboratory Use application segments are expanding fastest as cell-culture media formulations and molecular biology workflows multiply.
Japan's Ministry of Economy, Trade and Industry (METI) oversees industrial chemical classifications affecting agar resin import and processing standards, while the European Chemicals Agency (ECHA) enforces REACH registration thresholds that filter lower-purity suppliers from EU food-contact and medical channels. The U.S. Food and Drug Administration (FDA) maintains food additive and GRAS determinations that shape export eligibility for Asian producers targeting North American nutraceutical formulators. Stakeholders must monitor tightening endotoxin specifications in pharmaceutical applications and assess captive seaweed farming investments against climate-driven harvest variability.
Market Dynamics
Purification-grade certification requirements are compressing supplier margins and forcing long-term quality agreements between agar resin producers and pharmaceutical formulators.
Growth Catalysts
- Plant-based food additive mandates:Clean-label confectionery and dairy alternatives in Europe and North America require thermoreversible gelling agents that meet EFSA food-contact standards.
- REACH registration thresholds:ECHA compliance filters lower-purity suppliers from EU medical channels, concentrating volume among certified processors.
- Cell-culture media expansion:Biopharmaceutical manufacturing in South Korea and Japan drives laboratory-grade agar resin consumption for adherent cell workflows.
Market Restraints
- Seaweed harvest volatility:Climate-driven temperature shifts in Chilean and Indonesian coastal zones disrupt red algae (Gracilaria, Gelidium) feedstock availability.
- Endotoxin specification tightening:PMDA and FDA pharmaceutical-grade limits below 10 EU/g strain purification capacity at legacy extraction facilities.
- Carrageenan substitution:Cost-sensitive food processors in Southeast Asia pivot to kappa-carrageenan for dairy stabilization where gel strength requirements permit.
Strategic Opportunities
- Captive seaweed farming:Vertical integration into Chilean and Moroccan coastal aquaculture secures species-specific feedstock against wild harvest variability.
- 3D bioprinting scaffolds:Tissue engineering applications require low-endotoxin, high-clarity agarose derivatives for organoid and tumor model construction.
- ISO 17025 laboratory accreditation:Certified reference material programs for molecular biology create recurring revenue streams beyond commodity resin sales.
Industry Challenges
- Pharmaceutical-grade validation timelines:FDA Type II drug master file preparation and PMDA foreign manufacturer registration extend commercialization cycles by 18-24 months.
- Multi-step purification capex:Chromatographic endotoxin removal and sterile filtration infrastructure require capital deployment that mid-scale processors struggle to fund.
- Seaweed species authentication:DNA barcoding and isotope analysis capabilities are scarce among quality control laboratories, creating adulteration detection gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agar Resin Market |
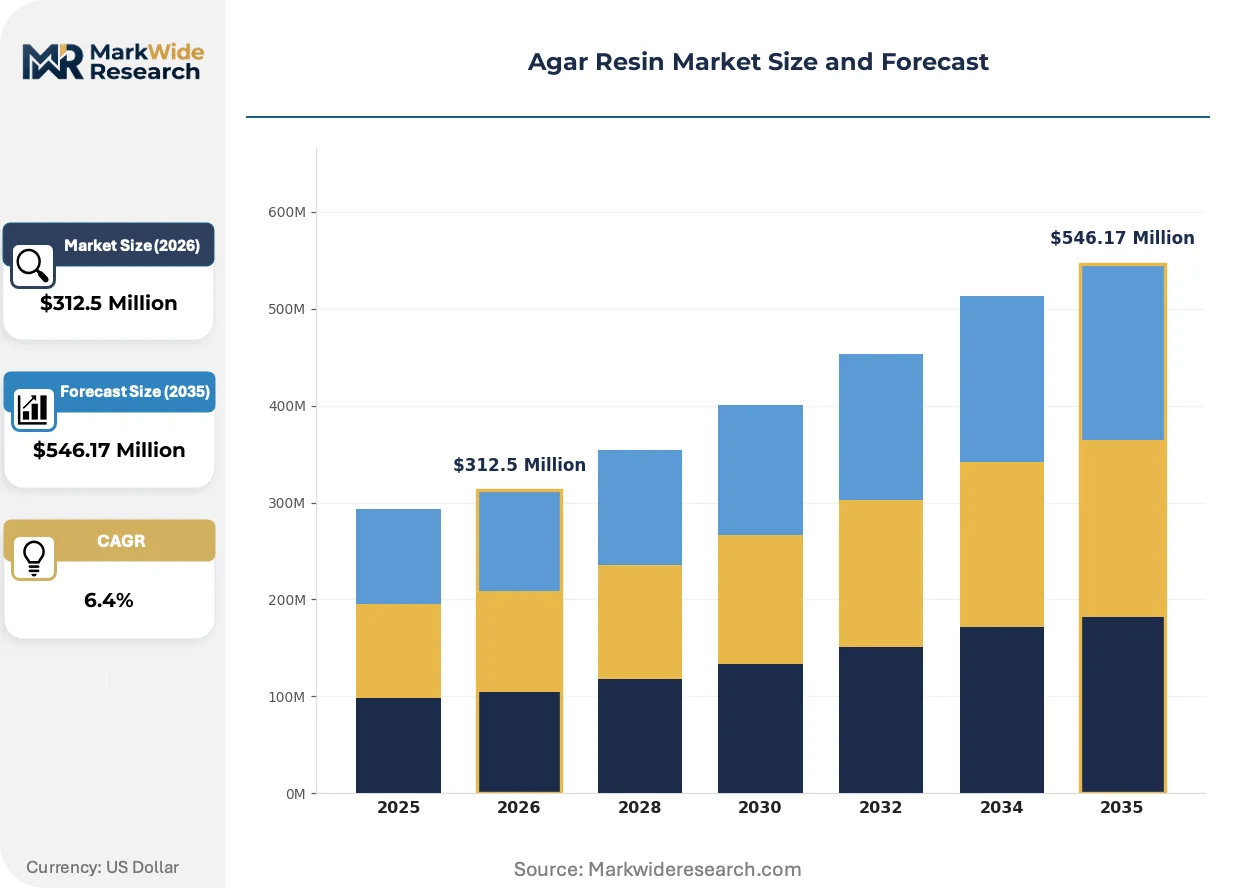
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food Additive, Laboratory Use, Medical Applications, Personal Care Packaging Type: Bags, Bottles, Bulk Containers, Pouches End User: Food Industry, Healthcare, Cosmetics Sector, Research Institutions |
| Companies Covered | Nippon Epoxy Resin Manufacturing Co., Ltd., MSR Holding B.V., Nippon Gohsei, Gelymar, PolyLabs Ltd., Reichhold Holdings International B.V., Agar Scientific Ltd., Kappa Bioscience, D&R Dispersions & Resins Sp Z O O, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agar Resin Market Emerging Trajectories
Membrane filtration and enzymatic refinement protocols are displacing traditional alkali-extraction methods, altering capital requirements and competitive positioning among agar resin processors.
Low-temperature enzymatic hydrolysis is integrating into pharmaceutical-grade production lines to preserve gel strength while achieving endotoxin levels below 5 EU/g. Japanese and South Korean biotech formulators are adopting these resins for stem-cell culture media. The technology is integrating quality-sensitive buyers into multi-year supply agreements that lock out commodity competitors.
EU F-Gas Regulation phase-down schedules are pressuring cold-chain-dependent agar resin storage and transport infrastructure. Processors must retrofit facilities with alternative refrigeration systems or absorb compliance penalties. Pharmaceutical-grade distributors in Germany and France are consolidating warehousing to shared temperature-controlled hubs.
Laboratory procurement departments are unbundling reagent purchasing from equipment service contracts, forcing agar resin suppliers to compete on certificate-of-analysis transparency rather than bundled pricing. Academic research institutes in Japan and contract research organizations in South Korea now require lot-specific gel strength and sulfate content data prior to order placement. This behavioral shift favors processors with integrated quality documentation systems.
Agar Resin Market Segmentation
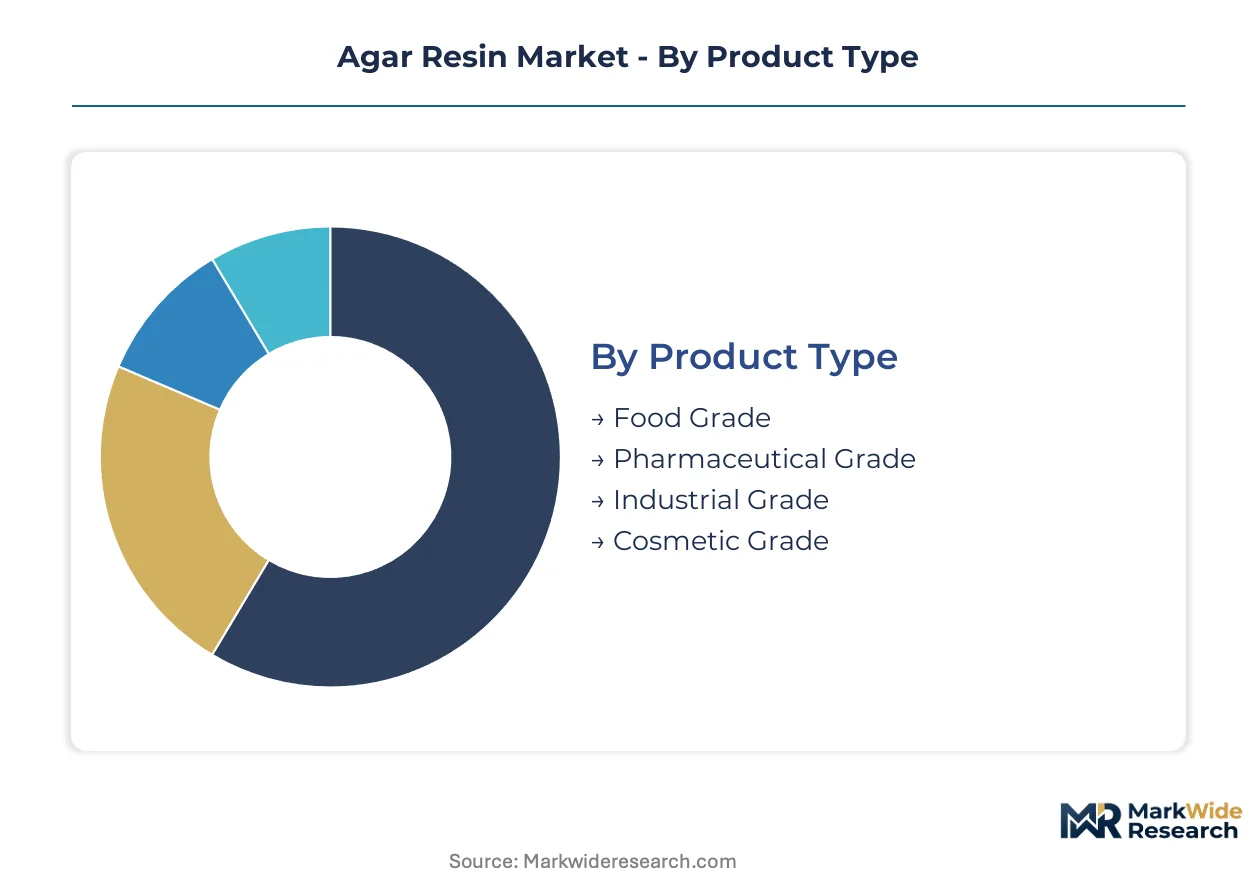
Agar resin segmentation reflects divergent purity thresholds across end-use verticals. Specification requirements for endotoxin limits, gel strength, and microbial contamination create distinct commercial tiers with limited substitution elasticity.
Product Type:
Gel strength and endotoxin specification define the technical axis separating commercial grades.
- Food Grade:Standard gelling fractions with gel strengths of 300-800 g/cm² dominate confectionery and dairy applications. EFSA food-contact compliance drives procurement from European processors reformulating plant-based desserts.
- Pharmaceutical Grade:Ultra-low endotoxin resins below 10 EU/g command concentrated margins through PMDA and FDA drug master file pathways. Japanese and South Korean biotech formulators lock supply through multi-year quality agreements.
- Industrial Grade:Lower-purity extracts serve microbiological media and non-critical applications where cost sensitivity permits sulfate content above 5%.
- Cosmetic Grade:Intermediate purity band targets skincare emulsification with controlled microbial limits for rinse-off formulations.
Food Grade leads on scale; Pharmaceutical Grade leads on momentum.
Application:
End-use thermal stability requirements and regulatory exposure shape segment boundaries.
- Food Additive:Thermoreversible gelation at 32-45°C enables clean-label confectionery and dairy alternatives. European clean-label mandates accelerate substitution of synthetic stabilizers.
- Laboratory Use:Cell-culture media and molecular biology workflows demand lot-specific certificate-of-analysis documentation. South Korean CROs and Japanese academic institutes now require sulfate content and gel strength data pre-order.
- Medical Applications:Wound dressing and drug delivery matrices require sterile filtration and biocompatibility testing under ISO 10993 protocols.
- Personal Care:Texture modification in premium skincare leverages agar's water-binding capacity without the carrageenan stigma affecting certain consumer segments.
Laboratory Use gains share fastest; Food Additive retains volume dominance.
Packaging Type:
Moisture sensitivity and contamination risk govern format selection across customer tiers.
- Bulk Containers:Industrial-scale food processors and pharmaceutical formulators in Germany and France favor 500kg+ totes for cold-chain efficiency.
- Bags:Standard 25kg multi-wall paper sacks serve mid-scale dairy and confectionery operations with moderate humidity control.
- Bottles:Laboratory-grade powders in amber glass or HDPE protect light-sensitive high-purity resins for cell-culture applications.
- Pouches:Single-use sachets address cosmetics sector sampling and small-batch research procurement with reduced contamination exposure.
Bulk Containers anchor industrial procurement; Bottles capture laboratory premium.
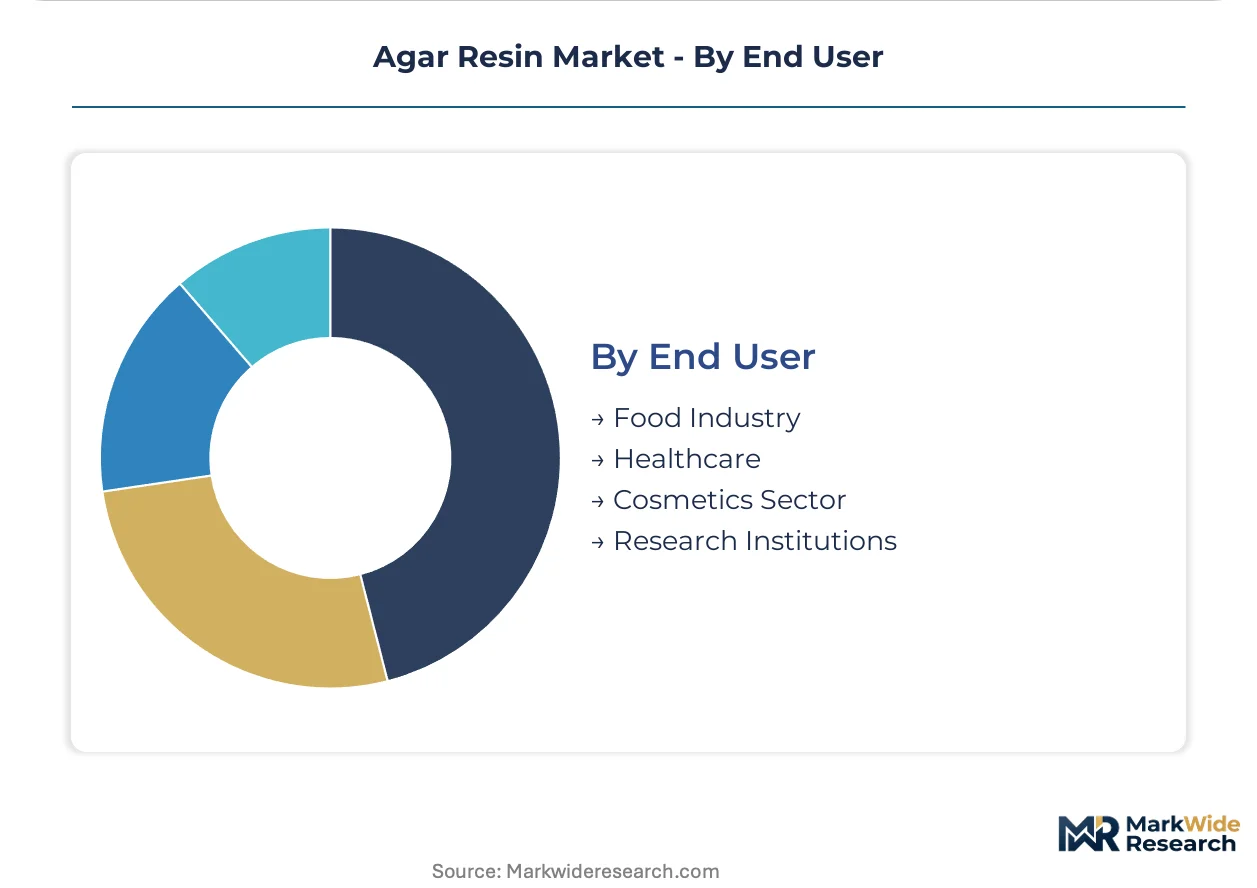
End User:
Customer sophistication and validation burden determine service intensity and contract structure.
- Food Industry:Confectionery and dairy processors in Japan's traditional food corridor prioritize consistent gel strength over purity certification.
- Healthcare:Pharmaceutical manufacturers face 18-24 month FDA Type II drug master file timelines, locking relationships with validated suppliers.
- Cosmetics Sector:Formulators balance texture performance against clean-label positioning, with European brands leading agar adoption over carrageenan.
- Research Institutions:Academic and government laboratories in South Korea's biotech cluster drive ISO 17025 accreditation requirements for reference material programs.
Food Industry sustains baseline volume; Research Institutions expand specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's traditional food processing corridor consumes more agar resin volume than Germany's pharmaceutical formulation hubs, yet South Korea's biotech laboratory cluster is accelerating specification intensity faster than either market.
Japan
Confectionery manufacturers in Tokyo and Osaka sustain baseline demand for thermoreversible gelling agents in wagashi and dairy desserts. METI oversees industrial chemical classifications that shape import standards for food-grade resins. The Kansai region anchors pharmaceutical-grade output through processors maintaining tight endotoxin controls for PMDA-compliant drug master files.
South Korea
Cell-culture media formulators in Seoul and Busan drive laboratory-grade consumption for adherent stem-cell workflows. MFDS pharmaceutical regulations enforce microbial limits that filter uncertified suppliers from biopharmaceutical channels. The Songdo biotech cluster concentrates demand for ISO 17025-accredited reference materials among contract research organizations.
Germany
Food-contact material rules under EFSA and ECHA REACH registration compress margins for lower-purity imports while concentrating volume among certified processors. The Rhine-Ruhr industrial corridor hosts cold-chain warehousing consolidation as EU F-Gas Regulation phase-downs pressure refrigeration infrastructure. Bavarian pharmaceutical distributors now require lot-specific gel strength documentation pre-order.
United States
FDA GRAS determinations and food additive petitions shape export eligibility for Asian producers targeting nutraceutical formulators in California and New Jersey. The FDA maintains endotoxin specifications below 10 EU/g for pharmaceutical-grade applications that strain legacy extraction capacity. Greater Boston's academic research institutes unbundle reagent purchasing from equipment contracts, demanding certificate-of-analysis transparency.
Chile
Red algae harvesters along the Biobío and Los Lagos coastlines supply Gracilaria feedstock to international processors amid climate-driven temperature variability. The national fisheries service monitors wild harvest quotas that constrain species-specific availability. Antofagasta and Valparaíso ports concentrate export logistics for Gelymar's captive sourcing network.
Agar Resin Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification creating tiered barriers that commodity food-grade suppliers cannot easily cross. The vendor base organizes around three strategic archetypes: Chilean-anchored seaweed integrators controlling upstream feedstock, Japanese pharmaceutical-grade validators with PMDA-aligned quality systems, and European laboratory specialists competing on ISO 17025 documentation. Dominant competitive moves include backward integration into coastal aquaculture and multi-year quality agreements that lock out uncertified processors.
Within the premium-certification tier, Nippon Epoxy Resin Manufacturing Co., Ltd. exemplifies Japanese pharmaceutical-grade validators, while Gelymar represents Chilean-anchored feedstock integrators. PolyLabs Ltd. occupies a position among European laboratory specialists emphasizing certificate-of-analysis transparency. These three company structures illustrate how geographic origin and regulatory alignment shape competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Nippon Epoxy Resin Manufacturing Co., Ltd. |
| MSR Holding B.V. |
| Nippon Gohsei |
| Gelymar |
| PolyLabs Ltd. |
| Reichhold Holdings International B.V. |
| Agar Scientific Ltd. |
| Kappa Bioscience |
| D&R Dispersions & Resins Sp Z O O |
| Others |
Supply Flow & Price Mechanics
Gracilaria and Gelidium seaweed spot indices in Chilean and Indonesian coastal zones cascade through extraction, purification, and certification stages into three distinct pricing tiers. Food-grade resins absorb harvest volatility directly while pharmaceutical-grade premiums widen as endotoxin specifications tighten under PMDA and FDA pathways.
Pricing Analysis
Capacity additions in Morocco and Chile are reshaping price floors for standard-grade agar resin. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates PMDA-validated supply from EFSA-compliant food channels and uncertified commodity lots. Cost compression in food-grade tiers is intensifying because carrageenan substitution in Southeast Asian dairy applications erodes volume leverage. Industrial processors exhibit highest price sensitivity while Japanese biotech formulators lock multi-year agreements at fixed premiums.
Supply Chain Analysis
Domestic-content mandates in South Korea and Japan are reshaping sourcing patterns for laboratory-grade resins. Feedstock concentration centers on Chile, Indonesia, and Morocco for wild red algae harvests. Downstream processing draws from Japanese pharmaceutical validators, European ISO 17025-accredited laboratories, and Chilean-anchored integrators. Single-source vulnerability runs through Chilean coastal temperature variability affecting Gracilaria yields. Distribution runs through Antofagasta and Valparaíso ports for Atlantic and Pacific basin delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in agar resin hinges on purification-grade certification premiums widening against commodity-grade compression. Low-temperature enzymatic hydrolysis adoption creates tier separation that rewards validated processors.
For Market Incumbents: Hedge harvest volatility through captive seaweed farming investments along Chile's Biobío coastline and Moroccan aquaculture zones. Lock pharmaceutical-grade relationships via multi-year quality agreements that preempt FDA Type II drug master file competitors. Carrageenan substitution in cost-sensitive food channels threatens volume leverage; reinforce position through EFSA food-contact certification bundling. For New Entrants and Emerging Players: Capture laboratory-use share among South Korean CROs and Japanese academic institutes demanding ISO 17025-accredited reference materials. 3D bioprinting scaffold applications present penetrable white space requiring only low-endotoxin, high-clarity agarose derivatives rather than full pharmaceutical validation. Lead with certificate-of-analysis transparency and lot-specific gel strength documentation as primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with Chilean-anchored feedstock integrators controlling captive seaweed sourcing networks. Five-to-ten year viability favors processors with backward integration into coastal aquaculture rather than wild-harvest-dependent competitors. Monitor PMDA foreign manufacturer registration timelines as inflection signal for pharmaceutical-grade supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Seaweed Farming | Chilean and Moroccan coastal aquaculture secures species-specific feedstock against climate-driven harvest variability. |
| Low-Temperature Enzymatic Hydrolysis | Japanese and South Korean biotech formulators adopt sub-5 EU/g endotoxin resins for stem-cell culture media. |
| ISO 17025 Laboratory Accreditation | South Korean CROs and Japanese academic institutes drive certified reference material programs beyond commodity sales. |
| FDA Type II Drug Master File Preparation | Pharmaceutical-grade validation timelines extend commercialization cycles and lock out uncertified processors. |
| EU F-Gas Regulation Compliance | German and French distributors consolidate cold-chain warehousing as refrigeration infrastructure faces retrofit pressure. |
Methodological Framework
Direct dialogue with extraction plant managers, pharmaceutical procurement leads at Japanese biotech formulators, EFSA regulatory affairs specialists, and Chilean fisheries coordinators grounded qualitative insights. Secondary validation drew from customs and trade data, ECHA REACH registration databases, PMDA foreign manufacturer filings, and SEC 10-K disclosures from listed processors. Bottom-up volume estimates by grade tier and application crossed with top-down market sizing from trade flow analysis.
Segment-level outputs across product type, application, packaging format, and regional production hub informed the analytical framework over the projection horizon. CAGRs derived from historical price-volume relationships and elasticity assumptions around substitution effects. Industry-specific inputs included seaweed harvest yield variability by coastal zone and pharmaceutical-grade certification penetration rates.
Climate-driven temperature shifts, regulatory tightening on endotoxin specifications, and carrageenan substitution acceleration are the dominant revision risks that could compress food-grade margins or extend pharmaceutical validation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polar Polymers Market