
 Middle East and Africa Adenomyosis Drugs Market | 2026-2036
Middle East and Africa Adenomyosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Adenomyosis Drugs Market Foresight
The R&D spending gap between multinational and regional players is reorganizing competitive hierarchy in the Middle East and Africa adenomyosis drugs space. Bayer AG leverages its captive hormone synthesis infrastructure to dominate gonadotropin-releasing hormone agonist supply. Novartis anchors its position through specialized distribution partnerships with tertiary hospital networks across the Gulf states. Pfizer competes by extending its injectable formulation portfolio into markets with limited cold-chain alternatives.
Adenomyosis drugs comprise pharmaceutical agents targeting ectopic endometrial tissue within the myometrium, with hormonal therapies typically formulated as leuprolide acetate depot injections at 3.75 mg or 11.25 mg doses to induce pseudomenopause and shrink uterine volume. These agents serve the primary commercial purpose of delaying or avoiding hysterectomy in women of reproductive age. Hormonal therapy leads current revenue pools due to established reimbursement pathways, while non-hormonal therapy represents the fastest-expanding segment as patients seek alternatives to androgenic side effects. Hospital pharmacies concentrate the highest margin capture because of their control over specialist-prescribed injectable and implantable formulations.
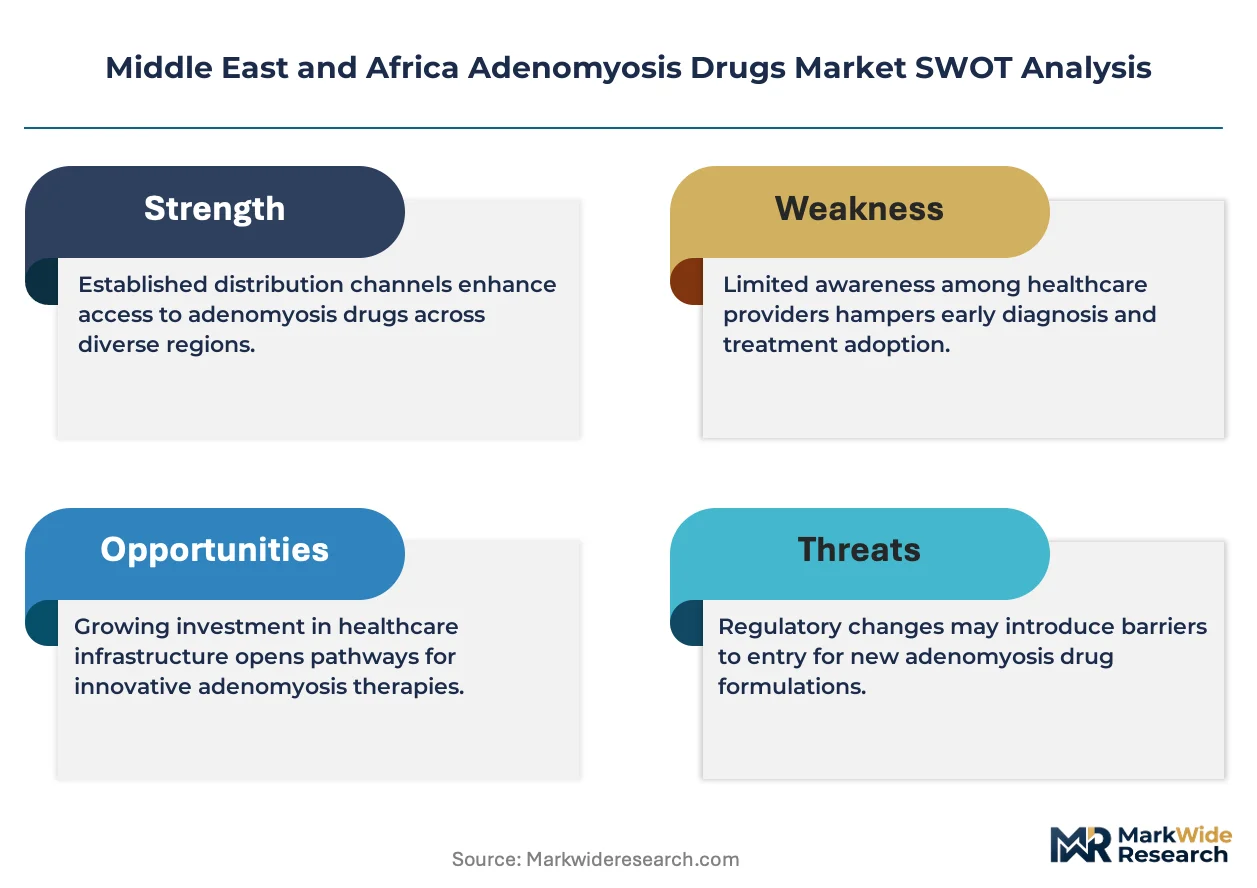
South Africa's SAHPRA, Saudi Arabia's SFDA, and Nigeria's NAFDAC collectively shape market access through divergent bioequivalence requirements and import licensing timelines for hormonal products. The EU MDR's extraterritorial influence on CE-marked devices also filters into Gulf Cooperation Council procurement standards, elevating documentation burdens for implantable drug-delivery systems. Stakeholders must monitor regulatory harmonization initiatives between the African Medicines Regulatory Harmonization initiative and Gulf central drug authorities to anticipate streamlined approval pathways.
Market Dynamics
SFDA's tightened import documentation for hormonal implants is restructuring supply chain configurations across Gulf Cooperation Council states, forcing distributors to consolidate documentation capabilities or exit the market entirely.
Growth Catalysts
- Gonadotropin-releasing hormone agonist protocol expansion:South African gynecology clinics are systematically broadening hormonal therapy protocols, creating pull-through demand for depot injection formulations.
- Urban hospital network concentration:Nigeria's metropolitan hospital chains are consolidating procurement volumes, generating economies of scale that reduce per-dose acquisition costs for advanced formulations.
- AMRH harmonization momentum:The African Medicines Regulatory Harmonization initiative is streamlining bioequivalence pathways, compressing multi-country registration timelines for hormonal products.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient synthesis for leuprolide acetate concentrates among three Asian manufacturing clusters, exposing Middle East and Africa distributors to geopolitical supply interruptions.
- Cold-chain infrastructure deficits:Temperature-controlled distribution networks remain underdeveloped across Sub-Saharan corridors, restricting injectable formulation penetration outside major metropolitan zones.
- Reimbursement pathway fragmentation:Divergent national health insurance formularies across Gulf states and North Africa create pricing arbitrage that complicates parallel trade management.
Strategic Opportunities
- Non-hormonal therapeutic white space:Patient preference for alternatives to androgenic side effects is opening positioning for selective progesterone receptor modulators in South African private practice channels.
- Implantable drug-delivery innovation:Subdermal hormonal implants with extended release profiles offer differentiation in Saudi Arabian tertiary hospital networks seeking reduced administration burden.
- Telemedicine-integrated prescription flows:Digital health platforms in UAE urban centers are creating direct-to-patient channels that bypass traditional hospital pharmacy gatekeepers.
Industry Challenges
- Specialist gynecologist density gaps:Diagnostic capacity for adenomyosis remains concentrated in capital cities, limiting patient identification and treatment initiation across secondary urban centers.
- Multi-jurisdiction compliance complexity:CE-marked implantable systems must satisfy both EU MDR documentation standards and SFDA localization requirements, extending product registration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Adenomyosis Drugs Market |
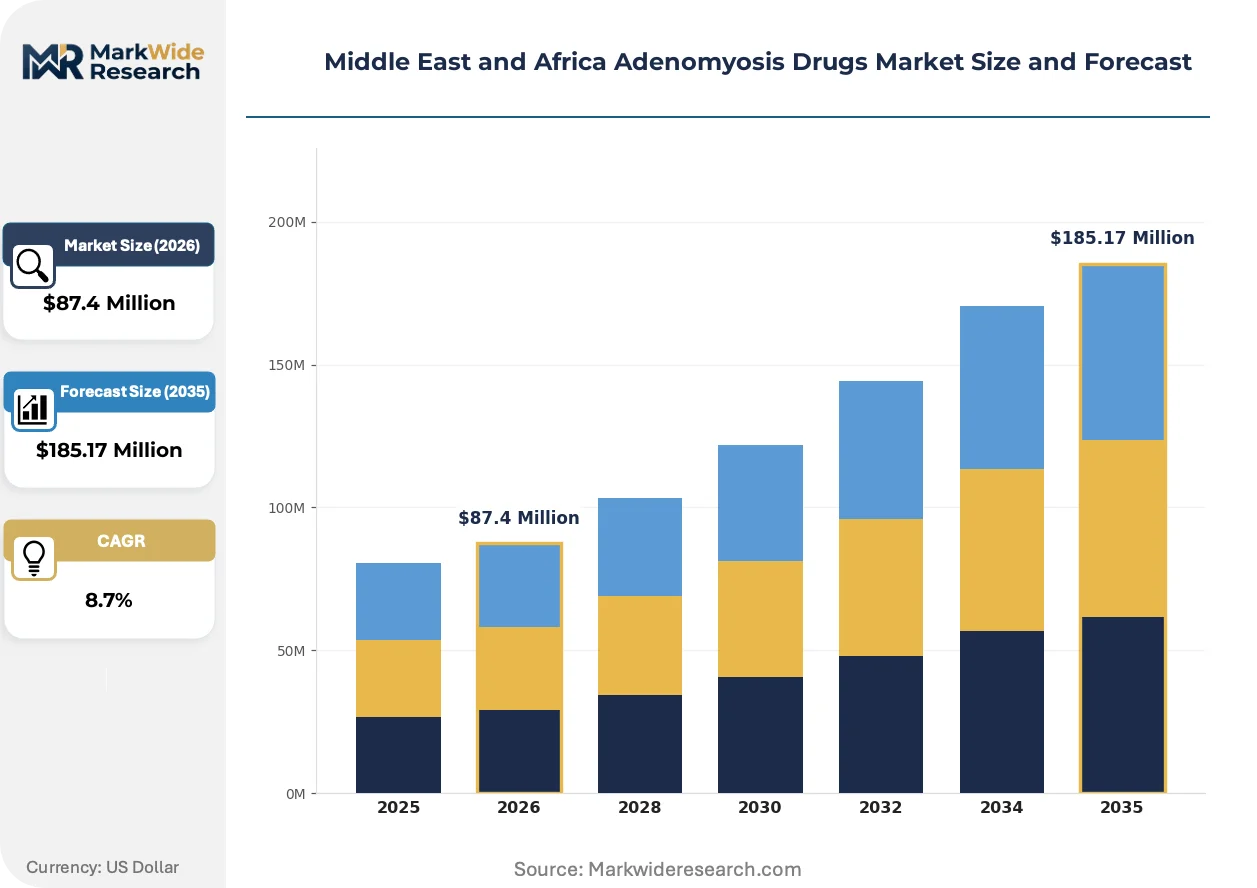
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Non-Hormonal Therapy, Surgical Treatment, Pain Management End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Settings Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Specialty Clinics Formulation: Tablets, Injections, Implants, Transdermal Patches |
| Companies Covered | Bayer AG, Novartis AG, Johnson & Johnson, Pfizer Inc., Merck KGaA, Ferring B.V., AbbVie Inc., Teva Pharmaceutical Industries, Sanofi, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Adenomyosis Drugs Market Shifts & Advancements
Formulation technology and distribution architecture are undergoing parallel transformation, with hormonal delivery systems and procurement channels each experiencing structural pressure toward consolidation and specialization.
Long-acting reversible contraceptive platforms are absorbing adenomyosis therapeutic functions, creating hybrid devices that deliver both contraceptive and disease-modifying effects. Private gynecology practices in Johannesburg and Cape Town are adopting these dual-purpose systems at accelerating rates. The technology is bifurcating the market between single-indication hormonal therapies and multifunctional implantable platforms.
EU MDR's extraterritorial documentation requirements are filtering into Gulf Cooperation Council procurement standards, elevating technical file burdens for implantable drug-delivery systems. Saudi Arabia's SFDA has adopted CE-marking equivalency protocols that demand additional clinical evidence for hormonal implants. Manufacturers targeting tertiary hospital networks across Dubai, Riyadh, and Jeddah are restructuring regulatory affairs teams to manage parallel compliance tracks.
Patient-initiated switching between hormonal and non-hormonal modalities is compressing physician consultation cycles and demanding more flexible prescription protocols. South African medical aid schemes are responding with broader formulary flexibility that accommodates rapid therapeutic transitions. This behavioral shift is most pronounced among reproductive-age patients in urban Nigerian hospital networks seeking fertility-preserving alternatives to hysterectomy.
Middle East and Africa Adenomyosis Drugs Market Segmentation
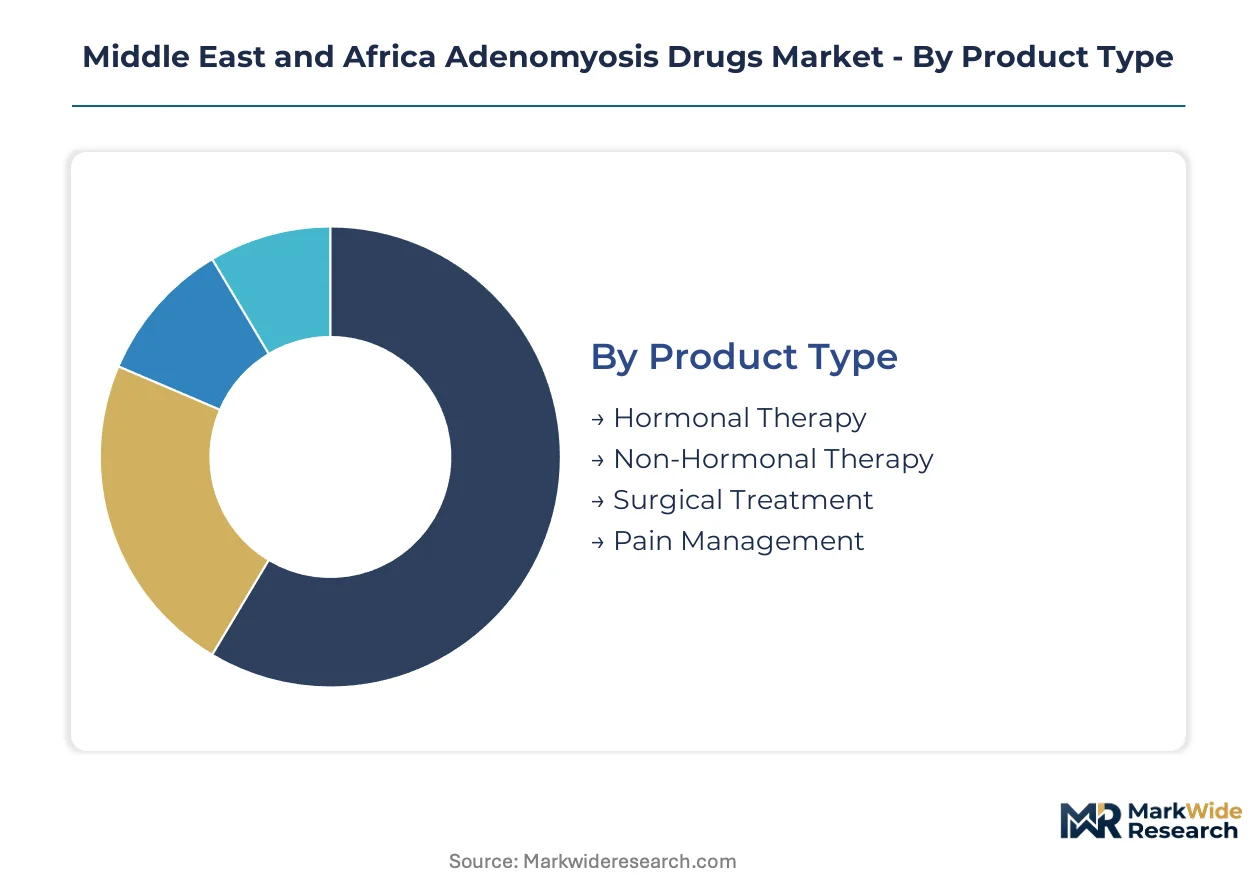
Segmentation in the Middle East and Africa adenomyosis drugs market reveals distinct procurement patterns across Gulf Cooperation Council states and Sub-Saharan corridors. Each category exposes structural divides between import-dependent supply chains and locally concentrated demand nodes.
Product Type:
Domestic formulation capacity concentrates in South Africa and Egypt, while Gulf states remain import-reliant for advanced hormonal delivery systems.
- Hormonal Therapy:Leuprolide acetate depot injections and GnRH agonists dominate therapeutic protocols across Saudi Arabian tertiary networks. SAHPRA-registered products in South Africa pull demand through Johannesburg gynecology clusters seeking pseudomenopause induction.
- Non-Hormonal Therapy:Selective progesterone receptor modulators and NSAID combinations address androgenic side-effect intolerance. Nigerian urban hospital networks in Lagos and Abuja are expanding these alternatives fastest among reproductive-age patients.
- Surgical Treatment:Hysterectomy and conservative excision procedures concentrate in Cairo and Casablanca medical centers.
- Pain Management:Adjunctive analgesic protocols support hormonal regimens in Dubai and Riyadh private practice channels.
Hormonal therapy commands the established base. The steepest expansion runs through non-hormonal alternatives.
End User:
Procurement volume tiers separate high-complexity surgical centers from routine prescription channels across the region's healthcare hierarchy.
- Hospitals:Tertiary institutions in Jeddah, Riyadh, and Johannesburg control specialist-prescribed injectable and implantable formulations. SFDA import licensing requirements favor consolidated procurement through these high-volume nodes.
- Clinics:Private gynecology practices in Cape Town and Nairobi drive ambulatory hormonal protocol adoption. These facilities prioritize depot injection convenience over surgical alternatives.
- Ambulatory Surgical Centers:Same-day procedural capacity concentrates in UAE urban corridors.
- Homecare Settings:Self-administered transdermal and oral regimens expand in South African medical aid networks.
Hospitals anchor volume concentration. Clinics are climbing the fastest as urban specialist density expands.
Distribution Channel:
Cold-chain capabilities and regulatory documentation burdens reshape channel viability across temperature-stressed distribution corridors.
- Hospital Pharmacies:Injectable and implantable hormonal products flow through controlled specialist channels in Saudi Arabian and South African tertiary networks. These pharmacies capture margin through exclusive formulary access.
- Retail Pharmacies:Oral hormonal and pain management products reach patients through Johannesburg and Lagos pharmacy chains. NAFDAC registration timelines determine product availability in Nigerian retail.
- Online Pharmacies:Telemedicine-integrated prescription flows accelerate in UAE urban centers.
- Specialty Clinics:Direct dispensing models operate in Dubai reproductive health centers.
Hospital pharmacies maintain the highest margin capture. Online channels are gaining share fastest where digital health infrastructure permits.
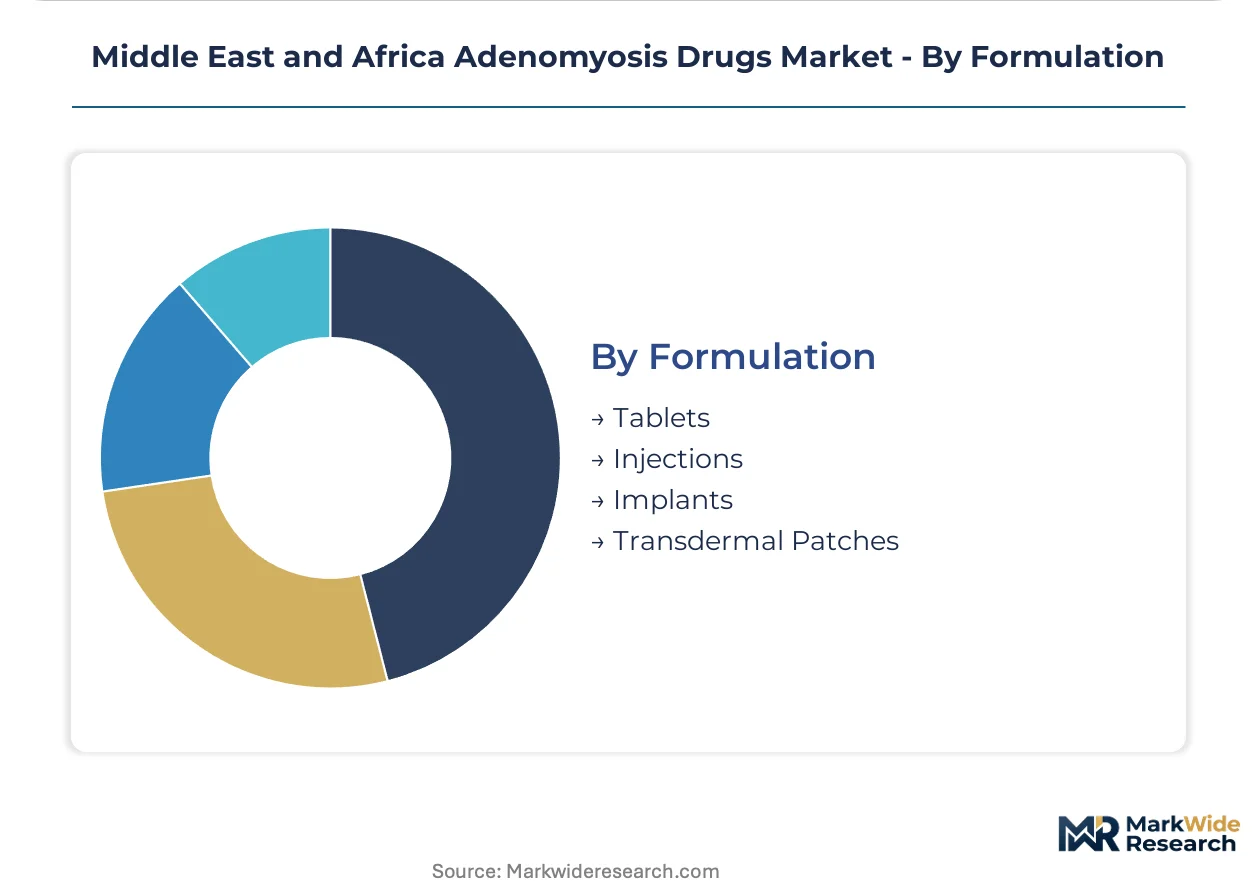
Formulation:
Stability requirements and administration burden segment demand across metropolitan and secondary urban access tiers.
- Injections:Leuprolide acetate depot formulations at 3.75 mg and 11.25 mg doses serve core pseudomenopause protocols. Cold-chain infrastructure in Sub-Saharan corridors restricts penetration outside Lagos, Nairobi, and Johannesburg metropolitan zones.
- Implants:Subdermal hormonal delivery systems with extended release profiles differentiate Saudi Arabian tertiary networks. EU MDR documentation requirements elevate technical file burdens for these CE-marked devices.
- Tablets:Oral hormonal and non-hormonal regimens suit homecare and retail pharmacy distribution.
- Transdermal Patches:Alternative delivery routes address injection tolerance issues in South African private practice.
Injections command the established therapeutic base. Implants show the steepest expansion trajectory in Gulf Cooperation Council procurement networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi Arabian tertiary hospital networks while procurement volume clusters in South African urban corridors, creating a structural asymmetry that shapes distributor strategies across the Middle East and Africa adenomyosis drugs market.
Saudi Arabia
SFDA's tightened import documentation for hormonal implants is forcing distributors to consolidate regulatory affairs capabilities or exit Gulf Cooperation Council markets entirely. Riyadh and Jeddah tertiary networks anchor demand for leuprolide acetate depot formulations, with procurement concentrated through specialist-prescribed channels that capture premium margins on injectable products.
South Africa
SAHPRA-registered hormonal therapies pull demand through Johannesburg and Cape Town gynecology clusters seeking pseudomenopause induction protocols. The African Medicines Regulatory Harmonization initiative is compressing multi-country registration timelines for regional distributors headquartered in Gauteng province.
Nigeria
NAFDAC registration timelines determine product availability in Lagos and Abuja urban hospital networks, where metropolitan procurement consolidation generates economies of scale for advanced formulations. Reproductive-age patients in these corridors drive fastest expansion of non-hormonal alternatives to address androgenic side-effect intolerance.
United Arab Emirates
Telemedicine-integrated prescription flows in Dubai are creating direct-to-patient channels that bypass traditional hospital pharmacy gatekeepers. MOHAP standards align with EU MDR documentation requirements, elevating technical file burdens for implantable drug-delivery systems targeting tertiary networks.
Egypt
Cairo medical centers concentrate hysterectomy and conservative excision procedures, with domestic formulation capacity serving North African demand for oral hormonal regimens. The country's central drug authority shapes market access timelines for products entering through Alexandria port corridors.
Middle East and Africa Adenomyosis Drugs Market Competitive Landscape
Concentration sits with multinational pharmaceutical conglomerates that leverage captive hormone synthesis infrastructure and specialized distribution partnerships across Gulf tertiary networks. The vendor base organizes around three strategic archetypes: integrated hormone manufacturers with backward control over active pharmaceutical ingredient supply, formulation specialists extending injectable portfolios into cold-chain-constrained corridors, and regional distributors consolidating documentation capabilities to meet SFDA localization requirements. Dominant competitive moves include vertical integration into leuprolide acetate synthesis and strategic partnerships with hospital pharmacy networks seeking exclusive formulary access.
Within the integrated pharmaceutical tier, Bayer AG and Novartis AG exemplify archetypes that anchor supply-side positioning through distinct infrastructure advantages. Bayer AG represents the hormone synthesis-integrated model with captive production capabilities, while Novartis AG occupies a position emphasizing specialized distribution partnerships across hospital networks. Pfizer Inc. sits within the formulation-extension archetype, with its corporate structure supporting injectable portfolio expansion into markets with limited cold-chain alternatives.
| Leading Market Players |
|---|
| Bayer AG |
| Novartis AG |
| Johnson & Johnson |
| Pfizer Inc. |
| Merck KGaA |
| Ferring B.V. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries |
| Sanofi |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day import licensing timelines for hormonal implants into Saudi Arabia concentrate pricing power among distributors with consolidated regulatory affairs capabilities, while compressing margins for smaller players lacking SFDA documentation bandwidth. This lead-time asymmetry between compliant and non-compliant supply channels directly shapes the premium capture available to tier-one hospital pharmacy networks across Gulf Cooperation Council states.
Pricing Analysis
The customization-premium spread between standard leuprolide acetate depot formulations and patient-specific dosing protocols reaches widest separation in South African private gynecology channels. Pricing stratifies across premium, standard, and economy tiers driven by cold-chain certification grade and volume procurement scale. Cost compression in the standard injectable tier is intensifying because Nigerian urban hospital networks are consolidating procurement volumes. Public hospital formulary managers exhibit highest price sensitivity; tertiary network specialists demonstrate lowest sensitivity due to exclusive supplier relationships.
Supply Chain Analysis
Port congestion at Jebel Ali and container availability constraints on Asia-Gulf trade lanes are elevating inbound logistics costs for temperature-sensitive hormonal products entering Dubai distribution hubs. Active pharmaceutical ingredient synthesis for leuprolide acetate draws from manufacturing clusters in India, China, and South Korea. Single-source vulnerability concentrates in GnRH agonist peptide production. Distribution runs through hospital pharmacy-controlled channels in Saudi Arabian and South African tertiary networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa adenomyosis drugs market sits at a platform-economics inflection where telemedicine-integrated prescription flows in UAE urban centers are collapsing traditional hospital pharmacy gatekeeper structures and enabling direct-to-patient channel interoperability.
For Market Incumbents: Compound formulary lock-in advantages by deepening captive hormone synthesis capacity and securing exclusive procurement contracts with Johannesburg and Riyadh tertiary networks. The threat of non-hormonal therapeutic displacement by selective progesterone receptor modulators demands accelerated R&D investment in dual-purpose implantable platforms. Backward integration into leuprolide acetate API production represents the critical defensive lever. For New Entrants and Emerging Players: Differentiate on cold-chain logistics capabilities as the primary axis for penetrating Sub-Saharan corridors outside Lagos and Nairobi metropolitan zones. The most penetrable white space sits in Nigerian urban hospital networks seeking fertility-preserving non-hormonal alternatives. Target ambulatory surgical centers in UAE urban corridors with implantable drug-delivery innovation. A telemedicine-integrated go-to-market angle bypasses established hospital pharmacy gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across implantable hormonal delivery systems due to EU MDR documentation burdens and SFDA localization requirements. Long-term viability over the coming decade rests on regulatory affairs scalability rather than manufacturing scale alone. Acquisition targets should display consolidated documentation capabilities spanning Gulf and African regulatory clusters. The signal to watch is AMRH harmonization momentum compressing multi-country registration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Consolidation | SFDA import documentation requirements favor distributors with unified Gulf-Africa compliance teams. |
| Hospital System Partnership | Exclusive formulary access with Riyadh and Johannesburg tertiary networks captures premium injectable margins. |
| Cold-Chain Infrastructure Investment | Temperature-controlled distribution networks unlock penetration into Lagos and Abuja secondary urban corridors. |
| Non-Hormonal Pipeline Diversification | Selective progesterone receptor modulators address androgenic side-effect intolerance in Nigerian reproductive-age patients. |
| Telemedicine Platform Integration | Direct-to-patient channels in Dubai and Abu Dhabi bypass traditional hospital pharmacy procurement gatekeepers. |
Research Methodology
Desk research of SFDA regulatory filings, SAHPRA registration databases, and AMRH harmonization protocols preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors across Gulf and African markets. Secondary validation drew from clinical trial registries, import licensing records, and hospital procurement databases. Bottom-up demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Variance decomposition across product type, end user, distribution channel, and regional regulatory cluster segments informed the analytical framework. CAGRs were derived from segment-level growth trajectory aggregation. Forecast inputs included specialist gynecologist density projections, cold-chain infrastructure development timelines, and reimbursement pathway evolution across national health insurance formularies.
The analysis sits within stated boundaries; outcomes outside sustained AMRH harmonization momentum, stable API supply from Asian manufacturing clusters, and continued tertiary hospital network procurement consolidation would require recalibration. Forecasts reflect documented assumptions regarding regulatory approval timelines, import licensing efficiency, and patient preference shifts between hormonal and non-hormodal modalities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Gabapentin Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market