
 Europe Generic Drug Market | 2026-2036
Europe Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Generic Drug Market Intelligence
A capital-intensity divergence between large-scale API producers and formulation-only competitors is reorganizing the Europe Generic Drug Market. Teva Pharmaceutical Industries Ltd leverages backward integration into active pharmaceutical ingredient manufacturing to protect margin pools across Central and Eastern Europe. Sandoz anchors its position through biosimilar and complex generic portfolios in Western European hospital channels. Dr. Reddy's Laboratories Ltd competes on cost-optimized oncology injectables, while Viatris specializes in respiratory and cardiovascular solid-dose generics across multiple EU member states.
Generic drugs are chemically equivalent copies of originator pharmaceuticals, containing identical active ingredients, dosage forms, and bioequivalence profiles, manufactured after patent expiry to deliver equivalent therapeutic outcomes at lower cost. Production requires dissolution testing, bioequivalence studies, and compliance with European Pharmacopoeia monographs to secure marketing authorization. Tablet and capsule formulations occupy the largest volume share due to patient convenience and stability advantages in retail pharmacy distribution. Injectable generics represent the fastest-expanding margin pool, driven by hospital preference for lower-cost oncology and anesthesia alternatives. E-commerce platforms are displacing traditional wholesale channels in direct-to-consumer fulfillment, particularly for chronic maintenance therapies.
EMA centralized procedures and national competent authorities in Germany, France, and Italy govern marketing authorization, while the Falsified Medicines Directive mandates end-to-end serialization across all pack sizes. REACH and ECHA frameworks additionally constrain excipient sourcing and packaging material compliance for EU-manufactured products. Stakeholders must monitor biosimilar interchangeability rulings and tender aggregation trends that will determine which manufacturing configurations sustain profitability under tightening reimbursement caps.
Market Dynamics
Hospital procurement consolidation across Germany, France, and Italy is compressing tender margins while the Falsified Medicines Directive forces serialization investments that favor scale players over mid-tier competitors.
Growth Catalysts
- EMA Centralized Procedures:Streamlined marketing authorization across EU member states accelerates product launches for complex generics and biosimilars in oncology and immunology segments.
- Patent Cliff Waves:Expiry of biologic patents between 2025 and 2030 opens formulation opportunities for insulin, monoclonal antibodies, and peptide therapies in hospital infusion centers.
- Active Pharmaceutical Ingredient Reshoring:REACH compliance costs and supply security concerns drive captive production investments in Czech Republic, Hungary, and Poland manufacturing zones.
Market Restraints
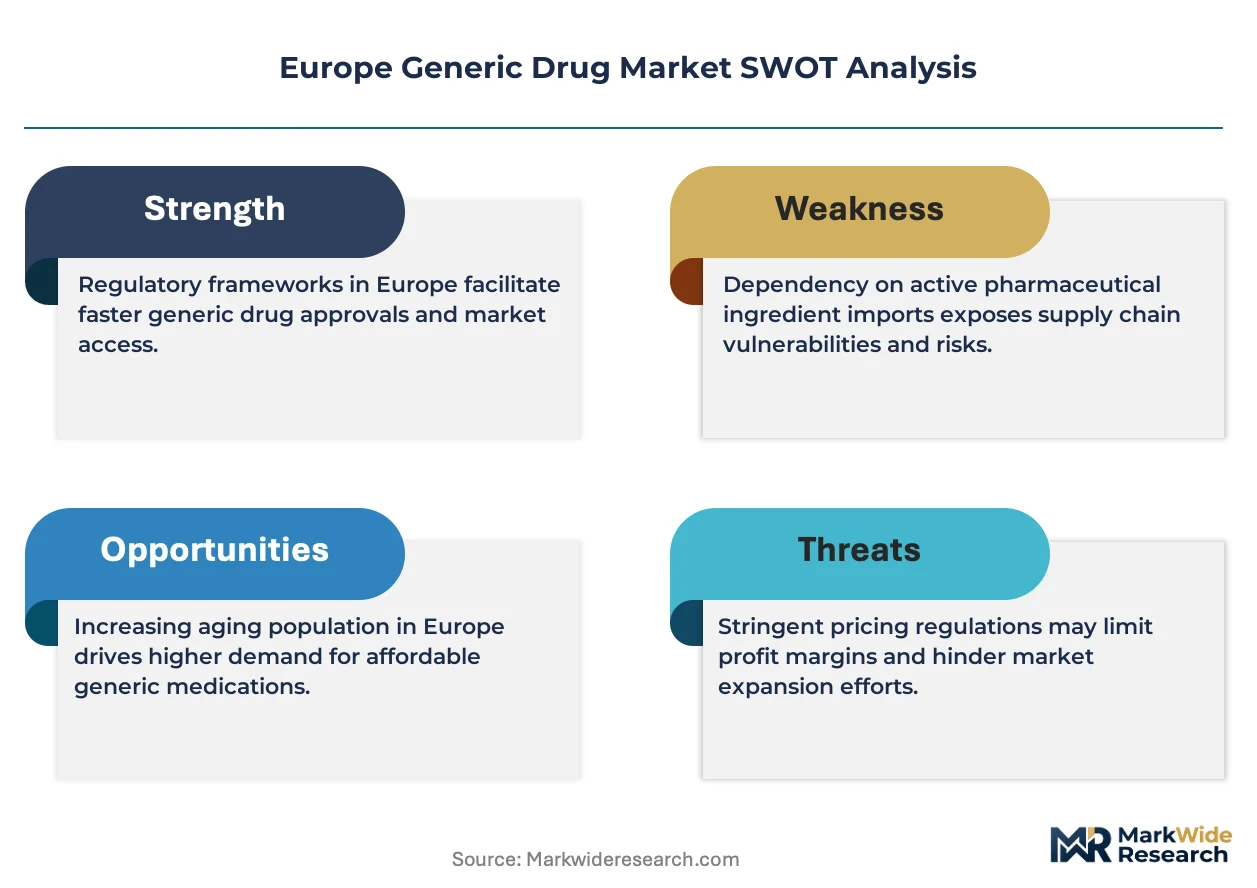
- API Import Concentration:Reliance on Chinese and Indian intermediate suppliers exposes European formulators to customs delays, currency volatility, and geopolitical trade friction.
- Bioequivalence Study Costs:Complex generic filings for inhalers, transdermal patches, and long-acting injectables require clinical endpoint studies costing multiple times standard ANDA-equivalent submissions.
- Reference Pricing Cascades:Cross-border reimbursement benchmarking between EU member states creates price erosion spirals that compress returns on established portfolio products.
Strategic Opportunities
- Central and Eastern Europe Tender Aggregation:Poland, Romania, and Bulgaria consolidate hospital purchasing into multi-year framework agreements favoring suppliers with localized manufacturing and cold-chain distribution.
- Complex Generic Formulation Gaps:Abuse-deterrent opioids, colloidal iron complexes, and liposomal delivery systems face limited competition due to formulation science barriers and specialized manufacturing requirements.
- Direct-to-Patient Pharmacy Platforms:Chronic disease maintenance therapies for hypertension, diabetes, and hyperlipidemia migrate from wholesale distribution to verified e-pharmacy fulfillment with prescription authentication.
Industry Challenges
- Serialization System Integration:EU Falsified Medicines Directive mandates require line-level hardware upgrades, warehouse management system overhauls, and contract manufacturer coordination across multi-site networks.
- Analytical Method Transfer Bottlenecks:Bioequivalence laboratories in Germany, the Netherlands, and Spain face capacity constraints extending study timelines for first-to-file generic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Generic Drug Market |
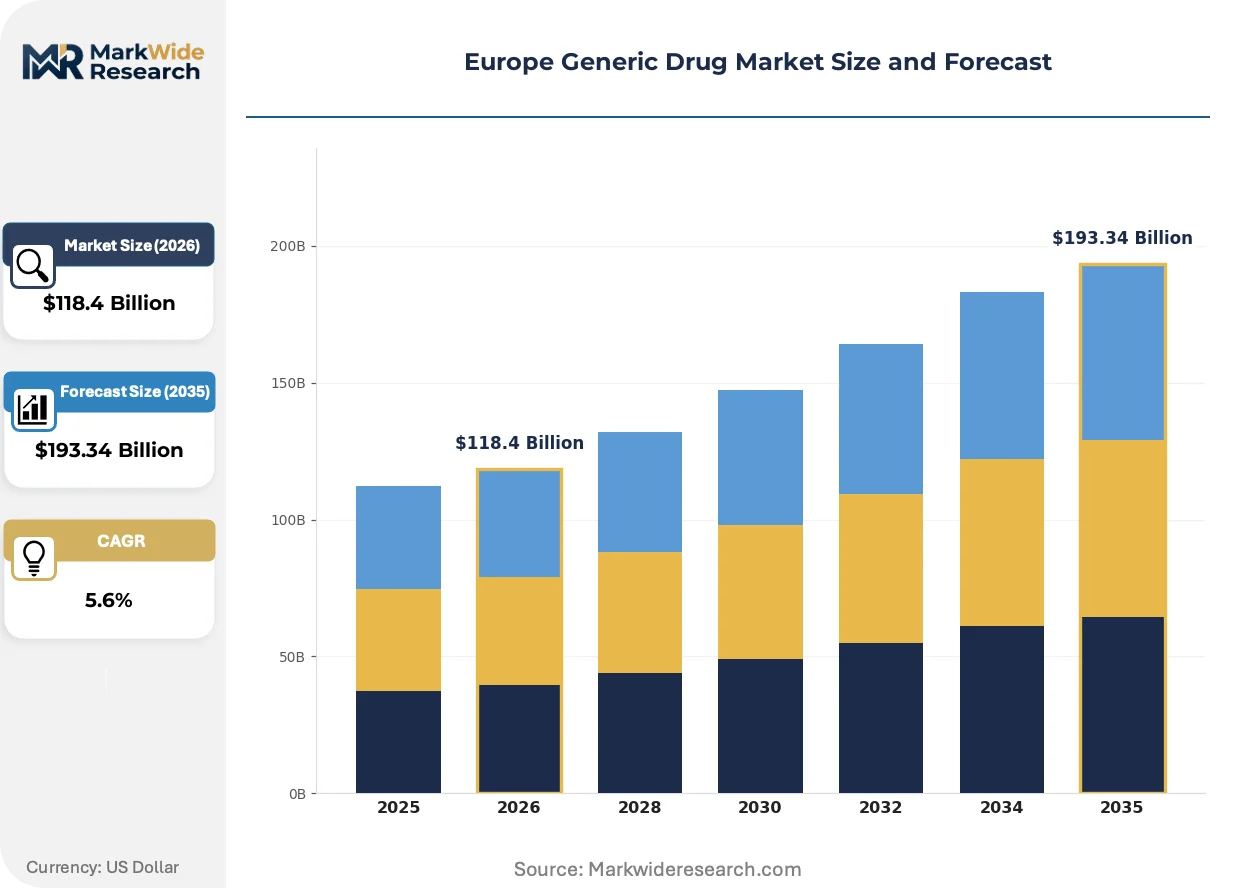
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $193.34 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectables, Ointments End User: Retail Pharmacies, Hospitals, Clinics, E-commerce Platforms Distribution Channel: Online, Offline, Wholesale, Direct Sales Formulation Type: Solid, Liquid, Semi-solid, Transdermal |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Lupin, Teva Pharmaceutical Industries Ltd, Wockhardt, Apotex, Viatris, Dr. Reddy’s Laboratories Ltd, Endo International plc, Sandoz, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Generic Drug Market Strategic Shifts & Innovations
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while regulatory science advances accelerate complex generic pathways previously blocked by bioequivalence uncertainty.
Continuous direct compression and hot-melt extrusion equipment is fragmenting traditional batch pharmaceutical manufacturing. Teva Pharmaceutical Industries and Sandoz deploy these platforms for high-volume solid-dose cardiovascular and respiratory products. The technology compresses production timelines from weeks to days, enabling just-in-time inventory models that reduce working capital requirements and obsolescence risk for short-dated generics.
EU Medical Device Regulation interoperability requirements now extend to drug-device combination products including auto-injectors and metered-dose inhalers. Manufacturers must maintain technical documentation and post-market surveillance systems that mirror pharmaceutical quality management standards. German notified bodies and EMA scientific advice procedures are experiencing backlogs that delay combination generic launches by 12 to 18 months versus pure drug submissions.
Hospital pharmacy consortia in France and Italy are consolidating oncology and anesthesia generic purchasing into multi-hospital framework agreements with compliance scorecards. These contracts bundle volume commitments with quality metrics, cold-chain reliability guarantees, and shortage mitigation obligations. Direct manufacturer relationships are displacing traditional wholesale intermediaries for injectable generics with narrow temperature stability windows.
Europe Generic Drug Market Segmentation
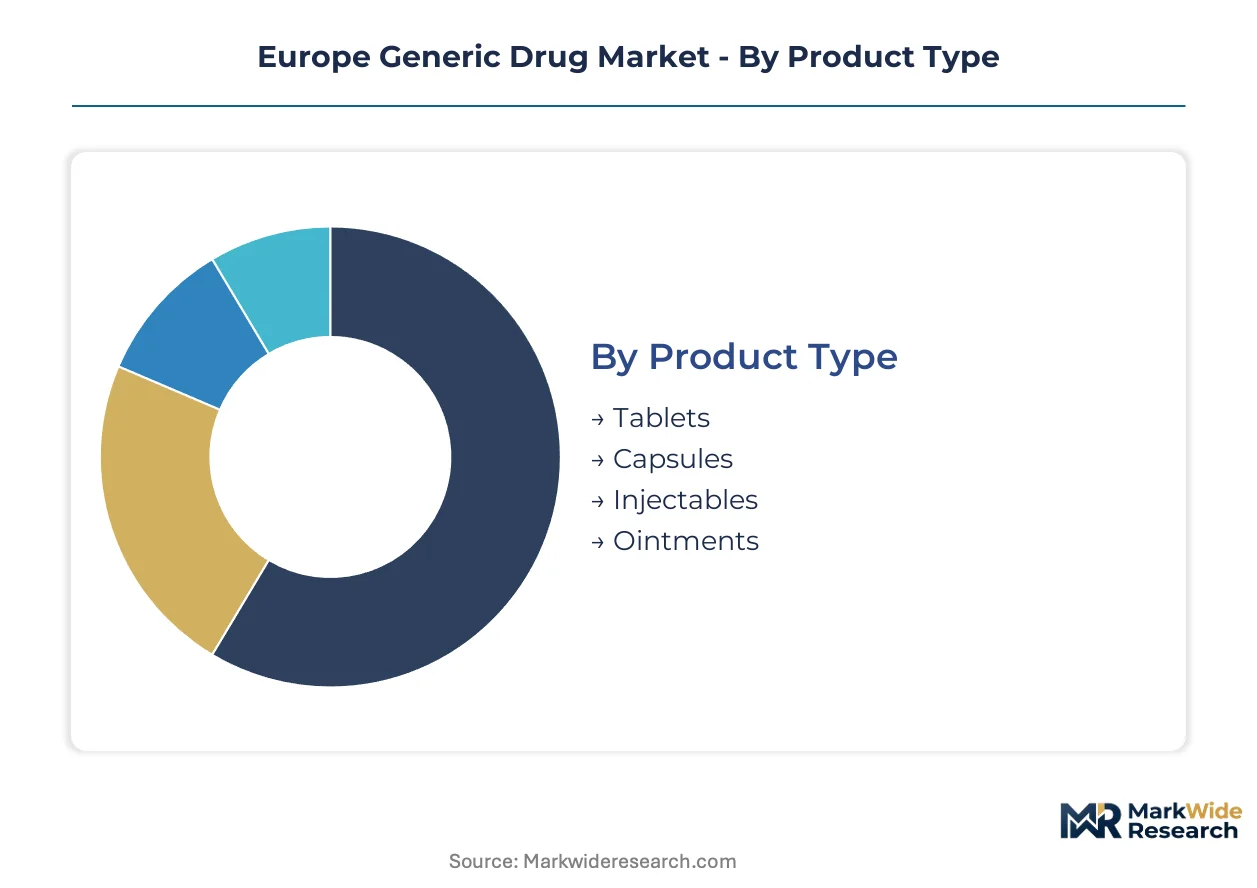
Segmentation in the Europe Generic Drug Market reveals how formulation science, procurement channel power, and regulatory compliance requirements reshape competitive positioning across member states. Each dimension exposes distinct margin structures and investment priorities for manufacturers navigating EMA frameworks and national tender systems.
Product Type:
Hospital procurement channels favor injectables and high-volume solid doses, while retail pharmacy networks concentrate on patient-administered oral formulations with longer stability profiles.
- Tablets:Compressed solid-dose formulations dominate chronic disease maintenance therapies including cardiovascular and metabolic conditions. German and French retail pharmacy chains drive volume through automated dispensing contracts, though EMA bioequivalence requirements for modified-release variants extend development timelines.
- Injectables:Sterile liquid formulations for oncology, anesthesia, and biologic delivery command premium positioning in hospital tender frameworks. Italy's oncology consortia and Poland's hospital purchasing alliances prioritize cold-chain reliability and shortage mitigation guarantees over unit cost.
- Capsules:Gelatin or HPMC shells accommodate moisture-sensitive APIs and combination therapies. Demand concentrates in Mediterranean markets where patient preference for swallowability influences prescriber choice.
- Ointments:Semi-solid topical preparations for dermatological and ophthalmic applications face limited competition due to specialized manufacturing equipment requirements.
By volume, tablets lead. By growth pace, injectables are ahead.
End User:
Cost tier differentiation separates institutional purchasers with consolidated bargaining power from fragmented individual consumers.
- Hospitals:Multi-hospital procurement consortia in France, Italy, and Germany aggregate oncology and anesthesia generic demand into framework agreements with compliance scorecards. These contracts bundle volume commitments with quality metrics and direct manufacturer relationships.
- Retail Pharmacies:Community and chain pharmacies across Spain, Portugal, and the Netherlands dispense maintenance therapies for hypertension, diabetes, and hyperlipidemia. Reimbursement negotiations with national health systems determine formulary placement.
- E-commerce Platforms:Verified digital pharmacies with prescription authentication capabilities expand chronic disease fulfillment. Regulatory alignment with Falsified Medicines Directive serialization requirements constrains platform eligibility.
- Clinics:Outpatient specialist centers in ambulatory care networks purchase limited generic portfolios for same-day procedures.
Institutional purchasers capture the deepest discounts. Direct-to-patient channels expand most quickly.
Distribution Channel:
Supply concentration in wholesale networks is fragmenting as direct manufacturer relationships and digital platforms capture margin pools.
- Wholesale:Traditional pharmaceutical distributors maintain inventory and cold-chain infrastructure across multiple EU member states. German and Dutch logistics hubs serve as consolidation points for cross-border hospital deliveries.
- Direct Sales:Manufacturers bypass intermediaries for injectable generics with narrow temperature stability windows. Hospital pharmacy consortia in France and Italy mandate direct relationships for oncology frameworks.
- Online:E-pharmacy platforms with FMD-compliant serialization authentication displace wholesale channels for chronic maintenance therapies. Regulatory verification requirements favor scale players with integrated IT infrastructure.
- Offline:Remaining brick-and-mortar pharmacy counters handle acute prescriptions and same-day needs.
Wholesale retains volume leadership. Online channels gain share fastest.
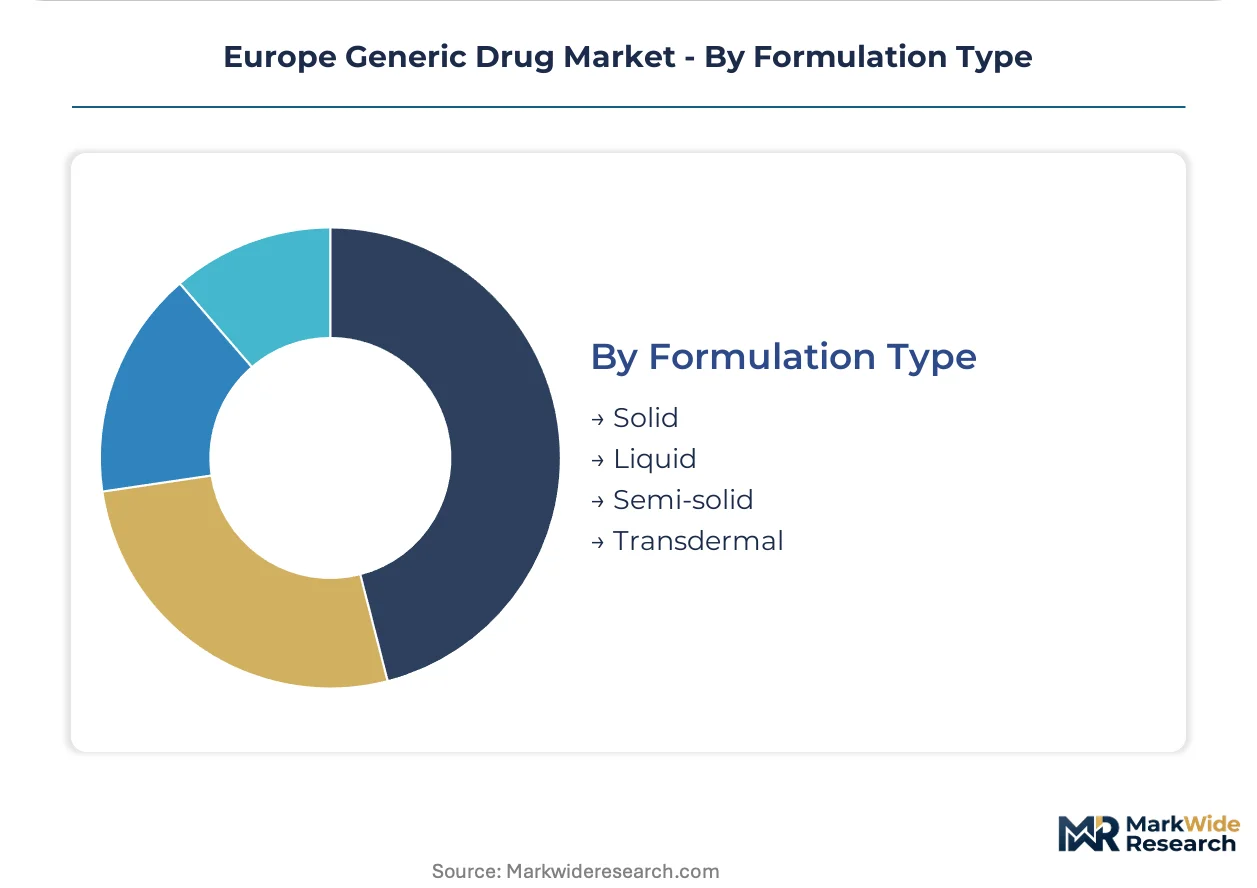
Formulation Type:
Manufacturing maturity separates established solid-dose platforms from emerging complex delivery systems facing bioequivalence uncertainty.
- Solid:Tablets, capsules, and powders leverage continuous manufacturing technologies for high-volume cardiovascular and respiratory production. Czech and Hungarian manufacturing zones specialize in captive API-to-finished-dose integration.
- Liquid:Solutions, suspensions, and syrups serve pediatric and geriatric populations with swallowing difficulties. Oral liquid generics face stability and taste-masking formulation challenges.
- Semi-solid:Creams, gels, and ointments require specialized homogenization equipment and preservative validation. Limited competition preserves margin pools for qualified manufacturers.
- Transdermal:Patches and topical delivery systems face EMA bioequivalence study requirements for adhesion, irritation, and pharmacokinetic endpoints. Complex generic pathways previously blocked by regulatory science gaps now attract development investment.
Solid formulations dominate volume. Transdermal systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement consortia command steeper tender discounts than Italian regional health authorities, creating a pricing-power asymmetry that fragments margin structures across the continent.
Germany
Hospital pharmacy alliances in North Rhine-Westphalia and Bavaria aggregate oncology and anesthesia generic demand into multi-year framework agreements. The Federal Institute for Drugs and Medical Devices (BfArM) enforces stringent bioequivalence documentation for modified-release formulations. Manufacturing clusters around Frankfurt and Munich specialize in continuous direct compression technologies for high-volume cardiovascular tablets.
France
Regional hospital consortia in Île-de-France and Auvergne-Rhône-Alpes consolidate purchasing for injectable generics with narrow temperature stability windows. ANSM maintains post-market surveillance requirements that align with EMA centralized procedures for complex generic pathways. Lyon and Paris host bioequivalence laboratories facing capacity constraints that extend study timelines for first-to-file entrants.
Italy
Oncology consortia in Lombardy and Lazio prioritize cold-chain reliability and shortage mitigation guarantees over unit cost in tender evaluations. The Italian Medicines Agency (AIFA) implements reference pricing cascades that trigger cross-border reimbursement benchmarking with German and French systems. Milan anchors formulation manufacturing for semi-solid dermatological preparations with limited competition.
Poland
Hospital purchasing alliances in Warsaw and Kraków consolidate multi-year framework agreements favoring suppliers with localized manufacturing. The Office for Registration of Medicinal Products enforces Falsified Medicines Directive serialization requirements across all pack sizes. Manufacturing zones in Łódź and Wrocław attract API reshoring investments from Indian and Chinese parent companies seeking REACH compliance.
Spain
Regional health systems in Catalonia and Madrid drive volume tendering for chronic maintenance therapies in hypertension and diabetes. The Spanish Agency for Medicines and Health Products (AEMPS) coordinates with EMA on centralized marketing authorization procedures. Barcelona hosts specialized facilities for transdermal patch development facing emerging bioequivalence study requirements.
Europe Generic Drug Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where backward-integrated API producers compete against formulation-only specialists. Large-scale manufacturers with captive active pharmaceutical ingredient production protect margin pools through supply security guarantees. Mid-tier competitors face compression from serialization investments and tender aggregation trends. Dominant competitive moves include strategic partnerships with hospital procurement consortia and geographic expansion into Central and Eastern European manufacturing zones.
Among Israel-based pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd exemplifies the backward-integrated archetype with captive API manufacturing. Indian specialists Dr. Reddy's Laboratories Ltd and Sun Pharmaceutical Industries Ltd occupy positions emphasizing cost-optimized oncology injectables and complex generic portfolios. Sandoz, operating as a Novartis division, anchors the biosimilar and hospital channel specialist tier across Western European markets.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Lupin |
| Teva Pharmaceutical Industries Ltd |
| Wockhardt |
| Apotex |
| Viatris |
| Dr. Reddy's Laboratories Ltd |
| Endo International plc |
| Sandoz |
| Others |
Cost & Logistics Intelligence
REACH compliance and EMA serialization mandates gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb fixed compliance costs that compress mid-tier margins while scale players capture premium positioning through supply security guarantees.
Pricing Analysis
The customization-premium spread separates standard solid-dose tablets from complex generic formulations requiring specialized bioequivalence documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and cold-chain reliability guarantees. Cost compression in standard oral generics is intensifying because hospital procurement consortia aggregate demand into multi-year framework agreements. Tender-driven hospital purchasers exhibit the highest price sensitivity, while retail pharmacy chains with automated dispensing contracts tolerate moderate premiums for supply continuity.
Supply Chain Analysis
Just-in-time inventory models predominate for high-volume solid-dose cardiovascular products, while strategic stockpiling characterizes injectable generics with narrow temperature stability windows. API production concentrates in India and China, with formulation finishing in Germany, France, and Italy. The supply chain draws from Chinese intermediate suppliers, Indian bulk API producers, and European excipient manufacturers. Single-source vulnerability in oncology injectable APIs creates structural risk for hospital pharmacy consortia. Distribution runs through direct manufacturer relationships for hospital channels and wholesale networks for retail pharmacy fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Generic Drug Market sits in a cyclical recovery phase driven by the biologic patent cliff wave between 2025 and 2030, which opens formulation opportunities for insulin, monoclonal antibodies, and peptide therapies.
For Market Incumbents: Fortify backward integration into active pharmaceutical ingredient manufacturing to protect margin pools against API import concentration risks. Scale players should expand captive production investments in Czech Republic and Hungarian manufacturing zones to satisfy REACH compliance requirements and tender aggregation preferences for localized supply. For New Entrants and Emerging Players: Lead with complex generic formulation gaps in abuse-deterrent opioids, colloidal iron complexes, and liposomal delivery systems where limited competition preserves margin pools. Central and Eastern Europe tender aggregation in Poland, Romania, and Bulgaria offers the most penetrable geography for suppliers with cold-chain distribution capabilities. For Investors and Strategic Acquirers: EMA centralized procedure backlogs and bioequivalence laboratory capacity constraints reshape the acquisition landscape by extending study timelines and elevating first-to-file premium capture. Long-term viability across the next decade hinges on manufacturing configurations that sustain profitability under tightening reimbursement caps. Acquisition targets should demonstrate integrated serialization infrastructure and direct hospital consortia relationships. Watch biosimilar interchangeability rulings as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| API Reshoring Investment | Captive production in Czech and Hungarian zones satisfies REACH and EMA serialization mandates for EU hospital tenders. |
| Continuous Manufacturing Scale-Up | Hot-melt extrusion and direct compression platforms compress batch cycles for cardiovascular solid-dose volume. |
| Hospital Consortia Partnership | Direct relationships with French and Italian oncology alliances displace wholesale intermediaries for injectables. |
| Complex Generic Pipeline Expansion | Abuse-deterrent and liposomal formulations face limited competition due to bioequivalence study barriers. |
| E-Pharmacy Platform Integration | FMD-compliant serialization authentication enables verified direct-to-patient fulfillment for chronic therapies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital pharmacy directors, EMA regulatory affairs specialists, generic drug manufacturing executives, and national tender procurement managers. Secondary validation incorporated EMA centralized procedure databases, national competent authority filings, hospital procurement consortium contract registries, and REACH compliance disclosure records. Bottom-up volume modeling and top-down value triangulation reconciled manufacturer shipment data with national reimbursement statistics.
Across the analysis window, the forecasting framework modeled segmentation dimensions including formulation type, distribution channel, end-user procurement tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of patent expiry waves, tender aggregation trajectories, and bioequivalence filing rates. Forecast inputs incorporated EMA approval pipeline velocity, hospital consortia contract renewal cycles, and API reshoring investment announcements.
The analysis sits within stated boundaries; outcomes outside sustained patent cliff timing, stable REACH enforcement, and continued hospital procurement consolidation would require recalibration. Forecasts reflect documented assumptions regarding bioequivalence study cost trajectories and serialization system adoption curves. Practitioners should keep alternative scenarios live as biosimilar interchangeability rulings and cross-border reimbursement benchmarking evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Medical Nitroglycerin Spray Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market