
 Trenbolone Acetate Market | 2026-2036
Trenbolone Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Trenbolone Acetate Market Insights
Veterinary pharmaceutical formulation expertise is reorganizing competitive dynamics as specialized compounding knowledge becomes scarcer. TIEN Pharmaceutical leverages its integrated fermentation and synthesis capabilities to control raw material costs across the supply chain. EUROAPI anchors European distribution through its established GMP-certified manufacturing network. Merck Animal Health competes by sustaining deep relationships with large-scale livestock integrators in North and South America.
Trenbolone acetate is a synthetic androgenic-anabolic steroid with a molecular structure derived from nandrolone, featuring an acetate ester at the 17-beta hydroxyl group that enables sustained release when administered via subcutaneous implant in cattle. The compound functions primarily as a growth promoter in livestock, increasing nitrogen retention and protein synthesis to accelerate muscle development and feed efficiency in beef production systems. Injectable formulations dominate commercial volumes due to their established use in veterinary protocols and predictable pharmacokinetic profiles, while pellet implants capture premium positioning among integrated cattle operations seeking labor-reducing administration methods. The livestock farmer customer segment generates the most concentrated revenue pool, though bodybuilder-directed demand through alternative channels creates parallel margin opportunities with distinct regulatory risk profiles.
The FDA's Center for Veterinary Medicine oversees approval and residue monitoring for trenbolone acetate implants under the New Animal Drug Application framework, while the EPA evaluates environmental discharge from concentrated animal feeding operations where metabolites enter wastewater streams. Brazil's MAPA and the EU's EMA maintain divergent stances on hormonal growth promoters, fragmenting market access and forcing manufacturers to maintain separate product registrations and labeling systems. Stakeholders must monitor shifting regulatory thresholds for residue limits in export markets and anticipate how precision livestock technologies might alter administration protocols and compliance documentation requirements.
Market Dynamics
Supply-side concentration among GMP-certified fermentation specialists is constraining formulation capacity expansion while FDA residue monitoring intensifies compliance costs for cattle finishing operations.
Growth Catalysts
- Export-oriented feedlot expansion:Brazilian beef processors are scaling implant procurement to meet Chinese and Middle Eastern import quotas, driving sustained volume demand for sustained-release pellet formulations.
- Veterinary Feed Directive adaptation:US livestock integrators have reorganized procurement workflows to comply with FDA veterinary oversight requirements, creating structured demand channels for prescription-aligned implant distribution.
- Precision livestock integration:Sensor-enabled cattle monitoring systems are enabling data-driven administration timing, improving feed conversion outcomes and justifying premium implant positioning.
Market Restraints
- Raw material concentration:Fermentation-derived steroid precursors depend on a limited base of European and Chinese API manufacturers, creating supply vulnerability during regulatory inspections.
- Environmental discharge liability:EPA evaluation of trenbolone metabolites in concentrated animal feeding operation wastewater imposes treatment infrastructure costs that squeeze margins in high-volume regions.
- Biologic growth promoter competition:Beta-agonist alternatives and ionophore combinations are capturing share in cost-sensitive feedlot segments where implant labor costs outweigh efficiency gains.
Strategic Opportunities
- Sub-Saharan African beef development:Emerging commercial cattle operations in Botswana and Namibia present first-mover positioning for implant suppliers as regional feedlot infrastructure materializes.
- Blockchain traceability integration:EU import documentation requirements are creating demand for implant lot-tracking systems that verify residue compliance across export supply chains.
- Compounding pharmacy channel development:Specialized veterinary formulation outsourcing is opening alternative distribution pathways for customized dose implants in niche cattle genetics segments.
Industry Challenges
- Sterile formulation expertise scarcity:Veterinary pharmaceutical compounding requires specialized aseptic processing skills that training pipelines have failed to replenish, constraining manufacturing scale-up.
- Cross-jurisdictional registration complexity:Divergent EMA and MAPA residue thresholds force manufacturers to maintain parallel product specifications, fragmenting production runs and diluting economies of scale.
- Legacy implant administration infrastructure:Existing cattle handling equipment in smaller feedlots lacks precision dosing capability, creating adoption friction for next-generation extended-release formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trenbolone Acetate Market |
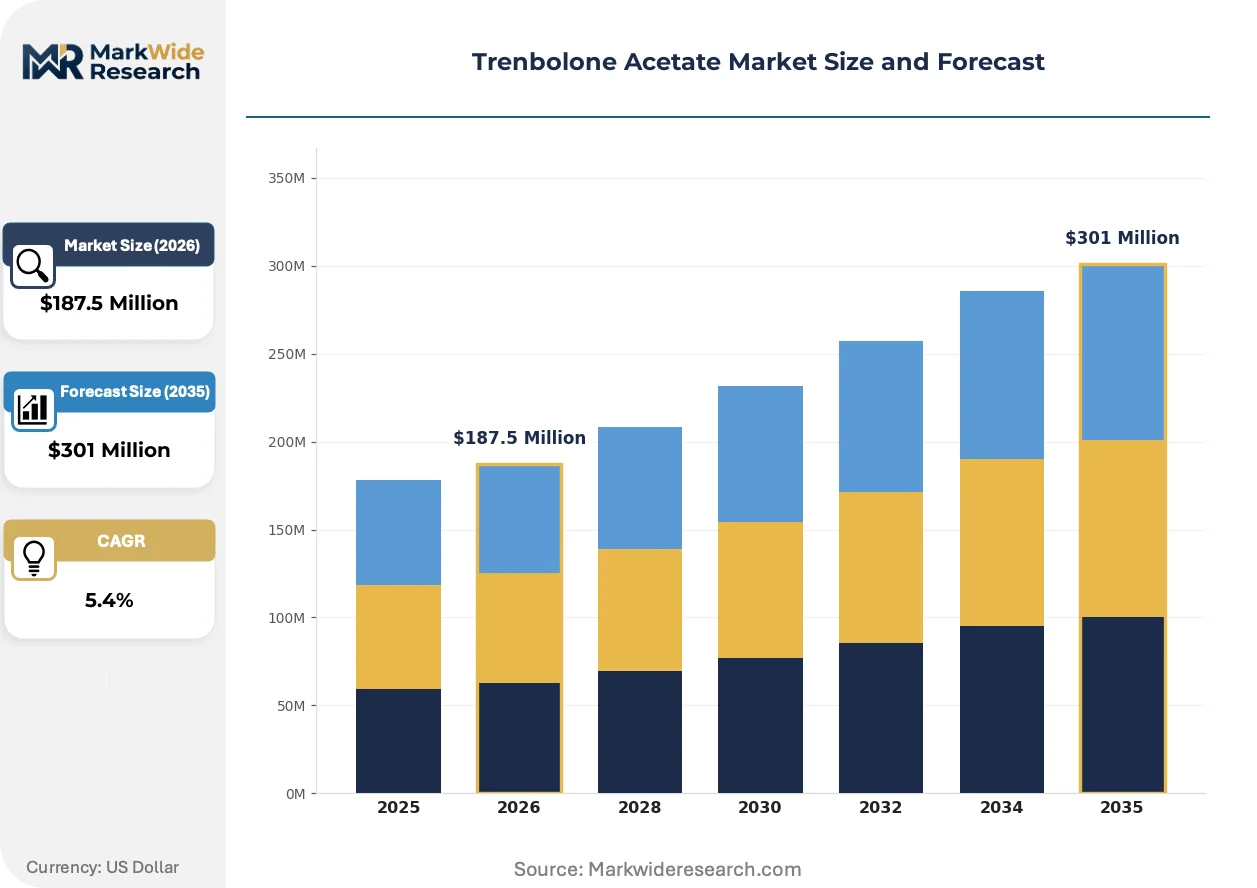
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $301 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Tablets, Powders, Pellets Application: Animal Growth, Muscle Building, Performance Enhancement, Veterinary Use Distribution Channel: Online Pharmacies, Retail Pharmacies, Veterinary Clinics, Supermarkets Customer Type: Bodybuilders, Athletes, Veterinarians, Livestock Farmers |
| Companies Covered | TIEN (Tianjin) Pharmaceutical, EUROAPI, Merck Animal Health, Sanofi, Minakem, Zoetis, Zhuhai Wumei Technology, ASG Biochem, Hubei Yikangyuan Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trenbolone Acetate Market Trends and Innovations
Active pharmaceutical ingredient traceability requirements and precision administration technologies are restructuring how trenbolone acetate moves from fermentation through finished implant deployment.
Extended-release polymer matrix technology is fragmenting traditional implant administration schedules. Large-scale Nebraska and Texas feedlots are adopting 200-day duration formulations to reduce labor-intensive re-implant cycles. This compression of veterinary service intervals is redistributing value capture toward formulation innovators and away from clinic-based administration providers.
EMA's tightened maximum residue limits for hormonal growth promoters in imported beef are forcing export-oriented Brazilian processors to implement enhanced withdrawal period documentation. The industrial consequence is accelerated investment in metabolite testing infrastructure at slaughter facilities. European supermarket chains are responding by demanding third-party verified implant-free certification for premium beef lines.
Direct procurement relationships between livestock integrators and API manufacturers are displacing traditional veterinary distributor intermediaries. Tyson Foods and JBS SA are establishing captive supply arrangements with fermentation specialists to secure volume commitments. This channel consolidation is most visible in the US Plains states and Mato Grosso feedlot corridors where integrated operations dominate cattle finishing capacity.
Trenbolone Acetate Market Segmentation
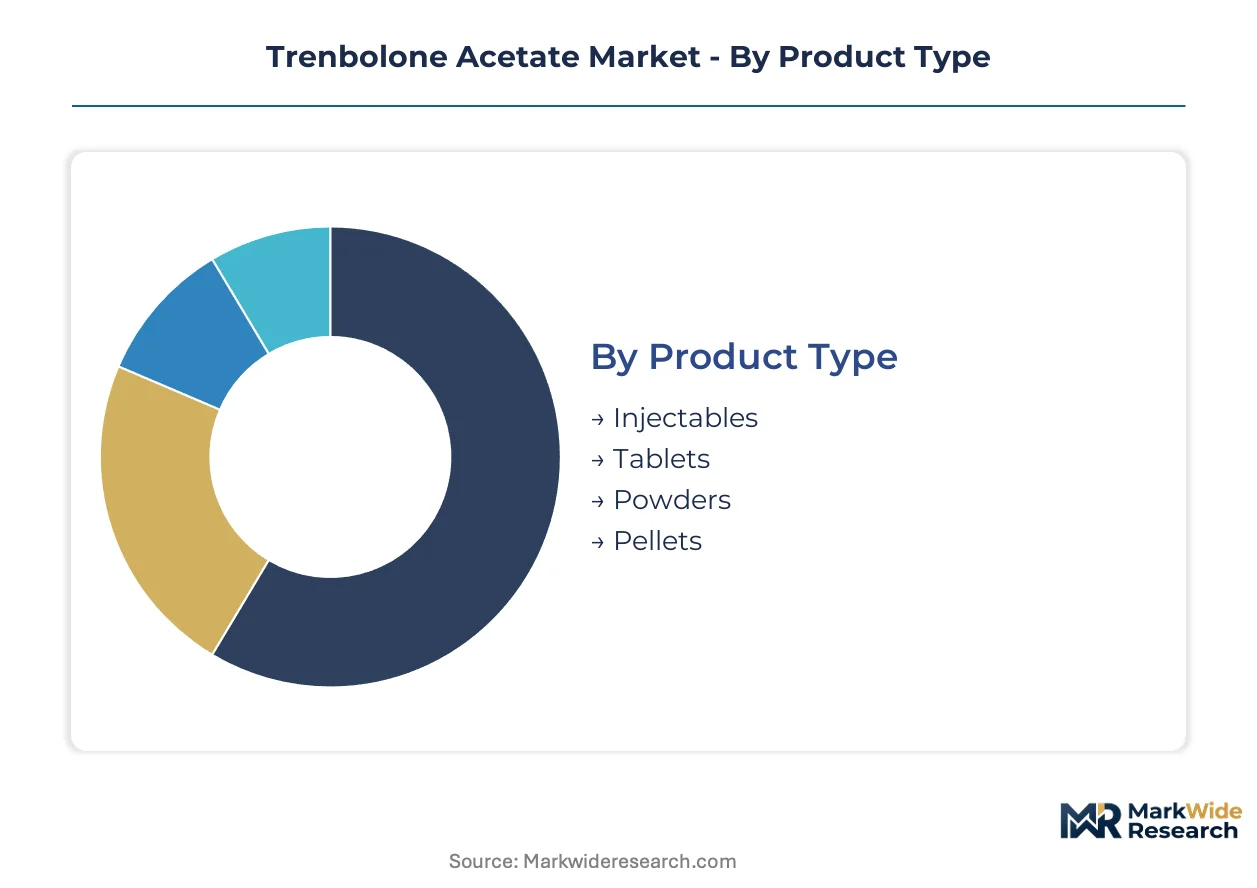
Trenbolone acetate segmentation reflects divergent regulatory frameworks governing veterinary versus human-directed use, with formulation choices directly shaped by compliance requirements in target jurisdictions. Product type and customer distinctions carry significant legal and operational consequences for manufacturers and distributors.
Product Type:
FDA's Center for Veterinary Medicine and EMA residue thresholds create divergent formulation standards that segment manufacturing capacity across implantable and injectable platforms.
- Injectables:Oil-based solutions for intramuscular administration dominate commercial volumes through established veterinary protocols in US feedlots. Nebraska and Texas cattle operations favor this format for predictable pharmacokinetic profiles and flexible dosing adjustment. FDA residue monitoring protocols are well-calibrated to injectable elimination curves.
- Pellets:Subcutaneous implant formulations capture premium positioning among integrated operations seeking labor reduction through extended-release delivery. Brazilian export-oriented processors are scaling procurement of 200-day polymer matrix implants to meet Chinese import documentation requirements.
- Tablets:Oral formulations face restrictive scheduling in most jurisdictions, limiting legitimate veterinary application to specific regulatory exemptions.
- Powders:Bulk active pharmaceutical ingredient form serves compounding pharmacies and specialized formulation facilities with custom dose capabilities.
Established volume favors injectables; emerging adoption favors pellets.
Application:
End-use segmentation tracks sharply divergent margin profiles and enforcement exposure between livestock production and human performance enhancement channels.
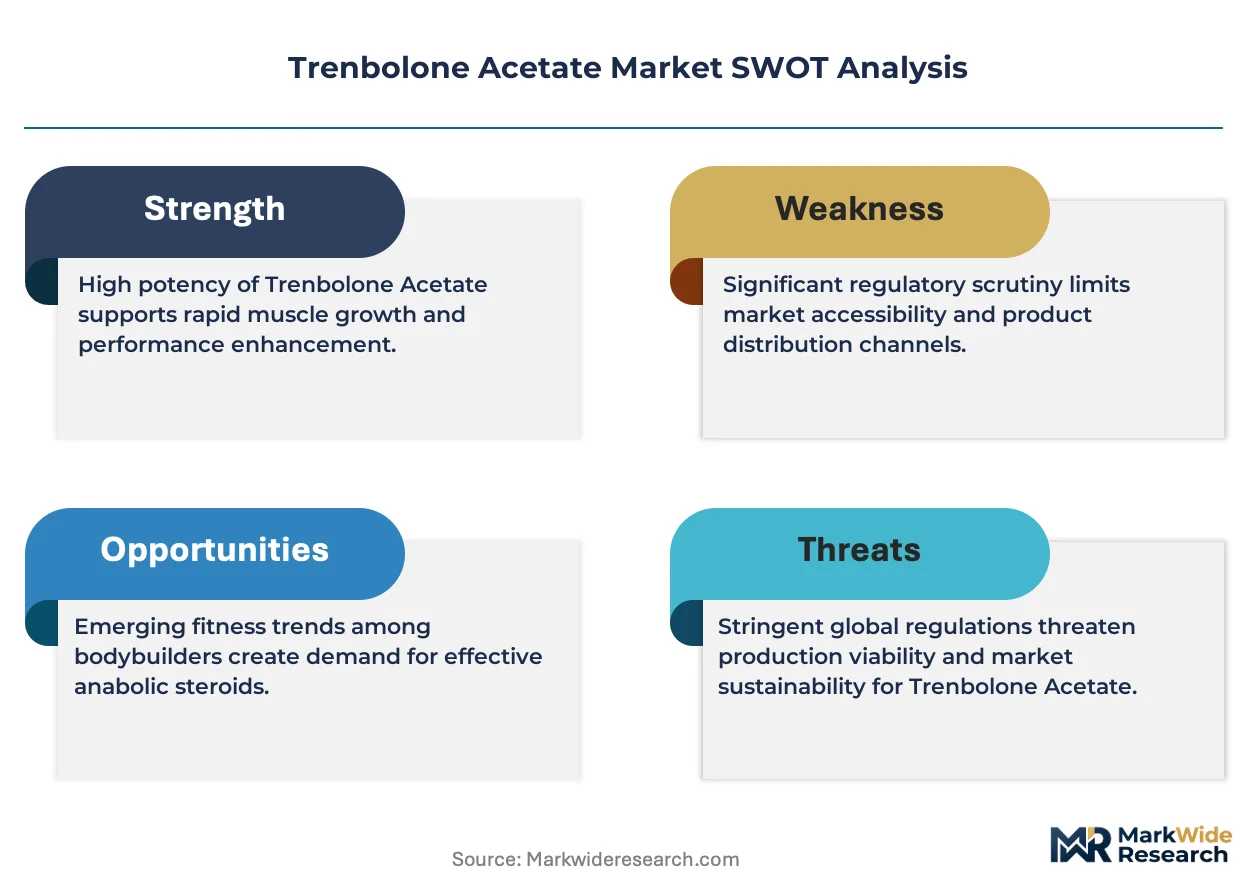
- Animal Growth:Cattle finishing operations in Brazil's Mato Grosso feedlot corridor and US Plains states generate concentrated revenue through nitrogen retention and protein synthesis acceleration. MAPA and FDA oversight frameworks structure procurement into prescription-aligned distribution channels.
- Veterinary Use:Clinical administration by licensed practitioners operates under veterinary feed directive compliance requirements, with Tyson Foods and JBS SA establishing direct API procurement relationships to secure supply.
- Muscle Building:Human-directed demand operates through alternative channels with distinct regulatory risk profiles and premium pricing outside legitimate pharmaceutical distribution.
- Performance Enhancement:Athletic use faces comprehensive prohibition by WADA and national anti-doping agencies, creating enforcement-driven market fragmentation.
Animal growth commands production scale; veterinary use concentrates margin capture.
Distribution Channel:
Channel structure is reorganizing around livestock integrator direct procurement and blockchain-enabled traceability for EU export compliance.
- Veterinary Clinics:Traditional administration points in US cattle regions are consolidating as extended-release formulations compress re-implant service intervals. Clinics are expanding pellet procurement for finishing operations while losing share on labor-reducing long-duration implants.
- Online Pharmacies:Digital distribution platforms face intensified scrutiny under FDA veterinary feed directive enforcement, with prescription verification requirements constraining volume growth.
- Retail Pharmacies:Limited veterinary pharmaceutical stocking due to specialized storage and handling requirements for controlled substance formulations.
- Supermarkets:Minimal direct participation; grocery chains are demanding third-party verified implant-free certification for premium beef lines sourced from export-oriented processors.
Veterinary clinics retain procedure-linked revenue; online pharmacies face compliance compression.
Customer Type:
Customer segmentation reflects fundamentally divergent procurement scale, price sensitivity, and regulatory exposure between commercial livestock operations and individual users.
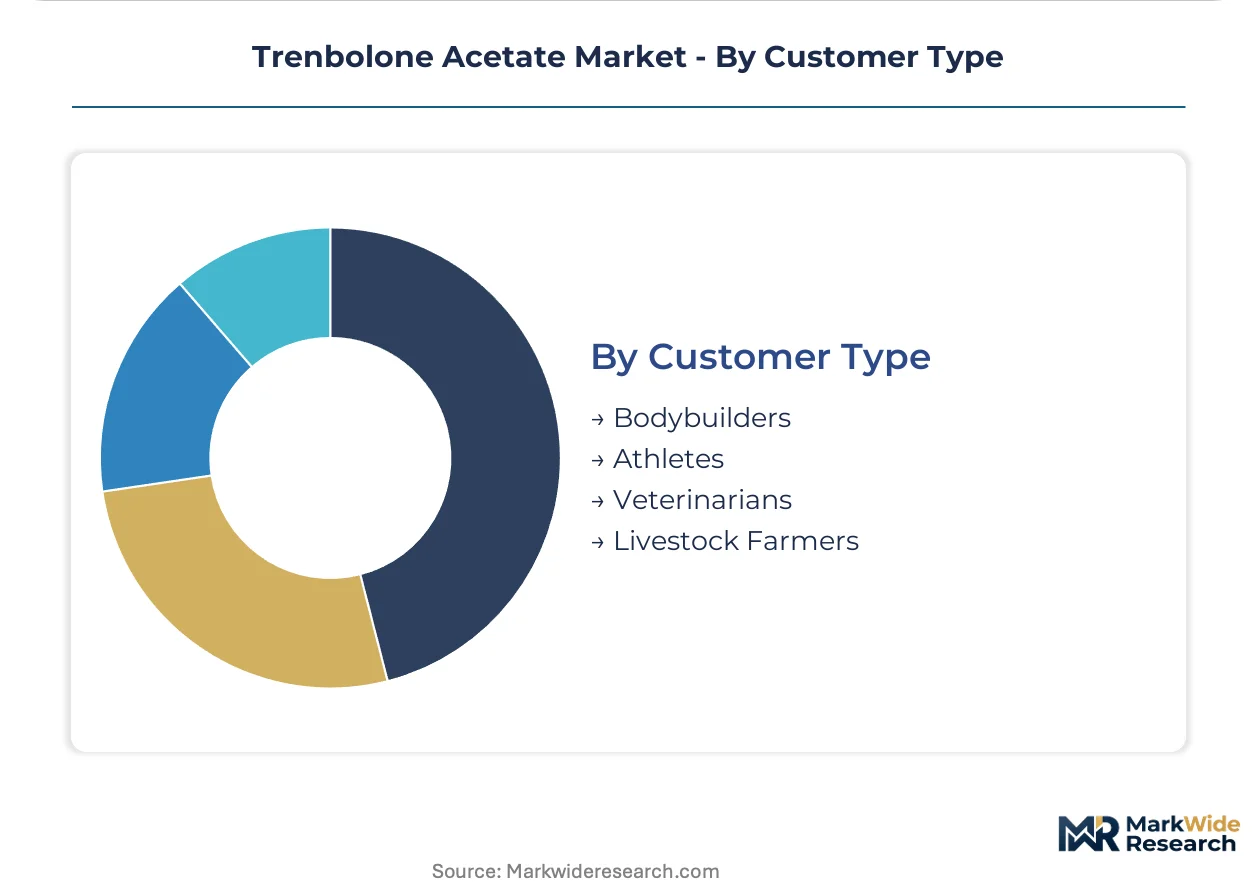
- Livestock Farmers:Integrated cattle operations in Botswana and Namibia emerging markets present first-mover positioning as regional feedlot infrastructure materializes. Brazilian processors prioritize weight-gain efficiency to meet Middle Eastern and Chinese import quotas.
- Veterinarians:Licensed practitioners serve as gatekeepers under FDA veterinary oversight requirements, with procurement workflows reorganized to comply with prescription-aligned distribution.
- Bodybuilders:Individual demand creates parallel margin opportunities through alternative channels with elevated legal risk and premium pricing relative to veterinary formulations.
- Athletes:Prohibited use under WADA codes creates enforcement-driven market concealment with minimal legitimate pharmaceutical participation.
Livestock farmers drive production volume; veterinarians control access gatekeeping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's veterinary feed directive anchors North American procurement structures while Brazil's MAPA and the EU's EMA maintain divergent residue thresholds that fragment cross-border trade flows.
United States
Nebraska and Texas feedlot corridors drive concentrated demand for extended-release pellet formulations. FDA residue monitoring protocols under the New Animal Drug Application framework structure prescription-aligned distribution channels. Large-scale integrators in the US Plains states are establishing direct API procurement relationships with fermentation specialists to secure volume commitments.
Brazil
Mato Grosso feedlot operations prioritize implant procurement to meet Chinese and Middle Eastern beef import quotas. MAPA's regulatory stance on hormonal growth promoters requires separate product registrations from European specifications. Export-oriented processors are scaling 200-day polymer matrix implants while implementing enhanced metabolite testing infrastructure at slaughter facilities.
Germany
EUROAPI's GMP-certified manufacturing network anchors European distribution capacity for veterinary steroid formulations. EMA's tightened maximum residue limits for imported beef force parallel product specifications that fragment production runs. The country's pharmaceutical compounding sector faces sterile formulation expertise scarcity that constrains manufacturing scale-up.
China
Zhuhai Wumei Technology and Hubei Yikangyuan Chemical represent fermentation-derived steroid precursor capacity serving global API demand. The country's national pharmaceutical regulator maintains oversight of active pharmaceutical ingredient exports for veterinary applications. Manufacturing clusters in the Pearl River Delta and central provinces supply raw material inputs to Brazilian and North American formulation facilities.
India
ASG Biochem occupies a position within the specialist API manufacturing tier serving compounding pharmacy channels. CDSCO's veterinary drug approval framework structures domestic market access for growth-promoting compounds. Emerging commercial cattle operations in neighboring sub-Saharan markets present first-mover positioning opportunities for implant suppliers as regional feedlot infrastructure materializes.
Trenbolone Acetate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the trenbolone acetate supply structure. Fermentation-capable pharmaceutical conglomerates control upstream steroid precursor production while specialized compounding pharmacies capture margin in customized dose segments. Three archetypes dominate: integrated API-to-implant manufacturers, GMP-certified formulation specialists, and regional distribution anchors. Competitive moves concentrate on backward integration into fermentation capacity and blockchain-enabled traceability partnerships for EU export compliance.
Within the integrated manufacturing tier, TIEN (Tianjin) Pharmaceutical exemplifies fermentation and synthesis capabilities that control raw material costs across supply chains. EUROAPI occupies a position as the European distribution anchor through its established GMP-certified manufacturing network. Merck Animal Health represents the livestock integrator relationship specialist, sitting within the North and South American market access tier. These three companies illustrate how geographic origin and corporate structure shape competitive positioning in a market where sterile formulation expertise scarcity constrains expansion.
| Leading Market Players |
|---|
| TIEN (Tianjin) Pharmaceutical |
| EUROAPI |
| Merck Animal Health |
| Sanofi |
| Minakem |
| Zoetis |
| Zhuhai Wumei Technology |
| ASG Biochem |
| Hubei Yikangyuan Chemical |
| Others |
Pricing and Supply Chain Analysis
Fermentation scale economies at Chinese API manufacturers compress unit economics for steroid precursors while simultaneously elevating price floors for GMP-certified formulation facilities in Europe and North America. This dual dynamic concentrates margin capture upstream among raw material specialists and squeezes compounding pharmacies attempting to scale sterile processing capacity.
Pricing Analysis
Brazilian import parity pricing for 200-day polymer matrix implants runs 15-25% above US Plains states contract rates due to MAPA documentation requirements and metabolite testing infrastructure costs. Three-tier pricing structure across premium extended-release, standard injectable, and economy bulk API levels reflects certification grade and withdrawal period verification intensity. Pricing pressure stems from EPA-mandated wastewater treatment investments at concentrated animal feeding operations that force feedlot procurement officers to squeeze implant budgets. Livestock integrators demonstrate highest price sensitivity due to volume scale and direct API procurement relationships, while specialized cattle genetics operations absorb premium positioning for customized dose formulations.
Supply Chain Analysis
China and India anchor fermentation-derived steroid precursor production, with Hubei province and Gujarat manufacturing clusters feeding global API demand. European GMP-certified formulation facilities and Brazilian pellet implant finishing operations draw from this upstream concentration, with polymer matrix technology inputs sourced from specialty chemical producers in Germany and the United States. Single-source vulnerability concentrates in Chinese fermentation capacity subject to regulatory inspection disruptions. Distribution runs through direct procurement relationships between livestock integrators and API manufacturers, displacing traditional veterinary distributor intermediaries in high-volume corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in sub-Saharan commercial beef development and precision livestock technology integration creates sustained tailwinds for implant suppliers with formulation flexibility and regional registration expertise.
For Market Incumbents: Shield formulation margins by securing captive fermentation capacity through backward integration into Chinese or Indian API manufacturing, insulating against raw material concentration risk. Deepen sterile processing expertise pipelines through veterinary pharmaceutical compounding partnerships to constrain competitor scale-up. Priority lever: blockchain traceability certification for EU export compliance. For New Entrants and Emerging Players: Anchor in Botswana and Namibia feedlot infrastructure development as first-mover positioning before established Brazilian and North American suppliers consolidate regional distribution. Target compounding pharmacy channel partnerships for customized dose implants in niche cattle genetics segments. Go-to-market angle: precision livestock integration sensor bundles paired with data-driven administration timing protocols. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors GMP-certified formulation specialists with established residue monitoring relationships and direct livestock integrator procurement channels. Five-to-ten year viability hinges on regulatory fragmentation persistence between EMA and MAPA residue thresholds. Signal to watch: precision livestock technology adoption rates in Brazilian Mato Grosso and US Plains states feedlots as indicator of next-generation implant demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | TIEN Pharmaceutical's captive raw material control insulates margin from API supply disruption. |
| Blockchain Traceability Partnership | EUROAPI's lot-tracking systems verify residue compliance for European supermarket chain certification. |
| Extended-Release Polymer Matrix Launch | 200-day formulations compress re-implant cycles and redistribute value from clinics to innovators. |
| Direct Procurement Relationship Establishment | Tyson Foods and JBS SA bypass distributor intermediaries to secure volume commitments. |
| Sub-Saharan Distribution Channel Development | First-mover positioning in Botswana and Namibia captures emerging commercial feedlot infrastructure buildout. |
Research Methodology
A standing panel of veterinary pharmaceutical formulation executives, livestock integrator procurement officers, regulatory affairs specialists at FDA and MAPA, and compounding pharmacy operations directors provided ongoing calibration against secondary validation. Primary interviews triangulated with customs trade data for steroid precursor movements, FDA New Animal Drug Application filings, EMA residue limit documentation, and Brazilian MAPA registration databases. Bottom-up volume modeling across implant and injectable product types converged with top-down market sizing through API manufacturer capacity assessments.
Consistency checks validated projection outputs against external benchmarks including feedlot capacity expansion announcements, precision livestock technology deployment rates, and export beef quota allocations. Segmentation dimensions modeled encompass product formulation type, application end-use, distribution channel structure, and customer procurement scale across the analysis window. CAGRs derived from iterative reconciliation of historical volume trajectories with adoption curve assumptions for extended-release polymer matrix technology and metabolite testing infrastructure investment.
Material uncertainties — regulatory threshold revisions, environmental discharge liability expansion, and biologic growth promoter substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding FDA veterinary feed directive enforcement continuity and EMA-MAPA regulatory divergence persistence. Recalibration cycles align with material shifts in precision livestock technology penetration and sub-Saharan feedlot infrastructure financing flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market