
 Varicella Attenuated Live Vaccination Market | 2026-2036
Varicella Attenuated Live Vaccination Market Size, Share, and Industry Trends Forecast 2026-2036
Varicella Attenuated Live Vaccination Market Insights
China is tilting toward expanded varicella vaccine capacity as domestic manufacturers respond to national immunization program expansion. Merck & Co., Inc. anchors its position through established cold-chain distribution networks across North American and European markets. GlaxoSmithKline plc leverages its combination vaccine R&D pipeline to differentiate within pediatric formulation segments. Green Cross Corporation dominates supply across South Korean public health channels through localized production scale.
Varicella attenuated live vaccination employs the Oka strain of live varicella-zoster virus propagated in human diploid cell cultures, with titers standardized to induce protective cell-mediated immunity following subcutaneous administration. The primary commercial purpose centers on preventing primary varicella infection in susceptible pediatric and adult populations, thereby reducing shingles incidence later in life. Combination vaccine formulations are capturing expanding margin pools as health departments prioritize reduced injection-burden schedules for childhood immunization. Single dose presentations retain mature demand in resource-constrained community clinic settings where cold-chain infrastructure limits multi-dose vial utilization. Subcutaneous administration routes sustain dominant clinical practice despite intramuscular alternatives gaining traction in specific pediatric hospital protocols.
The FDA's Center for Biologics Evaluation and Research enforces stringent lot-release testing for live viral vaccines, while WHO prequalification standards govern procurement eligibility for low-income country immunization programs. China's NMPA implements accelerated review pathways for domestically manufactured pediatric vaccines, reshaping competitive access dynamics for imported products. India's CDSCO mandates local bridging studies for varicella vaccine licensure, creating additional regulatory barriers for foreign manufacturers. Stakeholders must monitor evolving national immunization schedule inclusion decisions across high-burden countries, as these policy shifts determine volume allocation between public tender and private purchase channels.
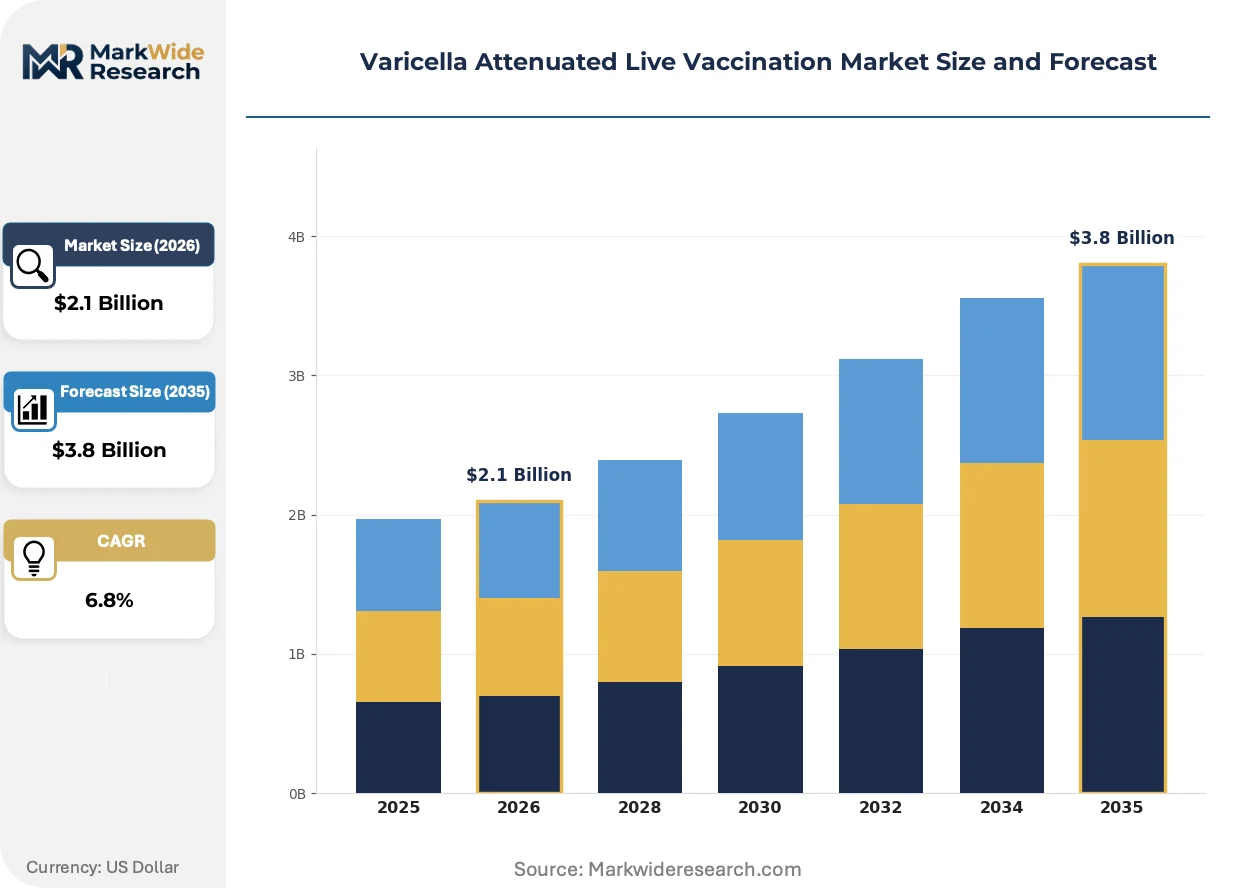
Market Dynamics
Pediatric hospitals are consolidating immunization programs around combination vaccine formats while China's NMPA accelerates domestic manufacturer approvals, compressing import-dependent supply structures and rewiring competitive access across high-volume public health channels.
Growth Catalysts
- National Immunization Schedule Expansion:China's inclusion of varicella vaccination in provincial public health mandates is pulling volume through domestic manufacturing scale. Local producers are capturing tender allocations previously reserved for imported presentations.
- Cold-Chain Infrastructure Modernization:Ultra-low temperature distribution networks are extending reach into community clinic settings previously excluded from live vaccine access. Equipment upgrades in South Korea and Japan are enabling subcutaneous administration at peripheral health posts.
- FDA Accelerated Approval Pathways:The Center for Biologics Evaluation and Research's priority review vouchers for pediatric indications are shortening development-to-market timelines. Sponsors are prioritizing combination formulations qualifying for these designations.
Market Restraints
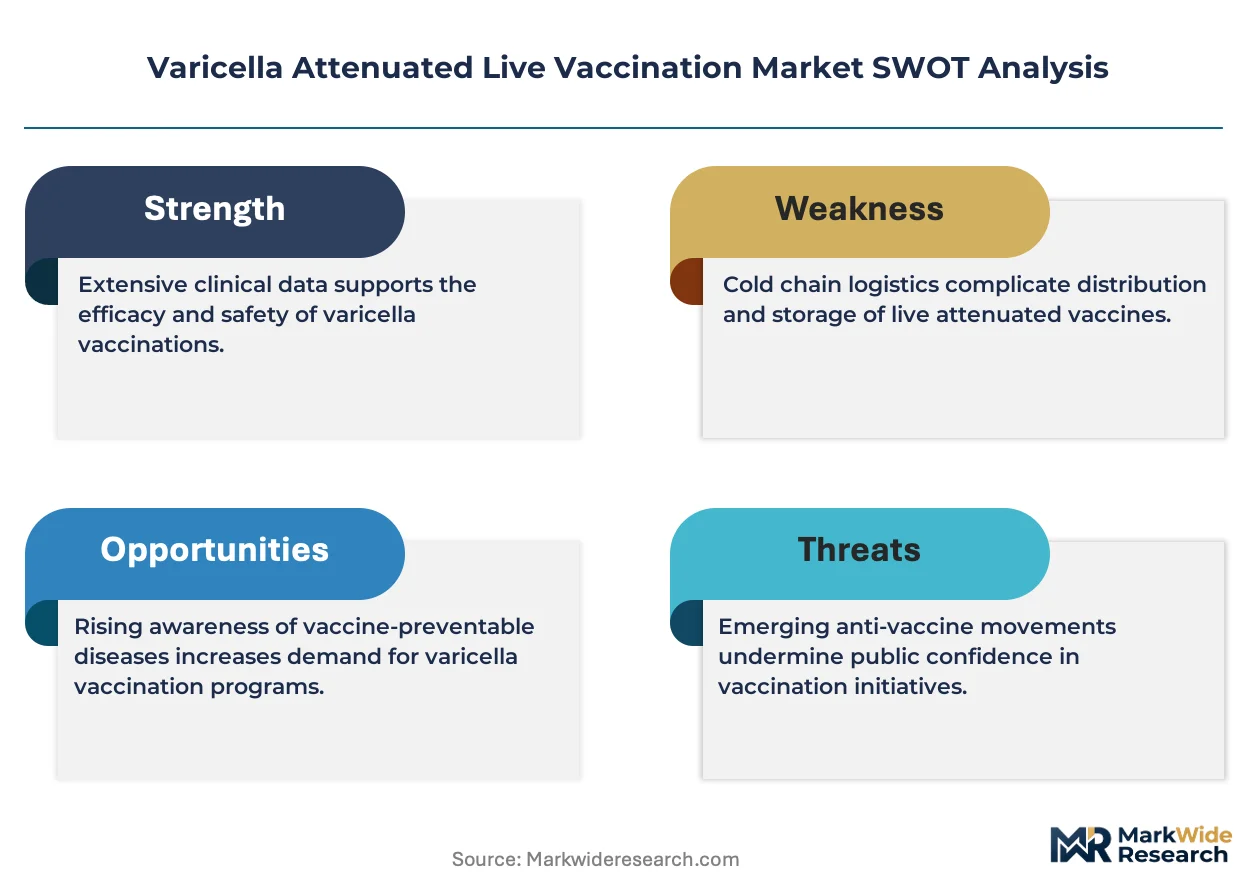
- MRC-5 Cell Substrate Supply Concentration:Human diploid cell culture material for Oka strain propagation concentrates among three qualified suppliers. Any contamination event disrupts batch release cycles across multiple manufacturers simultaneously.
- WHO Prequalification Cost Burden:Low-income country procurement eligibility requires extensive stability data packages. The documentation burden excludes smaller manufacturers from Gavi and UNICEF tender participation.
- Recombinant Zoster Vaccine Substitution:GlaxoSmithKline's adjuvanted subunit presentation for adult shingles prevention is capturing physician preference in private-pay segments. Live attenuated products face indication compression in aging populations.
Strategic Opportunities
- India CDSCO Local Bridging Study Requirements:Foreign manufacturers establishing domestic clinical trial infrastructure can circumvent lengthy import licensure delays. Joint development partnerships with Indian contract research organizations accelerate market entry.
- Intradermal Micro-Needle Delivery Convergence:Combination of live viral stabilization technology with dissolvable micro-array platforms enables needle-free pediatric administration. Early-stage developers are targeting hospital formulary committees with reduced phobia protocols.
- Pharmacy-Based Vaccination Channel Expansion:Retail clinic chains in the United States are securing standing orders for adult varicella catch-up programs. This channel bypasses traditional physician office inventory constraints.
Industry Challenges
- Cell Culture Technician Scarcity:Aseptic handling of live viral materials requires specialized GMP training. Manufacturers in emerging production hubs face recruitment competition from biologics contract manufacturing organizations.
- Lot Release Testing Backlogs:National control laboratories in high-volume markets face capacity constraints for adventitious agent screening. Extended hold times compress effective shelf life and complicate inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Varicella Attenuated Live Vaccination Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Dose, Multi Dose, Combination Vaccine, Pediatric Formulation End User: Pediatric Hospitals, Community Clinics, Doctor's Offices, Health Departments Administration Route: Subcutaneous, Intramuscular, Nasal, Oral Distribution Channel: Pharmacies, Hospitals, Online Platforms, Medical Supply Distributors |
| Companies Covered | Shanghai Institute of Biological Products, Biken (Research Foundation for Microbial Diseases of Osaka University), Merck & Co., Inc., Keygen Vaccines, BCHT (Beijing Chaoyang Biotechnology), GlaxoSmithKline plc, Green Cross Corporation, Changchun Changsheng Life Sciences Limited, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Varicella Attenuated Live Vaccination Market Trends and Innovations
Live vaccine formulation science is converging with delivery technology advances, while regulatory frameworks tighten around traceability and cold-chain verification. These forces are compressing traditional development timelines and redrawing competitive boundaries.
Lyophilized combination presentations incorporating measles-mumps-rubella-varicella antigens are collapsing the injection burden for pediatric completers. Large metropolitan health departments in the United States and France are adopting these quadrivalent formats for school-entry compliance programs. The technology is collapsing the margin structure of standalone varicella monotherapy, forcing single-dose manufacturers toward price-competitive community clinic segments.
China's NMPA implemented real-time temperature monitoring mandates for all pediatric live vaccines in 2023. Distributors must now deploy IoT-enabled cold boxes with blockchain-verified chain-of-custody documentation. Domestic manufacturers with integrated logistics capabilities are capturing provincial tender allocations that foreign competitors cannot service under the new technical requirements.
Hospital procurement committees are unbundling vaccine purchasing from bundled pharmaceutical contracts. Standalone immunization RFPs now specify combination product availability as a mandatory evaluation criterion. This pattern is most visible in German and Italian pediatric hospital networks, where formulary independence from group purchasing organizations is accelerating.
Varicella Attenuated Live Vaccination Market Segmentation
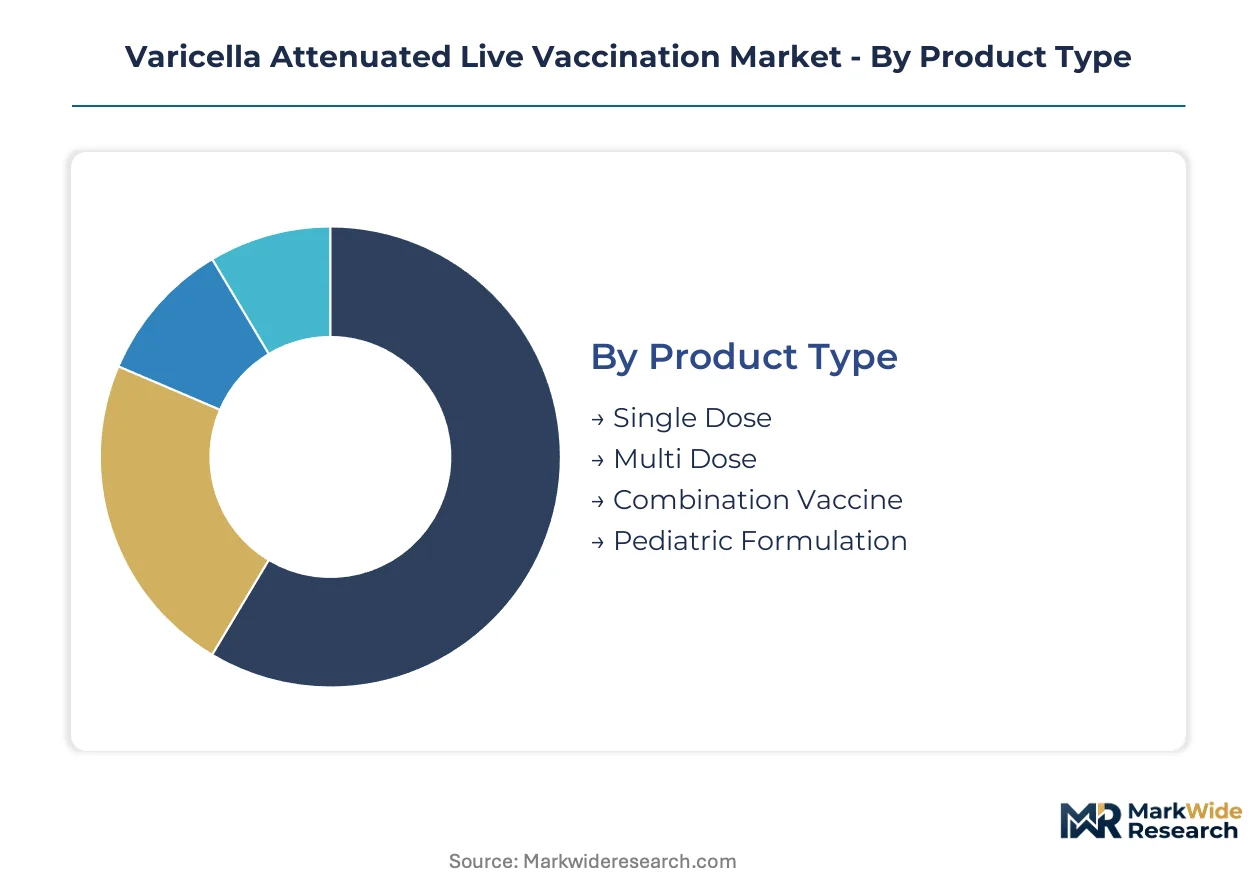
Varicella attenuated live vaccination demand fragments across product formats, care settings, and delivery pathways. Each segmentation dimension reveals distinct margin structures and regulatory exposure profiles that shape manufacturer positioning strategies.
Product Type:
Pediatric immunization programs span a cost-to-convenience spectrum, from standalone monotherapy to complex combination presentations.
- Combination Vaccine:Quadrivalent measles-mumps-rubella-varicella formulations collapse injection schedules for school-entry compliance. Metropolitan health departments in France and the United States prioritize these presentations to reduce clinic visit frequency and improve coverage rates.
- Single Dose:Lyophilized monotherapy presentations retain relevance in resource-constrained settings where cold-chain infrastructure limits multi-dose vial utilization. Community clinics in India and Brazil favor this format for its inventory flexibility and reduced wastage risk.
- Multi Dose:Ten-dose vials serve high-volume public health campaigns with cost efficiency per administered dose.
- Pediatric Formulation:Age-specific diluent volumes and needle gauges address neonatal and infant subcutaneous tissue depth requirements.
The dominant share belongs to Combination Vaccine, while Single Dose is closing the gap fastest in emerging market outreach programs.
End User:
Care setting determines cold-chain sophistication requirements and procurement authority structures.
- Pediatric Hospitals:Academic medical centers with dedicated immunization services manage ultra-cold storage and combination formulary adoption. These institutions drive protocol standardization that cascades to affiliated outpatient networks.
- Community Clinics:Federally qualified health centers and rural primary care sites face storage capacity constraints that favor single-dose presentations and shorter cold-chain intervals.
- Doctor's Offices:Private pediatric practices balance inventory carrying costs against patient convenience in fee-for-service reimbursement environments.
- Health Departments:State and municipal public health agencies control tender allocations for school-mandated immunization programs.
Pediatric Hospitals command the highest volume per site, though Community Clinics are expanding their immunization role through retail health partnerships.
Administration Route:
Delivery method selection reflects immunogenicity optimization and patient population characteristics.
- Subcutaneous:Delopectoral or anterolateral thigh injection remains the clinical standard for live varicella vaccine, with established immune response correlation and minimal adverse event profiles.
- Intramuscular:Deltoid administration gains adoption in adolescent catch-up programs where muscle mass supports larger volume delivery and healthcare workers prefer familiar injection technique.
- Nasal:Live viral aerosol delivery remains investigational for varicella, with mucosal immunity hypotheses yet to demonstrate non-inferiority to parenteral standards.
- Oral:Enteric-coated formulations face gastric acid barrier challenges that have stalled commercial development despite theoretical patient acceptance advantages.
Subcutaneous delivery holds entrenched clinical preference, yet Intramuscular protocols are gaining traction fastest among adolescent vaccination programs.
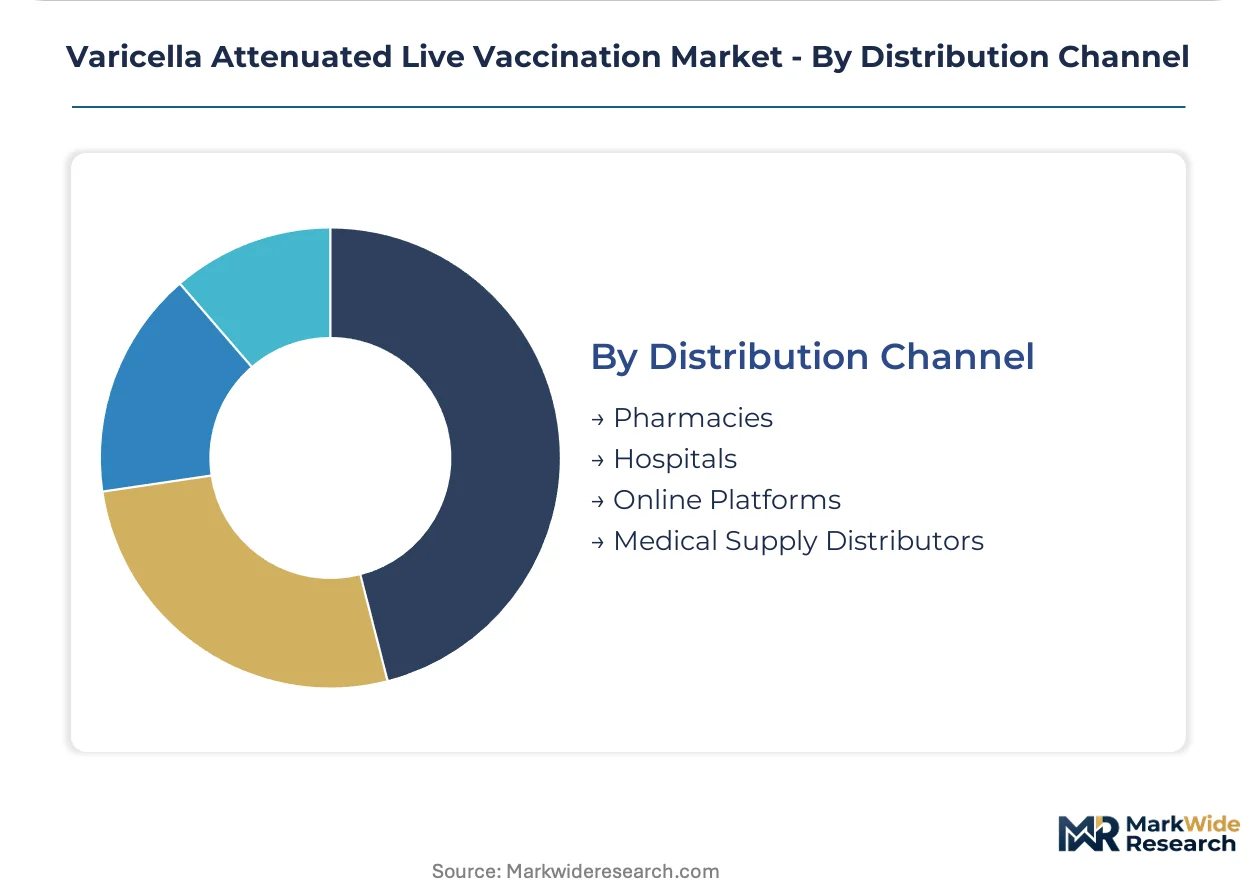
Distribution Channel:
Channel selection determines inventory velocity, temperature accountability, and margin capture allocation.
- Hospitals:Integrated delivery networks negotiate directly with manufacturers for combination vaccine bundles, capturing volume discounts and guaranteed supply commitments.
- Pharmacies:Retail clinic chains in the United States are securing standing orders for adult varicella catch-up, bypassing traditional physician office inventory constraints.
- Medical Supply Distributors:Specialized cold-chain logistics providers manage provincial tender fulfillment in China and national immunization program distribution in South Korea.
- Online Platforms:Direct-to-provider e-commerce channels serve independent practices with smaller lot sizes and expedited delivery guarantees.
Hospital purchasing aggregates the largest contract values, while Pharmacy channels are expanding their immunization service footprint fastest through retail clinic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pediatric vaccine approval pathways anchor the United States as the reference standard for regulatory stringency, while China's NMPA accelerates domestic manufacturer licensing to reshape supply access across high-volume immunization programs.
United States
Pediatric hospitals consolidate immunization programs around combination vaccine formats to reduce injection burden. FDA Center for Biologics Evaluation and Research enforces stringent lot-release testing that shapes global quality benchmarks. Merck & Co., Inc. maintains distribution networks across North American cold-chain infrastructure.
China
Provincial public health mandates pull volume through domestic manufacturing scale as national immunization schedules expand. NMPA implements real-time temperature monitoring mandates with blockchain-verified chain-of-custody requirements. Shanghai Institute of Biological Products and Changchun Changsheng Life Sciences Limited scale output to serve tender allocations.
Japan
Ultra-low temperature distribution networks extend reach into community clinic settings previously excluded from live vaccine access. PMDA maintains stability data requirements that align with WHO prequalification standards. Biken anchors supply through established production protocols derived from Research Foundation for Microbial Diseases of Osaka University heritage.
South Korea
Equipment upgrades enable subcutaneous administration at peripheral health posts beyond metropolitan centers. MFDS governs licensure pathways for pediatric live viral products. Green Cross Corporation dominates public health channel supply through localized manufacturing scale.
India
CDSCO mandates local bridging studies for varicella vaccine licensure, creating regulatory barriers for foreign manufacturers. Community clinics favor single-dose presentations for inventory flexibility in resource-constrained settings. Keygen Vaccines represents domestic manufacturing capacity targeting national program inclusion.
Varicella Attenuated Live Vaccination Market Competitive Landscape
Capability concentration sits with established multinationals possessing integrated cold-chain infrastructure; scale advantage sits with domestic Chinese manufacturers leveraging accelerated NMPA pathways. The market structure reflects a bifurcated tiering between heritage innovators and emerging regional suppliers. Three archetypes dominate: combination vaccine specialists, monotherapy cost leaders, and distribution-integrated logistics players. Competitive moves center on regulatory pathway acceleration and provincial tender capture rather than direct product differentiation.
Within the heritage multinational tier, Merck & Co., Inc. and GlaxoSmithKline plc occupy positions shaped by decades of pediatric vaccine development. Shanghai Institute of Biological Products and Changchun Changsheng Life Sciences Limited exemplify the domestic Chinese archetype benefiting from NMPA accelerated review pathways. Green Cross Corporation represents the Asia-Pacific regional specialist model with concentrated public health channel access.
| Leading Market Players |
|---|
| Shanghai Institute of Biological Products |
| Biken (Research Foundation for Microbial Diseases of Osaka University) |
| Merck & Co., Inc. |
| Keygen Vaccines |
| BCHT (Beijing Chaoyang Biotechnology) |
| GlaxoSmithKline plc |
| Green Cross Corporation |
| Changchun Changsheng Life Sciences Limited |
| Takeda Pharmaceutical Company Limited |
| Others |
Pricing and Supply Chain Analysis
Shanghai's vaccine manufacturing cluster concentrates lyophilized varicella production capacity, translating into asymmetric pricing power for domestic suppliers serving China's provincial tender markets. Cold-chain distribution costs and MRC-5 cell substrate scarcity feed downstream margin compression for import-dependent competitors.
Pricing Analysis
Geographic price spreads between North American hospital procurement and Indian community clinic channels exceed threefold, reflecting cold-chain infrastructure gaps and tender aggregation scale. Three-tier pricing structure across premium combination vaccines, standard monotherapy, and economy single-dose presentations stratifies by certification tier and volume commitment. Pricing pressure stems from GlaxoSmithKline's recombinant zoster vaccine capturing adult shingles preference, compressing live attenuated margins. Pediatric hospitals demonstrate lowest price sensitivity due to formulary standardization protocols, while Indian community clinics operate at highest elasticity.
Supply Chain Analysis
Contract manufacturing for live viral vaccines concentrates with Biken in Japan, Green Cross Corporation in South Korea, and domestic Chinese producers under NMPA oversight. MRC-5 human diploid cell cultures, specialized lyophilization equipment, and ultra-low temperature storage units constitute critical input dependencies. Single-source vulnerability in cell substrate supply creates systemic batch release risk across multiple manufacturers simultaneously. Distribution runs through specialized cold-chain logistics providers with provincial tender fulfillment mandates in China and national immunization program allocation in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Varicella attenuated live vaccination sits in early-cycle expansion as national immunization schedules in China and India drive pediatric coverage penetration. Cold-chain infrastructure modernization and combination vaccine adoption create parallel growth vectors.
For Market Incumbents: Build regulatory moat through WHO prequalification investment and NMPA real-time temperature monitoring compliance. Secure MRC-5 cell substrate supply through captive bioreactor capacity or long-term supplier agreements to defend against recombinant zoster substitution. Accelerate quadrivalent measles-mumps-rubella-varicella combination development to capture hospital formulary unbundling trends. For New Entrants and Emerging Players: India's CDSCO local bridging study requirement represents the most penetrable entry point for foreign manufacturers establishing domestic clinical trial infrastructure. Pharmacy-based vaccination channels in the United States offer standing order bypass of traditional physician office inventory constraints. Partner with Indian contract research organizations to accelerate market entry timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory pathway acceleration favors scale players with integrated cold-chain logistics. Target acquisition archetype: regional specialists with provincial tender access and NMPA-approved manufacturing scale. Monitor NMPA domestic approval velocity as inflection signal for import displacement trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | NMPA accelerated review for domestically manufactured pediatric vaccines reshapes competitive access dynamics. |
| Manufacturing Scale-Up | Shanghai Institute of Biological Products expands lyophilized output to serve China's national immunization schedule expansion. |
| Combination Vaccine Development | Quadrivalent measles-mumps-rubella-varicella formulations capture metropolitan health department school-entry compliance programs. |
| Cold-Chain Infrastructure Partnership | IoT-enabled distribution networks with blockchain verification meet China's real-time temperature monitoring mandates. |
| Clinical Trial Advancement | Local bridging studies in India circumvent CDSCO import licensure delays for foreign manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Biologics Evaluation and Research filings, NMPA pediatric vaccine approval databases, WHO prequalification records, and ClinicalTrials.gov protocols. Drug development executives, regulatory affairs leads at multinational manufacturers, hospital formulary directors, and provincial immunization program managers provided qualitative input. Bottom-up demand modeling triangulates against top-down market sizing from customs trade data and national health expenditure statistics.
Forecast inputs incorporate product type segmentation across combination, single-dose, and multi-dose presentations; end-user channels spanning pediatric hospitals, community clinics, and pharmacy retail; administration route preferences; and distribution channel structures. CAGRs derive from regression analysis of historical volume trends against immunization schedule policy shifts and cold-chain infrastructure investment cycles. Patient population coverage targets and regional regulatory cluster adoption curves inform projection boundaries.
Practitioners should monitor NMPA domestic approval velocity, WHO prequalification backlog duration, and recombinant zoster vaccine prescription share for early signals of forecast revision triggers. Quarterly review of provincial tender allocation shifts in China and CDSCO licensing timeline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Critical Care Therapeutics Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market