
 Nikethamide Injection Market | 2026-2036
Nikethamide Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Nikethamide Injection Market Insights
Multi-source API procurement is realigning how nikethamide injection manufacturers secure active pharmaceutical ingredients. Jayson Pharmaceuticals Ltd. leverages backward integration into chemical synthesis to buffer against raw material volatility. Fresenius Kabi AG anchors its position through stringent European pharmacopeia compliance and hospital-grade manufacturing scale. Beijing Yongkang Pharmaceutical Co. LTD competes on cost-optimized batch production tailored to domestic tender contracts.
Nikethamide injection contains the respiratory stimulant nikethamide, typically formulated as a clear aqueous solution at concentrations between 250 mg/mL, administered parenterally to reverse acute respiratory depression or central nervous system depressant overdose. The compound functions by direct stimulation of the medullary respiratory center and indirect enhancement of chemoreceptor sensitivity to carbon dioxide. Intravenous administration dominates hospital emergency protocols for rapid onset, while ampoule packaging retains preference in institutional settings where single-dose integrity and sterility assurance outweigh unit-cost considerations. Pre-filled syringes are gaining traction in ambulatory surgical centers seeking to reduce medication preparation errors and streamline anesthesia recovery workflows.
FDA current good manufacturing practice enforcement and EMA pharmacovigilance reporting obligations for central nervous system stimulants shape batch release protocols and post-market surveillance burdens for nikethamide injection suppliers. India's CDSCO and China's NMPA impose distinct bioequivalence and stability testing requirements that fragment registration pathways across major production hubs. Stakeholders must monitor evolving respiratory therapy guidelines and regional tender pricing mechanisms to anticipate volume shifts between hospital formularies and alternative care settings.
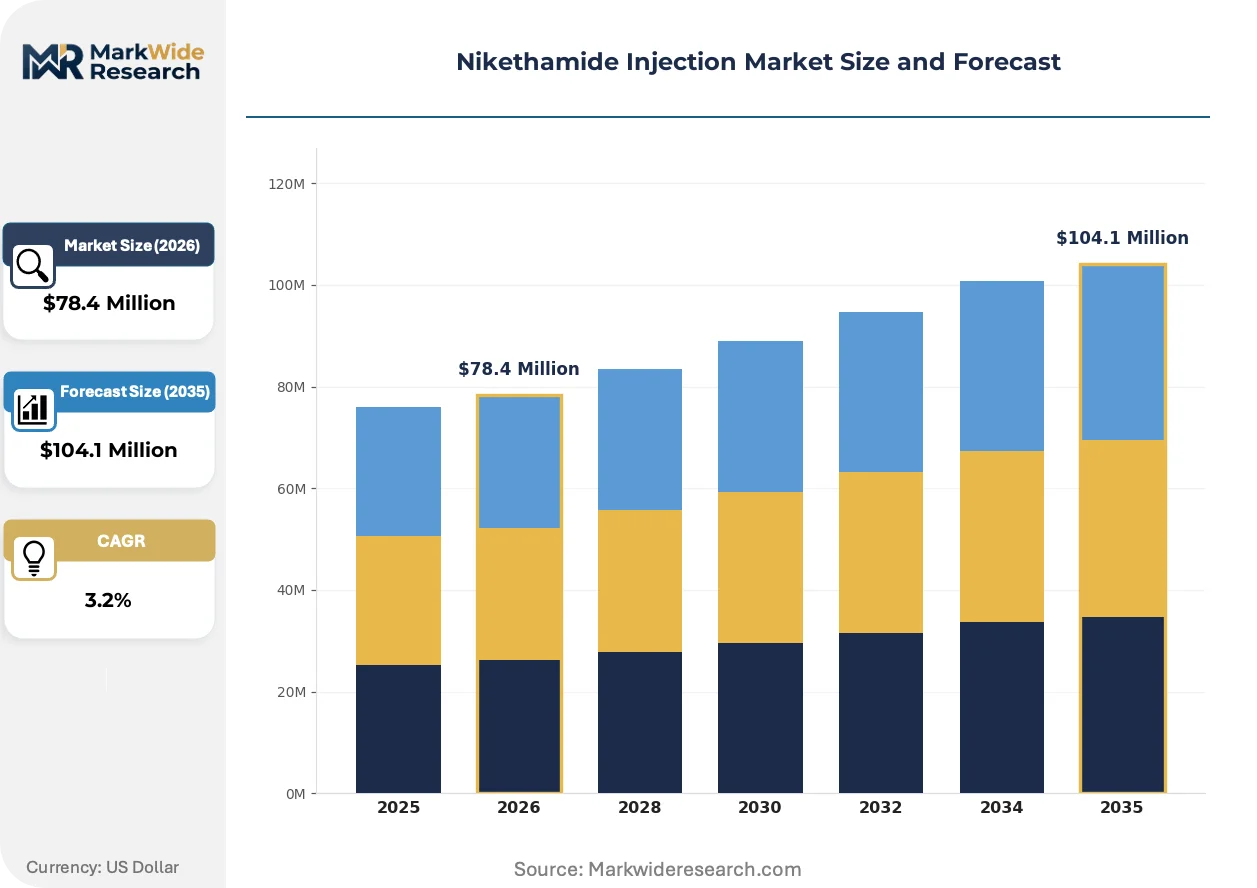
Market Dynamics
Hospital procurement of respiratory stimulants is accelerating in emerging economies, driven by expanding emergency medicine infrastructure and rising incidence of opioid-related respiratory depression requiring immediate pharmacological intervention.
Growth Catalysts
- Emergency Protocol Standardization:India's CDSCO is mandating nikethamide inclusion in tier-2 hospital emergency crash carts, expanding institutional volume commitments across state-level health networks.
- Pre-filled Syringe Adoption:Ambulatory surgical centers in China are converting from glass ampoules to polymer pre-filled formats, reducing medication errors and anesthesia recovery times.
- REACH Compliance Premium:European pharmacopeia alignment for parenteral stimulants is creating quality-tier differentiation that rewards manufacturers with EMA-certified batch release protocols.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production clusters in eastern China create single-source vulnerability for non-integrated injectable manufacturers.
- Naloxone Substitution Pressure:Opioid antagonist alternatives with superior safety profiles are displacing nikethamide in first-line overdose protocols across North American emergency departments.
- Stability Testing Burden:EMA pharmacovigilance requirements for central nervous system agents impose 24-month accelerated degradation studies that extend registration timelines.
Strategic Opportunities
- Sub-Saharan Hospital Networks:WHO essential medicines list inclusion creates tender pathways for nikethamide injection in Kenya, Nigeria, and Ethiopia as emergency respiratory care capacity expands.
- Cold Chain Bypass Formulations:Lyophilized powder presentations that eliminate refrigerated storage requirements are penetrating rural clinic distribution channels in India.
- Dual Carbon Alignment:China's NMPA is incentivizing domestic manufacturers with carbon-neutral production certifications for government procurement preference.
Industry Challenges
- Sterile Manufacturing Talent Scarcity:Aseptic processing specialists with parenteral stimulant experience command premium wages that compress margins for mid-scale producers.
- Legacy Equipment Retrofit Costs:Isolator technology upgrades required for FDA current good manufacturing practice compliance demand capital outlays exceeding $4 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nikethamide Injection Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $104.1 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous, Intramuscular, Subcutaneous, Oral End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Therapy Area: Respiratory Disorders, Cardiovascular Conditions, Neurological Disorders, Pain Management Packaging Type: Ampoules, Vials, Pre-filled Syringes, Bottles |
| Companies Covered | Jayson Pharmaceuticals Ltd., Imperia Lifesciences Pvt Ltd, Pharma Cure Laboratories, Beijing Yongkang Pharmaceutical Co. LTD, Tianjin Zhongmei Pharmaceutical Co., LTD, AdvaCare, Medriva, Fresenius Kabi AG, Jackson Laboratories Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nikethamide Injection Market Trends and Innovations
Pre-filled delivery systems and regulatory harmonization pressures are compressing traditional manufacturing advantages while opening new channel access routes for quality-certified suppliers.
Polymer pre-filled syringes with integrated needle safety systems are overtaking glass ampoules in institutional procurement specifications. European hospital purchasing consortiums now mandate single-dose ready-to-administer formats for emergency medications. This shift is compressing demand for conventional multi-dose vial presentations and rewarding manufacturers with blow-fill-seal integration capabilities.
EMA's tightened pharmacovigilance reporting for central nervous system stimulants is forcing batch-level serialization and real-time adverse event tracking. Manufacturers must now maintain 10-year retention of individual dose distribution records. Hospital formulary committees in Germany and France are prioritizing suppliers with demonstrated post-market surveillance infrastructure.
Centralized hospital purchasing through regional tender consortia is consolidating procurement decision-making in India and China. State-level health authorities in Maharashtra and Guangdong now negotiate multi-year volume commitments that displace fragmented distributor networks. Tier-3 city hospitals are gaining direct access to manufacturer pricing previously reserved for metropolitan medical centers.
Nikethamide Injection Market Segmentation
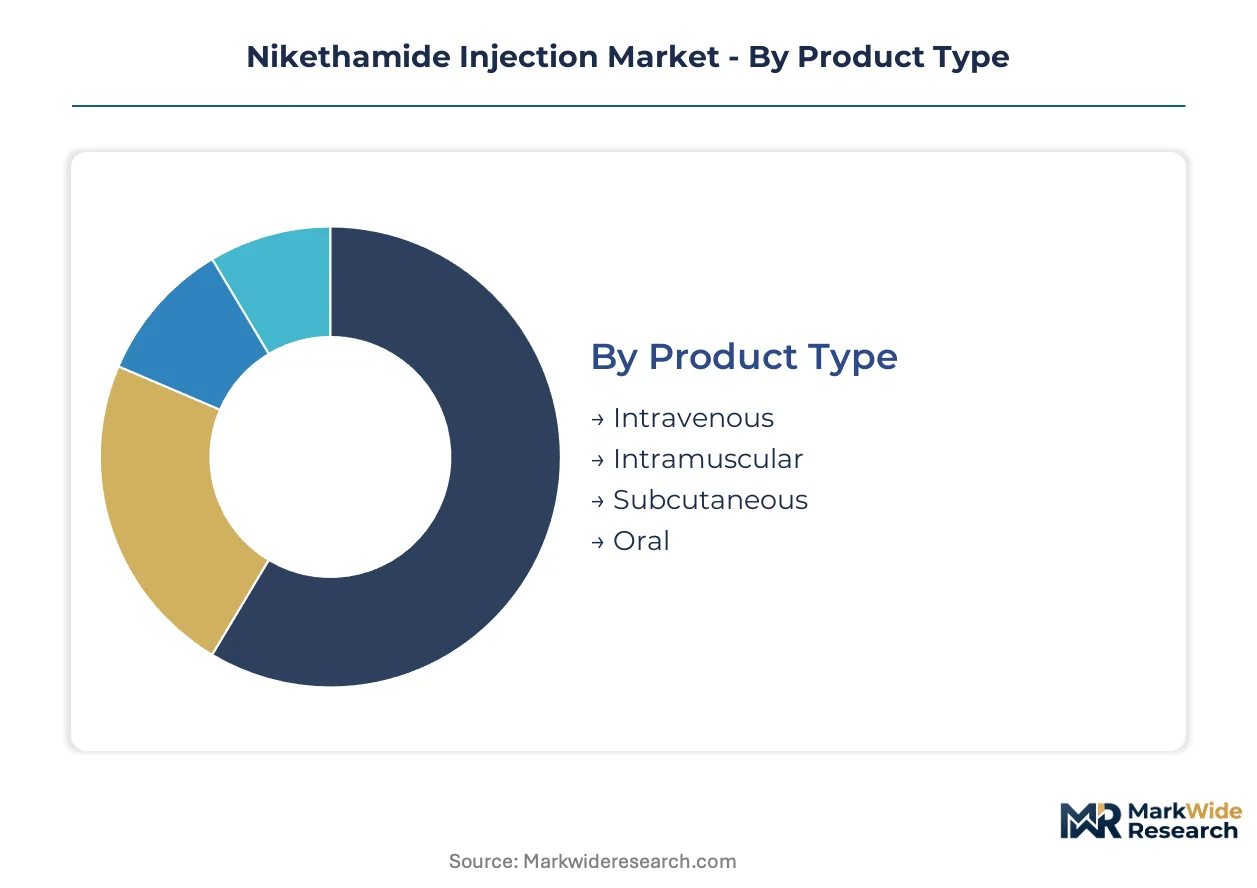
Nikethamide injection segmentation reveals how administration route, clinical setting, and packaging format each reshape procurement economics. Manufacturers align production capacity against these dimensions to capture volume commitments from hospital formularies and emergency medicine networks.
Product Type:
Volume concentrates in intravenous formats where rapid onset justifies premium pricing, while alternative routes serve cost-sensitive outpatient protocols.
- Intravenous:Direct injection into venous circulation achieves peak respiratory stimulation within 30-60 seconds. Emergency departments in India and China mandate this format for crash cart standardization, with CDSCO and NMPA both prioritizing IV nikethamide in tier-2 hospital procurement guidelines.
- Intramuscular:Sustained absorption through skeletal muscle depots extends therapeutic duration for patients lacking immediate venous access. Rural clinics across sub-Saharan Africa favor this route where IV infrastructure remains limited, though onset delay reduces adoption in critical care settings.
- Subcutaneous:Absorption through subcutaneous tissue layers offers intermediate onset for controlled respiratory support. Home care providers in European markets with established palliative protocols occasionally deploy this format.
- Oral:Gastrointestinal absorption delivers nikethamide through non-parenteral pathways, restricted to jurisdictions with specific regulatory waivers for respiratory stimulant alternatives.
Today's leader: Intravenous. Tomorrow's challenger: Intramuscular in resource-limited geographies.
End User:
Procurement authority concentrates in institutional purchasers with centralized tender mechanisms, fragmenting across ambulatory and home-based alternatives.
- Hospitals:Inpatient facilities with emergency medicine accreditation dominate volume through multi-year supply agreements. Maharashtra state health networks in India negotiate directly with manufacturers, bypassing distributor markups previously standard in metropolitan procurement.
- Clinics:Primary care and specialty outpatient settings manage stable respiratory depression cases without full emergency infrastructure. China's county-level medical institutions increasingly stock nikethamide as opioid-related presentations rise.
- Home Care:Palliative and chronic respiratory support in domestic settings requires patient or caregiver administration training. European reimbursement frameworks for home-based respiratory stimulants remain fragmented across national health systems.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritize pre-filled delivery systems to reduce anesthesia recovery medication errors. Guangdong province ASCs converted 40% of respiratory stimulant procurement to polymer syringe formats.
Hospital procurement anchors current revenue; ambulatory surgical centers are climbing the fastest as pre-filled formats penetrate outpatient surgery protocols.
Therapy Area:
Clinical application breadth spans acute intervention through chronic management, with regulatory scrutiny varying by indication risk profile.
- Respiratory Disorders:Direct medullary center stimulation reverses acute respiratory failure from drug overdose or central nervous system depression. WHO essential medicines list inclusion drives tender access across Kenya, Nigeria, and Ethiopia as emergency respiratory capacity expands.
- Cardiovascular Conditions:Adjunctive circulatory support in shock states leverages nikethamide's mild pressor effects. German hospital formularies restrict this application to secondary indications given superior agent availability.
- Neurological Disorders:Consciousness restoration in post-anesthetic or toxic encephalopathy states requires careful titration. EMA pharmacovigilance reporting obligations intensify for neurological applications given seizure threshold concerns.
- Pain Management:Opioid-induced respiratory depression reversal faces substitution pressure from naloxone in North American protocols, though nikethamide retains cost advantages in emerging market formularies.
Respiratory disorders command absolute volume; pain management faces steepest competitive headwinds from antagonist alternatives.
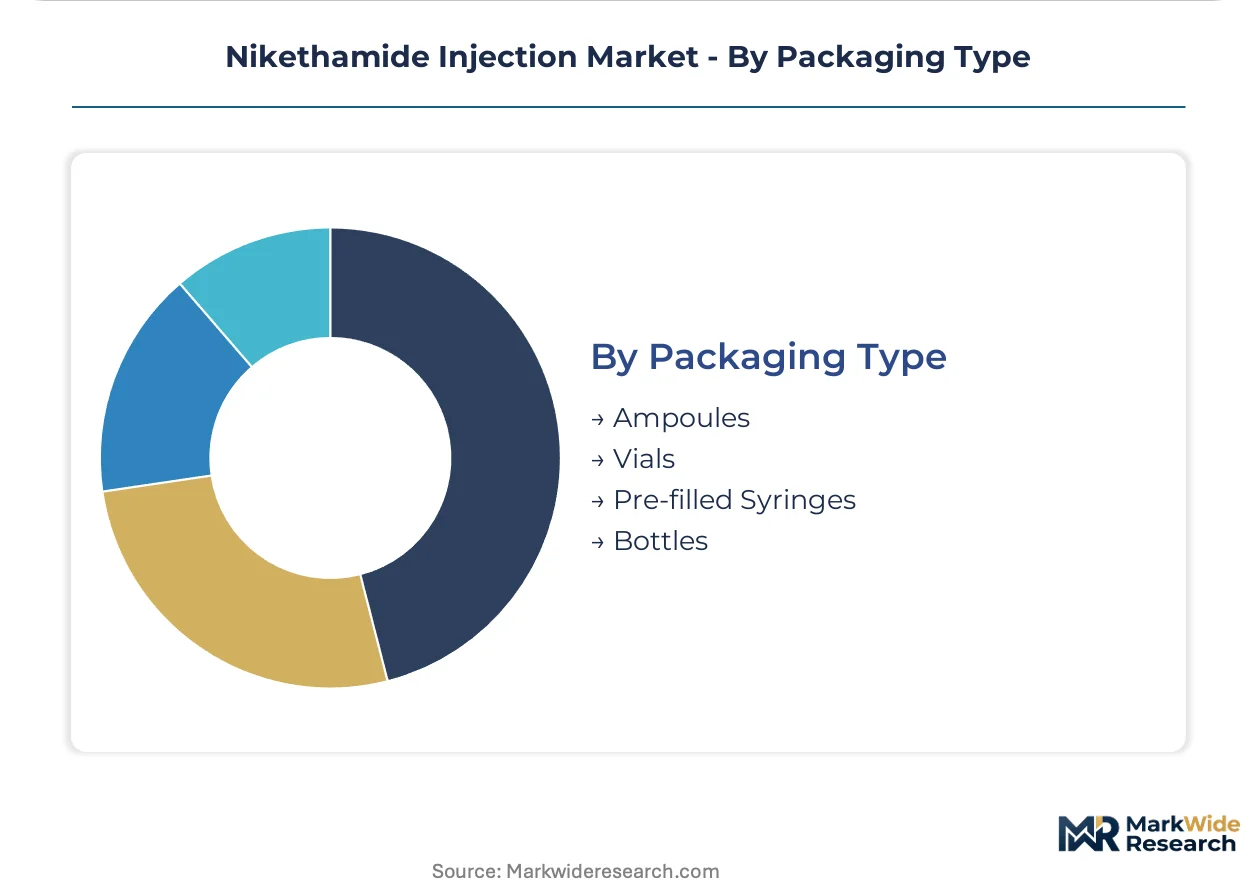
Packaging Type:
Format selection determines sterility assurance, preparation error rates, and cold chain requirements across distribution channels.
- Ampoules:Glass single-dose containers with scored necks dominate institutional procurement where cost minimization outweighs convenience. India's government hospitals continue specifying ampoules for emergency medicine stockpiles despite handling fragility.
- Vials:Multi-dose presentations with septum access reduce per-dose packaging costs for high-volume users. Contamination risk between withdrawals limits adoption in strict aseptic protocols.
- Pre-filled Syringes:Polymer or glass syringes with integrated needle safety systems eliminate preparation steps. European purchasing consortiums now mandate this format for emergency medications, compressing demand for conventional alternatives.
- Bottles:Bulk liquid presentations for compounding pharmacies enable customized concentration preparation. Regulatory complexity restricts this format to specialized manufacturing licensees.
Ampoules retain installed base; pre-filled syringes are gaining share fastest as error reduction drives institutional specification changes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting nikethamide injection production toward jurisdictions with streamlined bioequivalence pathways and lower cost-of-compliance structures. Manufacturers migrate capacity to exploit gaps between EMA pharmacovigilance burdens and emerging market registration efficiency.
India
Emergency medicine infrastructure expansion and state-level hospital procurement consolidation drive volume. CDSCO mandates nikethamide inclusion in tier-2 hospital crash carts, creating institutional demand anchors. Maharashtra state health networks negotiate direct manufacturer contracts, bypassing distributor layers previously entrenched in metropolitan supply chains.
China
Domestic production scales to serve regional hospital networks as opioid-related respiratory presentations climb. NMPA incentivizes carbon-neutral production certifications for government procurement preference. Guangdong province ambulatory surgical centers convert procurement to polymer pre-filled syringe formats, compressing traditional ampoule demand.
Germany
EMA-certified batch release protocols create quality-tier differentiation rewarding European pharmacopeia alignment. Hospital formulary committees prioritize suppliers with demonstrated post-market surveillance infrastructure. Isolator technology upgrades for current good manufacturing practice compliance demand capital outlays reshaping competitive entry.
United States
FDA enforcement of current good manufacturing practice standards tightens sterile manufacturing requirements. Naloxone substitution pressure displaces nikethamide in first-line overdose protocols, constraining volume growth. Aseptic processing specialists command premium wages, compressing margins for mid-scale producers lacking backward integration.
Brazil
WHO essential medicines list inclusion creates tender pathways as emergency respiratory care capacity expands. ANVISA bioequivalence requirements fragment registration timelines relative to Asian manufacturing hubs. Southeast hospital networks in São Paulo state anchor regional procurement consolidation.
Nikethamide Injection Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cost-optimized batch production and pre-filled format specialization. The supplier base stratifies across integrated API manufacturers, contract sterile injectable specialists, and regional tender-focused fabricators. Three archetypes dominate: backward-integrated chemical synthesis operations, European pharmacopeia-compliant hospital-grade manufacturers, and domestic-scale producers serving government procurement channels. Competitive moves concentrate on isolator technology upgrades for regulatory compliance and polymer pre-filled syringe capacity expansion for ambulatory surgical center penetration.
Among the named participants, Jayson Pharmaceuticals Ltd. and Beijing Yongkang Pharmaceutical Co. LTD occupy positions within the Asia-Pacific manufacturing cluster, while Fresenius Kabi AG anchors the European compliance tier. These three exemplify the geographic and regulatory segmentation shaping competitive positioning: Indian and Chinese producers leverage cost-optimized production for emerging market tenders, while German-based operations capture premium positioning through EMA-certified infrastructure.
| Leading Market Players |
|---|
| Jayson Pharmaceuticals Ltd. |
| Imperia Lifesciences Pvt Ltd |
| Pharma Cure Laboratories |
| Beijing Yongkang Pharmaceutical Co. LTD |
| Tianjin Zhongmei Pharmaceutical Co., LTD |
| AdvaCare |
| Medriva |
| Fresenius Kabi AG |
| Jackson Laboratories Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
State-level hospital procurement consortia in Maharashtra and Guangdong concentrate purchasing power, compressing distributor margins and forcing manufacturers toward direct-contract pricing models with volume-scaled rebates.
Pricing Analysis
Distributor markups of 15-25% in fragmented Indian supply chains face elimination as CDSCO-mandated tender consolidation enables direct manufacturer negotiation. Three-tier pricing structure across EMA-certified, pharmacopeia-compliant, and domestic-standard grades differentiates hospital formulary access. Cost compression in standard-tier injectables intensifies as Chinese producers scale batch output for government procurement. Tier-2 city hospitals in India exhibit highest price sensitivity; German academic medical centers demonstrate lowest, prioritizing batch traceability over unit cost.
Supply Chain Analysis
India's PLI scheme for pharmaceutical manufacturing and China's NMPA domestic-content preferences are reshaping API sourcing toward captive production. Active pharmaceutical ingredient supply draws from eastern China, western India, and limited European fermentation capacity. Nikethamide precursor chemicals, sterile packaging components, and isolator equipment feed downstream formulation. Single-source vulnerability in Chinese API clusters threatens non-integrated injectable manufacturers. Distribution runs through regional hospital purchasing consortia bypassing legacy wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA pharmacovigilance compliance costs in Europe run 40-60% above CDSCO registration expenses in India, creating manufacturing arbitrage for export-oriented producers.
For Market Incumbents: Deepen backward integration into nikethamide chemical synthesis to buffer against API price volatility from eastern Chinese suppliers. Expand isolator-equipped production lines in India to capture CDSCO-mandated tier-2 hospital volume while maintaining EMA-certified batch release capability for European premium positioning. Naloxone substitution in North American protocols threatens volume; counter with lyophilized powder development for cold-chain-limited geographies. For New Entrants and Emerging Players: Launch via direct tender participation in Sub-Saharan WHO essential medicines programs, bypassing established distributor relationships. Kenya, Nigeria, and Ethiopia offer lowest competitive density for respiratory stimulant procurement. Target intramuscular format specialization where IV infrastructure remains limited. Pre-filled syringe capacity investment unlocks Chinese ambulatory surgical center conversion demand. For Investors and Strategic Acquirers: Contract sterile injectable manufacturers with EMA-certified infrastructure are the most active acquirer targets in this space as quality-tier consolidation accelerates. Five-to-ten year viability hinges on regulatory moat durability and pre-filled format transition completion. Monitor CDSCO tier-2 hospital procurement mandate expansion as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Upgrade | FDA current good manufacturing practice enforcement demands capital deployment exceeding $4 million per line. |
| Lyophilized Powder Development | Cold chain elimination penetrates rural Indian clinics and Sub-Saharan distribution channels. |
| Pre-filled Syringe Capacity Expansion | Guangdong province ASCs converted 40% of respiratory stimulant procurement to polymer formats. |
| EMA Batch Release Certification | German hospital formulary committees prioritize suppliers with demonstrated post-market surveillance infrastructure. |
| CDSCO Tier-2 Hospital Direct Contracting | Maharashtra state health networks bypass distributor markups through centralized manufacturer negotiation. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with formulary directors, sterile manufacturing operations heads, regulatory affairs leads at CDSCO and NMPA, and hospital purchasing committee members combined with secondary validation against FDA 483 inspection records, EMA pharmacovigilance databases, CDSCO tender announcements, and WHO essential medicines procurement reports. Triangulation between demand-side volume commitments and supply-side capacity expansion announcements ensures cross-verified baseline calibration.
Input-output matrices map nikethamide injection demand across administration route, packaging format, end-user facility tier, and regional regulatory cluster against API synthesis capacity, sterile fill-finish throughput, and distribution channel evolution throughout the forecast period. CAGRs derive from regression analysis of historical tender volume data and projected hospital infrastructure expansion. Forecast inputs incorporate CDSCO tier-2 mandate implementation timelines and NMPA carbon-neutral certification incentive uptake rates.
Several conditions sit outside the modeled scope, including specific clinical trial outcomes for nikethamide neurological applications, unforeseen regulatory reclassification of respiratory stimulants, and abrupt API supply disruptions from geopolitical events. Forecasts reflect documented assumptions regarding tender pricing stability and sterile manufacturing talent availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market