
 Metal Foil Tapes Market | 2026-2036
Metal Foil Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Foil Tapes Market Intelligence
Multi-source procurement for acrylic and silicone adhesive chemistries is realigning how tier-one buyers qualify metal foil tape suppliers. 3M leverages its polymer science infrastructure to control specification-grade formulations across aerospace and electrical insulation channels. Tesa SE anchors European automotive demand through OEM-certified bonding tapes that meet thermal cycling requirements. Henkel competes on hot-melt adhesive platforms optimized for high-speed HVAC fabrication lines.
Metal foil tapes are pressure-sensitive adhesive laminates constructed from aluminum, copper, nickel, or stainless steel substrates ranging from 0.025 mm to 0.15 mm thickness, engineered for thermal conductivity, electrical shielding, and environmental sealing in industrial assemblies. The aluminum foil category dominates volume due to its cost-positioning in building services and appliance manufacturing, while copper foil commands premium positioning in electromagnetic interference applications for electronics and defense. Aerospace and electrical insulation segments are outpacing HVAC in value growth, driven by material certification requirements and performance warranties that lock in supplier relationships.
The U.S. EPA refrigerant regulations and the EU F-Gas Regulation are tightening duct-sealing standards and accelerating specification upgrades for low-permeability foil tape systems. REACH compliance in Europe and OSHA workplace exposure limits in the United States constrain solvent-based adhesive formulations, pushing investment toward waterborne acrylic and UV-curable silicone platforms. Stakeholders must monitor adhesive chemistry transitions and certification bottlenecks as regulatory thresholds tighten across multiple jurisdictions.
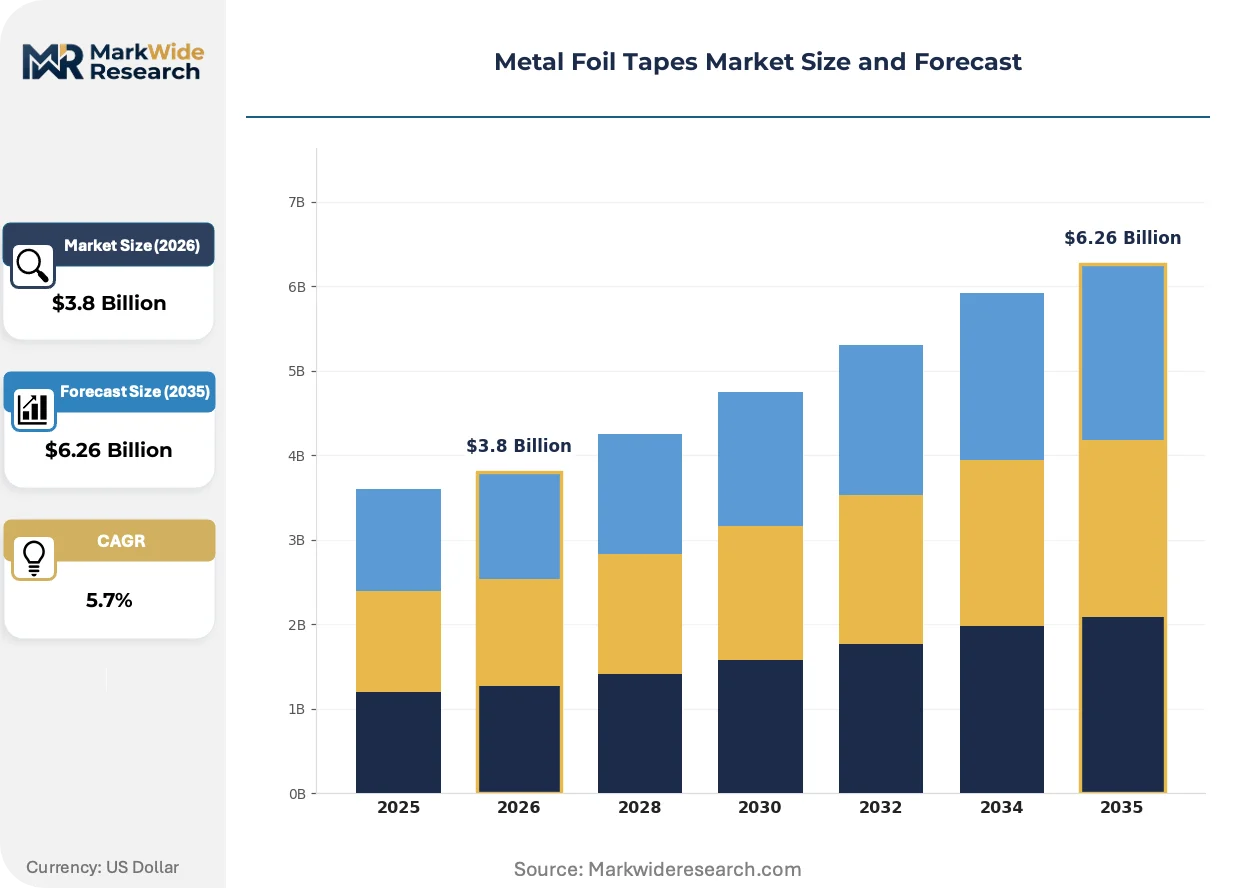
Market Dynamics
Adhesive chemistry transitions are restructuring supplier qualification protocols across aerospace, automotive, and HVAC procurement channels. Buyers now require dual-source validation for waterborne acrylic and UV-curable silicone platforms, compressing incumbent solvent-based adhesive margins.
Growth Catalysts
- AIM Act refrigerant phasedown:The U.S. EPA's hydrofluorocarbon reduction timeline is forcing HVAC system retrofits that specify low-permeability aluminum foil tape sealing for leak prevention.
- Aerospace thermal management:Copper foil tape procurement for satellite and aircraft EMI shielding is accelerating as OEMs redesign avionics packaging for higher power densities.
- German automotive bonding:OEM-certified foil tape grades are displacing mechanical fasteners in bonded assemblies subject to thermal cycling stress testing.
Market Restraints
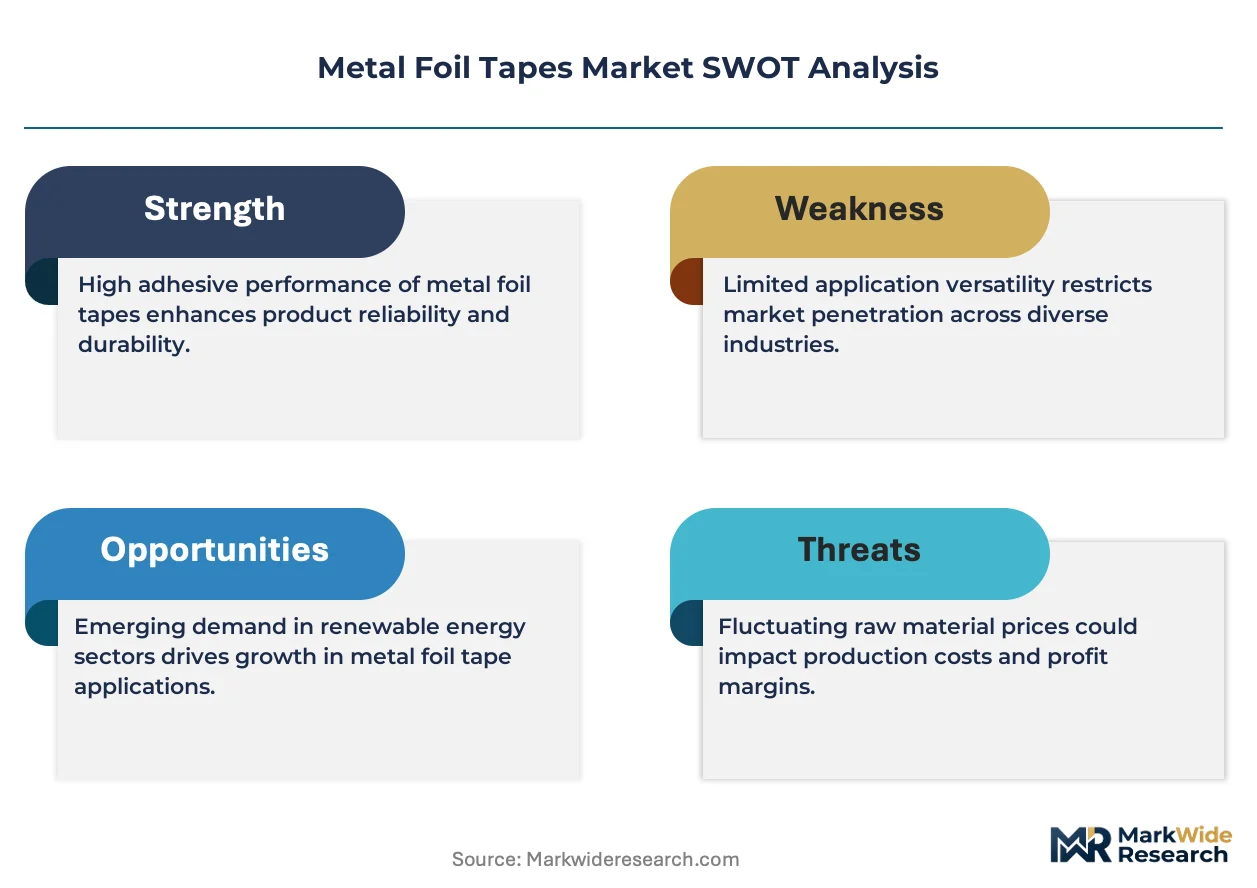
- Petrochemical feedstock volatility:Acrylic monomer and silicone precursor costs swing with crude oil and natural gas pricing, destabilizing adhesive formulation economics.
- Asian substrate concentration:Rolled aluminum and copper foil supply clusters in Chinese and South Korean smelter networks, exposing buyers to export control and logistics disruption risks.
- REACH solvent restrictions:ECHA's tightening VOC thresholds for toluene and xylene-based adhesives are forcing capital-intensive production line conversions at European tape laminators.
Strategic Opportunities
- India industrial HVAC expansion:BIS certification requirements for duct sealing materials are creating first-mover advantages for foil tape suppliers establishing local lamination capacity.
- Battery pack thermal interface:Nickel and aluminum foil tapes for EV cell-to-cell heat spreading represent an emerging specification channel outside traditional electrical insulation.
- EU F-Gas Regulation:The 2024-2030 phasedown schedule is mandating hermetic sealing standards that favor certified low-permeability tape systems over conventional cloth-backed alternatives.
Industry Challenges
- Adhesive formulation talent scarcity:Polymer chemists with pressure-sensitive adhesive expertise are concentrated at legacy tape manufacturers, constraining new entrant R&D velocity.
- Aerospace certification timelines:FAA and EASA material qualification cycles for flame-smoke-toxicity specifications extend 18-36 months, locking working capital in pre-revenue development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Foil Tapes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Foil, Copper Foil, Nickel Foil, Stainless Steel Foil Application: Electrical Insulation, HVAC, Automotive, Aerospace Thickness: Thin, Medium, Thick, Extra Thick Adhesive Type: Acrylic, Rubber, Silicone, Hot Melt |
| Companies Covered | 3M, Avery Dennison, Tesa SE, Nitto Denko Corporation, Saint-Gobain, Intertape Polymer Group, Henkel, Scapa Group, Shurtape Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Foil Tapes Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry mandates are converging to redefine performance benchmarks across metal foil tape specifications. Suppliers are racing to validate next-generation adhesive platforms before certification windows close.
Nanoparticle-reinforced acrylic adhesives are absorbing thermal stress in aerospace and electronics applications where traditional rubber-based chemistries fail cycling tests. Tier-one aircraft manufacturers are qualifying these formulations for wing ice protection and avionics shielding. The shift is absorbing margin from commodity tape producers unable to fund polymer science infrastructure.
The EU F-Gas Regulation's tightening leak-rate thresholds are compressing duct-sealing specifications toward laminated foil systems with quantified permeability ratings. HVAC contractors in Germany and France now face mandatory documentation of tape performance under pressure testing. This regulatory compression is displacing uncoated foil and cloth-backed tape from premium installation segments.
Consolidated procurement at multi-site facility operators is compressing distributor margins and favoring direct manufacturer relationships with documented technical support. Industrial buyers in the U.S. Gulf Coast petrochemical corridor are unbundling tape supply from MRO distributors to secure volume pricing and application engineering. The channel shift is most visible in Texas and Louisiana process industries where maintenance standardization programs mandate single-source tape specifications.
Metal Foil Tapes Market Segmentation
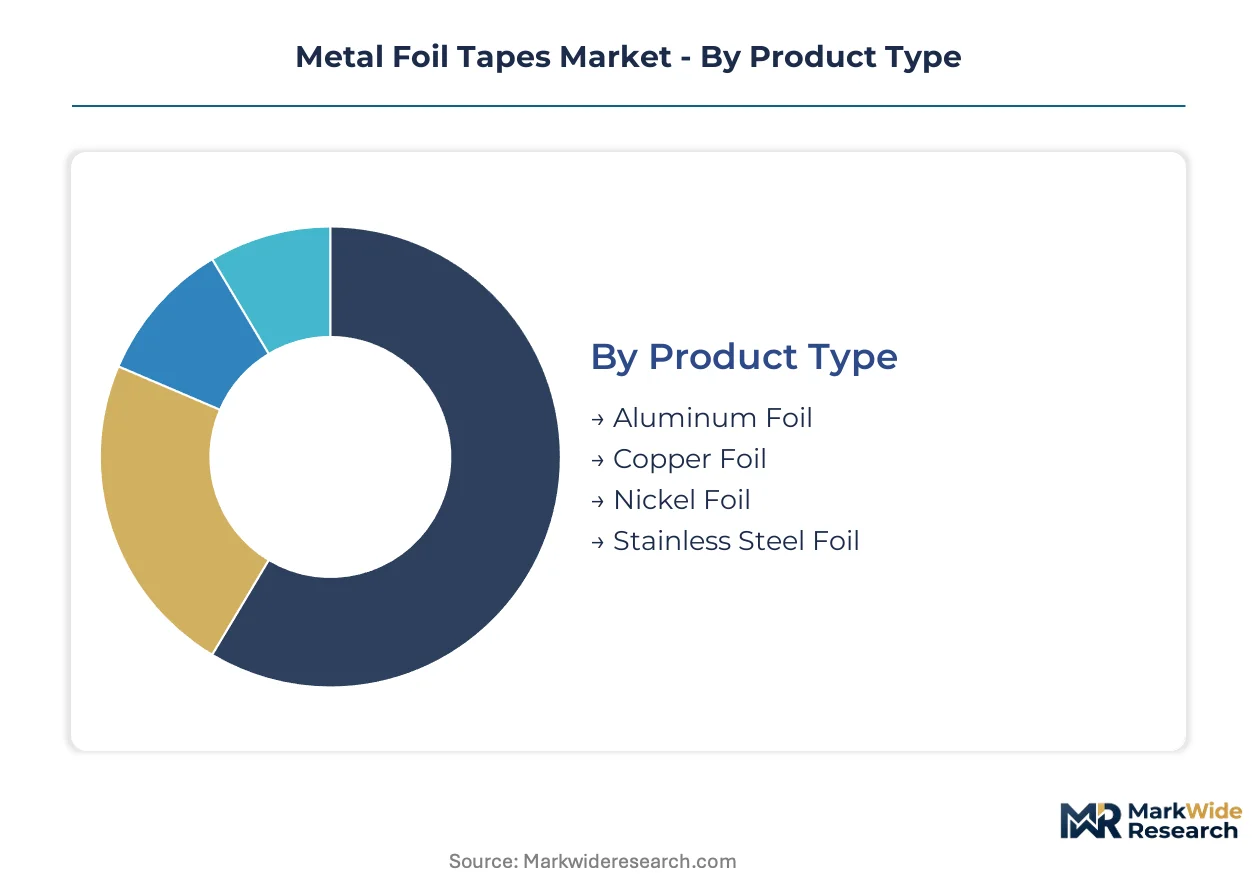
Metal foil tape procurement splits sharply between commodity building materials and certified aerospace-grade systems. Specification requirements diverge on thermal conductivity thresholds, flame-smoke-toxicity ratings, and adhesive chemistry compliance, creating parallel demand channels with minimal supplier overlap.
Product Type:
Cost positioning and conductivity specifications separate buyers across metal substrate categories.
- Aluminum Foil:Lightweight substrate with oxide-resistant surface treatment dominates HVAC duct sealing and appliance manufacturing. Demand concentrates in U.S. Gulf Coast petrochemical facilities where maintenance standardization programs specify single-source aluminum tape for corrosion protection under insulation.
- Copper Foil:High electrical conductivity substrate with EMI shielding effectiveness exceeding 80 dB commands premium positioning in satellite avionics packaging. German automotive OEMs are qualifying copper foil for battery module grounding as EV power densities escalate thermal management requirements.
- Nickel Foil:Corrosion-resistant alloy substrate withstands extreme thermal cycling in turbine engine compartments and fuel cell assemblies.
- Stainless Steel Foil:300-series austenitic grades serve cryogenic insulation and chemical processing environments where aluminum fails.
Volume sits with aluminum foil; growth tilts toward copper foil.
Application:
End-use certification requirements stratify procurement from commodity construction to aerospace qualification cycles.
- HVAC:Low-permeability sealing systems for ductwork and refrigeration lines. The U.S. EPA's AIM Act refrigerant phasedown is accelerating specification upgrades across commercial retrofit contractors in Texas and California.
- Aerospace:Flame-smoke-toxicity certified laminates for thermal management and EMI shielding. FAA material qualification cycles extending 18-36 months lock supplier relationships through performance warranties.
- Electrical Insulation:Dielectric barrier tapes for transformer winding and cable splicing in utility infrastructure.
- Automotive:OEM-certified bonding tapes displacing mechanical fasteners in bonded assemblies subject to thermal cycling stress testing.
Revenue concentrates in aerospace; expansion accelerates fastest in automotive electrification.
Thickness:
Mechanical handling and thermal mass requirements determine gauge selection across installation environments.
- Thin:Sub-0.05 mm gauges conform to complex geometries in electronics miniaturization and flexible circuit shielding.
- Medium:0.05-0.10 mm range balances tear resistance with hand-tearability for field HVAC applications.
- Thick:0.10-0.15 mm substrates provide structural rigidity for heavy-duty duct reinforcement and vibration damping.
- Extra Thick:Above 0.15 mm gauges serve cryogenic pipe insulation and industrial furnace lining where mechanical protection dominates.
Shipments favor medium gauges; specification intensity climbs with thin substrates.
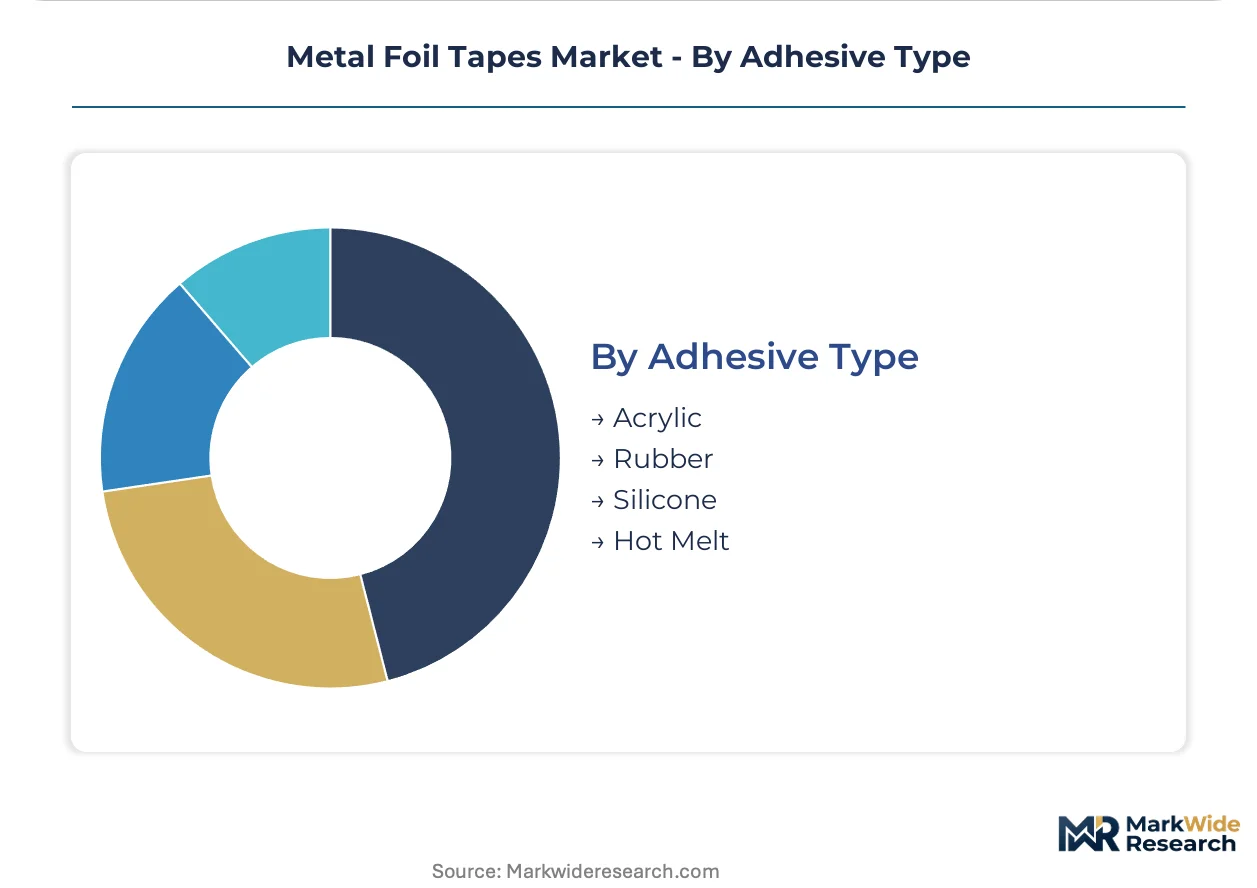
Adhesive Type:
Regulatory chemistry mandates and service temperature ranges are restructuring formulation procurement.
- Acrylic:Waterborne and solvent platforms offering UV resistance and plasticizer stability. REACH VOC restrictions are forcing European laminators toward waterborne systems.
- Silicone:High-temperature stability to 260°C with clean removal characteristics. UV-curable silicone platforms are gaining qualification for aerospace thermal cycling applications.
- Rubber:Natural and synthetic elastomer bases with aggressive initial tack for cold-weather HVAC installation.
- Hot Melt:Thermoplastic formulations optimized for high-speed lamination lines in commodity tape production.
Volume remains with rubber; chemistry transition favors silicone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rolled aluminum and copper substrate production clusters in Chinese and South Korean smelter networks anchor supply-side geography, while specification demand concentrates in German automotive corridors, U.S. Gulf Coast petrochemical facilities, and Indian industrial HVAC markets.
United States
HVAC retrofit contractors in Texas and California are accelerating procurement of low-permeability aluminum foil tape systems. The EPA's AIM Act hydrofluorocarbon phasedown mandates hermetic duct sealing standards that displace conventional cloth-backed alternatives. Houston's petrochemical maintenance standardization programs specify single-source aluminum tape specifications for corrosion protection under insulation.
Germany
Automotive OEMs in Stuttgart and Munich are qualifying copper foil tape grades for battery module grounding and bonded assembly applications. The EU F-Gas Regulation's 2024-2030 leak-rate thresholds compress duct-sealing specifications toward certified laminated foil systems. Bavarian industrial contractors now face mandatory documentation of tape permeability ratings under pressure testing protocols.
China
Rolled metal substrate production concentrates in Jiangsu and Shandong smelter networks serving domestic HVAC and electronics manufacturing. The country's dual carbon goals are tightening energy efficiency standards for building services that favor high-performance sealing materials. Shanghai's electronics corridor is absorbing copper foil tape volumes for flexible circuit shielding and thermal interface applications.
India
Industrial HVAC expansion in Maharashtra and Gujarat is creating specification windows for BIS-certified duct sealing materials. The Bureau of Indian Standards certification requirements for building services materials favor suppliers establishing local lamination capacity. Mumbai's commercial construction sector is specifying imported aluminum foil tape grades for large-scale retrofit programs.
South Korea
Electronics manufacturing clusters in Gyeonggi Province are driving copper foil tape procurement for EMI shielding in display and semiconductor packaging. The Ministry of Environment's VOC regulations are accelerating adhesive chemistry transitions toward waterborne acrylic platforms. Seoul's aerospace supply base is qualifying nickel foil laminates for satellite thermal management systems.
Metal Foil Tapes Market Key Industry Players
Capacity expansion dominates the current landscape as incumbent laminators add waterborne acrylic and UV-curable silicone production lines to meet REACH and OSHA chemistry mandates. The vendor base stratifies into three tiers: multinational polymer science conglomerates with aerospace certification infrastructure, regional automotive specialists with OEM-approved bonding tape portfolios, and commodity HVAC fabricators competing on high-speed lamination throughput. Strategic archetypes include specification-grade formulators, automotive-certified bonding specialists, and scale-driven commodity producers. M&A activity and geographic expansion into Indian BIS-certified markets represent the dominant competitive vectors.
Within the multinational specification-grade tier, 3M and Tesa SE occupy positions anchored by polymer science infrastructure and OEM certification relationships. Henkel exemplifies the adhesive chemistry specialist archetype with hot-melt platform expertise. Among Asia-Pacific fabricators, Nitto Denko Corporation represents the electronics-focused EMI shielding specialist. These companies illustrate how certification timelines and regulatory chemistry transitions are concentrating procurement relationships with laminators possessing in-house formulation capabilities and multi-jurisdiction compliance infrastructure.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| Tesa SE |
| Nitto Denko Corporation |
| Saint-Gobain |
| Intertape Polymer Group |
| Henkel |
| Scapa Group |
| Shurtape Technologies |
| Others |
Cost & Logistics Intelligence
LME aluminum and copper price indices cascade through metal foil tape supply chains, compressing margins at commodity laminators while specification-grade producers pass through alloy cost volatility via long-term aerospace and automotive contracts. This raw-material transmission mechanism stratifies pricing power between certified formulators with polymer science infrastructure and high-speed commodity fabricators competing on lamination throughput.
Pricing Analysis
Warranty-backed performance guarantees separate premium specification-grade tape from unbundled commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: aerospace-grade laminates with FAA flame-smoke-toxicity ratings command substantial premiums over HVAC commodity rolls. Price differentiation hinges on adhesive chemistry compliance and thermal cycling warranty coverage. Cost compression in commodity aluminum foil segments is intensifying because REACH solvent restrictions force capital-intensive production line conversions. Commercial retrofit contractors in Texas and California exhibit highest price sensitivity; satellite avionics OEMs demonstrate lowest.
Supply Chain Analysis
India's BIS certification requirements for duct sealing materials are reshaping sourcing decisions among HVAC contractors establishing local lamination partnerships. Rolled aluminum substrate production concentrates in Chinese and South Korean smelter networks; copper foil supply clusters in Jiangsu and Gyeonggi Province mill complexes. Acrylic monomer and silicone precursor feedstocks draw from petrochemical corridors in the U.S. Gulf Coast and Rotterdam. Single-source vulnerability in Chinese rolled metal supply exposes buyers to export control disruptions. Distribution runs through direct manufacturer relationships with industrial facility operators and MRO distributor networks serving fragmented contractor bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal foil tapes market functions as a cost-of-compliance story where REACH VOC thresholds and FAA certification timelines erect formidable barriers to entry, entrenching laminators with existing polymer science infrastructure and multi-jurisdiction regulatory expertise.
For Market Incumbents: Extend certification coverage into emerging adhesive chemistry platforms before qualification windows close. Incumbent laminators should deepen backward integration into waterborne acrylic formulation capacity to defend margin position against commodity competitors facing REACH-mandated capital expenditures. Aerospace material qualification cycles extending 18-36 months lock supplier relationships; incumbents must accelerate UV-curable silicone validation to preempt new entrant disruption in satellite thermal management segments.
For New Entrants and Emerging Players: Mid-tier automotive suppliers in India seeking BIS-certified bonding tapes for electrification programs represent the most penetrable buyer archetype. New entrants should establish local lamination capacity in Maharashtra and Gujarat to capture industrial HVAC expansion. A technical-service-led go-to-market approach—embedding application engineers with contractor specification teams—overcomes incumbent distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European tape laminators facing REACH conversion costs but possessing intact OEM certification relationships. Long-term viability across the analysis window rests on adhesive chemistry transition execution and aerospace qualification pipeline depth. Acquisition targets should demonstrate in-house polymer formulation capabilities rather than outsourced adhesive supply. The signal to watch is EASA acceleration of flame-smoke-toxicity specification updates, which would compress certification timelines and favor incumbent formulators with pre-validated platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Chemistry Transition | Waterborne acrylic and UV-curable silicone validation locks in REACH-compliant supply positions against solvent-based competitors. |
| Aerospace Certification Investment | FAA and EASA flame-smoke-toxicity qualification cycles secure long-term supplier relationships through performance warranties. |
| Geographic Capacity Expansion | Local lamination facilities in India satisfy BIS certification requirements for industrial HVAC duct sealing materials. |
| Backward Integration | In-house polymer science infrastructure controls specification-grade formulation economics across thermal cycling applications. |
| Direct Channel Development | Manufacturer relationships with multi-site facility operators compress distributor margins and capture specification influence. |
Research Approach
Trade flow databases, customs records, and SEC filings from publicly traded adhesive and tape manufacturers formed the secondary backbone of this analysis. Primary interviews with procurement leads at HVAC contractors, aerospace material qualification engineers, and automotive bonding tape specification managers combined with secondary validation to construct demand estimates. Bottom-up triangulation across end-use consumption patterns and top-down reconciliation against rolled metal substrate production data ensured cross-verified volume and value outputs.
Historical trendline analysis of aluminum and copper price indices, adhesive formulation cost structures, and certification timeline distributions informed the projection framework. Segmentation modeling captured metal substrate type, adhesive chemistry platform, end-use application, and regional regulatory cluster variations across the projection horizon. CAGRs were derived from regression-adjusted growth rates applied to base-year market sizing, incorporating EPA AIM Act implementation schedules and EU F-Gas Regulation phasedown milestones as structural demand shifters.
Revisions become necessary when petrochemical feedstock volatility exceeds historical bands, REACH enforcement intensity diverges from announced thresholds, or aerospace OEMs accelerate material qualification timelines beyond modeled distributions. Forecasts reflect assumptions regarding regulatory implementation consistency and certification backlog clearance rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tape Dispenser Market
Tapes
High Bond Tape Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Umbilical Tapes Market
Tapes
Flocking Tape Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Splicing Tapes Market
Tapes
Moisture Barrier Tapes Market
Tapes
Acoustic Tape Market
Tapes
Freezer Tape Market
Tapes
Carton Sealing Tape Market
Tapes
Heat Activated Tear Tape Market
Tapes
Tape Backing Materials Market
Tapes
Filmic Tapes Market
Tapes
India Reflective Tapes Market