
 Acoustic Tape Market | 2026-2036
Acoustic Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Tape Market Analytics
The capital-intensity gap between integrated foam compounders and converters is collapsing as raw material volatility squeezes mid-tier margins. 3M Company leverages captive polymer science capabilities to sustain pricing power across automotive OEM programs. Nitto Denko Corporation anchors its position through precision coating assets that dominate Asian electronics supply chains.
Acoustic tape denotes pressure-sensitive adhesive laminates engineered with viscoelastic cores, typically 0.5 mm to 5.0 mm thick, that convert mechanical vibration into negligible heat through constrained-layer damping. Foam-backed variants command the widest application footprint across automotive door seals and HVAC ductwork where broadband frequency absorption matters. Polyurethane grades compete aggressively in electronics gasketing where thin-profile damping and thermal stability overlap. Rubber compositions retain durable share in heavy-equipment cab insulation despite slower growth curves.
FDA and EPA frameworks in the United States govern adhesive emissions and workplace exposure limits that shape product chemistry roadmaps. The EU REACH regulation and F-Gas Directive constrain solvent-based manufacturing processes and fluorinated blowing agents across European supply chains. ECHA substance-of-very-high-concern listings are forcing reformulation timelines that favor waterborne acrylic systems. Stakeholders must monitor how building code acoustic performance tiers in China and India's urban centers redirect specification authority from contractors to material certifiers.
Market Dynamics
The collapse of capital-intensity gaps between integrated foam compounders and converters is redistributing margin capture toward polymer science specialists with captive raw material control.
Growth Catalysts
- EU Green Deal embodied carbon rules:Tightening material sourcing requirements for construction adhesives and sealants are redirecting specification authority toward certified acoustic tape suppliers with verified supply chain emissions data.
- Electric vehicle cabin quieting:Automotive manufacturers in Germany and Japan are expanding acoustic tape procurement for NVH management as powertrain electrification eliminates engine masking noise.
- China's eastern manufacturing corridor:Co-located EV and electronics assembly clusters are concentrating demand for thin-profile damping solutions within single logistics radii.
Market Restraints
- Raw material volatility:Polyurethane precursor and acrylic adhesive monomer price swings squeeze mid-tier converter margins without captive polymer supply.
- Fluorinated blowing agent constraints:The EU F-Gas Directive limits solvent-based manufacturing processes and legacy foam expansion chemistries across European supply chains.
- Waterborne system performance gaps:ECHA substance-of-very-high-concern listings force reformulation timelines where waterborne acrylics lag solvent-based adhesion in high-humidity automotive applications.
Strategic Opportunities
- India's urban acoustic codes:Building code performance tiers in Indian metropolitan centers are shifting specification authority from contractors to material certifiers for HVAC and construction applications.
- Electronics gasketing convergence:Overlapping demand for thin-profile damping and thermal stability in Asian consumer electronics assembly creates specification pull for multi-functional tape laminates.
- Waterborne acrylic tailwinds:REACH-compliant reformulation mandates favor suppliers with proven low-VOC adhesive platforms that satisfy both workplace exposure limits and embodied carbon accounting.
Industry Challenges
- Precision coating talent scarcity:Constrained supply of engineers capable of calibrating viscoelastic layer thickness tolerances below 50 microns limits converter expansion.
- Dual certification timelines:Simultaneous pursuit of automotive OEM PPAP approval and construction adhesive emissions certification stretches quality system resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Tape Market |
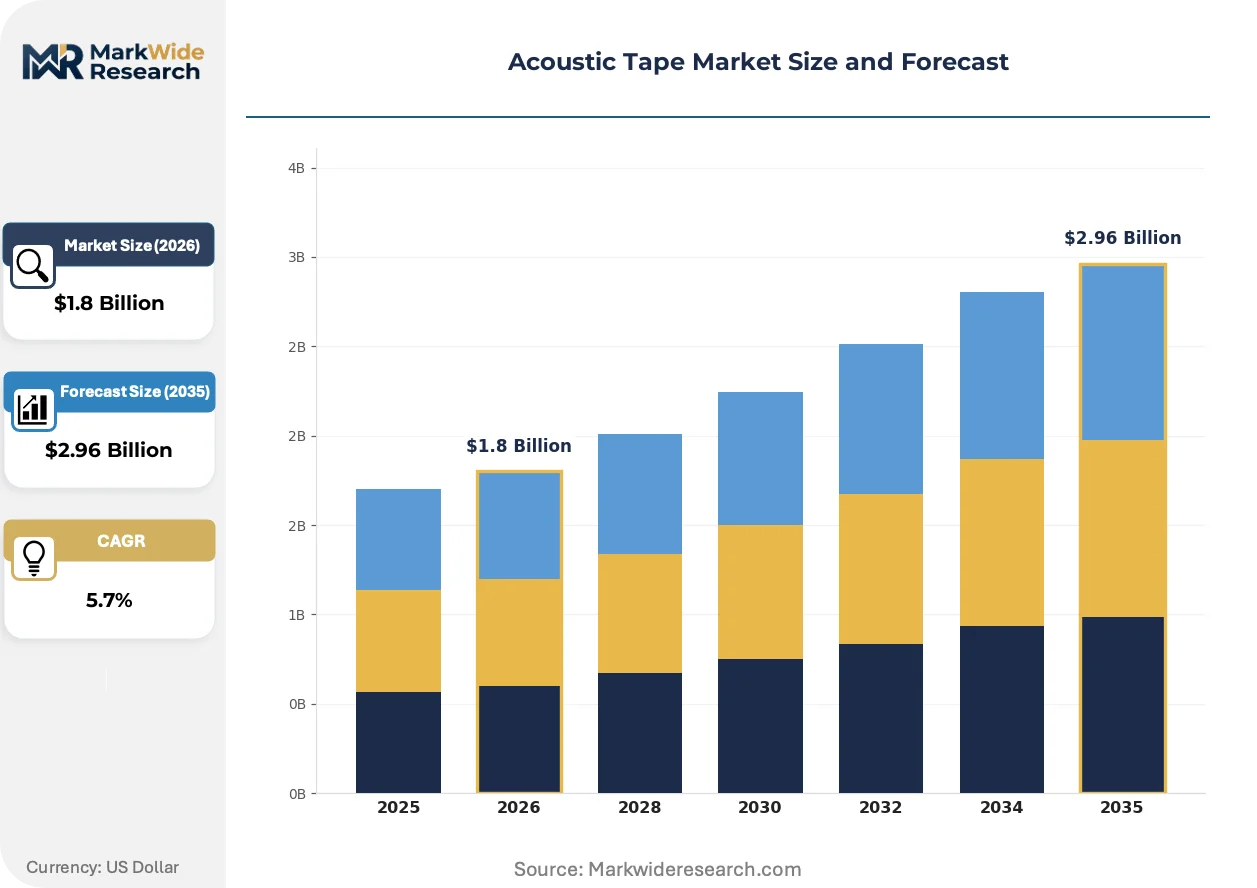
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Polyurethane, Rubber, PVC End User: Automotive, Electronics, Construction, HVAC Application: Soundproofing, Vibration Damping, Insulation, Sealing Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, tesa SE, Henkel AG & Co. KGaA, Intertape Polymer Group, Saint-Gobain, Scapa Group, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Tape Market Evolving Landscape
Active reformulation of adhesive platforms and coating precision capabilities is compressing product development cycles while regulatory emissions frameworks harden chemistry roadmaps.
Multi-layer viscoelastic cores with gradient density profiles are miniaturizing effective damping mass into sub-millimeter constructions. Consumer electronics OEMs in South Korea and Taiwan are adopting these laminates for smartphone hinge and display gasket applications within 12-month qualification windows. The technology is miniaturizing acoustic management footprints while preserving broadband frequency absorption across 100 Hz to 10 kHz ranges.
The EU F-Gas Directive and ECHA SVHC listings are forcing solvent-to-waterborne adhesive transitions across European acoustic tape manufacturing. Industrial consequence includes 18-24 month reformulation validation cycles and capital redeployment into aqueous coating lines. Construction and automotive OEMs in Germany and France are responding by consolidating supplier panels toward vertically integrated compounders with verified low-VOC platforms.
Specification authority is migrating from installation contractors to material certifiers as acoustic performance tiers harden in building codes. China's GB standards and India's urban development mandates are displacing price-driven procurement with certified-performance sourcing in commercial HVAC and residential construction channels. This behavioral shift is most visible in Shanghai and Mumbai metropolitan project pipelines where developer liability for acoustic failure has tightened.
Acoustic Tape Market Segmentation
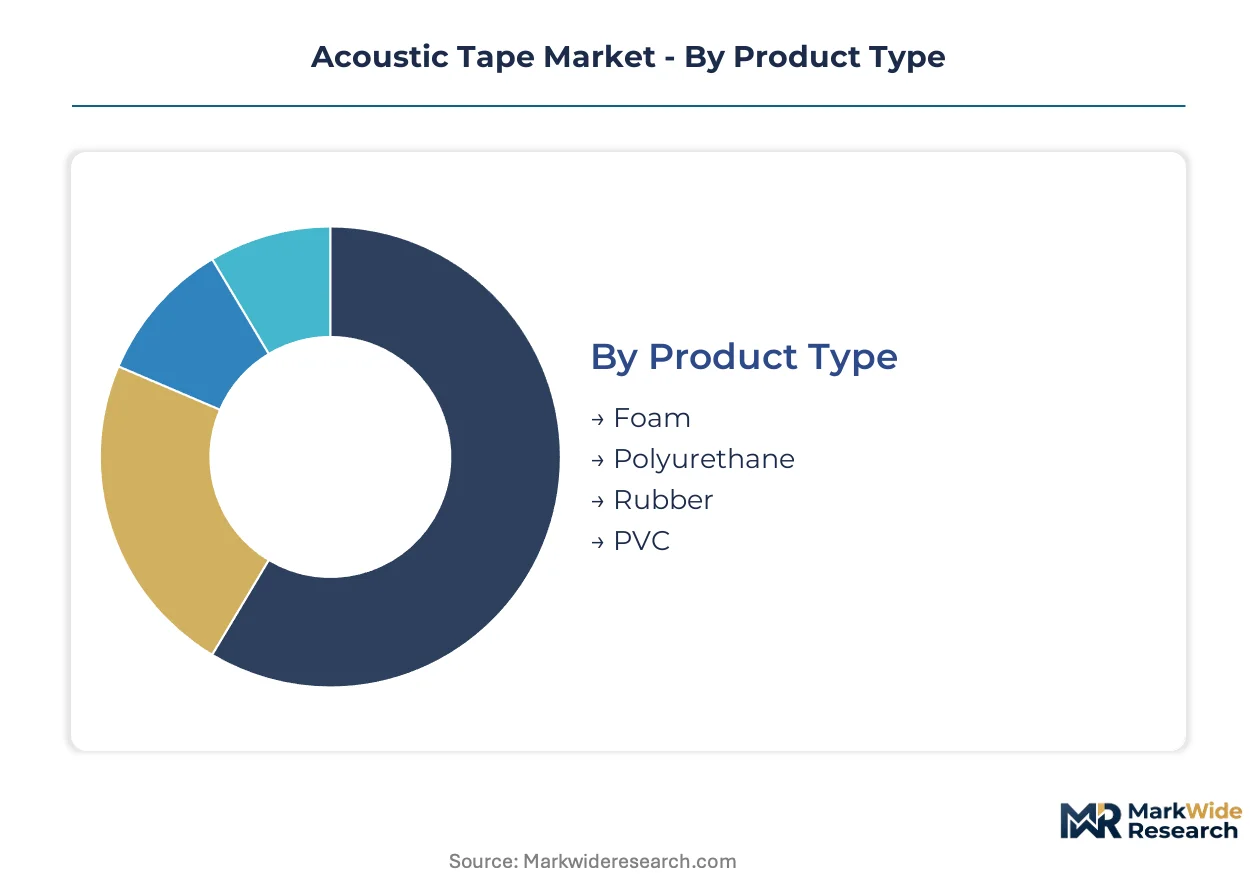
Acoustic tape segmentation reflects divergent technical requirements across NVH management, electronics miniaturization, and building envelope applications. Regulatory frameworks in automotive emissions, workplace exposure, and embodied carbon are fragmenting specification pathways by chemistry and construction type.
Product Type:
REACH and F-Gas Directive constraints are bifurcating competitive position between solvent-legacy compounders and waterborne-capable suppliers.
- Foam:Viscoelastic cores with constrained-layer damping construction dominate broadband frequency absorption. German and Japanese automotive OEMs specify foam-backed laminates for door seal and cabin NVH programs where powertrain electrification exposes road and wind noise.
- Polyurethane:Thin-profile grades with thermal stability overlap compete aggressively in electronics gasketing. China's eastern manufacturing corridor concentrates procurement for smartphone hinge and display gasket applications within single logistics radii.
- Rubber:Heavy-equipment cab insulation retains durable specification share despite slower expansion curves in mining and construction machinery.
- PVC:Cost-driven construction and HVAC ductwork applications favor PVC compositions where building code acoustic tiers remain less stringent.
Foam handles the majority of throughput; polyurethane is the fastest mover on share.
End User:
Customer procurement patterns split between OEM direct specification and distributor-mediated construction channels.
- Automotive:Cabin quieting programs in Germany and Japan drive specification authority toward compounders with captive polymer science and verified low-VOC platforms. Powertrain electrification eliminates engine masking noise, expanding damping material volumes per vehicle.
- Electronics:South Korean and Taiwanese OEMs adopt sub-millimeter gradient-density laminates within compressed qualification windows. Multi-functional tape specifications converge thermal management with vibration damping.
- Construction:EU Green Deal embodied carbon rules redirect specification authority toward certified suppliers with verified supply chain emissions data for commercial HVAC and residential envelope applications.
- HVAC:India's urban acoustic codes are shifting procurement from price-driven contractor selection to material certifier authority in Mumbai and Delhi metropolitan project pipelines.
Automotive commands the largest revenue pool; electronics is expanding most quickly as device miniaturization intensifies.
Application:
Functional requirements determine whether specification prioritizes frequency range, environmental durability, or installation speed.
- Soundproofing:Broadband absorption across 100 Hz to 10 kHz ranges governs automotive cabin and building partition applications. Gradient-density miniaturization preserves performance in reduced material footprints.
- Vibration Damping:Constrained-layer constructions convert mechanical energy to negligible heat. Electronics assembly in China's eastern corridor concentrates demand for thin-profile solutions.
- Insulation:Thermal-acoustic overlap specifications favor multi-functional laminates in HVAC and building envelope channels.
- Sealing:Pressure-sensitive adhesive compatibility with irregular substrates drives foam-backed variant selection in automotive and construction.
Soundproofing absorbs the greatest material volume; vibration damping is climbing the fastest on specification intensity.
Thickness:
Profile constraints from end-use dimensional budgets are compressing effective damping mass into thinner constructions.
- Thin:Sub-millimeter constructions with gradient-density viscoelastic cores address smartphone hinge and display gasket limitations. South Korean OEMs drive 12-month qualification compression.
- Medium:0.5 mm to 2.0 mm profiles balance broadband absorption with installation practicality across automotive door seal and HVAC ductwork.
- Thick:2.0 mm to 5.0 mm constructions retain specification in heavy-equipment cab and industrial machinery where space constraints relax.
- Extra Thick:Specialized applications in marine and rail transport accommodate mass damping requirements beyond standard automotive and electronics profiles.
Medium thickness carries the highest unit volume; thin profiles are gaining share fastest on electronics penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese automotive supply chains while Chinese converters compete on volume throughput. The EU Green Deal's embodied carbon accounting creates certification premiums that Asian exporters struggle to capture. Regulatory divergence between REACH-compliant European markets and GB standards-driven Chinese procurement is fragmenting specification pathways.
Germany
Automotive OEMs in Stuttgart and Munich are expanding acoustic tape procurement for electric vehicle cabin quieting programs. The EU F-Gas Directive and ECHA SVHC listings constrain solvent-based manufacturing processes, favoring waterborne acrylic suppliers with verified low-VOC platforms. The Baden-Württemberg industrial corridor hosts compounders with captive polymer science capabilities that sustain pricing power across NVH material specifications.
China
Co-located EV and electronics assembly clusters in the Yangtze River Delta and Pearl River Delta are concentrating demand for thin-profile damping solutions. GB standards and MIIT regulations govern workplace exposure limits and adhesive emissions in manufacturing facilities. Shanghai and Shenzhen metropolitan procurement pipelines are displacing price-driven contractor selection with certified-performance sourcing for commercial HVAC applications.
Japan
Automotive manufacturers in Toyota City and Yokohama are scaling acoustic tape volumes for powertrain electrification that eliminates engine masking noise. METI and JIS standards shape product chemistry roadmaps for adhesive platforms serving domestic OEM programs. The Chubu and Kanto industrial regions anchor precision coating assets that dominate Asian electronics supply chains for smartphone hinge and display gasket applications.
United States
FDA and EPA frameworks govern adhesive emissions and workplace exposure limits that shape reformulation timelines for construction and automotive channels. The Southeast manufacturing corridor and Midwest automotive belt concentrate converter operations serving domestic OEM programs. California's building code acoustic performance tiers are shifting specification authority from contractors to material certifiers in Los Angeles and San Francisco metropolitan project pipelines.
India
Urban development mandates in Mumbai and Delhi are tightening acoustic performance tiers for commercial HVAC and residential construction applications. BIS standards and CEA regulations redirect specification authority toward certified suppliers with verified supply chain emissions data. The Maharashtra and Gujarat industrial corridors are emerging as procurement hubs where developer liability for acoustic failure has tightened material selection protocols.
Acoustic Tape Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated compounders commanding specification authority while mid-tier converters compete on volume throughput. The vendor base separates into three strategic tiers: multinational material science conglomerates with captive polymer capabilities, regional precision coating specialists, and price-focused converters without upstream control. Consolidation pressures favor backward integration into raw material supply and aqueous coating line redeployment. Strategic partnerships between automotive OEMs and certified suppliers are displacing distributor-mediated procurement in European and Asian markets.
Among multinational material science conglomerates, 3M Company and Nitto Denko Corporation exemplify the technology-leadership archetype through captive polymer science capabilities and precision coating assets. Henkel AG & Co. KGaA occupies a position within the adhesive platform specialist tier, representing suppliers with proven low-VOC formulations that satisfy REACH compliance and embodied carbon accounting requirements. These three companies anchor the competitive structure by demonstrating how specification authority migrates toward vertically integrated compounders with verified supply chain emissions data.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| tesa SE |
| Henkel AG & Co. KGaA |
| Intertape Polymer Group |
| Saint-Gobain |
| Scapa Group |
| Sika AG |
| Others |
Value Network & Pricing Analysis
Capacity utilization at precision coating lines in Japan and Germany shapes both supply concentration and price floors for acoustic tape laminates. Scale advantages at integrated compounders with captive polymer science capabilities compress margins for mid-tier converters lacking upstream control, while raw material volatility in polyurethane precursors and acrylic monomers reinforces tiered pricing stratification across automotive OEM and construction channels.
Pricing Analysis
Configured-to-order pricing for automotive NVH programs commands substantial premiums over standard HVAC and construction grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant waterborne systems from German compounders price above solvent-legacy alternatives, while price erosion runs through PVC-backed construction tapes where building code tiers remain less stringent. Automotive OEM direct procurement demonstrates lowest price sensitivity; contractor-mediated construction channels exhibit highest elasticity.
Supply Chain Analysis
Inventory cycles at Asian precision coating assets stretch lead times for sub-millimeter gradient-density laminates serving South Korean electronics OEMs. Manufacturing concentrates in China, Japan, and Germany, with raw material supply drawing from petrochemical feedstocks in the US Gulf Coast and Middle Eastern propane dehydrogenation complexes. Single-source vulnerability in fluorinated blowing agent supply chains amplifies risk exposure under EU F-Gas Directive constraints. Distribution runs through Tier 1 automotive supplier networks and certified construction material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic tape manufacturing rests on scarce precision coating engineering talent capable of calibrating viscoelastic layer tolerances below 50 microns, creating sustainable advantage for incumbents with established technical workforces and capital-intensive aqueous coating infrastructure.
For Market Incumbents: Compound captive polymer science capabilities through backward integration into acrylic adhesive monomer supply, defending against margin compression from raw material volatility. Prioritize dual certification investments—simultaneous automotive OEM PPAP approval and construction adhesive emissions certification—to capture specification authority migrating from contractors to material certifiers under EU Green Deal embodied carbon rules. For New Entrants and Emerging Players: Lead with waterborne acrylic platform specialization targeting India's urban acoustic code enforcement in Mumbai and Delhi metropolitan construction pipelines, where certified-performance sourcing displaces price-driven procurement. Establish technical partnerships with precision coating equipment vendors to compress 18-24 month reformulation validation cycles and qualify for electronics gasketing specifications in China's eastern manufacturing corridor. For Investors and Strategic Acquirers: Regional precision coating specialists with proven aqueous line operations and existing automotive OEM relationships represent the most defensible acquisition archetype for medium-term consolidation plays. Long-term viability hinges on waterborne system performance convergence with solvent-based adhesion in high-humidity applications—monitor ECHA substance-of-high-concern listing velocity and automotive OEM qualification window compression as inflection signals for platform transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive raw material control insulates margin structures from polyurethane precursor volatility. |
| Aqueous Coating Line Redeployment | REACH-compliant waterborne platforms capture EU Green Deal certification premiums from German automotive OEMs. |
| Dual Certification Investment | Simultaneous PPAP and construction emissions approval stretches quality systems but locks specification authority. |
| Precision Coating Talent Acquisition | Engineers capable of sub-50-micron viscoelastic calibration remain scarce across Asian and European supply bases. |
| Electronics Gasketing Partnership | South Korean and Taiwanese OEM 12-month qualification windows demand compressed product development cycles. |
Research Methodology
A standing panel of automotive NVH material engineers, construction adhesive procurement managers, precision coating line operators, and electronics OEM supply chain directors provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation from customs trade data, SEC 10-K filings of listed compounders, automotive production databases, and ECHA regulatory submission records. Bottom-up volume builds from end-use application consumption rates triangulated against top-down market sizing from raw material throughput estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product chemistry type, end-use industry vertical, thickness profile tier, and regional regulatory cluster. CAGRs derived from historical growth rate analysis adjusted for technology substitution effects and regulatory phase-in timelines. Forecast inputs incorporated powertrain electrification penetration curves and building code acoustic tier adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Directive enforcement or accelerated China GB standard implementation would require recalibration. Forecasts reflect documented assumptions regarding waterborne acrylic performance convergence and precision coating capacity expansion timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Pucker Free Tapes Market
Tapes
Gaffers Tape Market
Tapes
Pre-Printed Tape Market
Tapes
Fine Line Striping Tape Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Spacer Tapes Market
Tapes
Carry Handle Tape Market
Tapes
Dry Wall Tapes Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Mastic Tapes Market
Tapes
Global Printed Tape Market
Tapes
Seam Tapes Market
Tapes
Medical Tapes Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
Twist Tube Market