
 Static Shielding Bags Market | 2026-2036
Static Shielding Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Static Shielding Bags Market Analytics
Buyer concentration among electronics contract manufacturers is expanding as tier-one OEMs consolidate vendor lists for ESD-sensitive component supply chains. Desco Industries Inc. leverages its vertically integrated domestic manufacturing to sustain pricing power across North American distribution channels. Protective Packaging Corporation anchors its position through specialized military and aerospace certifications that competitors struggle to replicate. Advantek Inc. differentiates via precision converting capabilities for custom gusseted and zip-lock configurations demanded by medical device OEMs.
Static shielding bags are multi-layer laminated enclosures incorporating metalized film barriers, typically aluminum deposited on polyester substrates, engineered to attenuate electrostatic discharge below damage thresholds for sensitive semiconductors and printed circuit assemblies. The primary commercial purpose centers on in-process handling, storage, and transport of ESD-sensitive devices across electronics manufacturing workflows. Flat bags dominate unit volume in high-throughput electronics assembly where automated bagging lines prioritize speed over reusability. Metalized film constructions command premium positioning due to superior shielding effectiveness and compliance with ANSI/ESD S20.20 discharge voltage requirements. Zip lock configurations represent the fastest-expanding format as medical device and aerospace end users prioritize contamination control with repeated access needs.
FDA quality system regulations for medical device packaging and EPA hazardous substance labeling requirements directly influence material selection and validation protocols for domestic suppliers. ANSI/ESD S20.20 and IEC 61340-5-1 standards govern discharge protection thresholds, creating compliance-driven replacement cycles and certification barriers for non-conforming imports. Stakeholders must monitor evolving EU RoHS substance restrictions and state-level extended producer responsibility frameworks as these reshape resin sourcing and recycling infrastructure investments.
Market Dynamics
Semiconductor fabrication capacity expansion in East Asia is concentrating demand for ANSI/ESD S20.20-compliant shielding solutions among a narrowing set of high-volume contract manufacturers, compressing supplier margins while elevating certification barriers for new entrants.
Growth Catalysts
- REACH substance restrictions:European chemical safety mandates are accelerating metalized film reformulation toward halogen-free barrier layers, creating replacement demand across medical device supply chains.
- Zip-lock format adoption:Aerospace maintenance operations are specifying reusable static shielding enclosures for field-replaceable unit programs, expanding addressable volume beyond single-use electronics assembly.
- Vietnam:Samsung and Intel fabrication investments are localizing ESD packaging procurement, pulling regional converter capacity from Thailand and Malaysia.
Market Restraints
- Aluminum spot volatility:Vacuum deposition feedstock costs swing with London Metal Exchange pricing, squeezing converter margins on fixed-price OEM contracts.
- Polyester substrate concentration:Three Korean resin suppliers control metallizable film substrate supply, creating single-source vulnerability for North American bag converters.
- IEC 61340-5-1 test protocol complexity:Extended validation timelines delay new product qualification, freezing out smaller converters without dedicated compliance laboratories.
Strategic Opportunities
- India:PLI scheme subsidies for semiconductor assembly and testing are attracting Foxconn and Tata Electronics investments, opening virgin demand for ESD packaging localization.
- Biodegradable barrier films:Convergence of polylactic acid substrates with thin-film aluminum deposition is enabling compostable shielding solutions for disposable medical electronics.
- Direct-to-fab distributor models:Bypassing traditional electronics distributors, bag converters are establishing consignment inventory at TSMC and GlobalFoundries campuses.
Industry Challenges
- Vacuum metallization technician scarcity:Specialized roll-to-roll coating expertise concentrates in German and Japanese equipment OEMs, constraining converter expansion.
- ANSI/ESD S20.20 audit backlog:Accredited third-party certification bodies face six-month queue times, delaying new supplier approval for tier-one OEM vendor lists.
- Legacy ERP integration:Medical device packaging converters struggle to synchronize lot traceability data with FDA 21 CFR Part 11-compliant customer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static Shielding Bags Market |
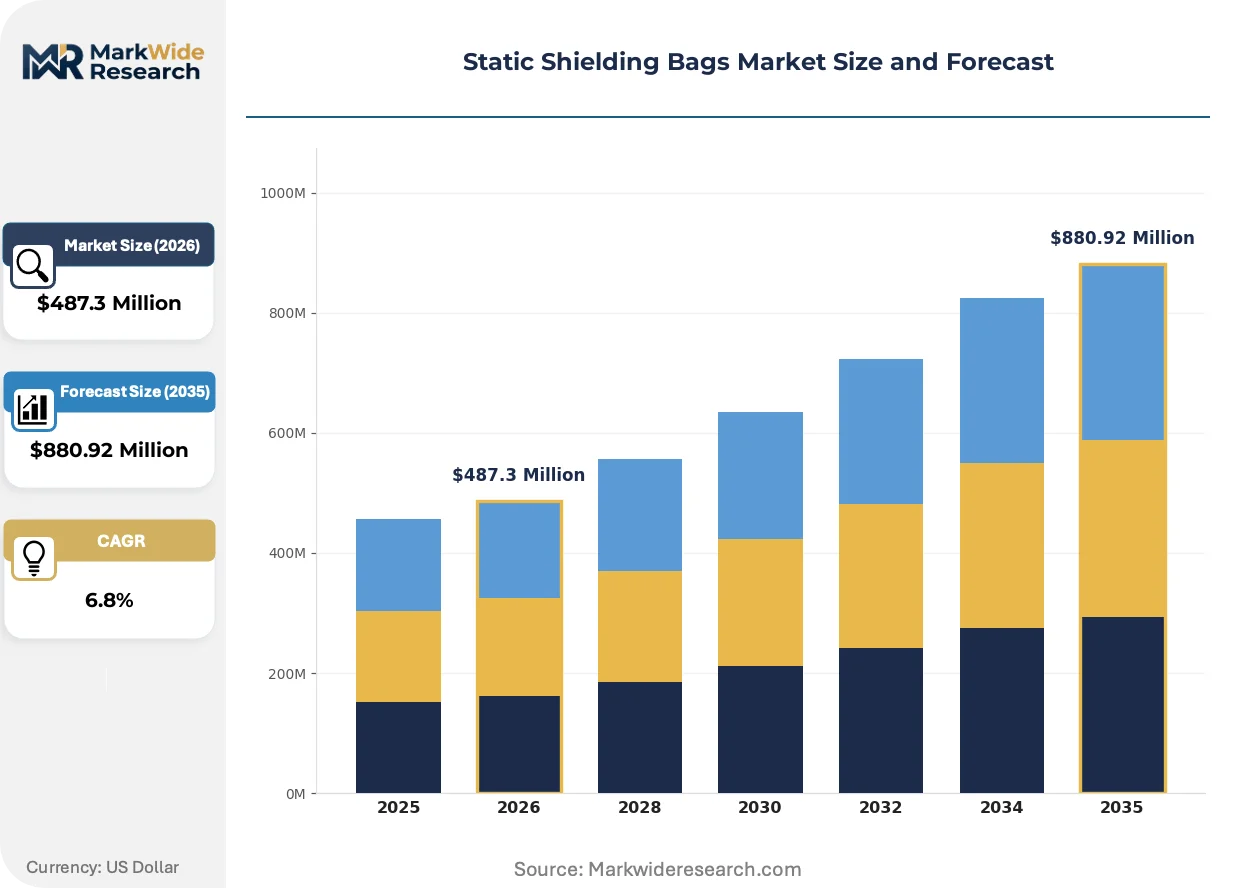
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Zip Lock Bags, Pouches Material: Polyethylene, Polyester, Metalized Film, Nylon Application: Electronics, Medical Devices, Aerospace, Automotive Components End User: Manufacturers, Distributors, Retailers, Government Agencies |
| Companies Covered | Desco Industries Inc., Protective Packaging Corporation, Advantek Inc., Antistat Inc., Statico, Elcom (UK) Ltd, Teknis Limited, Edco Supply Corporation, Dou Yee Enterprises (S) Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static Shielding Bags Market Evolving Landscape
Material science breakthroughs and regulatory chemistry mandates are converging to redefine static shielding bag construction, with performance validation protocols now as critical as barrier effectiveness in supplier selection.
Multi-layer coextrusion with embedded carbon nanotube conductive grids is rewriting performance benchmarks for ultra-thin shielding applications. Medical device OEMs in Minnesota and Massachusetts are specifying these constructions for implantable electronics where aluminum particulate contamination risks outweigh cost premiums. The technology is compressing acceptable thickness thresholds from 3.0 mil to 1.5 mil without attenuation loss, enabling downsized sterile packaging footprints.
EU RoHS substance restrictions are phasing out certain brominated flame retardants in polyester substrates, forcing reformulation of legacy metalized film laminates. German automotive electronics suppliers are accelerating qualification of phosphorus-based alternatives ahead of 2026 enforcement deadlines. Medical device packaging in Ireland and the Netherlands faces the tightest compliance timelines, with notified body review queues already extending eighteen months.
Consignment inventory programs are displacing traditional purchase-order procurement in high-volume semiconductor assembly. Texas Instruments and Analog Devices are mandating vendor-managed stock at their Philippines and Malaysia backend facilities, transferring working capital burden to bag converters. The model is most visible in power management IC packaging, where demand volatility from electric vehicle inverter programs defies conventional forecasting.
Static Shielding Bags Market Segmentation
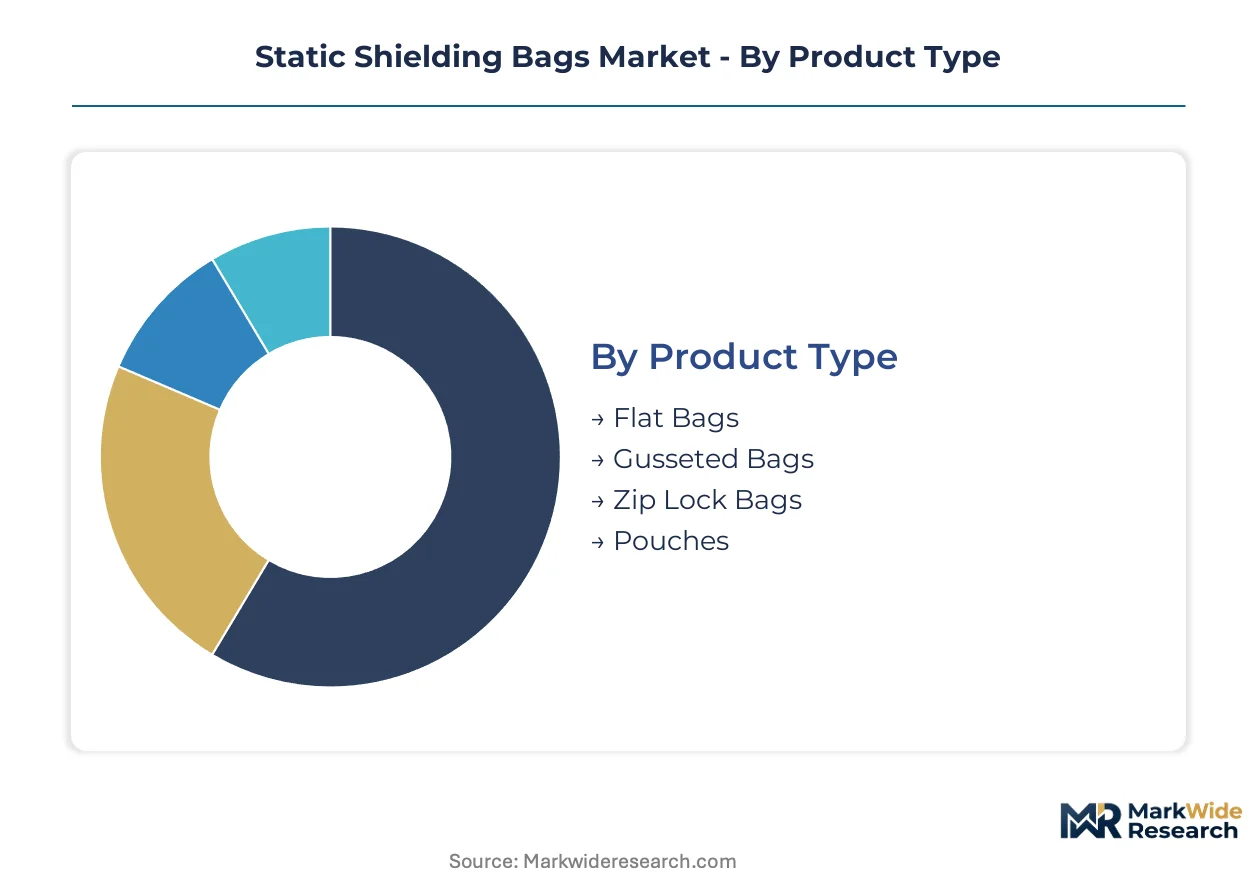
Static shielding bag converters must align production assets with distinct performance tiers and compliance regimes. Segmentation reveals where capital deployment yields durable returns versus commodity exposure.
Product Type:
Zip lock configurations demand the heaviest upfront investment in precision sealing equipment and cleanroom infrastructure.
- Flat Bags:Single-layer or multi-laminate envelopes without closure mechanisms, optimized for high-speed automated bagging lines in semiconductor backend facilities. Samsung and Intel procurement in Vietnam and Malaysia concentrates volume here, though margin compression intensifies as Chinese converters add metallization capacity.
- Zip Lock Bags:Reclosable polyethylene or metalized film enclosures with interlocking seals, specified for aerospace field-replaceable units and sterile medical device access. Boeing and Airbus maintenance programs in Toulouse and Hamburg are expanding reusable procurement, pulling capacity from single-use electronics applications.
- Gusseted Bags:Side-pleated constructions accommodating irregular PCB assemblies and cable harnesses.
- Pouches:Pre-formed three-seal enclosures for manual or semi-automated loading operations.
Most installed capacity flows through flat bags. Expansion is steepest in zip lock formats.
Material:
Metalized film constructions command the widest margin spreads but require vacuum deposition assets that concentrate among German and Japanese equipment suppliers.
- Metalized Film:Aluminum-vapor-deposited polyester or polyethylene substrates delivering attenuation below ANSI/ESD S20.20 discharge thresholds. REACH halogen-free reformulation is accelerating replacement demand across Irish and Dutch medical device supply chains ahead of enforcement deadlines.
- Polyester:Biaxially oriented terephthalate films providing dimensional stability and thermal resistance for reflow-compatible packaging. Three Korean resin suppliers—SKC, Kolon Industries, and Toray Korea—control metallizable substrate supply, creating single-source vulnerability for North American converters.
- Polyethylene:Low-density or linear low-density films serving cost-sensitive consumer electronics and inner liner applications.
- Nylon:Polyamide layers incorporated for puncture resistance in aerospace and military logistics.
Polyester substrates anchor current volume. Metalized film is gaining share fastest.
Application:
Medical device packaging carries the most stringent validation burden, extending qualification timelines and freezing out smaller converters.
- Electronics:Semiconductor, PCB, and component protection across fabrication, assembly, and distribution. TSMC and GlobalFoundries are mandating consignment inventory models at Philippines and Malaysia backend facilities, transferring working capital burden to bag converters.
- Medical Devices:Implantable electronics and diagnostic equipment packaging subject to FDA 21 CFR Part 11 lot traceability and EU MDR substance documentation. Minnesota and Massachusetts OEMs are specifying carbon nanotube conductive grids to eliminate aluminum particulate contamination risks.
- Aerospace:Military and commercial aircraft component protection requiring specialized certifications.
- Automotive Components:Power management IC and sensor packaging for electric vehicle inverter programs.
Electronics absorbs the largest capacity share. Medical devices show the steepest expansion trajectory.
End User:
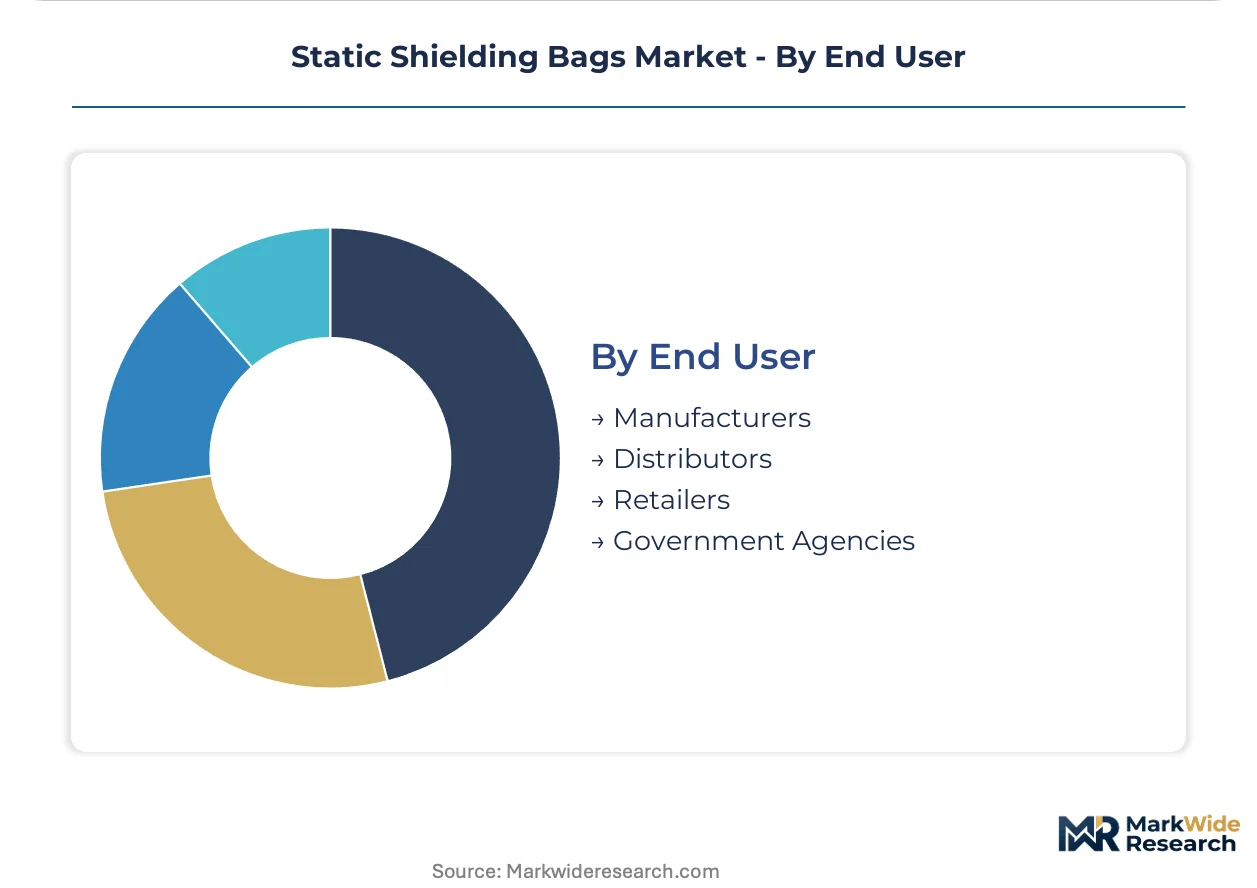
Manufacturer-direct procurement is displacing distributor intermediation as OEMs consolidate vendor lists.
- Manufacturers:Tier-one electronics and medical device OEMs qualifying converters directly for ESD-sensitive supply chains. Texas Instruments and Analog Devices are compressing approved vendor lists to three converters per region, elevating certification barriers for new entrants.
- Distributors:Electronics component distributors maintaining buffer stock for contract manufacturers. Arrow and Avnet are losing share as direct-to-fab models proliferate.
- Retailers:Consumer electronics aftermarket packaging for replacement components.
- Government Agencies:Defense and space programs requiring ITAR and AS9100 certification.
Manufacturer channels dominate current flow. Direct procurement models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vacuum metallization technicians cluster in German and Japanese equipment OEMs, constraining converter expansion elsewhere while semiconductor fabrication investments reshape regional demand patterns.
China
Semiconductor backend facilities in Jiangsu and Zhejiang provinces drive concentrated procurement of flat bag configurations for high-throughput automated lines. MIIT domestic content mandates accelerate local converter capacity additions. Yangtze River Delta clusters around Shanghai and Suzhou host expanding metallization operations serving TSMC Nanjing and SMIC fabs.
United States
Medical device OEMs in Minnesota and Massachusetts specify carbon nanotube conductive grids to eliminate aluminum particulate risks in implantable electronics packaging. FDA 21 CFR Part 11 lot traceability requirements extend qualification timelines for domestic converters. Austin and Phoenix semiconductor corridors pull ESD packaging demand toward Texas and Arizona backend facilities.
Germany
Automotive electronics suppliers accelerate phosphorus-based flame retardant qualification ahead of EU RoHS enforcement deadlines. ECHA REACH substance restrictions drive halogen-free metalized film reformulation across medical device supply chains. Bavarian industrial corridors around Munich and Nuremberg concentrate converter R&D for barrier layer innovation.
South Korea
Samsung and SK Hynix memory fabrication investments localize ESD packaging procurement from regional Thai and Malaysian converters. MFDS medical device regulations intersect with EU MDR documentation requirements for export-oriented suppliers. Gyeonggi Province semiconductor clusters around Suwon and Yongin anchor domestic bag converter expansion.
Vietnam
Samsung and Intel fabrication investments pull regional converter capacity from established Thai supply bases. BIS-equivalent national standards for ESD protection emerge as foreign direct investment conditions. Bac Ninh and Ho Chi Minh City industrial zones concentrate new bag converting operations serving backend assembly facilities.
Static Shielding Bags Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market tiers. The vendor base stratifies around three structural archetypes: vertically integrated domestic manufacturers sustaining pricing power through captive metallization assets, specialized military-aerospace certifiers leveraging ITAR and AS9100 barriers, and precision converters serving medical device OEMs with custom gusseted and zip-lock configurations. Consolidation pressures intensify as tier-one OEMs compress approved vendor lists to three converters per region, while six-month ANSI/ESD S20.20 audit backlogs freeze out new entrants lacking dedicated compliance laboratories.
Among North American fabricators, Desco Industries Inc. anchors the vertically integrated tier with domestic metallization assets, while Protective Packaging Corporation occupies the defense-specialist position through military certification concentration. Advantek Inc. exemplifies the medical-precision archetype with custom converting capabilities. These three patterns—captive supply chain control, regulatory barrier exploitation, and application-specific engineering—define competitive positioning across the analysis window.
| Leading Market Players |
|---|
| Desco Industries Inc. |
| Protective Packaging Corporation |
| Advantek Inc. |
| Antistat Inc. |
| Statico |
| Elcom (UK) Ltd |
| Teknis Limited |
| Edco Supply Corporation |
| Dou Yee Enterprises (S) Pte Ltd |
| Others |
Value Network & Pricing Analysis
Vacuum metallization technicians cluster in German and Japanese equipment OEMs, widening labor-cost differentials between converters with captive coating assets and those sourcing toll services, which in turn separates premium-certified pricing from commodity flat-bag tiers.
Pricing Analysis
Bundled certification-plus-validation services command spreads over unbundled bag-only procurement, with ANSI/ESD S20.20 audit documentation and lot-traceability integration priced separately. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with medical device OEMs least sensitive and consumer electronics contract manufacturers most responsive to per-unit swings. Pricing pressure stems from Chinese converter capacity additions compressing flat-bag margins in Vietnam and Malaysia. Aerospace maintenance programs purchasing zip-lock formats show lowest price elasticity due to ITAR compliance requirements.
Supply Chain Analysis
MIIT domestic content mandates in China and PLI scheme localization conditions in India are reshaping sourcing patterns, pulling metallization capacity toward semiconductor cluster zones. Polyester substrate supply draws from South Korea, China, and Japan, with aluminum feedstock and polyethylene resin completing the input stack. Single-source vulnerability concentrates in Korean metallizable film substrates controlled by SKC, Kolon Industries, and Toray Korea. Distribution runs through direct-to-fab consignment models at TSMC and GlobalFoundries campuses, displacing traditional electronics distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with semiconductor fabrication capacity expansion providing steady, non-cyclical demand visibility across the analysis window.
For Market Incumbents: Hedge aluminum spot exposure through long-term London Metal Exchange hedging instruments or toll-metallization partnerships that transfer feedstock risk. Deepen backward integration into polyester substrate extrusion where Korean supply concentration creates vulnerability, or secure dedicated cleanroom capacity for zip-lock medical device qualifications before FDA audit backlogs extend further. ANSI/ESD S20.20 certification scarcity protects position against Asian converters lacking accredited laboratory infrastructure. For New Entrants and Emerging Players: Indian contract manufacturers represent the most penetrable buyer archetype, with Foxconn and Tata Electronics backend facilities creating virgin demand unclaimed by established Thai and Malaysian converters. Target biodegradable barrier film development for disposable medical electronics as EU MDR sustainability documentation requirements tighten. Bypass distributor intermediation entirely through direct consignment inventory models at semiconductor assembly campuses. For Investors and Strategic Acquirers: Diversified packaging conglomerates seeking ESD capability adjacencies are the most active acquirer in this space, particularly those lacking vacuum metallization assets. Five-to-ten-year viability rests on certification moat durability rather than commodity scale. Monitor ANSI/ESD S20.20 audit queue lengths as the critical inflection signal—shortening backlogs indicate competitive pressure intensification, while extended delays preserve incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyester Extrusion | Captive substrate supply insulates converters from Korean resin supplier concentration. |
| Halogen-Free Metalized Film Reformulation | REACH compliance positions converters for Irish and Dutch medical device procurement. |
| Direct-to-Fab Consignment Inventory | Texas Instruments and Analog Devices mandates transfer working capital to converter balance sheets. |
| Carbon Nanotube Conductive Grid Qualification | Minnesota and Massachusetts OEMs specify aluminum-free construction for implantable electronics. |
| Vietnam Metallization Capacity Addition | Samsung and Intel fabrication investments localize procurement from Thai supply bases. |
Research Methodology
Multiple input streams — vacuum metallization equipment OEM technical specifications, converter production capacity surveys, and semiconductor fab procurement databases — were reconciled against trade flow records and regulatory filing documents. Primary interviews with ESD compliance officers, medical device packaging engineers, and electronics distributor category managers were cross-referenced with secondary validation from IEC 61340-5-1 certification registries, FDA 21 CFR Part 11 guidance documents, and ECHA REACH substance restriction notices. Bottom-up unit demand modeling and top-down value reconciliation were applied across product type, material construction, and end-user channel segments.
Historical shipment patterns were cross-referenced against panel input from converter operations directors and OEM procurement leads to establish baseline trajectory assumptions across the analysis window. Segmentation dimensions modeled include bag configuration format, barrier layer composition, application compliance tier, and regional fabrication cluster. CAGRs were derived from volume elasticity coefficients applied to semiconductor capacity expansion schedules and medical device packaging validation timelines. Forecast inputs incorporated aluminum spot price volatility bands and ANSI/ESD S20.20 certification throughput constraints.
Underlying measurement precision varies by segment; medical device and aerospace applications carry tighter precision than commodity consumer electronics due to documented procurement volumes and certification audit records. Forecasts reflect assumptions regarding semiconductor fab buildout schedules, regulatory enforcement timelines, and metallization equipment delivery lead times. Raw material price swings, trade policy shifts, or accelerated biodegradable film adoption could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Packaging and Protective Packaging Market