
 Wine Bottle Sealing Wax Market | 2026-2036
Wine Bottle Sealing Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Bottle Sealing Wax Market Analysis
Premium winery adoption is shifting toward wax-sealed bottles as estate bottlers replace synthetic enclosures with dipped finishes that signal craft authenticity. Southwest Wax LLC leverages its Texas manufacturing base to supply domestic vintners with custom color-matched formulations. Calwax LLC sustains long-term contracts with Napa Valley estates through consistent batch quality and rapid turnaround on metallic variants. The Darent Wax Company Ltd anchors European supply through its Kent refining facility, serving Champagne houses and Bordeaux châteaux with heritage-grade beeswax blends.
Wine bottle sealing wax comprises thermoplastic formulations—typically paraffin, beeswax, or synthetic polymers—melted and dip-applied to create an airtight, tamper-evident closure over cork or capsule. Melting points range from 58°C to 82°C depending on composition, with drip profiles engineered to achieve controlled flow patterns that signal artisanal production values. Beeswax and natural resin segments command premium positioning among organic-certified wineries seeking compostable closure credentials, while synthetic wax variants dominate high-volume sparkling wine operations where consistency and cost control outweigh biodegradability concerns. Metallic and marbled color variants concentrate margin pools, as custom pigment matching for limited releases generates pricing power unavailable in standard opaque formulations.
FDA food-contact regulations govern wax purity thresholds for US-bound exports, while REACH restricts certain petroleum-derived additives across European supply chains. ECHA substance evaluations periodically recategorize paraffin byproducts, forcing reformulation cycles among suppliers serving EU wineries. ISO 22000 certification increasingly gates access to major distributor procurement lists, particularly for bulk pack configurations sold to commercial bottling lines. Stakeholders must monitor regulatory divergence between California's Proposition 65 disclosure requirements and emerging EU packaging waste directives, as compliance cost asymmetries will reshape competitive positioning across Atlantic supply corridors.
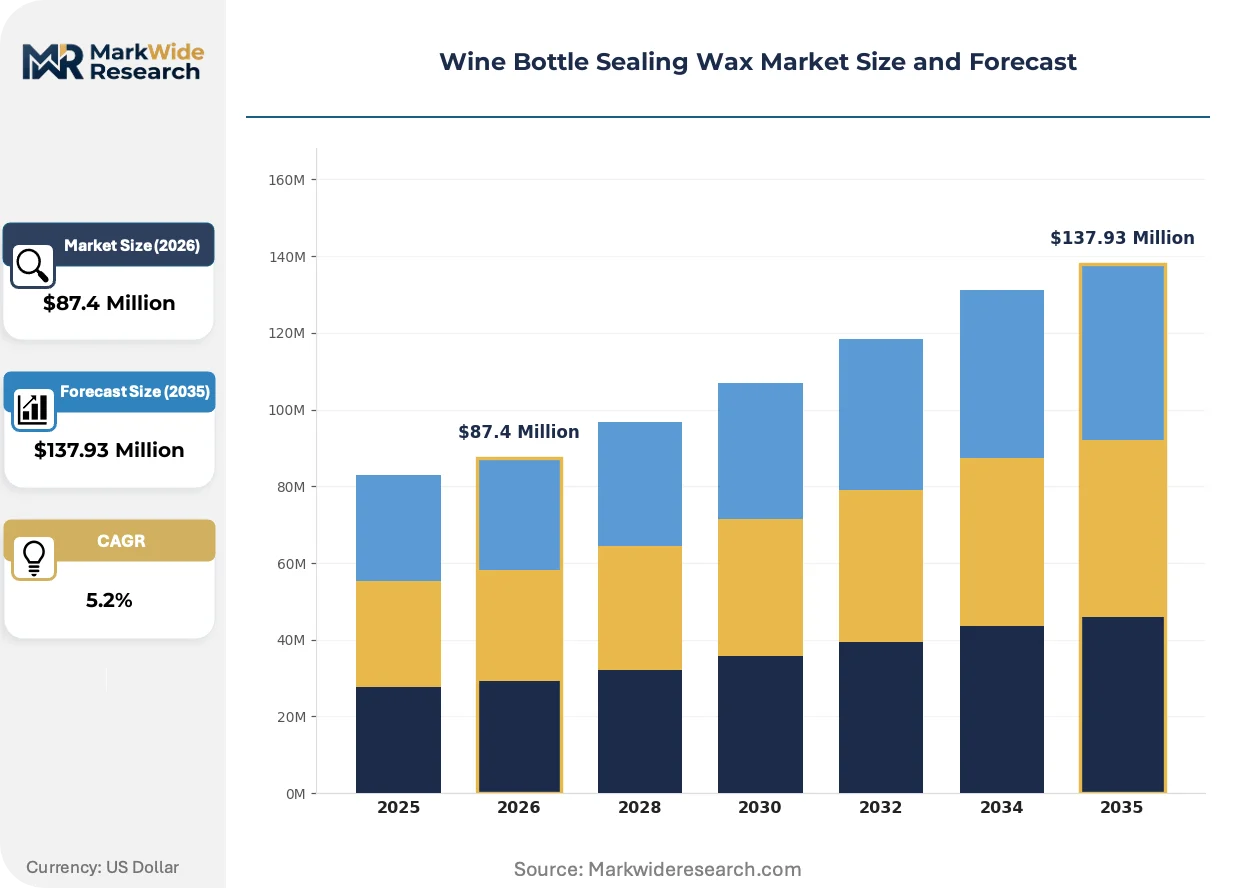
Market Dynamics
Estate wineries in France, Italy, and California are accelerating wax-seal adoption to differentiate premium releases from mass-market synthetic closures, tightening formulation purity requirements under REACH and FDA frameworks while compressing supplier qualification timelines.
Growth Catalysts
- REACH additive restrictions:ECHA substance evaluations are recategorizing paraffin byproducts, forcing reformulation investments that filter out commodity suppliers and consolidate share among certified refiners serving EU wineries.
- Heritage estate bottling:Champagne houses and Bordeaux châteaux are specifying heritage-grade beeswax blends for limited releases, creating margin pools unavailable in standard opaque formulations.
- Organic certification demand:Compostable closure credentials are pulling natural resin and beeswax segments ahead of synthetic variants as certified organic wineries replace petroleum-derived seals.
Market Restraints
- Petroleum feedstock volatility:Paraffin wax, the dominant base material for high-volume sparkling wine operations, tracks crude oil indices, compressing margins when energy markets spike.
- Supplier concentration in Kent refining:European heritage-grade beeswax supply anchors on a single UK refining corridor, exposing Champagne and Bordeaux producers to Brexit-related customs friction.
- Technical limitation in drip engineering:Controlled flow patterns requiring precise viscosity tuning at 58°C to 82°C melting points demand batch-to-batch consistency that commodity blenders cannot achieve.
Strategic Opportunities
- California Proposition 65 disclosure requirements:Compliance cost asymmetries between US and EU standards are creating openings for domestic Texas refiners to capture Napa Valley estate contracts from European importers.
- Metallic and marbled pigment matching:Custom color formulation for vintage-specific releases generates pricing power through small-batch exclusivity unavailable in standard SKUs.
- ISO 22000 certification gates:Bulk pack configurations for commercial bottling lines increasingly require food-safety certification, disqualifying regional wax traders and concentrating procurement among integrated refiners.
Industry Challenges
- Thermoplastic formulation expertise gap:Blending paraffin, beeswax, and synthetic polymers to achieve specific drip profiles requires polymer chemistry skills scarce among traditional candle wax suppliers pivoting into wine applications.
- Dual jurisdiction compliance timelines:Simultaneous FDA food-contact reviews and ECHA substance registrations stretch product development cycles, delaying market entry for reformulated low-additive variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Bottle Sealing Wax Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $137.93 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paraffin Wax, Beeswax, Natural Resin, Synthetic Wax Application Type: Red Wine, White Wine, Sparkling Wine, Fortified Wine Color Variant: Opaque, Transparent, Metallic, Marbled Packaging Type: Single Stick, Bulk Pack, Gift Set, Custom Design |
| Companies Covered | Southwest Wax LLC, Calwax LLC, Australian Wax Co, The Darent Wax Company Ltd, Blended Waxes Inc, The British Wax Refining Company Ltd, Westech Wax, Brick Packaging LLC, Oakbank Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Bottle Sealing Wax Market Emerging Trajectories
Dip-application automation and precision temperature control systems are compressing unit labor costs while regulatory divergence between California and EU standards is fragmenting formulation strategies across Atlantic supply corridors.
Precision temperature-controlled dipping rigs are automating wax application consistency for high-volume sparkling wine operations. Prosecco and Cava bottlers in Italy and Spain are deploying these systems to maintain drip-profile uniformity across 24-hour production cycles. The technology is automating quality control steps previously requiring manual inspection, reducing defect rates and labor headcount in commercial bottling facilities.
REACH restrictions on petroleum-derived additives are forcing systematic reformulation of paraffin-based sealing waxes across European supply chains. ECHA substance evaluations have recategorized certain byproducts, triggering mandatory replacement cycles for suppliers serving Champagne houses and Bordeaux estates. Beeswax and natural resin segments are capturing displaced volume as organic-certified wineries accelerate substitution timelines ahead of regulatory deadlines.
Direct procurement relationships between estate wineries and regional refiners are displacing distributor-mediated supply in premium segments. Napa Valley and Sonoma County vintners are sourcing custom color-matched formulations through contracted batch production rather than catalog SKUs. California's concentration of estate bottlers with in-house packaging design teams is driving this channel shift, compressing lead times for limited-release metallic and marbled variants.
Wine Bottle Sealing Wax Market Segmentation
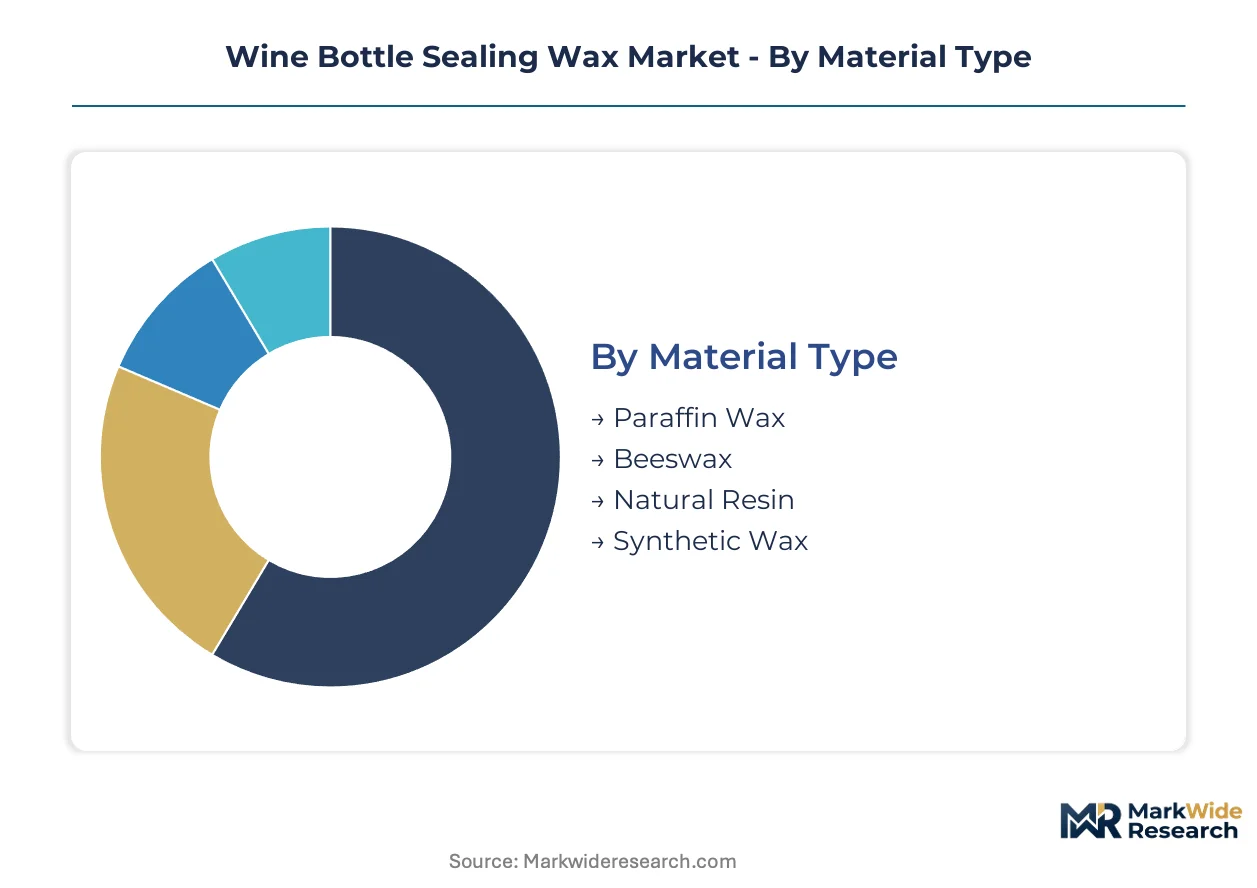
Wax formulation choices directly determine regulatory compliance pathways and margin structures across estate and commercial bottling operations. Material composition governs melting point engineering, drip profile consistency, and biodegradability credentials that differentiate premium positioning from commodity supply.
Material Type:
Volume applications favor petroleum-derived bases while premium segments migrate toward natural alternatives under tightening purity mandates.
- Paraffin Wax:Petroleum-derived formulations dominate high-throughput sparkling wine facilities with melting points engineered between 58°C and 62°C for rapid dip-cycle throughput. Prosecco and Cava bottlers in Spain and Italy specify this grade for cost-controlled 24-hour production cycles despite REACH-driven additive restrictions compressing supplier qualification timelines.
- Beeswax:Heritage-grade blends command premium positioning among Champagne houses and organic-certified estates seeking compostable closure credentials and controlled drip aesthetics. Bordeaux châteaux specify Kent-refined batches for limited releases where batch-to-batch viscosity consistency justifies pricing multiples unavailable in synthetic alternatives.
- Natural Resin:Plant-derived binders serve organic-certified wineries requiring petroleum-free supply chains under EU organic regulation compliance frameworks.
- Synthetic Wax:Polymer-engineered formulations deliver melting point precision for automated dipping systems in commercial bottling lines where consistency outweighs biodegradability priorities.
Today's leader: Paraffin Wax. Tomorrow's challenger: Beeswax.
Application Type:
Closure engineering diverges between still and effervescent formats, with pressure resistance and cork integration demands shaping formulation specifications.
- Red Wine:Estate bottlers in Napa Valley and Bordeaux favor wax-dipped finishes for reserve-tier Cabernet and Merlot releases, with drip-profile customization signaling craft authenticity against synthetic cork competition.
- White Wine:Chardonnay and Sauvignon Blanc producers specify lower-temperature formulations to prevent thermal degradation of delicate aromatics during dip application.
- Sparkling Wine:Champagne and Prosecco operations require pressure-rated seals with reinforced adhesion to withstand 5-6 atmospheres of internal carbonation, driving specification of high-tensile synthetic blends.
- Fortified Wine:Port and Sherry producers in Portugal and Spain utilize thicker deposit formulations to accommodate extended aging protocols and high-alcohol content exposure.
Sparkling Wine generates the steepest volume expansion trajectory as automation investments spread across Italian and Spanish bottling corridors.
Color Variant:
Pigmentation strategy separates catalog commodity supply from contracted custom production with direct margin implications.
- Opaque:Standard black, red, and cream formulations serve high-volume commercial bottling with minimal color-matching overhead and rapid inventory turns.
- Transparent:Clear wax variants showcase cork branding and vineyard embossing for estate wineries prioritizing visual heritage communication.
- Metallic:Gold, silver, and copper pigment matching commands premium positioning for anniversary releases and luxury tier positioning among California cult producers.
- Marbled:Multi-tone swirl effects require small-batch blending expertise, generating exclusivity premiums for vintage-specific limited editions.
Metallic variants capture the fastest margin expansion as direct procurement relationships displace distributor channels.
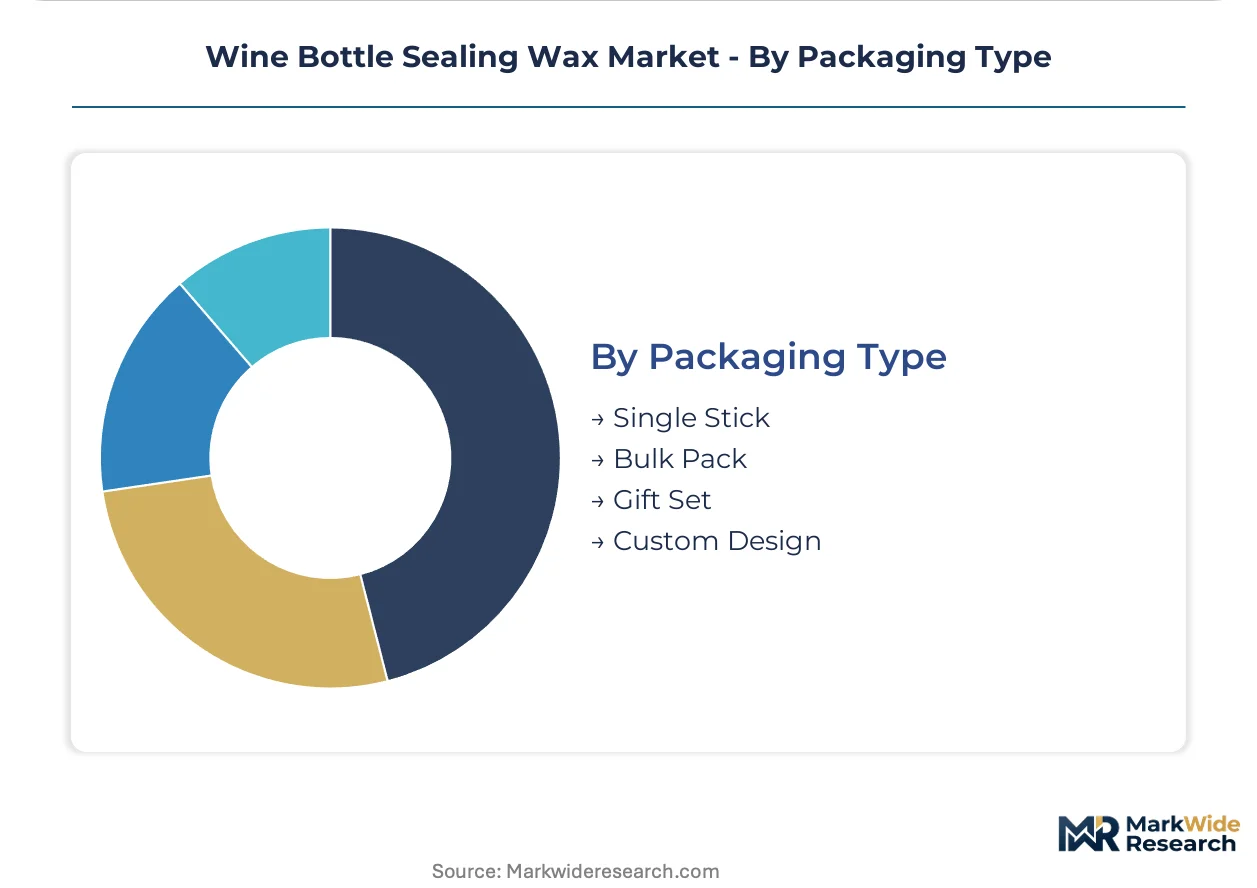
Packaging Type:
Format selection reflects operational scale, with bulk configurations gating access to ISO-certified supply and custom formats enabling brand differentiation.
- Single Stick:Retail-format wax sticks serve home winemakers and small-batch producers with low minimum order quantities and rapid fulfillment.
- Bulk Pack:Industrial totes and drums for automated bottling lines require food-contact certification and batch traceability documentation under FDA and REACH frameworks.
- Gift Set:Curated color assortments with dipping tools target direct-to-consumer channels and tasting room retail.
- Custom Design:Estate-specific color matching and embossed seal dies generate recurring revenue through contracted production relationships.
Bulk Pack configurations concentrate procurement volume among integrated refiners with ISO 22000 certification gates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between REACH-mandated reformulation in Europe and California's Proposition 65 disclosure requirements are redirecting procurement flows toward domestic refiners. Texas-based suppliers now capture Napa Valley estate contracts previously served by European importers.
United States
Napa Valley and Sonoma County vintners drive premium wax-seal adoption for reserve-tier releases. FDA food-contact regulations govern purity thresholds for domestic and export-bound production. Texas refiners leverage geographic proximity to California wine country, compressing lead times for custom metallic and marbled formulations.
France
Champagne houses and Bordeaux châteaux specify heritage-grade beeswax blends for limited releases and luxury positioning. REACH restrictions on petroleum-derived additives force systematic reformulation of paraffin-based sealing waxes. The Kent refining corridor across the English Channel anchors European heritage-grade supply, though Brexit customs friction exposes producers to intermittent delays.
Italy
Prosecco bottlers deploy precision temperature-controlled dipping rigs to maintain drip-profile uniformity across 24-hour production cycles. ECHA substance evaluations recategorize paraffin byproducts, triggering mandatory replacement cycles for suppliers serving sparkling wine operations. Veneto and Piedmont host the densest clusters of automated bottling facilities transitioning from synthetic cork enclosures.
Spain
Cava producers utilize high-tensile synthetic wax blends engineered for pressure-rated seals withstanding 5-6 atmospheres of internal carbonation. EU packaging waste directives shape formulation strategies for export-oriented bottlers. Catalonia concentrates commercial-scale operations where consistency and cost control outweigh biodegradability priorities.
Australia
Organic-certified wineries in South Australia and Victoria accelerate substitution timelines toward natural resin and beeswax segments ahead of regulatory deadlines. The country's national food safety regulator enforces import parity standards on wax purity. Barossa Valley estate bottlers source compostable closure credentials to differentiate premium releases in Asian export markets.
Wine Bottle Sealing Wax Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage-grade beeswax blending concentrated among European refiners and high-volume synthetic supply dominated by North American integrated producers. The market structure reflects a bifurcation between certified refiners serving estate wineries and commodity blenders supplying commercial bottling lines. Three archetypes occupy distinct positions: heritage beeswax specialists, petroleum-derived wax refiners, and custom color-matching formulators. Capacity expansion and ISO 22000 certification acquisition represent the dominant competitive moves, gating access to bulk pack procurement channels.
Among Texas-based refiners, Southwest Wax LLC occupies a position exemplifying geographic arbitrage strategy, while Calwax LLC represents the custom formulation archetype serving Napa Valley estates. The Darent Wax Company Ltd anchors European heritage-grade supply from its Kent refining facility. These three companies illustrate how regional regulatory divergence creates protected competitive positions: domestic US suppliers leverage FDA compliance timelines against REACH-driven European reformulation costs, while UK-based heritage specialists maintain relationships with Champagne houses despite Brexit-related friction.
| Leading Market Players |
|---|
| Southwest Wax LLC |
| Calwax LLC |
| Australian Wax Co |
| The Darent Wax Company Ltd |
| Blended Waxes Inc |
| The British Wax Refining Company Ltd |
| Westech Wax |
| Brick Packaging LLC |
| Oakbank Products Limited |
| Others |
Supply Flow & Price Mechanics
Polymer chemistry expertise concentrated in Texas and Kent refining corridors drives labor-cost differentials that widen pricing-tier spreads between heritage-grade beeswax blends and commodity paraffin formulations. REACH-mandated reformulation cycles in Europe compress supplier margins while California Proposition 65 compliance costs create arbitrage opportunities for domestic US refiners serving Napa Valley estates.
Pricing Analysis
Distributor margins on metallic and marbled custom formulations capture 35-50 point spreads over standard opaque SKUs, with direct-to-estate contracting displacing catalog pricing for limited releases. Price differentiation rests on ISO 22000 certification tier and batch-to-batch viscosity consistency rather than raw material base alone. Pricing pressure stems from petroleum feedstock volatility tracking crude indices, compressing margins in high-volume sparkling wine supply. Commercial bottling lines exhibit highest price sensitivity, while heritage Champagne houses prioritize batch quality over unit cost.
Supply Chain Analysis
California's domestic-content preferences under Proposition 65 disclosure requirements are reshaping sourcing toward Texas-based refiners for Napa Valley contracts. Raw material supply draws from petroleum derivatives, Kent-refined beeswax, and plant-derived natural resins. Single-source vulnerability concentrates in the Kent refining corridor serving European heritage-grade demand. Distribution runs through direct procurement relationships displacing distributor-mediated channels in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
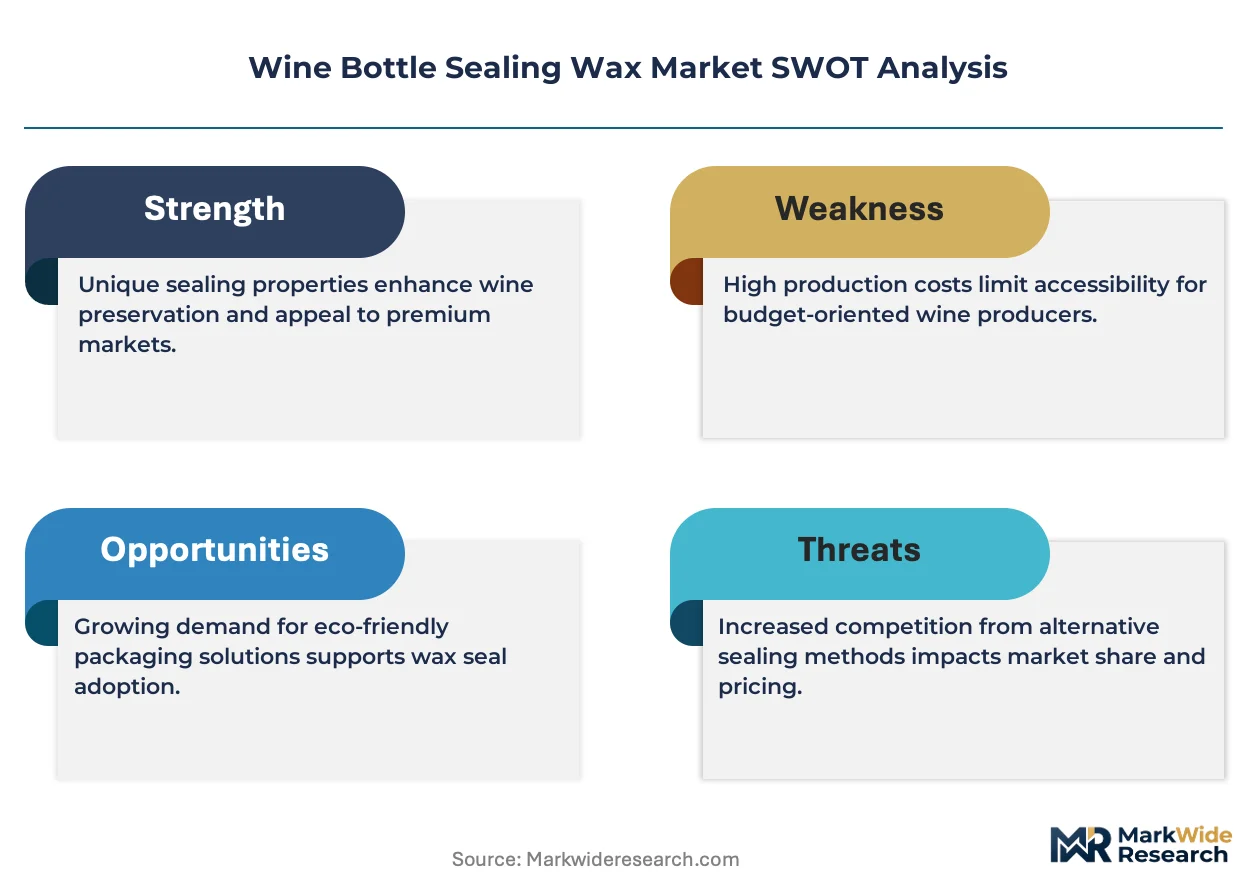
This market functions as a geographic-arbitrage play where REACH-driven European reformulation costs create protected competitive positions for domestic US suppliers serving California wine country under FDA timelines.
For Market Incumbents: To counter REACH additive restrictions filtering commodity suppliers, integrated refiners should pursue ISO 22000 certification gating bulk pack procurement and establish captive beeswax sourcing through backward integration into Kent refining relationships. Capacity addition in Texas preserves geographic proximity advantages against European importers facing customs friction.
For New Entrants and Emerging Players: Direct-to-estate digital channels enable white-space penetration among Sonoma County vintners seeking custom color-matched formulations with compressed lead times. Target organic-certified wineries in Australia and California accelerating substitution timelines toward natural resin segments. Lead with small-batch metallic pigment matching unavailable from catalog suppliers.
For Investors and Strategic Acquirers: Specialty chemicals divisions of diversified industrial conglomerates represent the most active acquirer category in this space, consolidating regional refiners to capture estate bottler procurement relationships. Long-term viability hinges on dual-jurisdiction compliance capabilities spanning FDA and REACH frameworks. Monitor ECHA substance evaluation cycles as inflection indicators for reformulation-driven supplier displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Acquisition | Gates access to bulk pack configurations for commercial bottling lines serving Prosecco and Cava operations. |
| Backward Integration into Beeswax Supply | Secures heritage-grade raw material access for Champagne house contracts amid Kent corridor concentration risk. |
| Custom Color-Matching Capability Buildout | Captures metallic and marbled formulation premiums from Napa Valley cult producers releasing vintage-specific editions. |
| Dual Jurisdiction Compliance Investment | Enables simultaneous FDA and REACH qualification to serve estate wineries across Atlantic supply corridors. |
| Precision Temperature-Controlled Dipping Rig Partnership | Automates quality consistency for high-volume Italian and Spanish sparkling wine bottlers deploying 24-hour production cycles. |
Methodological Framework
Bottom-up winery procurement modeling reconciled against top-down refiner capacity tracking forms the analytical core of this study. Primary interviews with estate bottling managers, commercial packaging line engineers, wax refinery technical directors, and distributor procurement leads combined with secondary validation from FDA food-contact guidance documents, ECHA substance evaluation databases, customs trade records, and ISO certification registries. Triangulation across supply-side capacity assessments and demand-side adoption patterns ensures coverage of both heritage-grade beeswax blending and high-volume synthetic formulation segments.
Input-output matrices map material type, application format, color variant, and packaging configuration against regional regulatory clusters and end-use scale tiers across the projection horizon. CAGRs derive from segmented adoption curves weighted by estate bottler concentration in France, Italy, and California. Forecast inputs incorporate REACH reformulation timelines, automation investment cycles in Italian Prosecco corridors, and organic certification penetration rates in Australian export markets.
The model assumes a particular technology adoption path; alternative pathways for precision temperature-controlled dipping automation would alter the outlook for labor-cost compression in commercial bottling. Forecasts reflect assumptions regarding regulatory divergence persistence and petroleum feedstock price regimes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages Packaging
APAC Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Corrugated Wine Carrier Market
Alcoholic Beverages Packaging
Cluster Packaging for Beer Market
Alcoholic Beverages Packaging
Global Cider Packaging Market
Alcoholic Beverages Packaging
Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Beer Packaging Market
Alcoholic Beverages Packaging
Wine Totes Packaging Market
Alcoholic Beverages Packaging
US Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcohol Packaging Market
Alcoholic Beverages Packaging
Europe Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Alcoholic Beverage Packaging Market
Alcoholic Beverages Packaging
Middle East and Africa Alcoholic Drinks Packaging Market
Alcoholic Beverages Packaging
Global Wine Packaging Market