
 Filmic Tapes Market | 2026-2036
Filmic Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Filmic Tapes Market Analysis
ISO 9001 quality management certification is reorganizing supplier eligibility across automotive and electronics procurement chains, favoring manufacturers with documented process control. 3M leverages its materials science portfolio to sustain premium positioning in specialty adhesive formulations. Tesa SE anchors European supply through vertically integrated film coating operations in Germany. Avery Dennison Corporation competes on brand strength and direct OEM relationships in North American packaging segments.
Filmic tapes are pressure-sensitive adhesive constructions laminated onto polymeric film substrates such as polyester, polyimide, or polypropylene, engineered for dimensional stability, chemical resistance, and clean removability in precision assembly operations. Double-sided configurations command the highest margin pools in electronics display lamination, while single-sided variants dominate mature packaging sealing applications where cost efficiency outweighs performance premiums. Specialty tapes incorporating thermally conductive or electrically insulating fillers represent the fastest-growing product type as electric vehicle battery module assembly expands.
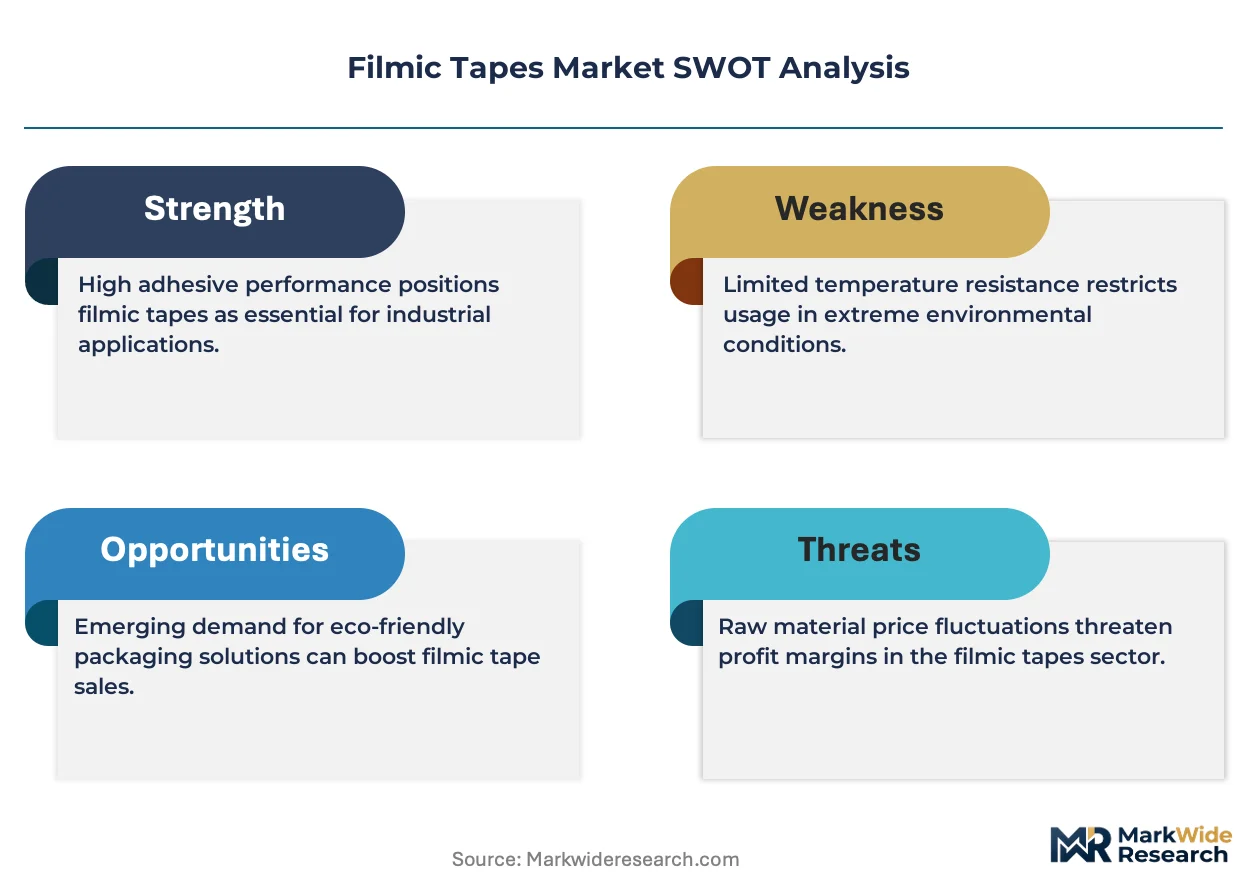
EPA regulations on hazardous air pollutants from adhesive manufacturing constrain solvent-based formulation capacity in the United States, while REACH registration requirements in Europe restrict certain phthalate plasticizers used in tape backings. The EU Green Deal carbon border adjustments will incrementally raise compliance costs for imported filmic tape substrates from carbon-intensive production origins. Stakeholders must monitor evolving substance restriction lists and assess captive coating capacity versus contract manufacturing trade-offs before committing to regional supply base expansion.
Market Dynamics
Electronics miniaturization and thermal management requirements are compressing tape specification cycles, forcing adhesive suppliers to synchronize formulation development with semiconductor packaging roadmaps and battery module assembly protocols.
Growth Catalysts
- EV Battery Assembly:Electric vehicle manufacturers are expanding thermally conductive tape procurement for cell-to-cell bonding and module encapsulation, creating dedicated supply agreements with coating specialists.
- REACH Substance Restrictions:European phthalate limitations on tape backings are accelerating solvent-free acrylic migration, rewarding early reformulators with automotive qualification status.
- Display Lamination:Foldable OLED manufacturing in Korea and China is consuming ultra-thin double-sided polyester tapes for hinge protection and cover glass bonding.
Market Restraints
- Petrochemical Feedstock Volatility:Polyimide and polyester substrate costs fluctuate with purified terephthalic acid and pyromellitic dianhydride pricing, compressing margin predictability for coating operations.
- East Asian Supply Concentration:Over 60% of biaxially oriented polyester film capacity sits in China and Taiwan, creating geographic vulnerability for non-integrated tape converters.
- Silicone Adhesive Performance Ceiling:High-temperature electronics applications exceeding 200°C expose the thermal stability limits of conventional silicone formulations, restricting penetration into aerospace engine compartment bonding.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and mobile device assembly are attracting tape converters to establish local slitting and distribution operations near Chennai and Noida clusters.
- EU Green Deal Carbon Border Adjustments:Import levies on carbon-intensive substrates will advantage European coating operations with renewable energy sourcing, creating margin expansion for domestic producers.
- Direct-to-Factory Digital Platforms:B2B procurement portals are disintermediating traditional industrial distributors for standardized packaging and masking tape categories, enabling price transparency and volume aggregation.
Industry Challenges
- Formulation Chemist Scarcity:Solvent-free adhesive development requires expertise in UV-curable and hot-melt polymerization that outpaces current technical training pipeline output.
- ISO 9001 Recertification Burden:Automotive OEMs are tightening audit frequency and documentation depth, consuming quality management resources at mid-sized coating operations.
- Legacy Equipment Retrofit Costs:Converting solvent-based coating lines to aqueous or UV-curable systems demands capital outlays that strain private-equity-owned tape manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filmic Tapes Market |
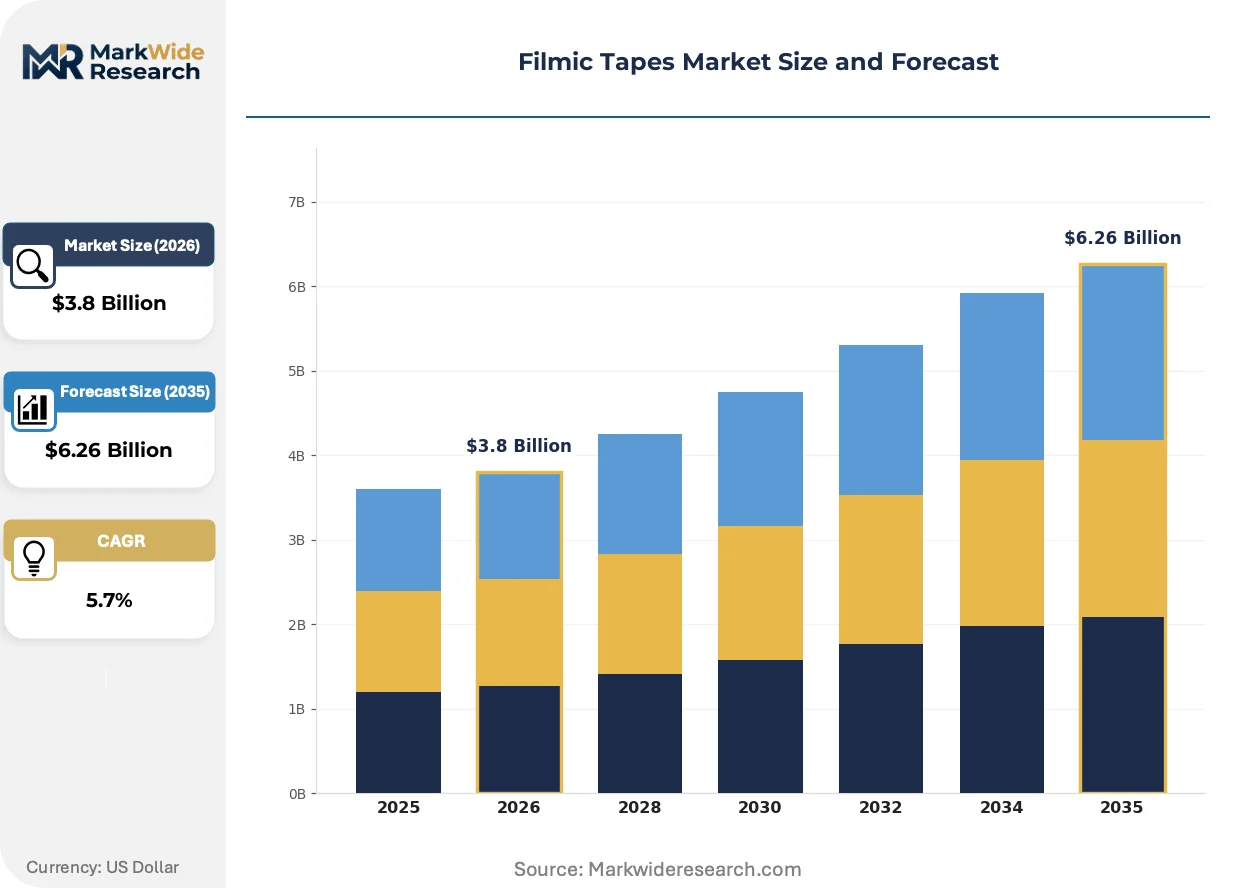
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Single-Sided, Transfer, Specialty Application: Electronics, Automotive, Packaging, Construction End User: Manufacturers, Distributors, Retailers, Contractors Delivery Mode: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | 3M, Tesa SE, Avery Dennison Corporation, Nitto Denko Corporation, Saint-Gobain, Lintec Corporation, Scapa Group plc, Berry Global Inc., Intertape Polymer Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filmic Tapes Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to redefine adhesive performance benchmarks, with substrate-engineering and curing-process innovations outpacing traditional formulation refinement.
Thermally conductive acrylic tapes loaded with boron nitride or aluminum oxide fillers are displacing mechanical fastening and liquid adhesive dispensing in electric vehicle battery pack assembly. Automotive tier-one suppliers in Germany and China are qualifying these tapes for cell-to-cell bonding at volumes exceeding 50 meters per battery module. The shift is compressing cycle times from hours to minutes while eliminating cure-stage bottlenecks in high-throughput production lines.
REACH Annex XVII restrictions on cyclic siloxanes are forcing tape manufacturers to reformulate release coatings and pressure-sensitive adhesives for European medical and electronics markets. ECHA substance evaluation timelines are compressing reformulation windows to 18-24 months, forcing parallel development tracks rather than sequential qualification. German and French medical device OEMs are now requiring D4/D5/D6-free declarations for all adhesive components in diagnostic equipment.
Direct long-term agreements between electronics OEMs and specialty tape coaters are fragmenting traditional distribution channels for high-performance product categories. Contract terms now specify dedicated production slots, custom width slitting, and bonded inventory programs rather than spot purchasing through industrial distributors. This pattern is most pronounced in Korea and Taiwan, where display panel manufacturers are consolidating supplier bases to three approved coating operations per substrate type.
Filmic Tapes Market Segmentation
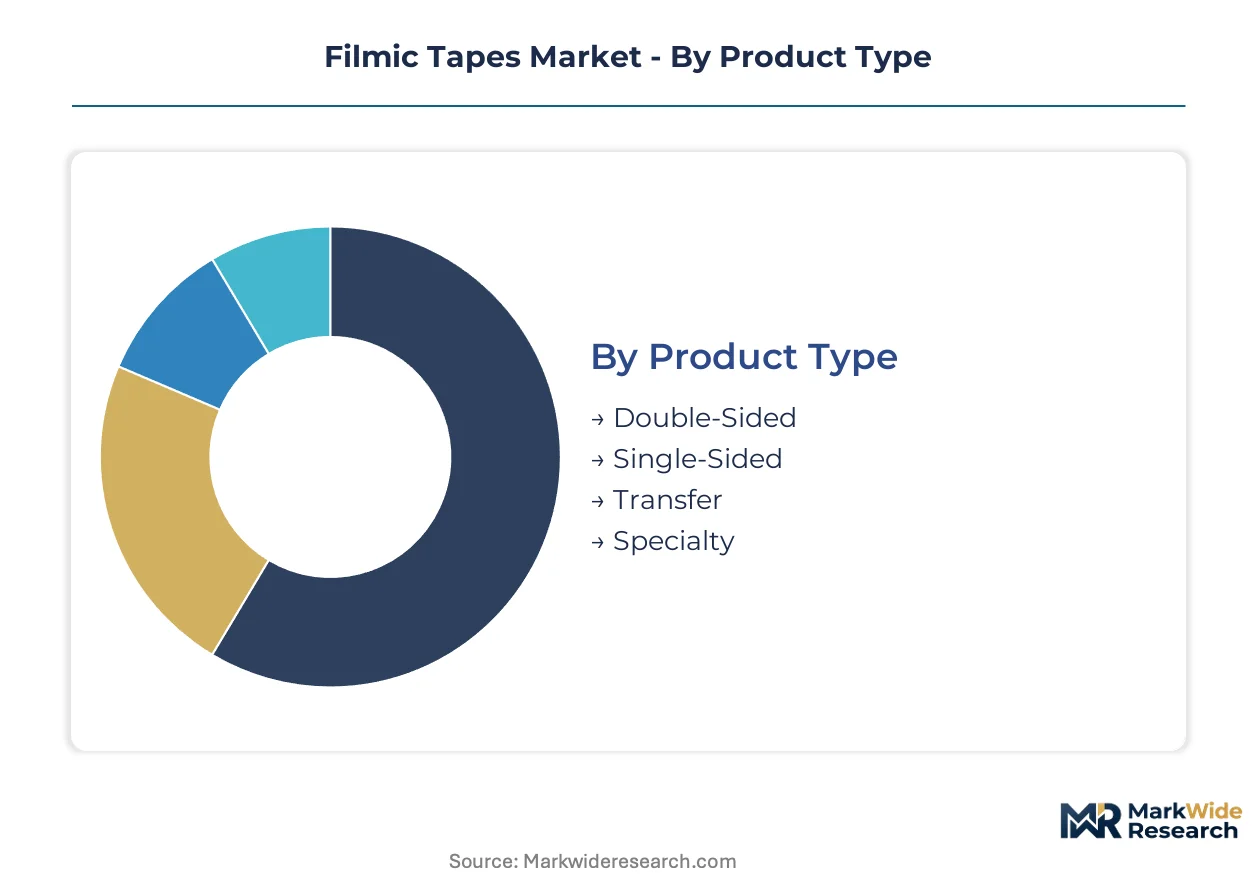
Filmic tape procurement patterns diverge sharply across product constructions and buyer channels, with electronics OEMs driving specification intensity while packaging buyers prioritize cost efficiency. Understanding these segment boundaries clarifies where formulation investments yield returns versus where price competition dominates.
Product Type:
Domestic consumption concentrates in single-sided variants for packaging and masking, while double-sided and specialty grades generate disproportionate export revenue from electronics clusters in Korea, Taiwan, and Germany.
- Double-Sided:Pressure-sensitive adhesive coats both faces of polyester or polyimide substrates, enabling hinge bonding in foldable displays and cell-to-cell attachment in EV battery modules. Korean display panel manufacturers in Gyeonggi Province consume ultra-thin configurations under 50 micrometers for cover glass lamination, with procurement volumes scaling alongside OLED fab capacity expansion.
- Specialty:Boron nitride or aluminum oxide fillers embedded in acrylic matrices deliver thermal conductivity for power electronics and battery thermal interface management. German automotive tier-one suppliers in Baden-Württemberg are qualifying these tapes for 800V battery architectures, where dielectric strength and thermal stability requirements exceed conventional adhesive capabilities.
- Single-Sided:Cost-optimized polypropylene or polyester constructions dominate carton sealing and surface protection in high-volume packaging operations.
- Transfer:Adhesive-only layers without carrier substrates enable precise thickness control in semiconductor die attach and microelectronic assembly.
Single-sided configurations hold the largest share; momentum sits with specialty thermally conductive grades.
Application:
Cost tiers separate these segments, with electronics and automotive commanding 3-5x price multiples over construction and packaging due to qualification burdens and performance specifications.
- Electronics:Display lamination, semiconductor packaging, and PCB masking drive demand for ultra-clean, low-outgassing formulations. Chinese contract manufacturers in Shenzhen and Dongguan are expanding procurement of double-sided polyester tapes for smartphone and tablet assembly, with specifications tightening as bezel widths shrink.
- Automotive:Battery module bonding, interior trim attachment, and wire harness wrapping require temperature resistance from -40°C to 150°C and long-term aging stability. European OEMs through KBA certification pathways are mandating REACH-compliant solvent-free acrylics for all interior applications.
- Packaging:Carton sealing and label protection consume commodity-grade polypropylene tapes where price per meter dominates supplier selection.
- Construction:HVAC insulation facing, vapor barrier sealing, and temporary surface protection employ UV-stabilized polyethylene tapes in building envelope applications.
Electronics captures the highest absolute revenue; automotive is climbing the fastest as EV production scales.
End User:
Volume concentration sits with manufacturers, though distributors retain influence in fragmented construction and maintenance segments where technical specification depth varies.
- Manufacturers:Electronics and automotive OEMs with captive engineering teams drive custom formulation development, bonded inventory programs, and direct long-term supply agreements. These buyers specify adhesive chemistry, carrier thickness, and release liner configuration rather than accepting catalog standards.
- Distributors:Industrial supply houses aggregate demand from mid-sized converters and maintenance operations, carrying inventory for packaging and masking grades where immediate availability outweighs technical customization.
- Retailers:Consumer-facing channels move small-format rolls for home improvement and light industrial use, with private-label penetration highest in North American home center chains.
- Contractors:Construction trades purchase through wholesale channels for job-specific quantities, with price sensitivity elevated in residential building segments.
Manufacturers hold the largest share; momentum sits with direct procurement models displacing distribution.
Delivery Mode:
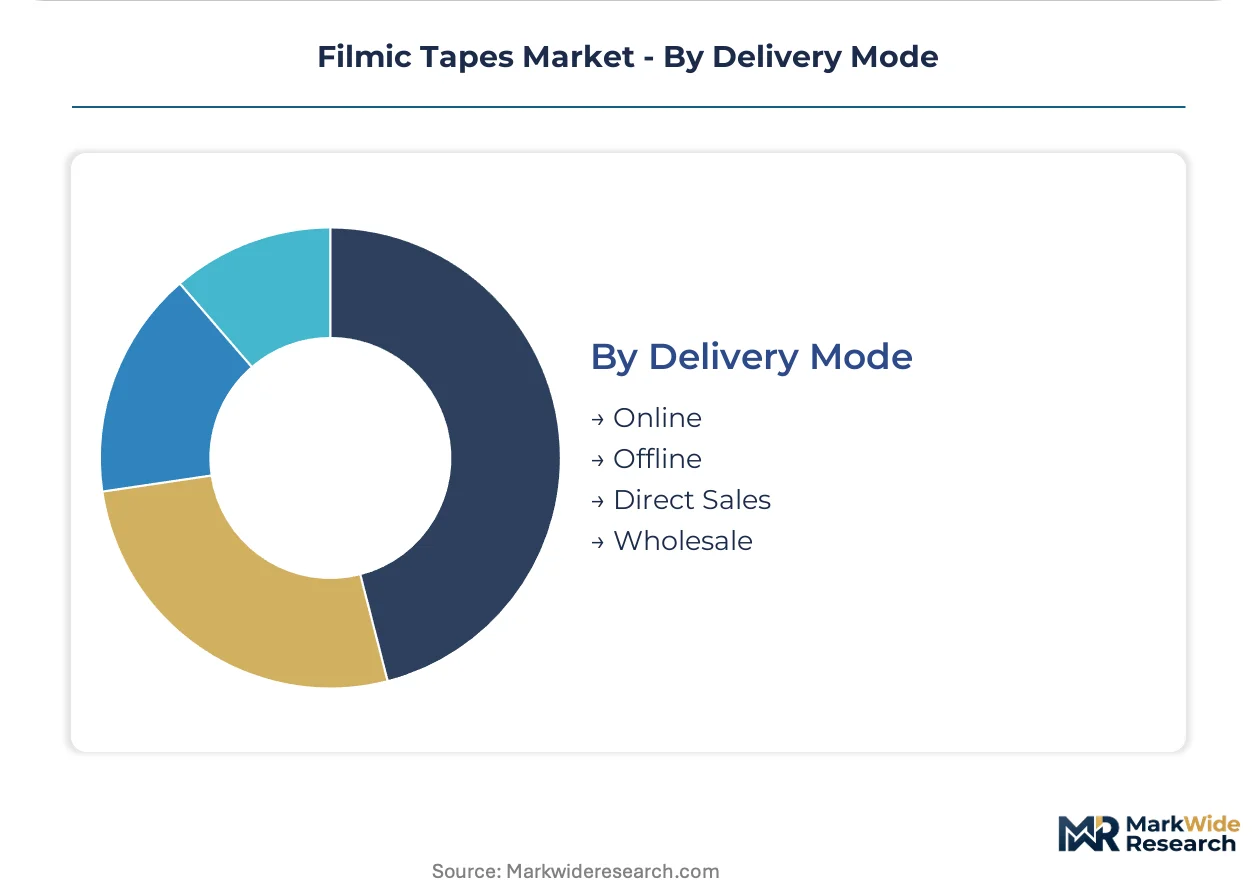
Supply concentration shapes channel strategy, with integrated coaters favoring direct sales for high-performance grades while commodity converters rely on wholesale aggregation.
- Direct Sales:Specialty tape coaters maintain field engineering teams for electronics and automotive accounts, embedding technical support into contract structures. Korean display manufacturers now require dedicated production slots with quarterly volume commitments rather than spot purchasing.
- Online:B2B procurement portals are gaining traction for standardized packaging and masking tapes, enabling price transparency and volume aggregation for mid-sized converters.
- Offline:Traditional industrial distributors with regional stocking points serve construction and maintenance segments where immediate availability drives purchasing decisions.
- Wholesale:Bulk slitting and repackaging operations aggregate demand from fragmented end users, particularly in emerging markets where converter infrastructure remains underdeveloped.
Direct sales holds the largest share in value terms; online channels are gaining share fastest in commodity grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives for semiconductor and mobile device assembly are redirecting procurement patterns across Asia-Pacific manufacturing clusters. EPA hazardous air pollutant constraints and REACH substance restrictions are reshaping formulation standards in Western markets. Carbon border adjustments under the EU Green Deal are incrementally altering substrate sourcing economics for coating operations.
China
Domestic electronics assembly and automotive production clusters drive bulk consumption of high-performance filmic tapes. MIIT dual carbon goals are pressuring coating operations to migrate from solvent-based acrylics toward aqueous formulations. Shenzhen and Dongguan contract manufacturers are expanding procurement of double-sided polyester tapes for smartphone and tablet assembly as bezel widths shrink.
Germany
Automotive tier-one suppliers in Baden-Württemberg are qualifying thermally conductive tapes for 800V battery architectures. KBA certification pathways are mandating REACH-compliant solvent-free acrylics for all interior applications. Vertically integrated film coating operations in the country anchor European supply for specialty adhesive formulations.
United States
Electronics manufacturers are expanding adhesive tape procurement for display bonding and thermal management applications. EPA regulations on hazardous air pollutants from adhesive manufacturing constrain solvent-based formulation capacity. Direct OEM relationships in North American packaging segments favor brand strength and technical service capabilities.
South Korea
Foldable OLED manufacturing is consuming ultra-thin double-sided polyester tapes for hinge protection and cover glass bonding. Display panel manufacturers in Gyeonggi Province are consolidating supplier bases to three approved coating operations per substrate type. MFDS-equivalent substance declarations are tightening for medical device adhesive components.
India
PLI scheme incentives for semiconductor and mobile device assembly are attracting tape converters to establish local slitting and distribution operations. BIS quality standards are reorganizing supplier eligibility across automotive and electronics procurement chains. Chennai and Noida clusters are emerging as concentration points for converter infrastructure investment.
Filmic Tapes Market Vendor Landscape
Listed leaders compete with private specialists across formulation depth and geographic coverage, creating a tiered structure where scale and specialization coexist. The market segments into integrated material science conglomerates, regional coating specialists with captive film production, and mid-sized converters focused on slitting and distribution. Three archetypes dominate: vertically integrated substrate-to-adhesive coaters, formulation-focused technology licensors, and volume-driven commodity converters. Competitive moves center on solvent-free formulation migration and direct long-term supply agreements with electronics OEMs.
Within the integrated materials tier, 3M leverages its portfolio breadth across specialty adhesive formulations. Tesa SE anchors European supply through German-based film coating operations. Avery Dennison Corporation occupies a position in North American packaging segments built on brand recognition and OEM relationship depth.
| Leading Market Players |
|---|
| 3M |
| Tesa SE |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Saint-Gobain |
| Lintec Corporation |
| Scapa Group plc |
| Berry Global Inc. |
| Intertape Polymer Group Inc. |
| Others |
Supply Flow & Price Mechanics
Biaxially oriented polyester film capacity utilization above 85% in East Asian coating clusters compresses margin buffers for non-integrated converters while anchoring price floors for specialty grades. REACH-compliant solvent-free acrylic formulations command 40-60% premiums over commodity solvent-based tapes, with automotive OEMs absorbing these differentials through bonded inventory programs.
Pricing Analysis
Certification level (ISO 9001 automotive-grade versus industrial-standard) creates the primary spread between specialty and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels segments the market: premium grades for EV battery thermal interface management, standard double-sided tapes for display lamination, and economy polypropylene variants for carton sealing. Cost compression in the economy tier is intensifying because Chinese converters are expanding aqueous coating capacity. Packaging buyers exhibit highest price sensitivity, while automotive tier-one suppliers prioritize qualification stability over per-meter cost.
Supply Chain Analysis
Inventory lead times for polyimide substrates now stretch 12-16 weeks, forcing tape coaters to pre-position bonded stock near Korean and German automotive clusters. Supply concentrates in China, Taiwan, and Germany: over 60% of biaxially oriented polyester film capacity sits in China and Taiwan, while German operations anchor European specialty coating. Raw material dependencies draw from purified terephthalic acid, pyromellitic dianhydride, and acrylic monomer feedstocks. Single-source vulnerability for ultra-thin polyester below 25 micrometers threatens display tape supply continuity. Distribution runs through direct long-term agreements for high-performance grades, with industrial distributors retaining packaging and masking segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid adhesive dispensing systems and mechanical fastening technologies are encroaching on tape applications in EV battery assembly, forcing incumbents to defend substitution risk through performance differentiation and captive customer relationships.
For Market Incumbents: Secure solvent-free formulation capacity ahead of REACH Annex XVII expansion into cyclic siloxane restrictions. Deepen backward integration into biaxially oriented polyester film production to offset East Asian supply concentration. Lock direct long-term agreements with Korean display manufacturers through dedicated production slots and custom slitting capabilities. Defend against liquid adhesive substitution by qualifying thermally conductive tapes at 800V battery architectures where dielectric strength requirements exceed mechanical alternatives. For New Entrants and Emerging Players: Technical service gaps in Indian electronics clusters present immediate white-space opportunity, as PLI scheme incentives attract semiconductor assembly without established local coating infrastructure. Target Chennai and Noida converter operations with slitting and distribution partnerships rather than greenfield coating investment. Penetrate through B2B procurement portals for standardized packaging grades where price transparency disintermediates traditional distributors. Qualify BIS standards compliance early to access automotive procurement chains as domestic OEMs expand. For Investors and Strategic Acquirers: Regional coating specialists with captive film production and established automotive qualification status represent the highest-conviction acquisition archetype. Long-term viability hinges on solvent-free migration completion and EV battery thermal interface share capture. Monitor ECHA substance evaluation timelines for D4/D5/D6 restriction announcements as inflection indicators for reformulation capex cycles and competitive shakeout acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Formulation Migration | REACH compliance locks in automotive qualification status ahead of phthalate restriction expansion. |
| Backward Integration into Film Substrates | Captive polyester supply insulates margin from purified terephthalic acid volatility. |
| Direct OEM Supply Agreements | Korean display manufacturers now require quarterly volume commitments rather than spot purchasing. |
| India Converter Infrastructure Investment | PLI scheme incentives attract semiconductor assembly without established local slitting operations. |
| Thermally Conductive Grade Qualification | 800V battery architectures demand dielectric strength exceeding conventional adhesive capabilities. |
Methodological Framework
Operator-level perspectives from coating plant managers, automotive tier-one procurement leads, electronics OEM adhesive engineers, and industrial distribution channel partners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings of listed materials companies, ECHA substance registration databases, and MIIT dual carbon policy documentation. Bottom-up volume estimates from substrate consumption patterns triangulated against top-down market sizing from adhesive formulation capacity announcements.
Sensitivity analysis tested forecast robustness across petrochemical feedstock price scenarios and regulatory compliance timing variations. The analytical framework modeled product type, application, end-user channel, and regional production hub dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by pricing tier mix, with EV battery thermal interface demand and foldable OLED display lamination intensity as primary industry-specific inputs.
Underlying assumptions cover REACH substance restriction implementation timelines and MIIT aqueous coating migration enforcement, with deviation risk concentrated in East Asian supply disruption events and faster-than-expected silicone adhesive thermal stability breakthroughs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Wire Harness Tape Market
Tapes
Heat Activated Tear Tape Market
Tapes
PVC Tapes Market
Tapes
Heat Sealing Tape Market
Tapes
Painting Masking Tapes Market
Tapes
Carton Sealing Tape Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Global Non Woven Tape Market
Tapes
Edge Band Tapes Market
Tapes
Strapping Tapes Market
Tapes
Dicing Tapes Market
Tapes
Tape Dispenser Market
Tapes
High Bond Tape Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Europe Packaging Tapes Market
Tapes
Glue Tape Market