
 Asia-Pacific Packaging Tapes Market | 2026-2036
Asia-Pacific Packaging Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Packaging Tapes Market Outlook
E-commerce fulfillment is pivoting toward higher-tensile, low-noise tape specifications as automated sortation centers multiply across the region. 3M Company leverages its adhesive chemistry portfolio to dominate high-performance segments in Japan and South Korea. Nitto Denko anchors its position through precision coating capabilities serving electronics OEMs with clean-room-compatible tape grades.
Asia-Pacific packaging tapes are pressure-sensitive adhesive strips, typically 25–75 microns thick, composed of oriented polypropylene or PVC film coated with hot-melt, acrylic, or solvent-based adhesives, designed to seal corrugated fiberboard cases and unitize palletized loads. Polypropylene tapes occupy the volume core due to cost efficiency in high-speed applicators, while acrylic adhesive formulations capture expanding share in temperature-variable logistics lanes. Water-based adhesives are gaining traction as food and beverage exporters adapt to tightening volatile organic compound limits.
China's SAMR enforces GB standards on adhesive content and labeling transparency, while India's BIS certification mandates tensile strength benchmarks for industrial packaging grades. Japan's METI circular economy guidelines pressure converters toward thinner calipers and recyclable film constructions. Stakeholders must calibrate product portfolios against divergent national compliance timelines rather than treating the region as a uniform specification zone.
Market Dynamics
Automated carton-sealing lines across Asia-Pacific fulfillment centers are forcing adhesive reformulation and caliper standardization at speeds legacy coating assets cannot match. China's SAMR enforcement of GB standards on volatile organic compound content is compressing solvent-based adhesive share while accelerating water-based and hot-melt line conversions.
Growth Catalysts
- Cross-border e-commerce fulfillment:Platforms operating automated sortation hubs in China's Yangtze River Delta and India's Maharashtra corridor are specifying low-noise, high-tensile tape grades that reduce line stoppages.
- BIS certification mandates:India's Bureau of Indian Standards tensile strength benchmarks for industrial packaging grades are disqualifying uncoated imports and redirecting procurement toward certified domestic converters.
- Hot-melt adhesive advances:Metallocene polyolefin formulations are extending temperature performance windows for acrylic tapes used in Southeast Asian ambient-to-cold logistics lanes.
Market Restraints
- Propylene monomer volatility:BOPP film costs fluctuate with naphtha-cracker economics in South Korea and Singapore, squeezing converter margins on fixed-price annual contracts.
- Solvent-based adhesive phase-out friction:China's MEE enforcement timelines for volatile organic compound limits are stranding capital in legacy coating assets before depreciation cycles complete.
- Paper tape substitution:Japan's METI circular economy guidelines and brand sustainability commitments are accelerating kraft paper-based sealing alternatives in premium consumer goods segments.
Strategic Opportunities
- Vietnam's northern industrial zones:Electronics contract manufacturers relocating from China are importing tape specifications that exceed domestic Vietnamese converter capabilities, creating tier-one supplier entry points.
- Recyclable film constructions:Japan's container-to-container recycling mandates for polyethylene films are rewarding converters with verified mono-material constructions compatible with existing reprocessing infrastructure.
- Blockchain-enabled provenance tracking:Food and beverage exporters in Australia and New Zealand are piloting adhesive-lot traceability to satisfy supermarket chain ethical sourcing audits.
Industry Challenges
- Coating technician scarcity:Precision adhesive weight control for clean-room electronics grades requires skills concentrated in Japan and South Korea, limiting expansion in lower-cost manufacturing locations.
- Dual certification timelines:Exporters serving both China's SAMR GB standards and India's BIS regimes face non-overlapping testing protocols that extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Packaging Tapes Market |
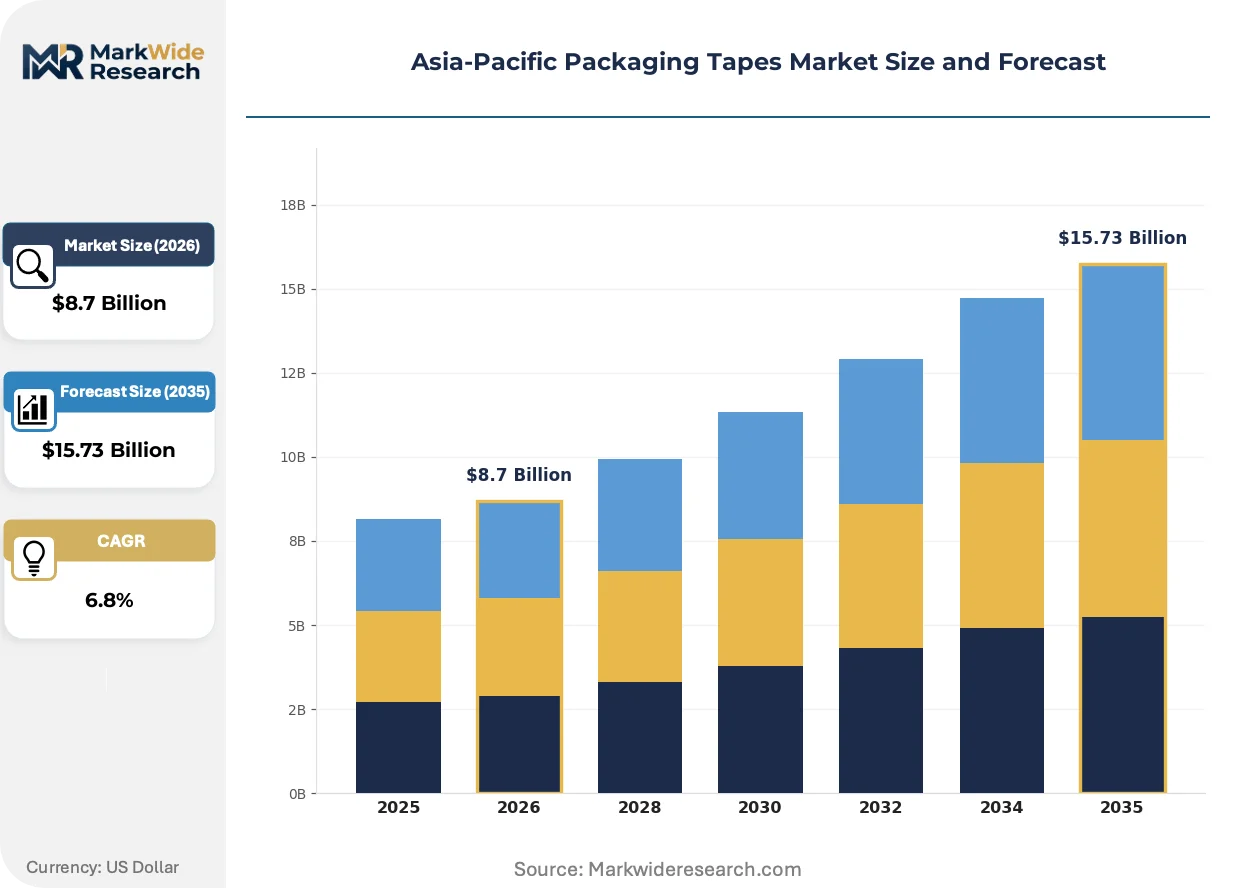
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
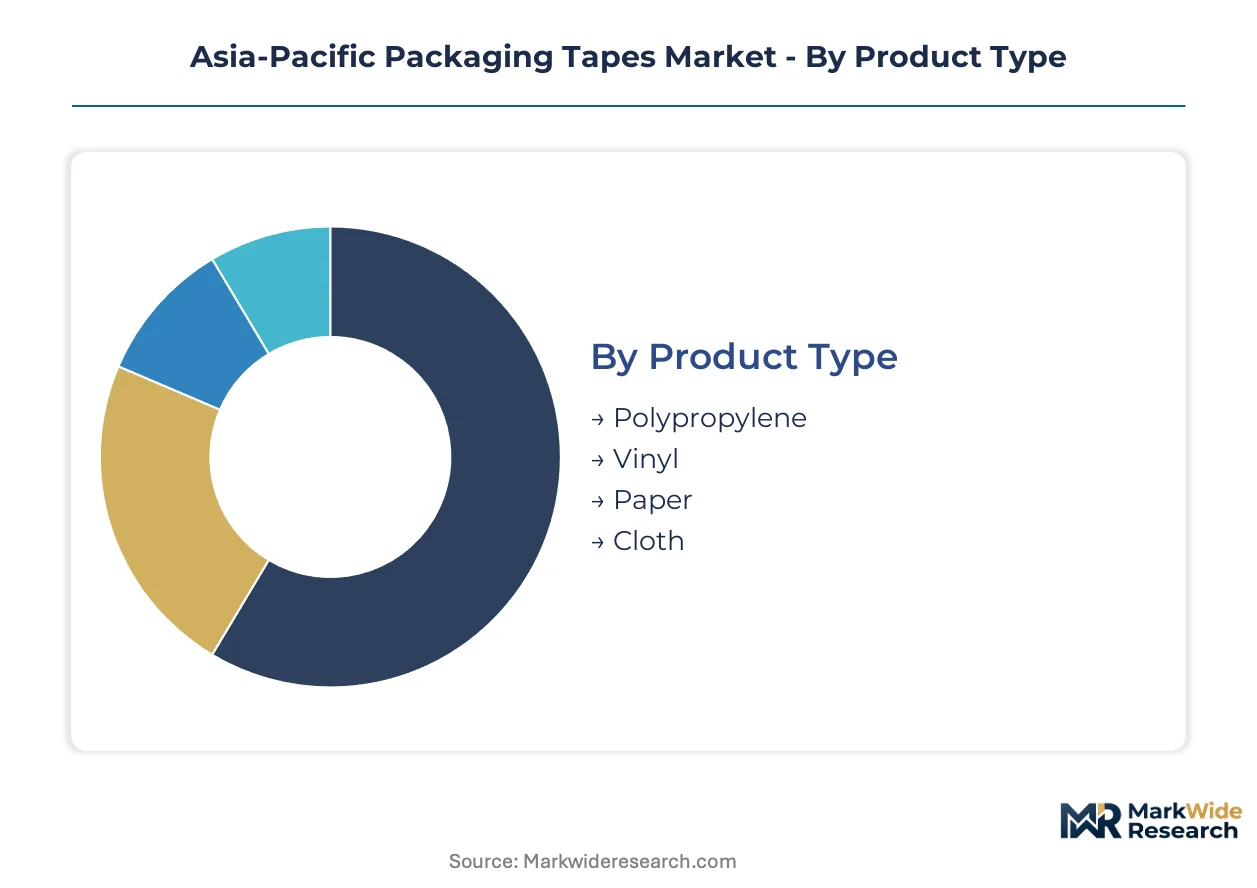
| Segmentation | Product Type: Polypropylene, Vinyl, Paper, Cloth End Use Industry: Food & Beverage, Consumer Goods, Electronics, Pharmaceuticals Thickness: Thin, Medium, Thick, Ultra-Thick Adhesive Type: Hot Melt, Acrylic, Water-Based, Solvent-Based |
| Companies Covered | 3M Company, AVERY DENNISON CORPORATION, Nitto Denko, Intertape Polymer Group Inc., CCT Tapes, Berry Global Inc., Henkel AG and Corporation, Saint-Gobain, Advance Tapes International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Packaging Tapes Market Strategic Shifts
Adhesive chemistry and substrate engineering are converging to meet performance specifications that automated fulfillment equipment demands. Three developments are compressing legacy product cycles and redrawing competitive boundaries.
Water-based acrylic emulsions with enhanced shear resistance are rewriting the cost-performance tradeoff for temperature-variable logistics. Third-party logistics operators in Australia's east coast corridor are specifying these formulations for ambient-to-refrigerated lane consolidation. The technology is compressing the premium historically commanded by solvent-based natural rubber adhesives in high-humidity environments.
China's GB standards on adhesive content disclosure and labeling transparency are forcing reformulation documentation through the supply chain. Converters must now certify volatile organic compound levels at the resin source, not just finished tape. Electronics OEMs in South Korea and Japan are responding by qualifying suppliers with integrated resin-to-tape traceability systems.
Direct procurement from tape converters by e-commerce platform operators is disintermediating traditional packaging distributors in high-volume corridors. Amazon's India fulfillment network and Shopee's Southeast Asian hubs are negotiating annual tonnage contracts that specify applicator compatibility and line-speed performance metrics. This pattern is most visible in India's western industrial corridors and China's Zhejiang province.
Asia-Pacific Packaging Tapes Market Segmentation
Segmentation in Asia-Pacific packaging tapes reveals how converter capabilities align with divergent national compliance timelines and end-use performance thresholds. Product specifications that satisfy Japan's METI circular economy guidelines often fail India's BIS tensile benchmarks, forcing portfolio stratification rather than regional standardization.
Product Type:
Customization intensity varies sharply across this category, from commodity grades suited to high-speed automated lines to specialty constructions demanding precision coating assets.
- Polypropylene:Biaxially oriented polypropylene film dominates high-volume carton sealing with cost efficiency in 25–50 micron calipers. Demand clusters in China's Zhejiang and Guangdong provinces where e-commerce fulfillment centers specify low-noise unwind properties for automated applicators. BOPP film costs track naphtha-cracker economics in South Korea and Singapore, squeezing converter margins on fixed-price contracts.
- Vinyl:PVC film constructions deliver superior conformability on irregular surfaces and extreme temperature stability from -10°C to 60°C. Japanese electronics OEMs in Osaka and Nagoya industrial corridors specify vinyl grades for clean-room-compatible precision coating. The segment commands premium positioning where acrylic adhesive formulations require substrate dimensional stability.
- Paper:Kraft paper tapes with water-activated adhesives serve Japan's METI circular economy mandates and brand sustainability commitments in premium consumer goods. The segment accelerates as mono-material constructions gain verification for container-to-container recycling.
- Cloth:Woven fabric backings reinforced with glass filaments unitize heavy palletized loads in India's western industrial corridors. BIS certification requirements for tensile strength are disqualifying uncoated imports and redirecting procurement toward certified domestic converters.
Leading the category by volume: Polypropylene. Expanding most quickly: Paper.
End Use Industry:
Application-driven specification divergence separates price-sensitive bulk logistics from precision-tolerance electronics assembly.
- Food & Beverage:Temperature-variable logistics lanes from Australia's ambient corridors to Southeast Asian cold chains specify water-based acrylic emulsions with enhanced shear resistance. Exporters pilot blockchain-enabled adhesive-lot traceability to satisfy supermarket chain ethical sourcing audits in Australia and New Zealand.
- Consumer Goods:Cross-border e-commerce platforms operating automated sortation hubs in China's Yangtze River Delta and India's Maharashtra corridor specify low-noise, high-tensile tape grades that reduce line stoppages. Direct procurement from converters is disintermediating traditional packaging distributors.
- Electronics:Clean-room-compatible tape grades demand precision coating capabilities concentrated in Japan and South Korea. Coating technician scarcity limits expansion in lower-cost manufacturing locations despite electronics contract manufacturers relocating to Vietnam's northern industrial zones.
- Pharmaceuticals:Adhesive content disclosure requirements under China's GB standards force reformulation documentation through the supply chain. Converters must certify volatile organic compound levels at the resin source, not just finished tape.
Dominant by procurement scale: Consumer Goods. Steepest specification escalation: Electronics.
Thickness:
Caliber selection traces a direct path from protection requirements through material cost to applicator compatibility.
- Thin:25–35 micron constructions optimize film economics for high-speed automated lines in China's coastal manufacturing provinces. METI guidelines pressure Japanese converters toward thinner calipers compatible with recyclable film mandates.
- Medium:40–50 micron grades balance tensile performance with cost efficiency across Southeast Asian ambient logistics. The segment captures standard-duty carton sealing in India's western industrial corridors.
- Thick:60–75 micron backings reinforce heavy-load unitization where pallet integrity demands exceed standard specifications. Australia's east coast third-party logistics operators specify these grades for lane consolidation.
- Ultra-Thick:Specialized constructions exceeding 75 microns address extreme-duty applications in industrial machinery export packaging. Limited converter capability restricts supply to tier-one adhesive chemistry specialists.
Highest shipment volumes: Medium. Fastest specification migration: Thin.
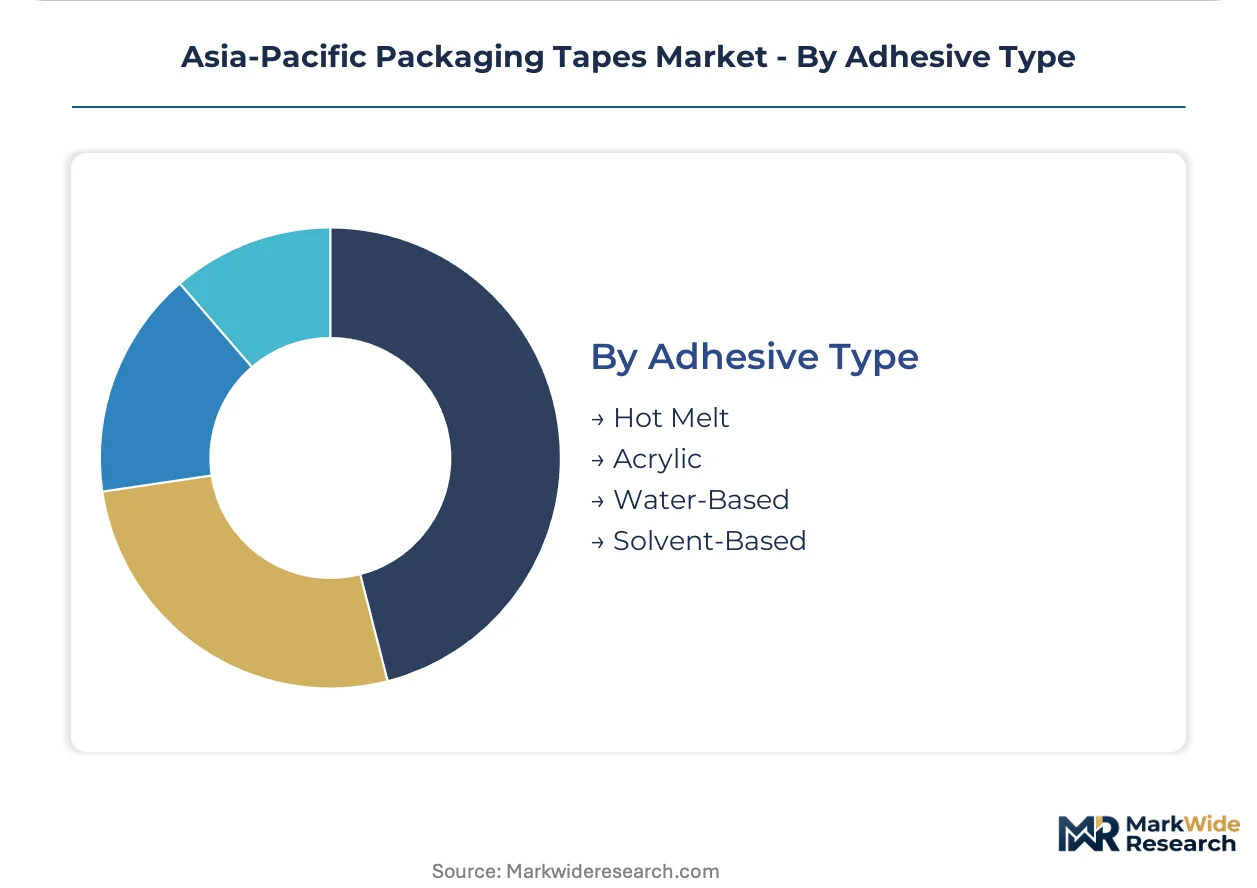
Adhesive Type:
Chemistry selection increasingly reflects regulatory enforcement timelines rather than pure performance optimization.
- Hot Melt:Metallocene polyolefin formulations extend temperature performance windows for Southeast Asian ambient-to-cold logistics lanes. The technology offers immediate tack and shear resistance without solvent content.
- Acrylic:Water-based emulsions with enhanced shear resistance rewrite the cost-performance tradeoff for temperature-variable logistics. Australia's third-party logistics operators specify these formulations for ambient-to-refrigerated lane consolidation.
- Water-Based:Food and beverage exporters adapt to tightening volatile organic compound limits under China's MEE enforcement timelines. The segment gains traction as converters accelerate line conversions from solvent-based assets.
- Solvent-Based:Natural rubber adhesives in high-humidity environments face phase-out friction as China's GB standards compress their market share. Legacy coating assets face stranded capital risk before depreciation cycles complete.
Widest installed base: Hot Melt. Gaining share fastest: Water-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate automated fulfillment infrastructure that consumes low-noise, high-tensile tape grades at scale. India's western industrial corridors attract contract manufacturers qualifying for production-linked incentive schemes. Southeast Asian electronics hubs in Vietnam and Thailand import specifications exceeding domestic converter capabilities.
China
E-commerce platforms operating automated sortation hubs in Zhejiang and Guangdong provinces specify caliper-standardized tapes for high-speed applicators. SAMR enforcement of GB standards on volatile organic compound content accelerates water-based adhesive line conversions. Coastal manufacturing provinces face stranded capital risk in legacy solvent-based coating assets before depreciation cycles complete.
India
Bureau of Indian Standards tensile strength benchmarks for industrial packaging grades disqualify uncoated imports and redirect procurement toward certified domestic converters. Maharashtra's logistics corridor hosts third-party operators consolidating ambient-to-refrigerated lanes with medium-thickness polypropylene specifications. Western industrial states attract electronics contract manufacturers relocating supply chains from China.
Japan
METI circular economy guidelines pressure converters toward thinner calipers and recyclable mono-material film constructions compatible with container-to-container reprocessing. Osaka and Nagoya industrial corridors specify vinyl grades for clean-room-compatible precision coating. Electronics OEMs demand integrated resin-to-tape traceability systems for adhesive content disclosure.
South Korea
Precision coating capabilities for clean-room electronics grades concentrate technical skills that limit expansion in lower-cost manufacturing locations. BOPP film costs track naphtha-cracker economics in Ulsan and Yeosu, squeezing converter margins on fixed-price annual contracts. Seoul Capital Area electronics manufacturers qualify suppliers with metallocene polyolefin hot-melt formulations.
Vietnam
Electronics contract manufacturers relocating from China import tape specifications exceeding domestic Vietnamese converter capabilities, creating tier-one supplier entry points. Northern industrial zones in Bac Ninh and Hai Phong absorb transferred production capacity seeking tariff-advantaged export routes. Domestic coating infrastructure lacks precision adhesive weight control for clean-room grades.
Asia-Pacific Packaging Tapes Market Competitive Environment
Top-tier vendors anchor high-performance segments through adhesive chemistry portfolios and precision coating assets, while mid-scale converters compete on BOPP film economics and regional logistics proximity. The vendor base stratifies across three archetypes: integrated resin-to-tape specialists, film-coating converters with applicator compatibility expertise, and commodity distributors serving price-sensitive bulk logistics. Dominant competitive moves include backward integration into resin sourcing and geographic expansion through acquisition of certified domestic converters in India and Southeast Asia.
Among diversified adhesive and materials specialists, 3M Company and Henkel AG occupy positions exemplifying integrated chemistry-to-application capability. Nitto Denko represents the precision-coating archetype serving electronics OEMs with clean-room-compatible specifications. AVERY DENNISON CORPORATION anchors the film-and-adhesive systems tier with applicator compatibility focus across automated fulfillment networks.
| Leading Market Players |
|---|
| 3M Company |
| AVERY DENNISON CORPORATION |
| Nitto Denko |
| Intertape Polymer Group Inc. |
| CCT Tapes |
| Berry Global Inc. |
| Henkel AG and Corporation |
| Saint-Gobain |
| Advance Tapes International |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters across China's coastal provinces anchor regional supply discipline through multi-generational control of coating assets and long-term naphtha-cracker offtake agreements. Their pricing power stems from captive relationships with e-commerce fulfillment operators in Zhejiang and Guangdong, while procurement concentration in India's western corridors forces margin compression on unintegrated competitors.
Pricing Analysis
Short lead-time premiums command substantial markups from electronics OEMs in Japan's Osaka-Nagoya corridor facing line-stoppage costs, while spot inventory discounts attract bulk logistics operators in India's Maharashtra belt. Three-tier pricing structure across premium, standard, and economy levels separates clean-room-certified vinyl grades from commodity BOPP carton-sealing tapes. Pricing pressure stems from propylene monomer volatility tied to South Korean naphtha-cracker economics. Bulk e-commerce platforms exhibit highest price sensitivity; precision electronics OEMs tolerate premium positioning for certified traceability.
Supply Chain Analysis
Precision coating technician scarcity in Vietnam's northern industrial zones constrains domestic capability expansion despite electronics contract manufacturing relocation from China. Supply concentrates in China, South Korea, and Japan for BOPP film extrusion and adhesive resin synthesis. Raw material dependencies center on naphtha-derived propylene, acrylic monomers, and metallocene polyolefin elastomers. Single-source vulnerability runs through South Korean petrochemical complexes for film substrate. Distribution runs through converter-direct contracts with e-commerce platform operators, disintermediating traditional packaging distributors in high-volume corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over resin-to-tape traceability systems determines qualification for electronics OEM procurement. Players are pursuing backward integration into adhesive resin sourcing to secure GB standards compliance and margin defense.
For Market Incumbents: Hedge against solvent-based asset stranding by accelerating water-based line conversions ahead of China's MEE enforcement timelines. Secure BIS certification for Indian industrial grades to capture import-disqualified demand. Defensive capacity positioning in Vietnam's Bac Ninh corridor addresses electronics contract manufacturing relocation without precision coating technician dependency. For New Entrants and Emerging Players: Mid-tier food and beverage exporters in Australia's east coast corridor represent an underserved buyer archetype seeking blockchain-enabled adhesive-lot traceability for supermarket chain audits. White-space targets include water-based acrylic emulsions for ambient-to-refrigerated lane consolidation and recyclable mono-material film constructions for Japan's container-to-container recycling mandates. Go-to-market through direct procurement contracts with third-party logistics operators bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor certified domestic converters in India facing working capital constraints from BIS compliance investments. Long-term viability across the analysis window rests on integrated resin-to-tape traceability capabilities qualifying for South Korean and Japanese electronics OEM procurement. Acquisition targets should demonstrate verified mono-material constructions compatible with Japan's METI recycling mandates. Watch for GB standards enforcement acceleration as inflection indicator for water-based adhesive line conversion urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Resin Sourcing | GB standards compliance and margin defense against naphtha-cracker volatility anchor competitive positioning. |
| Water-Based Line Conversion | China's MEE enforcement timelines strand solvent-based assets, rewarding early converters with qualification advantage. |
| BIS Certification Investment | India's tensile strength benchmarks disqualify uncoated imports, redirecting procurement toward certified domestic suppliers. |
| Precision Coating Capability Expansion | Electronics OEMs in Japan and South Korea demand clean-room-compatible grades with integrated traceability systems. |
| Blockchain-Enabled Provenance Tracking | Australian and New Zealand food exporters pilot adhesive-lot traceability to satisfy supermarket chain ethical sourcing audits. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coating line managers, procurement leads at e-commerce fulfillment operators, adhesive R&D directors, distribution channel partners, and electronics OEM supply chain managers combined with secondary validation from SAMR GB standards documentation, BIS certification registries, and METI circular economy guidelines. Bottom-up tape volume estimates by end-use industry and adhesive chemistry triangulated against top-down macroeconomic indicators across the Asia-Pacific region.
Data-stream reconciliation across shipment volumes, resin consumption patterns, and applicator installation rates informed the analytical framework. Segmentation dimensions modeled include product type, end-use industry, thickness tier, adhesive chemistry, and national regulatory compliance cluster throughout the forecast period. CAGRs derived from trend extrapolation of e-commerce fulfillment infrastructure expansion and adhesive formulation conversion rates. Forecast inputs incorporated propylene monomer price trajectories and automated carton-sealing line deployment schedules.
Revisions become necessary when regulatory enforcement timelines accelerate, naphtha-cracker economics shift substantially, or electronics manufacturing relocation patterns alter import specification flows. Forecasts reflect assumptions regarding BIS certification adoption rates and water-based adhesive line conversion pacing. Specific risk factors include stranded capital in legacy solvent-based assets and precision coating technician scarcity constraining Vietnam expansion. A small set of named triggers—GB standards acceleration, propylene volatility spikes, and METI recycling mandate tightening—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Wing Walk Tapes Market
Tapes
Building and Construction Tapes Market
Tapes
UV Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Global Specialty Tapes Market
Tapes
Double Coated Film Tapes Market
Tapes
Packaging Tapes Market
Tapes
Galley Tapes Market
Tapes
Silicone Tape Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Umbilical Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Differential Tapes Market
Tapes
Nano Tapes Market
Tapes
Breathable Tape Market
Tapes
Global Construction Tape Market