
 Umbilical Tapes Market | 2026-2036
Umbilical Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Umbilical Tapes Market Analytics
The capital-intensity divergence between fully integrated weavers and downstream converters is unwinding competitive stability in umbilical tape supply. Medtronic leverages captive fiber processing to control input costs across its securement portfolio. Johnson & Johnson sustains brand preference in hospital purchasing committees through decades of clinical validation. Cardinal Health competes on distribution density, stocking umbilical tapes within same-day delivery networks for acute care facilities.
Umbilical tapes are woven or non-woven textile strips, typically 0.5 to 2.5 inches in width, manufactured from polyester or cotton blends with pressure-sensitive adhesive coatings, designed to secure umbilical catheters and dressings in neonatal and maternal care settings. Multi-ply reinforced variants command premium positioning due to their tensile strength requirements in critical care environments, while single-ply cotton formats serve cost-sensitive maternity wards where shorter dwell times apply. Polyester material grades are capturing expanded share as hospitals prioritize moisture-wicking performance and reduced skin maceration incidence.
The US FDA governs biocompatibility testing under ISO 10993 for skin-contact medical textiles, while the EU MDR requires notified body intervention for adhesive wound care products entering European clinical channels. These frameworks elevate compliance spending for mid-tier converters without in-house regulatory affairs capacity. Stakeholders must monitor how FDA guidance on antimicrobial claims reshapes product differentiation strategies without explicit efficacy data.
Market Dynamics
Neonatal intensive care units are consolidating vendor relationships around single-source securement contracts, compressing procurement cycles and elevating technical service requirements for umbilical tape suppliers.
Growth Catalysts
- ISO 10993 biocompatibility mandates:The US FDA's tightened testing protocols for Class I medical devices are forcing substrate upgrades toward polyester woven grades, expanding addressable premium product volume.
- Germany's Tuttlingen manufacturing corridor:Concentrated medical device production in this southwestern cluster generates localized demand pull for specialized securement textiles with same-day logistics requirements.
- Moisture-wicking substrate technology:Advanced polyester fiber treatments are reducing skin maceration incidence in extended-dwell catheter applications, creating clinical preference shifts in critical care settings.
Market Restraints
- Petrochemical input volatility:Polyester staple fiber prices fluctuate with purified terephthalic acid and monoethylene glycol feedstock costs, squeezing converter margins on fixed hospital contracts.
- Single-source adhesive dependency:Medical-grade pressure-sensitive adhesive supply concentrates among three specialty chemical producers, creating vulnerability to force majeure disruptions.
- Cotton blend substitution ceiling:Natural fiber formats face intrinsic tensile strength limitations that prevent penetration into multi-lumen catheter securement applications above 48-hour dwell times.
Strategic Opportunities
- India's expanding NICU infrastructure:Government-funded maternal health initiatives are installing neonatal intensive care capacity in tier-2 and tier-3 cities, opening underpenetrated procurement channels for standard-grade securement products.
- Antimicrobial claim differentiation:Pending FDA guidance on silver-ion and chlorhexidine-impregnated substrates creates white space for efficacy-validated premium positioning without explicit therapeutic claims.
- Direct-to-hospital digital procurement:E-commerce platforms serving acute care facilities are disintermediating traditional distributor networks, enabling margin capture by specialized converters with regulatory self-sufficiency.
Industry Challenges
- Regulatory affairs talent scarcity:Mid-tier converters face recruitment bottlenecks for ISO 13485 quality management system auditors capable of managing FDA 510(k) and EU MDR parallel submissions.
- Legacy sterilization validation:Ethylene oxide process qualification for new substrate-adhesive combinations requires 12-18 month timeline compression to match hospital formulary review cycles.
- Multi-site quality harmonization:Converters operating toll-manufacturing relationships across Asian subcontractor networks struggle to maintain lot-to-lot biocompatibility consistency under ISO 10993-10 sensitization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Umbilical Tapes Market |
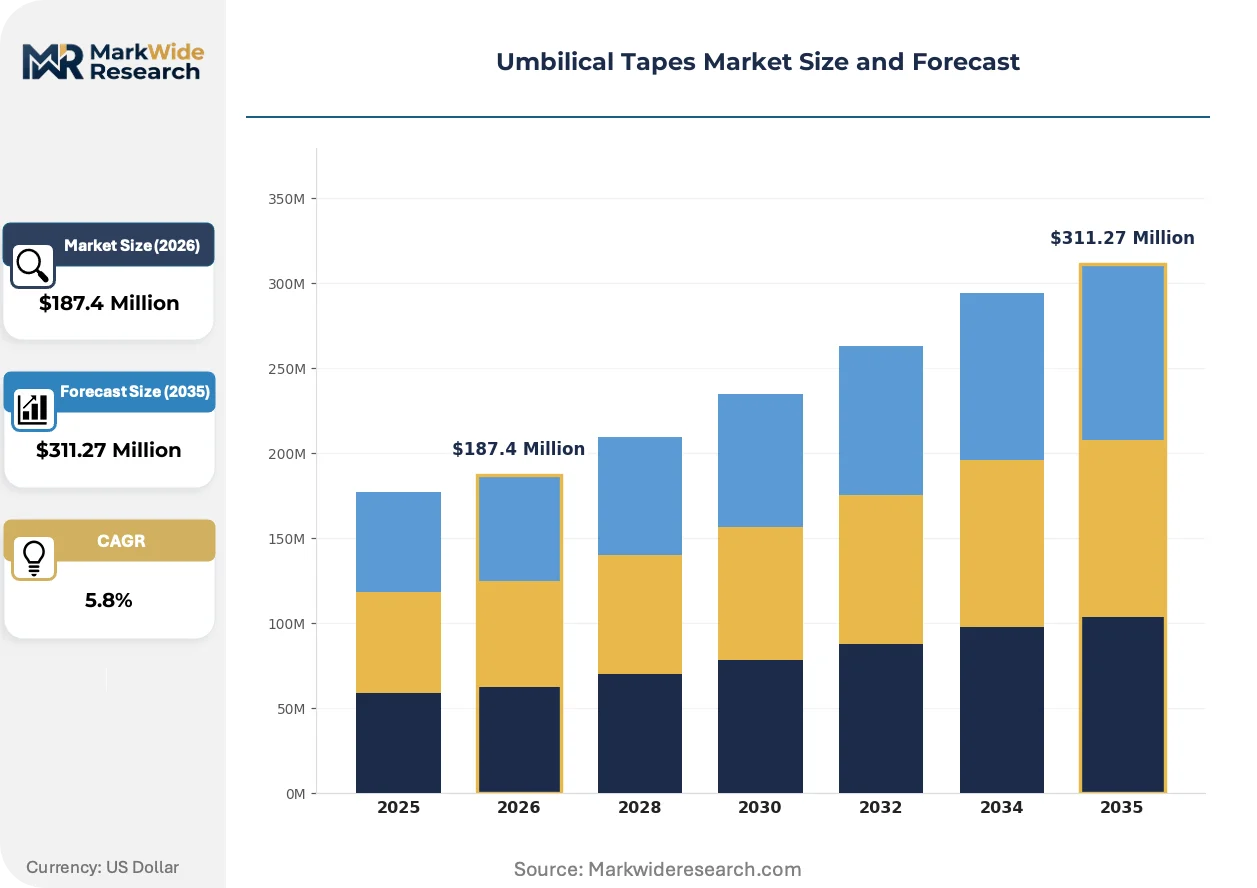
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Ply, Multi-Ply, Reinforced, Non-Reinforced Material: Polyester, Polypropylene, Nylon, Cotton Application: Medical, Industrial, Aerospace, Marine End User: Hospitals, Manufacturing, Research Institutions, Laboratories |
| Companies Covered | Medtronic, Johnson & Johnson, Covidien, Medline Industries, DeRoyal, SDP, Jorvet, Xiangde Medical, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Umbilical Tapes Market Evolving Landscape
Material science advances and procurement digitization are restructuring how umbilical tapes are specified, validated, and replenished across acute care networks.
Silicone-based gentle-adhesion substrates are supplanting traditional acrylic pressure-sensitive adhesives in neonatal populations with fragile epidermal integrity. Level III NICUs in academic medical centers are adopting these formats at accelerated pace for infants below 1,500 grams birth weight. This transition is compressing market share for conventional adhesive systems while expanding total addressable spend per patient day.
EU MDR Article 117 requirements for notified body involvement in adhesive wound care product certification are elevating technical documentation burdens for European market entry. Manufacturers without in-house clinical evaluation report capabilities face outsourcing costs that disadvantage smaller converters. German and French notified bodies are experiencing 14-18 month backlog queues, forcing commercial timeline recalibration for 2025-2026 product launches.
Hospital value analysis committees are consolidating securement product categories under single-source contracts with performance guarantees on catheter dwell time and unplanned removal rates. This behavioral shift concentrates purchasing authority among supply chain directors and away from individual unit nurse managers. The United States exhibits the most pronounced committee consolidation, with integrated delivery networks standardizing across 15-30 affiliated facilities simultaneously.
Umbilical Tapes Market Segmentation
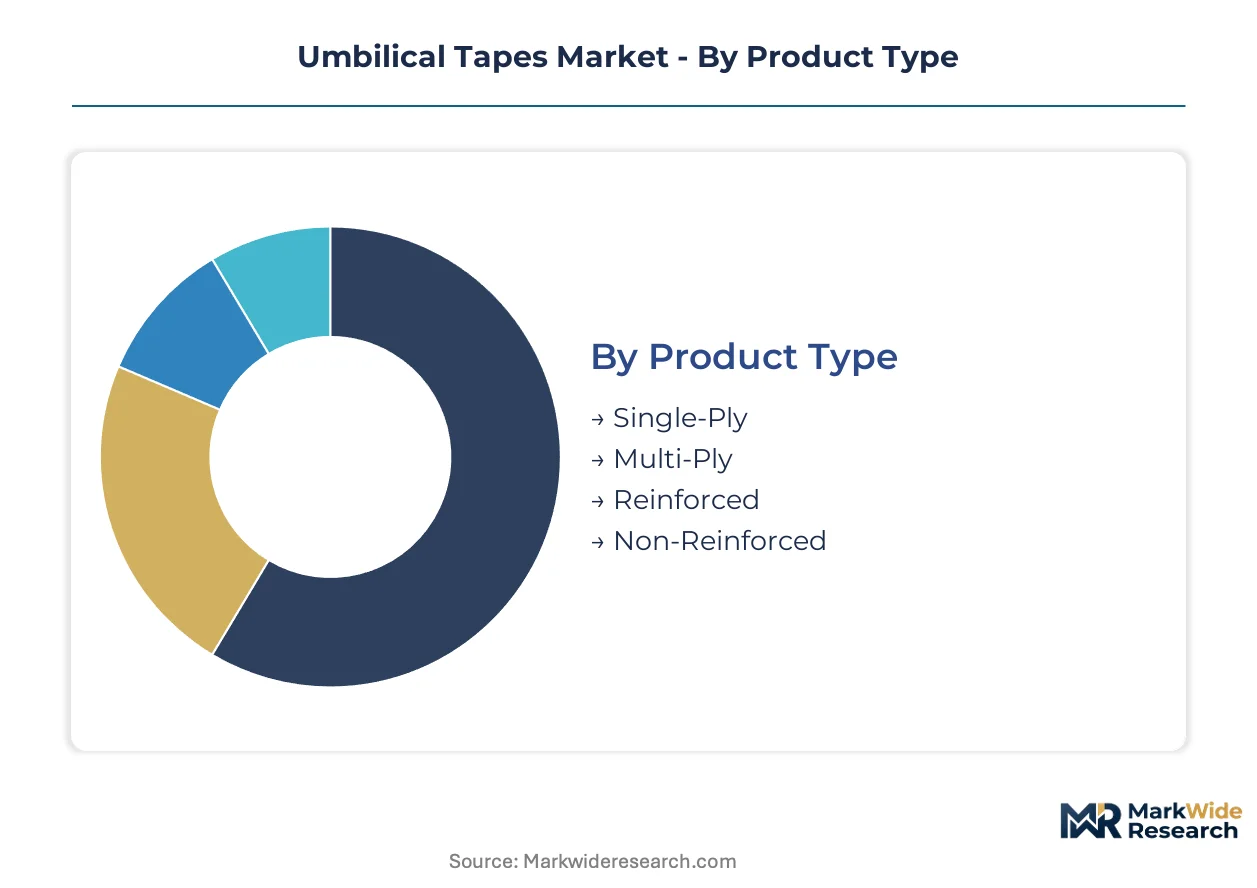
Umbilical tape procurement diverges sharply across clinical and industrial channels, with substrate specifications and adhesive chemistries calibrated to dwell time requirements and environmental exposure conditions. Regulatory frameworks governing skin-contact medical textiles impose tiered compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
FDA ISO 10993 biocompatibility testing intensity varies directly with ply count and reinforcement architecture, concentrating compliance investment in formats destined for neonatal critical care.
- Multi-Ply:Laminated woven substrates with intermediate scrim layers deliver tensile strength exceeding 50 pounds per inch, satisfying securement requirements for multi-lumen umbilical catheters in Level III NICUs. German hospital systems in the Tuttlingen corridor specify these formats for extended-dwell applications where unplanned removal carries sepsis risk.
- Reinforced:Longitudinal filament yarns or cross-woven aramid inserts distribute mechanical stress across adhesive interfaces, preventing catheter migration in high-moisture environments. Demand concentrates in academic medical centers adopting silicone-based gentle-adhesion substrates for infants below 1,500 grams birth weight.
- Single-Ply:Lightweight cotton or polyester woven substrates serve cost-sensitive maternity wards with discharge protocols under 24 hours.
- Non-Reinforced:Unidirectional fiber alignment suits short-term dressing securement where tensile loading remains minimal.
Established volume favors Single-Ply; emerging adoption favors Reinforced.
Material:
Petrochemical feedstock volatility and moisture-management performance specifications are rebalancing procurement preferences across fiber categories.
- Polyester:Hydrophobic fiber surfaces wick moisture away from epidermal interfaces, reducing maceration incidence in catheter dwell times exceeding 48 hours. US FDA substrate upgrade mandates for Class I medical devices are accelerating hospital formulary shifts toward polyester woven grades.
- Cotton:Natural fiber absorbency and skin-breathability characteristics retain preference in maternal care settings with shorter securement durations. India's expanding NICU infrastructure in tier-2 and tier-3 cities sources cotton blends for standard-grade procurement channels.
- Polypropylene:Olefin-based substrates offer chemical resistance for industrial cable bundling applications.
- Nylon:High-tenacity fiber grades serve aerospace and marine securing operations requiring abrasion resistance.
Procurement authority is concentrating around Polyester for medical channels; Cotton maintains defensive positions in cost-optimized installations.
Application:
End-use environment severity dictates adhesive system selection and substrate durability specifications across divergent operating conditions.
- Medical:Neonatal and maternal care applications dominate value concentration, with securement performance tied to catheter dwell time guarantees in single-source hospital contracts. Silicone-based gentle-adhesion substrates are displacing acrylic systems in academic medical center NICUs.
- Industrial:Cable harness organization and temporary fastening operations in manufacturing facilities utilize commodity-grade woven tapes without medical-device regulatory overhead.
- Aerospace:Flame-retardant substrate specifications and outgassing compliance requirements constrain supplier qualification to specialty converters with AS9100 certification.
- Marine:Salt-spray corrosion resistance and UV-stabilized adhesive formulations address offshore platform and vessel construction applications.
Medical commands premium positioning; Industrial captures volume scale.
End User:
Purchasing committee consolidation and digital procurement platform penetration are restructuring vendor access patterns across institutional categories.
- Hospitals:Integrated delivery networks in the United States standardize securement contracts across 15-30 affiliated facilities, compressing supplier rosters and elevating technical service requirements. Value analysis committees now control procurement authority previously held by unit nurse managers.
- Manufacturing:Industrial buyers prioritize same-day delivery availability and volume pricing tiers over substrate technical differentiation.
- Research Institutions:Protocol-specific customization requirements and small-batch flexibility favor specialized converters with in-house weaving operations.
- Laboratories:Contamination-controlled environments and traceability documentation needs align with ISO 13485-certified supply sources.
Hospital consolidation favors scaled converters; Research Institution fragmentation rewards agile specialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in India and Southeast Asia exhibit acute price sensitivity, driving cotton-blend single-ply volumes, while German and US academic medical centers absorb premium polyester multi-ply formats without volume elasticity.
United States
Integrated delivery networks consolidate securement contracts across 15-30 affiliated facilities, compressing supplier rosters toward scaled converters. The FDA's tightened ISO 10993 biocompatibility mandates for Class I medical devices accelerate substrate upgrades toward polyester woven grades. Academic medical centers in Boston and the Research Triangle adopt silicone-based gentle-adhesion substrates for infants below 1,500 grams birth weight.
Germany
The Tuttlingen medical device manufacturing corridor generates localized demand pull for specialized securement textiles with same-day logistics requirements. EU MDR Article 117 notified body involvement extends certification timelines to 14-18 months, elevating technical documentation burdens. Bavarian and Baden-Württemberg hospital systems specify multi-ply reinforced formats for extended-dwell catheter applications where unplanned removal carries sepsis risk.
India
Government-funded maternal health initiatives install neonatal intensive care capacity in tier-2 and tier-3 cities, opening underpenetrated procurement channels for standard-grade cotton-blend products. CDSCO medical device regulations tighten quality system requirements for imported securement textiles. Maharashtra and Gujarat manufacturing clusters source cotton blends for cost-optimized maternity wards with discharge protocols under 24 hours.
China
NMPA biocompatibility testing protocols for skin-contact medical textiles impose tiered compliance burdens on domestic converters. Yangtze River Delta and Pearl River Delta hospital procurement bureaus consolidate vendor relationships around technical service guarantees for catheter dwell time performance. Shanghai academic medical centers pilot silicone-based substrates for premature infant populations.
Japan
PMDA quality management system audits for adhesive wound care products favor established converters with in-house regulatory affairs capacity. METI-funded maternal health infrastructure programs expand NICU bed capacity in prefectural medical centers. Kanto and Kansai region hospital value analysis committees standardize securement contracts across affiliated facility networks.
Umbilical Tapes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in umbilical tape supply. Medtronic leverages captive fiber processing to control input costs across its securement portfolio, while Johnson & Johnson sustains brand preference through decades of clinical validation. Cardinal Health competes on distribution density, stocking products within same-day delivery networks for acute care facilities. Strategic moves concentrate on backward integration into polyester staple fiber processing and regulatory self-sufficiency for FDA 510(k) and EU MDR parallel submissions.
Among US-based diversified medical device manufacturers, Medtronic and Johnson & Johnson occupy positions reflecting integrated supply chain control and clinical validation heritage. Cardinal Health represents the distribution-centric archetype, competing on logistics density rather than substrate innovation. Chinese specialists including Xiangde Medical exemplify regional cost-optimized production for standard-grade cotton-blend formats serving price-sensitive maternity wards.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Covidien |
| Medline Industries |
| DeRoyal |
| SDP |
| Jorvet |
| Xiangde Medical |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month ethylene oxide sterilization validation cycles compress pricing power for converters without in-house regulatory capacity, concentrating margin capture among integrated manufacturers with captive fiber processing and established FDA 510(k) portfolios. Hospital value analysis committees exploit this asymmetry to extract performance guarantees on catheter dwell time in exchange for single-source contract awards.
Pricing Analysis
After-sales technical service contracts and clinical training programs drive lifetime value capture for umbilical tape suppliers, offsetting commodity pressure on per-unit product margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 biocompatibility certification tier and substrate reinforcement architecture. Pricing pressure stems from fixed-price hospital contracts confronting petrochemical feedstock volatility in polyester staple fiber inputs. Cotton-blend single-ply formats face acute price sensitivity in India's tier-2 and tier-3 maternity wards, while silicone-based gentle-adhesion substrates command premium absorption in US academic medical center NICUs.
Supply Chain Analysis
Strategic stockpiling of medical-grade pressure-sensitive adhesive raw materials dominates inventory strategy, given single-source dependency on three specialty chemical producers and vulnerability to force majeure disruptions. Polyester staple fiber supply concentrates in China, Germany, and the United States, drawing from purified terephthalic acid and monoethylene glycol feedstocks. Woven substrate production rests on cotton sourcing from India and polyester fiber processing in the Yangtze River Delta. Tariff exposure on Chinese medical textile imports creates structural risk for downstream converters. Distribution runs through integrated delivery network same-day delivery networks and specialized medical device distributors serving acute care facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward hospital value analysis committees consolidating securement contracts across 15-30 affiliated facilities, fragmenting vendor access and compressing procurement cycles for mid-tier converters without regulatory self-sufficiency.
For Market Incumbents: Fortify backward integration into polyester staple fiber processing to insulate margins from petrochemical input volatility, and deepen ISO 13485 quality management system capabilities to accelerate sterilization validation timelines. Silicone-based gentle-adhesion substrate adoption by academic medical centers threatens acrylic adhesive incumbents with clinical preference displacement. Captive fiber processing and in-house regulatory affairs capacity represent the critical defensive levers against emerging Asia-Pacific cost-optimized entrants. For New Entrants and Emerging Players: Differentiate on antimicrobial substrate efficacy validation pending FDA guidance on silver-ion and chlorhexidine-impregnated formats, creating premium positioning without explicit therapeutic claims. India's government-funded NICU infrastructure expansion in tier-2 and tier-3 cities offers the most penetrable geography for standard-grade cotton-blend products. Direct-to-hospital digital procurement platform partnerships provide the essential go-to-market angle to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat consolidation play because EU MDR Article 117 notified body backlogs and FDA ISO 10993 testing intensity are structurally advantaging scaled converters with in-house clinical evaluation report capabilities. Acquisition targets should display ISO 13485 certification, established notified body relationships, and toll-manufacturing networks across Asian subcontractor bases. The signal to watch is silicone-based substrate adoption rates in Level III NICUs as inflection indicator for adhesive system displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Processing | Medtronic's captive polyester staple fiber production insulates input cost exposure across securement portfolios. |
| EU MDR Notified Body Pre-Submission | Early engagement with German and French notified bodies compresses 14-18 month certification queues for adhesive wound care products. |
| Silicone-Based Substrate Development | Academic medical center NICU adoption for infants below 1,500 grams birth weight displaces conventional acrylic adhesive market share. |
| Direct-to-Hospital Digital Procurement | E-commerce platform partnerships disintermediate traditional distributor networks and enable margin capture by specialized converters. |
| Antimicrobial Efficacy Validation | Pending FDA guidance on silver-ion substrates creates white space for premium positioning without explicit therapeutic claims. |
Research Methodology
The analysis maps polyester woven substrates, cotton-blend formats, silicone-based gentle-adhesion systems, and multi-ply reinforced architectures, each validated through hospital purchasing committee directors, neonatal intensive care unit clinicians, biomedical engineers, and GPO contracts managers. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement contract registries, and customs trade data for medical textile imports. Bottom-up unit demand modeling and top-down market sizing triangulate volume estimates across substrate material and ply count segments.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation dimensions spanning product type, material grade, adhesive chemistry, end-use application, and regional regulatory cluster. CAGRs derive from trend extrapolation of hospital procurement cycle data, NICU bed capacity expansion rates, and substrate technology substitution patterns. Forecast inputs incorporate ISO 10993 biocompatibility testing cost trajectories and EU MDR notified body queue duration projections.
Material uncertainties — petrochemical feedstock price volatility, FDA antimicrobial claim guidance timing, and force majeure disruptions in medical-grade adhesive supply — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued hospital procurement committee consolidation and silicone-based substrate clinical validation expansion. Revision becomes warranted when EU MDR notified body backlog durations or polyester staple fiber input cost movements cross thresholds that alter converter margin structures or hospital formulary shift timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Non-UV Dicing Tapes Market
Tapes
Breathable Tape Market
Tapes
Seam Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
BOPP Packaging Tapes Market
Tapes
Mastic Tapes Market
Tapes
Galley Tapes Market
Tapes
Tear Tape Dispenser Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Heat Release Tape Market
Tapes
Flocking Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Sterilization Indicator Tape Market