
 Carton Sealing Tape Market | 2026-2036
Carton Sealing Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Sealing Tape Market Outlook
E-commerce fulfillment is broadening the end-use vertical mix for carton sealing tape, pulling demand away from traditional brick-and-mortar retail replenishment cycles. 3M leverages its materials science portfolio to dominate high-performance acrylic adhesive segments. Intertape Polymer Group sustains manufacturing scale across North American corrugated supply chains. Avery Dennison Corporation differentiates through pressure-sensitive adhesive technology leadership in sustainable tape formulations.
Carton sealing tape comprises a flexible backing substrate—typically oriented polypropylene film or paper—coated with a pressure-sensitive adhesive layer applied via direct gravure or slot-die coating processes, engineered to create instantaneous surface bonds on corrugated fiberboard at ambient temperatures. Polypropylene-backed tapes occupy the highest volume position due to cost efficiency and tensile strength, while water-based acrylic adhesives are gaining structural share as converters respond to volatile organic compound restrictions. Hot melt formulations retain margin concentration in automated high-speed packaging lines where shear resistance commands premium positioning.
The EPA regulates adhesive volatile organic compound emissions under the National Emission Standards for Hazardous Air Pollutants, compelling tape manufacturers to reformulate solvent-based systems or invest in recovery equipment. REACH compliance in Europe restricts phthalate plasticizers in PVC backings, redirecting procurement toward polypropylene alternatives. California's South Coast Air Quality Management District imposes the strictest state-level adhesive solvent limits in the United States. Stakeholders must monitor evolving state-level air quality regulations and adhesive chemistry transitions to preserve market access and avoid stranded inventory in reformulation cycles.
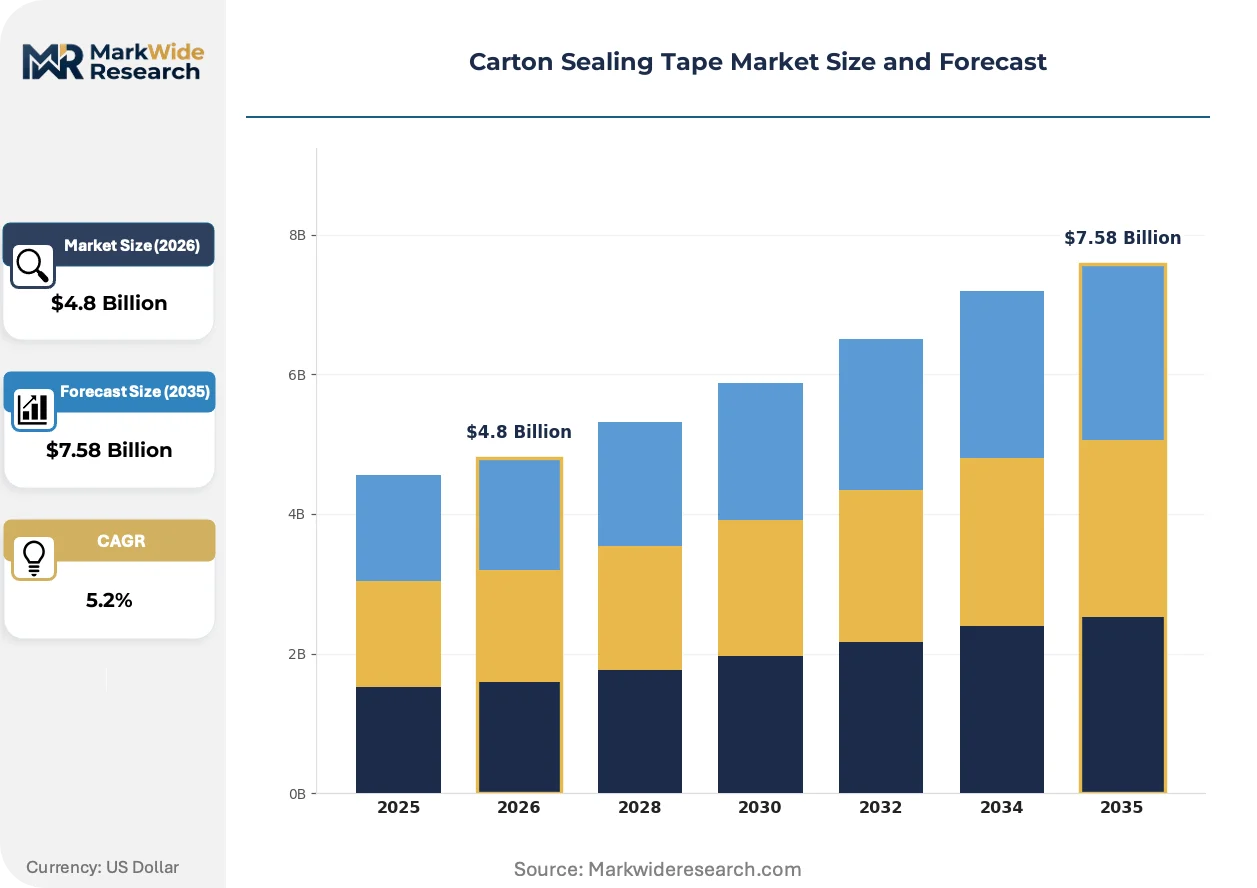
Market Dynamics
E-commerce fulfillment networks are compressing replenishment cycles and fragmenting order sizes, forcing tape converters to reconfigure coating lines for shorter production runs while maintaining adhesive performance consistency across climate zones.
Growth Catalysts
- Cross-border e-commerce volumes:Parcel throughput at Shanghai and Shenzhen export hubs is pulling polypropylene-backed tape demand into sustained double-digit consumption curves.
- China's GB standards tightening:NMPA adhesive emission limits are accelerating water-based acrylic formulation adoption among domestic converters seeking regulatory clearance.
- Automated packaging lines:Hot melt shear-resistant tapes are capturing share in high-speed corrugated sealing operations where downtime costs dominate procurement criteria.
Market Restraints
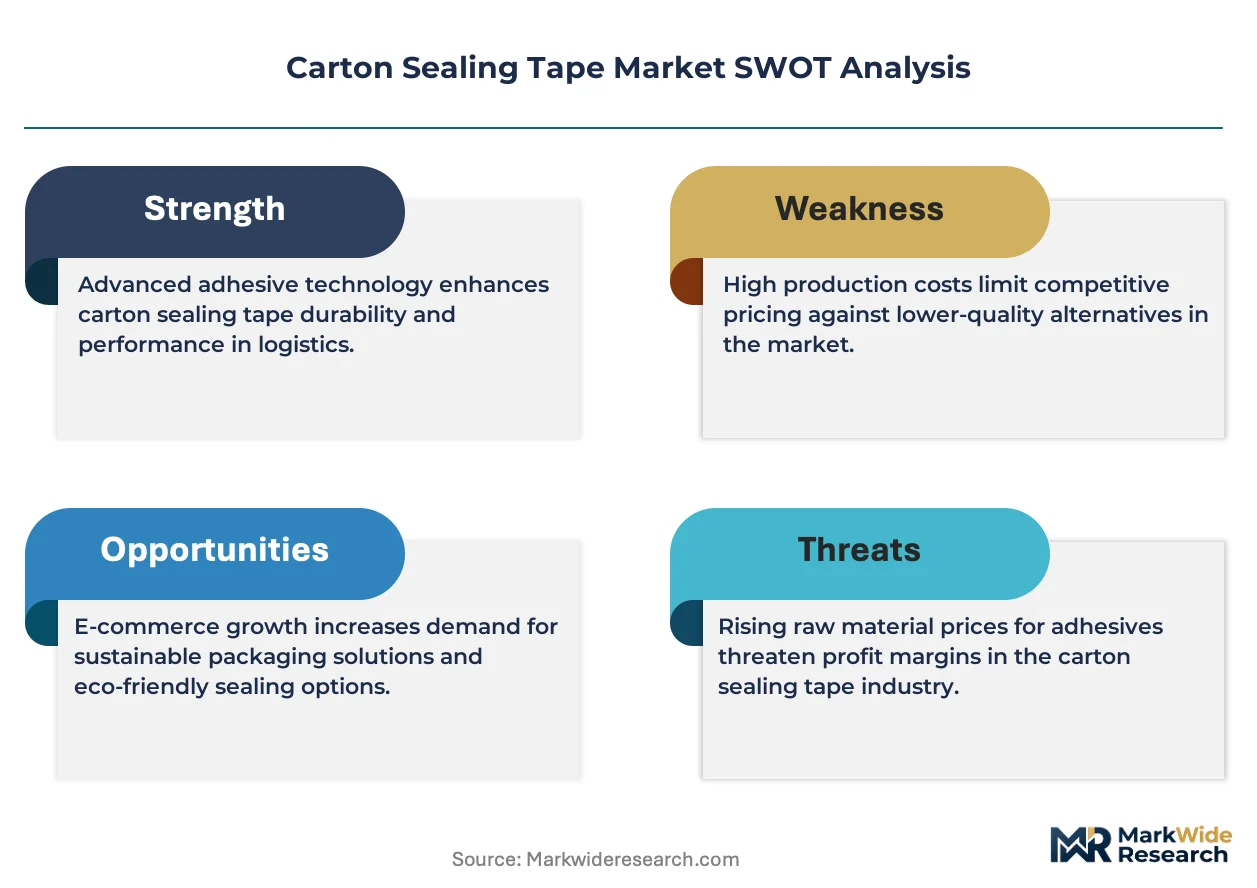
- Petrochemical feedstock volatility:Polypropylene resin price swings compress converter margins and complicate long-term contract pricing with corrugated box manufacturers.
- East Asian supply concentration:Oriented polypropylene film production clusters around Zhejiang province, exposing buyers to single-region logistics disruptions.
- REACH phthalate restrictions:PVC backing alternatives face reformulation costs that disadvantage smaller European converters against polypropylene-backed competitors.
Strategic Opportunities
- India's packaging material standards:BIS certification requirements for export-grade corrugated shipments are creating specification-grade tape demand among Mumbai and Chennai logistics hubs.
- Cold-chain pharmaceutical distribution:Temperature-stable acrylic adhesives are penetrating vaccine and biologics packaging applications where bond integrity spans -20°C to +40°C transit windows.
- California SCAQMD solvent limits:The strictest US state-level adhesive VOC caps are rewarding early movers with water-based formulation capabilities in West Coast fulfillment markets.
Industry Challenges
- Gravure coating technician scarcity:Slot-die and direct gravure process expertise is concentrating among aging workforces in legacy manufacturing regions.
- Reformulation inventory stranding:EPA NESHAP compliance deadlines force converters to write down solvent-based adhesive stocks before recovery equipment investments mature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Sealing Tape Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
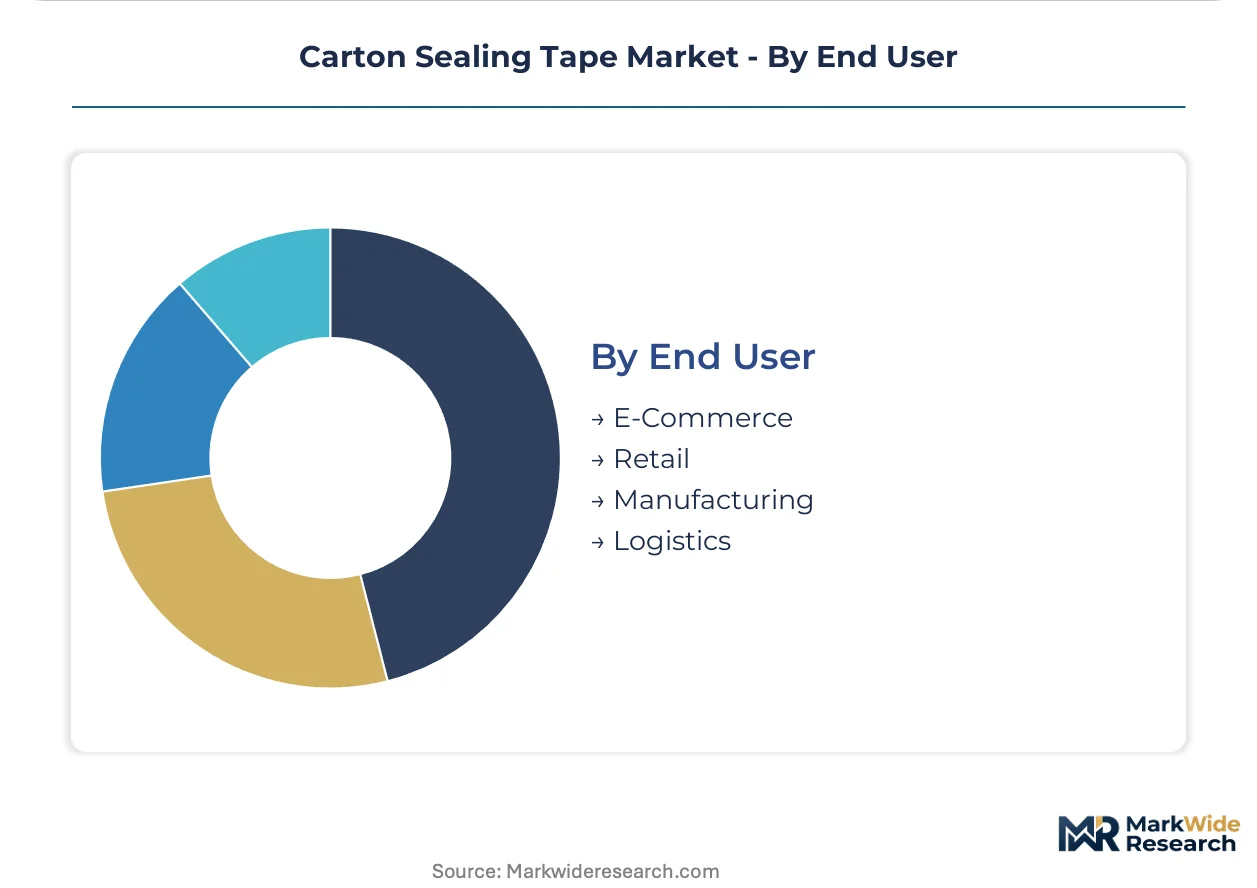
| Segmentation | Product Type: Polypropylene, PVC, Paper, Reinforced Adhesive Type: Hot Melt, Water-Based, Solvent-Based, Acrylic Thickness: Low, Medium, High, Extra Heavy End User: E-Commerce, Retail, Manufacturing, Logistics |
| Companies Covered | 3M, Intertape Polymer Group, Avery Dennison Corporation, Nitto Denko Corporation, Tesa SE, Berry Global Inc., Shurtape Technologies, Scapa Group plc, Advance Tapes International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Sealing Tape Market Strategic Shifts
Adhesive chemistry transitions and backing material substitutions are redefining performance benchmarks across ambient, cold-chain, and automated sealing applications. Regulatory pressure on volatile organic compound emissions is accelerating capital deployment toward water-based coating infrastructure.
Water-based acrylic adhesive technology is expanding into high-speed automated lines previously dominated by hot melt formulations. E-commerce fulfillment centers in Germany and the Netherlands are piloting these systems to satisfy EU Green Deal procurement mandates. The shift is compressing solvent-based equipment utilization rates and redirecting converter capex toward aqueous coating line retrofits.
REACH restrictions on phthalate plasticizers in PVC backings are forcing European converters toward polypropylene film alternatives. The regulation eliminates a cost-competitive substrate option for food-contact corrugated applications. German and French packaging distributors are now specifying polypropylene-backed tapes exclusively for export shipments to avoid dual inventory complexity.
Buyer consolidation among third-party logistics providers is compressing supplier qualification timelines and unbundling after-sales technical support from unit pricing. Large fulfillment operators in the United States are demanding direct mill relationships that bypass traditional distribution intermediaries. This pattern is most visible in Texas and Georgia logistics corridors where Amazon, Walmart, and Target operate captive packaging specification teams.
Carton Sealing Tape Market Segmentation
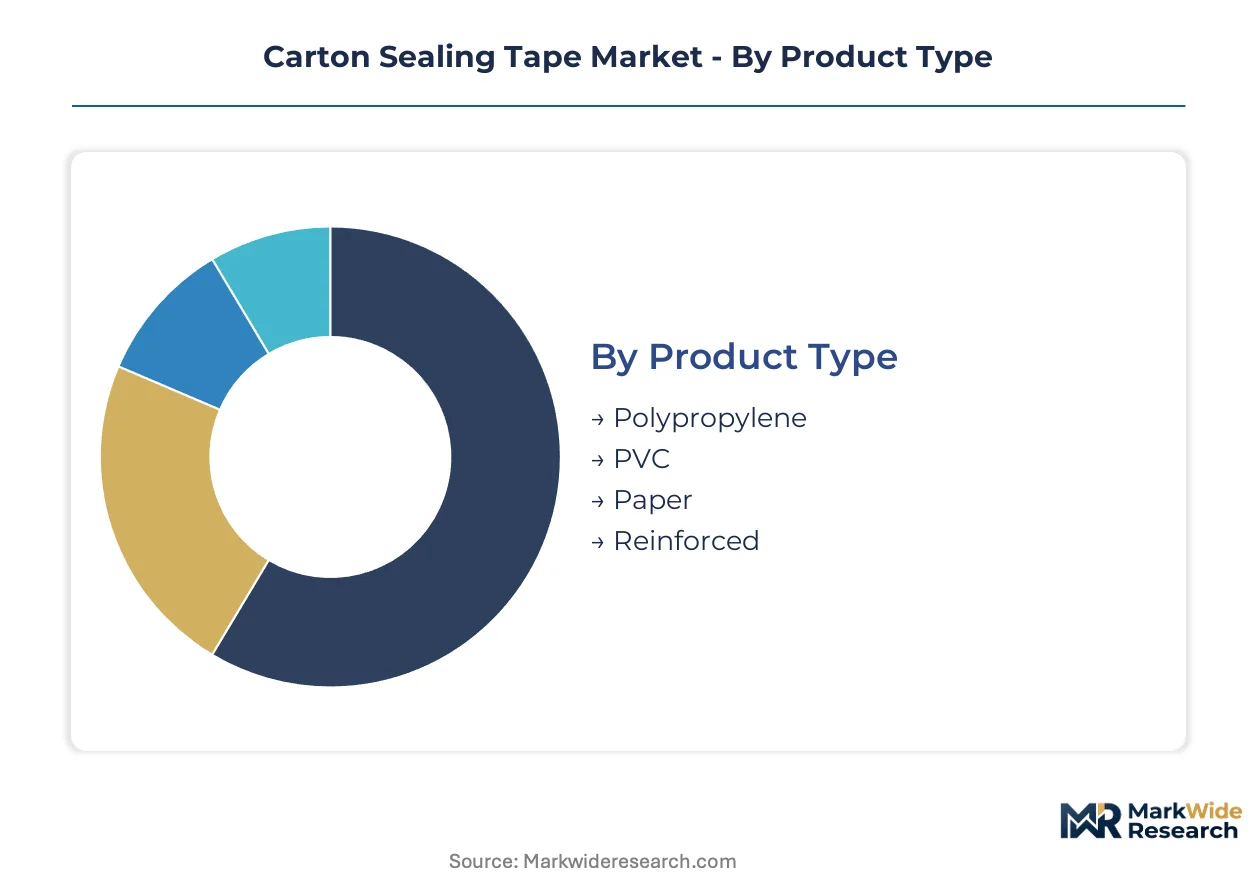
Carton sealing tape segmentation reflects divergent capital deployment strategies across substrate chemistry, adhesive formulation, and thickness calibration. Converters configure coating lines around specific segment combinations to capture margin pools in automated packaging versus cold-chain logistics.
Product Type:
Oriented polypropylene film backing demands the heaviest coating line investment due to biaxial orientation equipment and tension-controlled unwind systems.
- Polypropylene:Biaxially oriented polypropylene film delivers tensile strength above 30 MPa with density advantages over PVC. Shanghai and Shenzhen export corridors pull consumption into sustained volume curves as cross-border e-commerce parcel throughput expands.
- PVC:Phthalate-plasticized polyvinyl chloride backing offers conformability around irregular corrugated edges. REACH restrictions in Europe are redirecting procurement toward polypropylene alternatives and stranding legacy inventory in reformulation cycles.
- Paper:Kraft paper backing provides renewable substrate options for brands pursuing EU Green Deal procurement mandates. German fulfillment centers specify paper-backed tapes for last-mile packaging.
- Reinforced:Fiberglass or polyester yarn integration creates cross-directional tear resistance for heavy-load industrial sealing. Manufacturing facilities in India's Mumbai corridor specify reinforced grades for export-grade corrugated shipments.
Polypropylene absorbs the bulk of installed capacity; reinforced grades are expanding most quickly in heavy-load industrial applications.
Adhesive Type:
Water-based acrylic systems require aqueous coating infrastructure with drying tunnel retrofits that solvent-based lines cannot accommodate without substantial capital outlay.
- Hot Melt:Synthetic rubber-based hot melt adhesives deliver instantaneous shear resistance for automated high-speed lines. Temperature-stable formulations are penetrating vaccine distribution packaging where bond integrity spans -20°C to +40°C transit windows.
- Water-Based:Acrylic emulsion adhesives satisfy EPA NESHAP and California SCAQMD volatile organic compound limits. E-commerce fulfillment networks in Germany and the Netherlands pilot these systems to meet EU Green Deal mandates.
- Solvent-Based:Natural rubber or synthetic resin solutions in organic solvent carriers retain niche positioning where aggressive tack on recycled corrugated is non-negotiable. China's NMPA emission limits are accelerating converter migration away from this chemistry.
- Acrylic:Pressure-sensitive acrylic adhesives balance peel strength with UV resistance for outdoor storage applications. Texas and Georgia logistics corridors specify acrylic grades for climate-variable warehousing.
Hot melt formulations command the highest throughput per coating line; water-based acrylic is climbing the fastest as regulatory deadlines compress solvent-based equipment utilization.
Thickness:
Extra heavy gauge production strains coating line speed-tension relationships and demands precision gravure roll calibration.
- Low:Sub-40 micron constructions serve lightweight e-commerce parcel sealing where material cost minimization dominates procurement. Single-item shipment growth in cross-border channels pulls demand toward thinner specifications.
- Medium:40-50 micron backings balance tensile performance with roll yardage efficiency for retail replenishment cycles. Brick-and-mortar distribution centers in France and Germany standardize on medium thickness for case sealing.
- High:50-65 micron constructions provide puncture resistance for manufacturing export pallets. Chennai logistics hubs specify high-thickness grades for BIS-certified export corrugated.
- Extra Heavy:Above-65 micron backings with reinforced scrim address automated stretch-wrapping tension loads. Heavy manufacturing facilities deploy extra heavy grades for steel and machinery export packaging.
Medium thickness holds the largest production footprint; extra heavy specifications are gaining share fastest in automated pallet sealing operations.
End User:
E-commerce fulfillment centers demand shortest production runs with climate-zone adhesive consistency, fragmenting converter line scheduling.
- E-Commerce:Fragmented order sizes and compressed replenishment cycles force tape converters toward flexible coating line configurations. Amazon, Walmart, and Target captive specification teams in Texas and Georgia bypass traditional distribution intermediaries.
- Retail:Seasonal demand spikes around holiday fulfillment windows concentrate volume in predictable annual patterns. Big-box distribution networks in the United States negotiate annual contracts with volume-tier pricing structures.
- Manufacturing:Export-grade corrugated specifications in India require BIS-certified tape performance documentation. Mumbai and Chennai manufacturing clusters drive specification-grade demand for international shipment compliance.
- Logistics:Third-party logistics provider consolidation compresses supplier qualification timelines and unbundles technical support from unit pricing. Large 3PL operators demand direct mill relationships with standardized performance metrics.
E-commerce channels absorb the steepest capacity expansion; logistics end users are consolidating procurement fastest around direct mill relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai Free Trade Zone incentives concentrate oriented polypropylene film manufacturing capacity, pulling carton sealing tape supply chains toward East Asian export corridors. Zhejiang province hosts the densest cluster of biaxial orientation equipment. Cross-border e-commerce parcel volumes through Shenzhen and Shanghai hubs are reshaping regional demand curves.
China
NMPA adhesive emission limits under GB standards are accelerating water-based acrylic formulation adoption among domestic converters. Shanghai and Shenzhen export corridors pull polypropylene-backed tape consumption into sustained volume expansion. Zhejiang province's biaxial orientation film clusters supply substrate to converters serving cross-border e-commerce fulfillment networks.
United States
EPA NESHAP regulations compel tape manufacturers to reformulate solvent-based systems or invest in recovery equipment. California SCAQMD imposes the strictest state-level adhesive VOC caps, rewarding early movers with water-based capabilities. Texas and Georgia logistics corridors host Amazon, Walmart, and Target captive specification teams that bypass traditional distribution intermediaries.
Germany
EU Green Deal procurement mandates drive German fulfillment centers toward paper-backed tape specifications for last-mile packaging. REACH restrictions on phthalate plasticizers in PVC backings redirect procurement toward polypropylene alternatives. German and French packaging distributors specify polypropylene-backed tapes exclusively for export shipments to avoid dual inventory complexity.
India
BIS certification requirements for export-grade corrugated shipments create specification-grade tape demand among Mumbai and Chennai logistics hubs. Mumbai manufacturing clusters drive demand for reinforced grades in heavy-load industrial sealing. Chennai logistics hubs specify high-thickness grades for BIS-certified export corrugated compliance documentation.
Carton Sealing Tape Market Competitive Environment
Top-tier vendors anchor the high-performance acrylic adhesive segment, while mid-scale converters compete on coating line flexibility for fragmented e-commerce runs. The vendor base spans materials science conglomerates, specialized adhesive coaters, and regional substrate suppliers. Two strategic archetypes dominate: integrated materials science players leveraging polymer portfolios, and focused coating specialists optimizing gravure line utilization. Competitive moves concentrate on aqueous coating line retrofits and direct mill relationships with consolidated third-party logistics providers.
Among diversified materials science conglomerates, 3M and Avery Dennison Corporation represent the integrated technology tier, while Intertape Polymer Group exemplifies manufacturing scale optimization across North American corrugated supply chains. 3M occupies a position anchored in materials science breadth. Avery Dennison Corporation sits within the pressure-sensitive adhesive technology leadership archetype. Intertape Polymer Group exemplifies the manufacturing scale specialist model.
| Leading Market Players |
|---|
| 3M |
| Intertape Polymer Group |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Tesa SE |
| Berry Global Inc. |
| Shurtape Technologies |
| Scapa Group plc |
| Advance Tapes International |
| Others |
Value Chain & Pricing Dynamics
California SCAQMD adhesive VOC limits gate qualified supply for West Coast fulfillment contracts and prop premium-tier pricing for water-based acrylic formulations that clear compliance thresholds. Tape converters lacking aqueous coating infrastructure face margin compression as buyer specifications harden around emission-certified supply sources.
Pricing Analysis
Lead-time-driven pricing stratification rewards converters with aqueous coating flexibility, with short-run e-commerce orders commanding premium positioning against spot inventory liquidations from solvent-based legacy stocks. Three-tier pricing structure across premium performance, standard compliance, and economy spot grades reflects certification level and volume scale differentiation. Pricing pressure stems from polypropylene resin feedstock volatility compressing converter margins on long-term corrugated box contracts. Third-party logistics providers exhibit highest price sensitivity due to direct mill relationship procurement, while pharmaceutical cold-chain buyers prioritize bond integrity over unit cost.
Supply Chain Analysis
Reverse-logistics flows for reformulated solvent-based adhesive inventories strand working capital as EPA NESHAP compliance deadlines accelerate write-downs. Oriented polypropylene film supply concentrates in China, South Korea, and Japan, with Zhejiang province hosting densest biaxial orientation equipment clusters. Raw material dependencies center on polypropylene resin, acrylic emulsion polymers, and synthetic rubber feedstocks. Single-region logistics vulnerability in East Asian substrate production exposes buyers to port congestion and energy rationing disruptions. Distribution runs through corrugated packaging converters and direct mill relationships with consolidated fulfillment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carton sealing tape supply is tightening around aqueous coating line capacity, with qualified water-based formulation output constraining premium-tier availability and supporting margin structures for compliant converters.
For Market Incumbents: Deploy aqueous coating line retrofits to capture California SCAQMD-compliant contract demand before competitor capacity additions saturate the premium tier. Consolidate gravure technician training programs to address workforce scarcity threatening coating line utilization rates. Defensive positioning against emerging Asian converters requires backward integration into oriented polypropylene film substrate production to secure supply continuity. For New Entrants and Emerging Players: China's NMPA GB standard tightening opens a window for water-based acrylic specialists to displace solvent-based incumbents in domestic export corridor supply chains. Target India's BIS-certified tape specification demand among Mumbai and Chennai logistics hubs where compliance documentation creates qualification barriers for unverified imports. Go-to-market execution should anchor on direct technical support bundled with performance certification to bypass established distribution intermediaries. For Investors and Strategic Acquirers: Converter announcements of aqueous coating line commissioning is the leading indicator that premium-tier supply expansion is imminent and margin compression will follow. Long-term viability favors integrated players controlling substrate supply and adhesive formulation chemistry. Acquisition screening should prioritize coating specialists with EPA NESHAP-compliant infrastructure and established direct relationships with consolidated third-party logistics providers. Monitor polypropylene resin price volatility spikes as signals for margin stress among non-integrated converters.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Coating Line Retrofit | California SCAQMD compliance unlocks West Coast fulfillment contract access for water-based acrylic formulations. |
| Backward Integration into Substrate | Zhejiang province biaxial orientation equipment ownership secures polypropylene film supply against logistics disruptions. |
| Direct Mill Relationship Development | Amazon and Walmart captive specification teams in Texas bypass distribution intermediaries for technical support bundling. |
| Cold-Chain Adhesive Certification | Temperature-stable acrylic validation for vaccine distribution penetrates pharmaceutical packaging with bond integrity premiums. |
| Gravure Technician Training Pipeline | Slot-die and direct gravure expertise concentration addresses aging workforce scarcity threatening coating line output. |
Study Parameters
Trade association filings, customs export records, and EPA enforcement databases formed the secondary backbone for supply chain mapping and regulatory compliance tracking. Primary interviews with coating line operators, corrugated box procurement managers, adhesive formulation chemists, and third-party logistics specification directors validated capacity utilization assumptions and pricing dynamics. Bottom-up tape consumption estimates by end-use vertical triangulated against top-down packaging materials demand projections from corrugated industry associations.
Historical trendline analysis of polypropylene resin pricing, coating line investment cycles, and e-commerce parcel throughput informed the projection framework across the analysis window. Segmentation modeling incorporated substrate chemistry, adhesive formulation type, thickness calibration, and end-use vertical demand patterns. CAGR derivation rested on adhesive chemistry transition timelines and regulatory compliance deadline clustering. Forecast inputs included biaxial orientation film capacity expansion announcements and cross-border e-commerce volume trajectories at Shanghai and Shenzhen export hubs.
Caveats apply where NMPA emission limit enforcement intensity, polypropylene feedstock price volatility, or gravure technician labor availability could materially shift the outlook. Forecasts reflect assumptions around aqueous coating line commissioning schedules and buyer specification adoption curves. Practitioners should monitor EPA NESHAP compliance deadline adherence and California SCAQMD penalty actions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Raffia Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Tape Banding Machine Market
Tapes
PVC Tapes Market
Tapes
Global Surface Protection Tapes Market
Tapes
High Bond Tape Market
Tapes
Heat Sealing Tape Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Invisible Tapes Market
Tapes
Global Construction Tape Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Thread Seal Tape Market
Tapes
Acoustic Tape Market
Tapes
Nylon Cable Ties Market
Tapes
Paper Tapes Market
Tapes
Void Pattern Tamper-Evident Tapes Market