
 Metal Recycling Market | 2026-2036
Metal Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Recycling Market Intelligence
The capability gap between integrated steel producers and specialized non-ferrous recyclers is collapsing under pressure from advanced sorting technologies. ArcelorMittal leverages its vast scale in ferrous scrap processing to feed its own electric arc furnaces, controlling input costs. In contrast, Aurubis AG specializes in the complex metallurgical recovery of non-ferrous and precious metals from industrial scrap and e-waste. Sims Metal Management Limited operates a global network connecting diverse collection points with processing facilities.
Metal recycling is the process of recovering scrap metal from end-of-life products or manufacturing waste for use as a secondary raw material. It involves shredding, sorting, and melting to meet purity specifications, such as 99.5% for aluminum, required for industrial remanufacturing. While ferrous metals from construction represent the largest volume, high-value non-ferrous metals from e-waste and packaging dominate revenue streams. High-purity grades are critical for aerospace components, whereas foundries utilize a wider spectrum of semi-refined inputs from scrap dealers.
Government policies are a primary market influence, with frameworks like the EU Green Deal and China's dual carbon goals setting aggressive recycled content targets. In the United States, EPA regulations on waste management and landfill diversion directly support scrap collection. Decisions on investment in advanced sensor-based sorting versus traditional manual methods will define the future cost structure for processors.
Market Dynamics
The central dynamic in the metal recycling market is the collision between stringent circular economy mandates and the high capital investment required for advanced sorting technologies. Governments are setting aggressive recycled content targets, while processors must decide whether to invest in sensor-based systems to meet the necessary purity specifications for industrial remanufacturing.
Growth Catalysts
- Circular Economy Mandates:Regulatory frameworks, including the EU Green Deal and India's Production Linked Incentive (PLI) scheme, compel manufacturers in sectors like automotive and electronics to increase the percentage of recycled materials in their products, creating guaranteed demand for secondary metals.
- Automotive Lightweighting:The automotive industry's push for vehicle efficiency and electrification accelerates demand for lightweight materials, particularly high-purity recycled aluminum, to reduce vehicle mass and improve battery range without compromising structural integrity.
- Advanced Sorting Technology:The deployment of sensor-based sorting technologies such as X-ray fluorescence (XRF) and laser-induced breakdown spectroscopy (LIBS) enables processors to achieve higher purity grades, unlocking access to high-value end markets like aerospace and electronics manufacturing.
Market Restraints
- Input Price Volatility:Scrap metal prices are subject to sharp fluctuations driven by global commodity markets, industrial production levels, and currency exchange rates, creating significant margin pressure and planning uncertainty for recycling processors.
- Complex Alloy Separation:The increasing complexity of alloys used in modern products, especially in electronics and specialty steels, poses significant metallurgical challenges for separation, often requiring energy-intensive processes that limit economic viability.
- Cross-Border Trade Friction:Inconsistent national interpretations and enforcement of international agreements like the Basel Convention on transboundary waste shipments create logistical bottlenecks and compliance risks, hindering the efficient global flow of scrap metal.
Strategic Opportunities
- Battery Metal Recovery:The expanding electric vehicle market creates a substantial opportunity for developing specialized recycling streams focused on recovering critical materials like lithium, cobalt, and nickel from end-of-life EV batteries, a currently underserved segment.
- AI-Powered Robotics:The convergence of artificial intelligence with robotic automation offers the potential to automate the manual sorting and disassembly of complex products like e-waste, improving both safety and recovery rates for valuable non-ferrous metals.
- Infrastructure in Southeast Asia:Rapid industrialization in Southeast Asian nations presents a significant opportunity for investment in modern, localized recycling infrastructure to process domestic scrap and meet the growing regional demand for secondary raw materials.
Industry Challenges
- High Capital Expenditure:The acquisition and integration of advanced processing equipment, from high-capacity shredders to sophisticated sensor-based sorting systems, require substantial upfront capital investment, posing a barrier to entry for smaller operators.
- Specialized Talent Scarcity:Effective operation of modern recycling facilities demands a new set of skills, including metallurgists, data scientists for process optimization, and technicians trained in robotics, creating a talent gap in the industry.
- Content Verification and Traceability:Meeting stringent recycled content mandates requires robust chain-of-custody and verification systems, adding a layer of administrative complexity and cost for recyclers to prove material origin and purity to downstream customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Recycling Market |
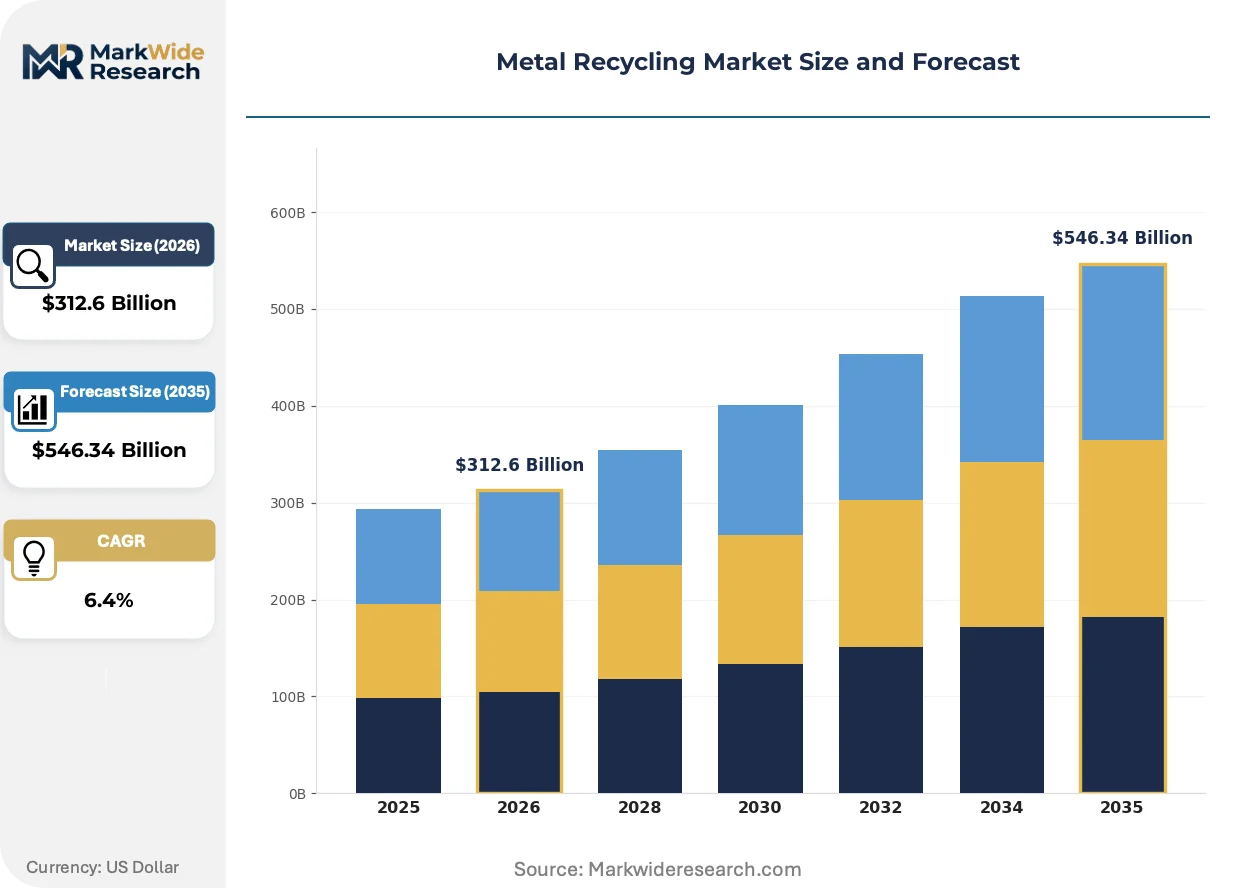
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $546.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrous Metals, Non-Ferrous Metals, Industrial Scrap, E-Waste, Precious Metals Grade: Low Purity, Medium Purity, High Purity, Refined Metals, Semi-Refined Metals Application: Construction, Automotive Components, Electronics Manufacturing, Aerospace Components, Packaging End User: Manufacturers, Fabricators, Foundries, Metal Traders, Scrap Dealers |
| Companies Covered | ArcelorMittal, Nucor Corporation, Commercial Metals Company, Sims Metal Management Limited, Aurubis AG, Dowa Holdings Co., Ltd., Tata Steel, European Metal Recycling Limited, Radius Recycling, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Recycling Market Strategic Shifts & Innovations
Precision is displacing scale as the primary value driver in metal recycling. The market is shifting from a focus on bulk ferrous recovery toward the high-fidelity separation of complex non-ferrous and precious metals, enabled by new sensing technologies and demanded by circular economy policies.
Technology-Driven Purity Gains
Advanced analytical technologies like Laser-Induced Breakdown Spectroscopy (LIBS) provide real-time, in-line identification of specific metal alloys. High-volume aluminum and copper recyclers are adopting these systems to segregate scrap with extreme precision for demanding end-uses. This technology is miniaturizing the quality control lab, moving its function directly onto the sorting line to enable granular classification at processing speeds previously unattainable.
Regulatory Mandates for Recycled Content
Regulatory frameworks are becoming a primary market force, directly influencing material sourcing. China's "dual carbon" objectives and updated GB standards for recycled steel and aluminum are compelling domestic industries to integrate secondary metals. This affects heavy industries the most, forcing steel mills and aluminum smelters to reconfigure supply chains and invest in technologies compatible with higher scrap utilization rates.
Shift to Closed-Loop Supply Agreements
Downstream consumers are moving away from transactional scrap purchasing on the spot market. They are instead establishing long-term, closed-loop tolling agreements directly with specialized recyclers to secure a consistent supply of specific-grade secondary materials. This trend disrupts the role of traditional scrap aggregators and is most visible in the European automotive sector, where manufacturers seek to guarantee access to low-carbon aluminum for vehicle production.
Metal Recycling Market Segmentation
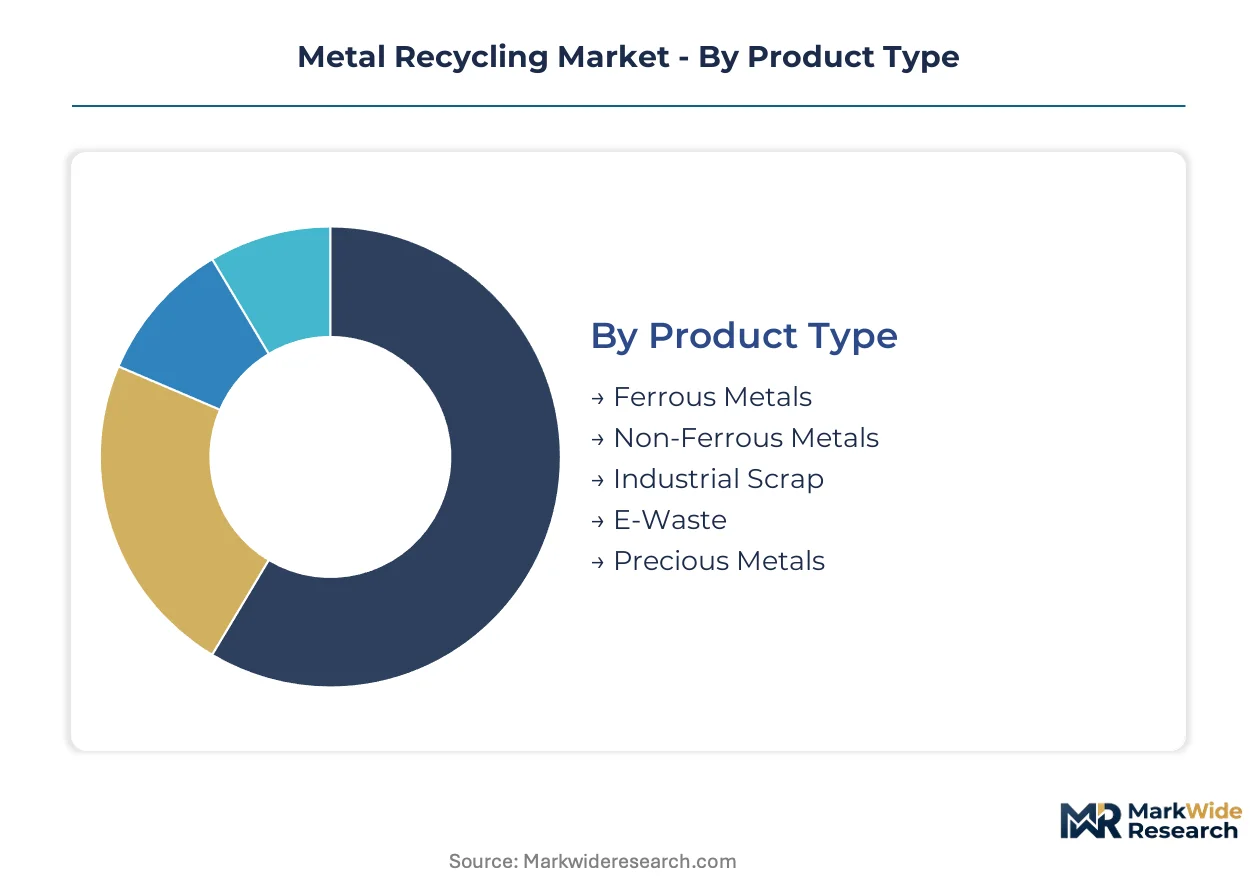
Metal recycling market segmentation illuminates the diverse material streams and processing requirements driving industry value. Understanding these categories helps stakeholders align investment with demand for specific secondary raw materials. Each segment presents unique challenges and opportunities for resource recovery.
Product Type:
The metal recycling market processes materials through distinct collection and refining channels based on their composition and value. Each product type follows a specialized recovery pathway to meet purity standards for industrial reuse.
- Non-Ferrous Metals:These include aluminum, copper, and zinc, recovered for their high economic value and excellent recyclability. Demand is accelerating from the automotive industry in Germany for lightweight components and in China for electrical infrastructure.
- E-Waste:Consists of discarded electronic devices containing complex alloys and critical minerals, requiring advanced disassembly and metallurgical separation. The EU Green Deal mandates drive recovery efforts in countries like France and the Netherlands for circular electronics.
- Ferrous Metals:Comprise iron and steel scrap, primarily sourced from construction and manufacturing, forming the largest volume segment for bulk recycling.
- Industrial Scrap:Refers to waste generated during manufacturing processes, such as stamping remnants, offering high-purity, traceable input for remelting.
- Precious Metals:Include gold, silver, platinum, and palladium, primarily recovered from e-waste and industrial catalysts due to their extreme value.
Ferrous Metals dominates installed base. Non-Ferrous Metals is where expansion concentrates.
Grade:
Metal grades dictate processing costs and the value realized from secondary raw materials. Achieving higher purity often involves more capital-intensive sorting and refining technologies.
- High Purity:These materials, often exceeding 99% purity, are critical for sensitive applications like aerospace components and advanced electronics manufacturing. Demand in the United States aerospace sector requires stringent quality control and advanced sensor-based sorting.
- Refined Metals:Metals purified to primary-grade specifications, often through electrolytic processes or vacuum melting, commanding premium prices due to their direct substitutability for virgin materials. The automotive industry in Japan increasingly seeks these for critical engine and battery components.
- Low Purity:Represents mixed scrap or contaminated materials suitable for less demanding applications like counterweights or general construction fillers.
- Medium Purity:Offers a balance between processing cost and material quality, typically used in standard casting applications or less critical structural components.
- Semi-Refined Metals:Partially processed scrap that has undergone initial sorting and shredding but requires further purification before specific industrial use.
The pursuit of higher-grade recycled metals is a central theme, with advanced sorting technologies enabling access to premium markets.
Application:
End-use applications define the required specifications and volumes for recycled metals, influencing processing methods and quality control. Each sector presents unique demands for secondary raw materials.
- Automotive Components:This segment demands high-purity, lightweight recycled aluminum and steel for vehicle bodies, engine parts, and battery casings. Regulatory pressure from the EU Green Deal drives demand for recycled content in German and French car manufacturing.
- Aerospace Components:Requires extremely high-purity aluminum, titanium, and nickel alloys, with stringent traceability and mechanical property requirements for structural integrity. Manufacturers in the United States and the United Kingdom prioritize certified recycled inputs to meet sustainability goals.
- Construction:Represents the largest volume consumer of ferrous scrap for rebar, structural steel, and other building materials, providing a consistent demand base.
- Electronics Manufacturing:Utilizes recycled copper, aluminum, and precious metals for circuit boards, wiring, and casings, driven by circular economy mandates in countries like South Korea.
- Packaging:Primarily consumes recycled aluminum and steel for beverage cans and food containers, benefiting from established collection systems and consumer recycling habits.
While construction remains a volume anchor, specialized applications like automotive and aerospace drive innovation in purity and material performance.
End User:
Different end-user types interact with the recycling value chain at various stages, from initial collection to final remanufacturing. Their specific needs shape the demand for processed scrap.
- Manufacturers:Large-scale industrial producers, including steel mills and aluminum smelters, integrate recycled metals directly into their primary production processes. China's dual carbon goals compel domestic manufacturers to increase scrap utilization rates.
- Foundries:These facilities melt and cast metals into specific shapes, utilizing a wide range of semi-refined and refined scrap inputs depending on the final product's specifications. Foundries in India are increasingly sourcing local scrap to meet infrastructure project demand.
- Fabricators:Businesses that cut, bend, and assemble metal products, generating industrial scrap which then re-enters the recycling stream.
- Metal Traders:Intermediaries who buy and sell processed or unprocessed scrap, facilitating its movement between collection points and industrial users across regions.
- Scrap Dealers:Local entities that collect, sort, and initially process scrap metal from various sources before selling it to larger processors or traders.
Direct consumers like manufacturers and foundries are increasingly seeking long-term supply agreements to secure high-quality recycled inputs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the metal recycling market exhibits regional asymmetry, with Asian nations consolidating supply infrastructure while European markets face intense demand-side regulatory pressure. This dynamic shapes investment priorities and material flow across global supply chains. Regional policies and industrial demand significantly influence the type and volume of metals recycled.
China
China's robust industrialization drives demand for recycled steel and aluminum, supported by significant domestic scrap processing. China's "dual carbon" objectives and updated GB standards compel industries to integrate secondary metals. Heavy industries in the Yangtze River Delta reconfigure supply chains and invest in higher scrap utilization rates.
Germany
German automotive manufacturers increasingly seek high-purity recycled aluminum for lightweight components and EV battery casings. The EU Green Deal mandates drive demand for recycled content in German car manufacturing. European automotive companies in Bavaria are establishing long-term, closed-loop tolling agreements with specialized recyclers to secure consistent supply.
United States
The United States aerospace sector requires extremely high-purity aluminum and titanium alloys for critical components. EPA regulations on waste management and landfill diversion directly support scrap collection infrastructure. Manufacturers in the Pacific Northwest prioritize certified recycled inputs to meet stringent quality control and sustainability goals.
Japan
Japanese automotive manufacturers increasingly seek refined metals purified to primary-grade specifications for critical engine and battery components. METI initiatives encourage resource efficiency and circular economy practices within key industries. The automotive industry in the Chubu region drives demand for these premium recycled inputs.
India
India's rapid infrastructure development and automotive sector expansion generate substantial demand for ferrous and non-ferrous recycled metals. India's PLI scheme compels manufacturers to increase recycled materials in their products. Foundries in Maharashtra increasingly source local scrap to meet growing infrastructure project demands.
Metal Recycling Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the metal recycling market. The industry exhibits a tiered structure, ranging from global integrated steel producers to specialized non-ferrous recyclers and local scrap dealers. Three strategic archetypes emerge: large-scale ferrous processors, precision non-ferrous specialists, and regional aggregators. Dominant competitive moves include strategic partnerships for material sourcing and significant capacity expansion in advanced sorting technologies.
Specialists in large-scale ferrous scrap processing, such as ArcelorMittal, leverage vast operational scale to control input costs for their own electric arc furnaces. Aurubis AG, a German-based company, exemplifies expertise in the complex metallurgical recovery of non-ferrous and precious metals from industrial scrap and e-waste. Meanwhile, Sims Metal Management Limited, a global entity, occupies a position as a comprehensive network operator, connecting diverse collection points with advanced processing facilities worldwide. These distinct approaches highlight the varied strategies for value capture across different metal types and processing complexities.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nucor Corporation |
| Commercial Metals Company |
| Sims Metal Management Limited |
| Aurubis AG |
| Dowa Holdings Co., Ltd. |
| Tata Steel |
| European Metal Recycling Limited |
| Radius Recycling, Inc. |
| Others |
Cost & Logistics Intelligence
Long-term closed-loop tolling agreements between specialized recyclers and downstream manufacturers lock in both supply access and price visibility for high-purity recycled metals. This model mitigates input price volatility for automotive manufacturers in Germany.
Pricing Analysis
Configured-to-order pricing for specialized high-purity alloys drives premium rates, contrasting with standard pricing for bulk ferrous scrap. The dominant pricing structure remains commodity spot pricing for most raw scrap, transitioning to contract-based long-term offtake for refined materials. Price differentiation stems from purity specifications required for aerospace components and the certification level for automotive applications. Pricing softness reflects global industrial production levels, impacting bulk ferrous volumes. Foundries sourcing semi-refined inputs exhibit higher price sensitivity compared to aerospace manufacturers requiring ultra-high purity.
Supply Chain Analysis
Inventory levels for high-purity non-ferrous metals are tightly managed due to specific application demands and processing lead times. Geographic supply concentration for scrap collection and initial processing centers in China and Southeast Asia. Raw material dependencies include end-of-life vehicles for aluminum and copper, and e-waste for precious metals. Cross-border trade friction, driven by inconsistent national interpretations of the Basel Convention, presents a structural supply chain risk. Distribution runs through a network of local scrap dealers feeding into larger processors and metal traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal recycling market is undergoing a buyer-power shift, driven by the consolidation of large automotive and electronics manufacturers seeking secure, high-purity recycled content. This shift compels recyclers to adapt their strategic focus.
For Market Incumbents: Fortify processing capabilities in advanced sorting technologies like LIBS to meet stringent purity specifications for aerospace and automotive clients. This defends against margin pressure from volatile input prices and ensures consistent supply for long-term contracts. Leverage existing scale in ferrous scrap processing to cross-subsidize investment in non-ferrous recovery infrastructure within China and India.
For New Entrants and Emerging Players: Differentiate on specialized recovery streams for critical battery metals from end-of-life EV batteries, an underserved segment. Target the rapidly industrializing Southeast Asian nations, where localized recycling infrastructure is underdeveloped. A go-to-market angle involves offering AI-powered robotic disassembly services for complex e-waste, improving recovery rates and safety.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized non-ferrous recyclers with long-term, closed-loop agreements with industrial partners. Over a 5-10 year window, the market favors entities capable of consistently supplying high-purity, traceable materials. Target acquisition archetype involves technology-driven processors excelling in e-waste or battery metal recovery. A signal to watch is the increasing enforcement of recycled content mandates in sectors like electronics manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing advanced sorting capacity in China meets growing industrial demand for secondary raw materials. |
| Green Manufacturing Transition | Implementing energy-efficient melting processes reduces carbon footprint for steel producers. |
| Long-term Supply Agreement | Securing consistent recycled aluminum supply stabilizes input costs for German automotive manufacturers. |
| Joint Venture | Partnering for battery metal recovery addresses the underserved electric vehicle market segment. |
| Product Launch | Introducing new high-purity alloy grades targets specialized aerospace component applications. |
Research Approach
A standing panel of metallurgists, data scientists, automotive procurement leads, and regulatory affairs specialists provided ongoing calibration for primary insights and secondary data validation. This analysis combined in-depth interviews with industry stakeholders across Europe, Asia, and North America. Secondary data sources included government reports from the EPA and METI, industrial association publications, and company financial filings. Bottom-up market sizing was triangulated with top-down validation.
Outputs were validated against external benchmarks from organizations like the World Steel Association and the International Aluminium Institute, ensuring consistency across the analysis window. The analytical framework modeled market dynamics across product type, grade, application, and end-user, with an additional dimension for regional regulatory impact. Compound Annual Growth Rates were derived from historical trends and projected demand from electrification and circular economy mandates. Key forecast inputs included projected EV battery production and construction material demand in India.
Forecasts assume regulatory continuity in the EU Green Deal and China's dual carbon goals; material policy shifts would require re-modeling. Geopolitical tensions affecting global trade and unforeseen technological breakthroughs in material science represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminium Collars Market
Metals
Global Bronze Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
North America Electrical Steel Market
Metals
Electrolytic Iron Market
Metals
Cobalt Market
Metals
Japan Aluminium Powder Market
Metals
High Purity Boron Market
Metals
Copper and Brass Flat Products Market
Metals
South America Metal Finishing Market
Metals
Colloidal Metal Particles Market
Metals
Copper Smelting Market
Metals
Metal Forging Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Global Nickel Alloy Welding Consumables Market