
 Pump Casing Materials Market | 2026-2036
Pump Casing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Pump Casing Materials Market Analytics
Aftermarket service revenue is reconfiguring margin distribution across the pump casing value chain. KSB SE & Co. KGaA leverages its global service network to capture recurring overhaul contracts. Flowserve Corporation anchors its profitability through spare parts logistics and field engineering capabilities. Sulzer Ltd. specializes in advanced coating technologies that extend casing life cycles in abrasive environments.
Pump casing materials encompass the structural housings that contain pressurized fluids, typically specified by alloy composition, wall thickness tolerance, and corrosion resistance ratings measured in mils per year penetration. These components protect internal impellers and shafts while maintaining hydraulic efficiency across temperature ranges from minus forty to six hundred degrees Celsius. Stainless steel grades dominate high-pressure chemical applications where chloride exposure exceeds cast iron tolerances, while plastic composites represent the fastest-expanding category in residential water systems due to weight reduction and electrochemical inertness. The oil and gas end-user segment retains the deepest margin pools through super-duplex and nickel-alloy specifications for sour service environments.
The EPA enforces corrosion resistance benchmarks under the Safe Drinking Water Act that directly specify acceptable casing materials for municipal pumping stations. API standards for oilfield equipment and ISO 5199 chemical pump specifications further constrain material selection and testing protocols across North American and European supply chains. Stakeholders must monitor evolving PFAS restrictions and embodied carbon disclosure requirements that threaten plastic casing acceptance in European water infrastructure procurement.
Market Dynamics
Stainless steel substitution is accelerating across municipal water infrastructure as corrosion-resistant specifications tighten, compressing cast iron's historical dominance in utility procurement while redistributing margin pools toward alloy suppliers with certified metallurgical capabilities.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:Municipal utilities in the United States face mandated material upgrades for potable water systems, forcing wholesale casing replacements and expanding addressable demand for certified stainless grades.
- Coastal Manufacturing Cluster Concentration:China's Jiangsu and Zhejiang provinces are consolidating pump assembly capacity, creating localized procurement gravity that favors regional casing suppliers with just-in-time delivery networks.
- Super-Duplex Alloy Adoption:Sour service environments in oil and gas extraction are specifying nickel-alloy casings for hydrogen sulfide resistance, opening premium specification tiers unavailable to standard carbon steel producers.
Market Restraints
- Nickel Price Volatility:Stainless steel and super-duplex alloy production depends on nickel cathode inputs whose price swings compress foundry margins and destabilize long-term contract pricing.
- European PFAS Restrictions:ECHA regulatory frameworks are threatening polymer composite acceptance in water infrastructure, creating compliance uncertainty for plastic casing manufacturers targeting municipal buyers.
- Foundry Capacity Concentration:Specialized sand-casting operations for large-diameter casings concentrate in Germany and India, creating single-source vulnerability for critical pump OEMs.
Strategic Opportunities
- Desalination Plant Rollouts:Saudi Arabia and the UAE are expanding seawater reverse osmosis capacity, creating demand for titanium-clad and super-duplex casings resistant to chloride attack at high pressures.
- Embodied Carbon Disclosure Mandates:The EU Green Deal's procurement rules are rewarding casing suppliers with verified lifecycle emissions data, creating first-mover advantage for electric-arc furnace producers.
- Digital Twin Integration:Predictive maintenance platforms are converging with casing sensor networks, enabling condition-based overhaul contracts that extend replacement cycles and capture aftermarket value.
Industry Challenges
- Welding Inspector Certification Bottlenecks:ASME Section IX qualified welders for high-pressure alloy casings are in short supply across North American fabrication shops, extending lead times for critical orders.
- API 610 Compliance Timelines:Oil and gas purchasers require third-party witness testing for centrifugal pump casings, creating 12-16 week certification delays that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pump Casing Materials Market |
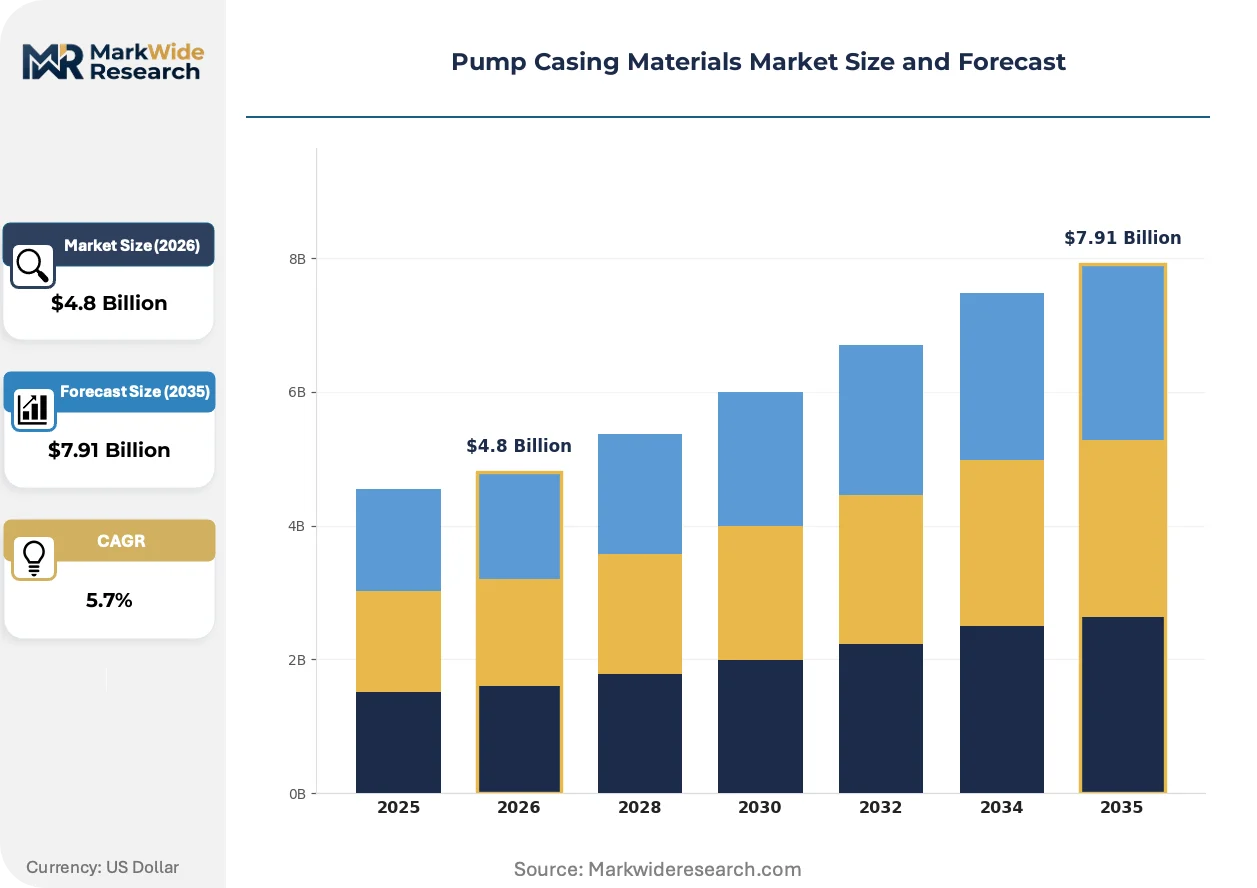
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Stainless Steel, Cast Iron, Plastic, Aluminum End User: Oil & Gas, Water Treatment, Chemical Processing, Marine Application: Industrial Pumps, Submersible Pumps, Centrifugal Pumps, Positive Displacement Pumps Size: Small Pumps, Medium Pumps, Large Pumps, Specialty Pumps |
| Companies Covered | CP Pumpen AG, HMS Group, Zibo Qingdong Machinery Manufacturing Co., Ltd, KSB SE & Co. KGaA, Wilo SE, Flowserve Corporation, Sulzer Ltd., Grundfos Holding A/S, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pump Casing Materials Market Evolving Landscape
Material science advances and digital manufacturing are compressing development cycles for corrosion-resistant casings while regulatory disclosure requirements reshape supplier qualification protocols across water and energy infrastructure.
Additive manufacturing of nickel-alloy casings is migrating from prototyping to production for complex geometries in chemical processing. Specialty pump OEMs are adopting directed energy deposition for impeller housings with internal cooling channels. This technology is migrating from aerospace-qualified suppliers toward mid-tier foundries seeking differentiation in custom orders.
REACH authorization procedures are restricting chromium(VI) surface treatments historically used for cast iron corrosion protection. European casing manufacturers are pivoting to trivalent chrome and ceramic coating alternatives. Water utilities in Germany and France are now specifying coating chemistries in tender documents, disqualifying legacy surface preparation methods.
Buyers are unbundling aftermarket service contracts from initial equipment purchases. Municipal water authorities in Australia and Canada are separating casing procurement from installation and overhaul agreements. This pattern is most visible in large-diameter vertical turbine applications where specialized diving contractors now handle wet-pit installations independent of casing suppliers.
Pump Casing Materials Market Segmentation
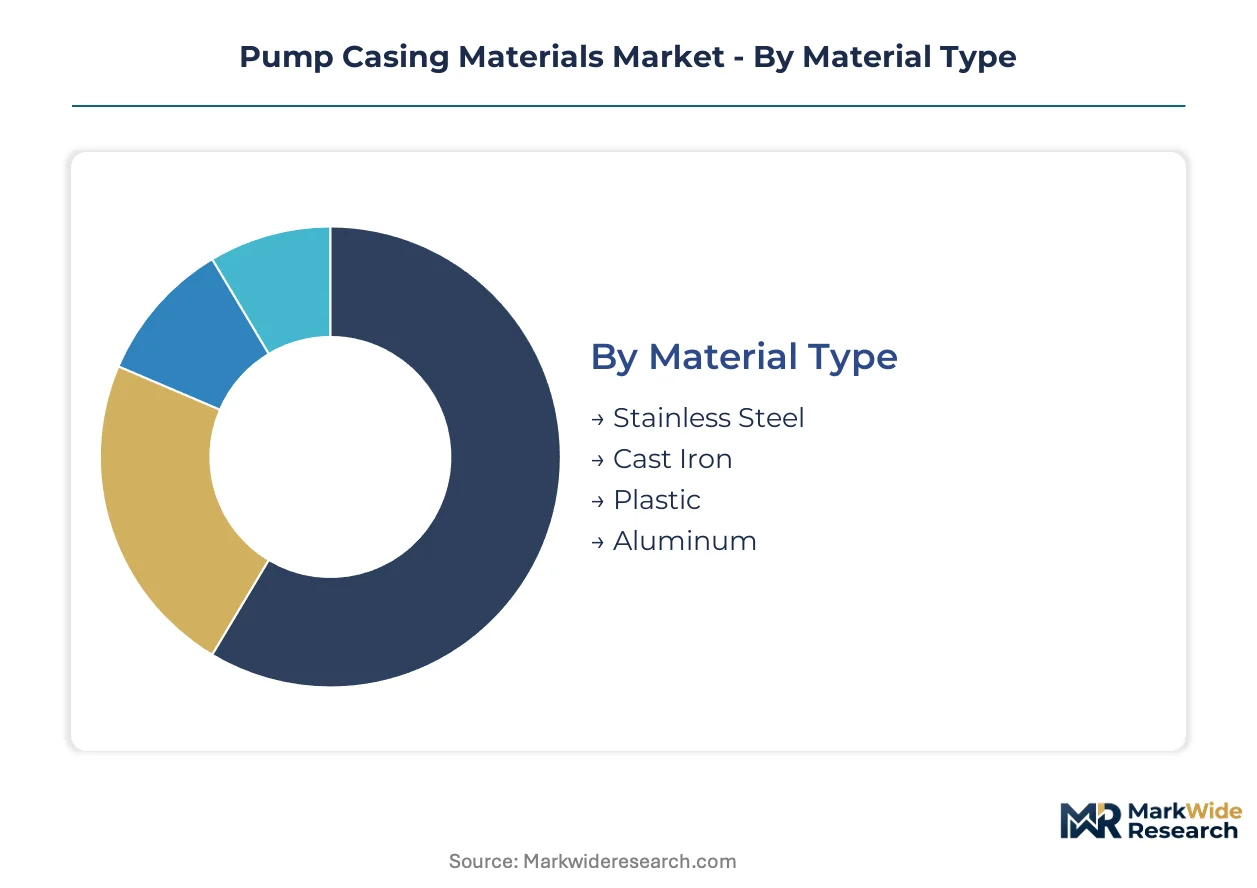
Pump casing material selection directly determines corrosion tolerance, pressure ratings, and lifecycle economics across divergent operating environments. Specification patterns fragment sharply between municipal infrastructure priorities and hydrocarbon extraction demands, creating distinct procurement channels with incompatible certification requirements.
Material Type:
Material selection spans corrosion resistance ratings, thermal operating windows, and embodied carbon profiles that reshape tender qualification across water and energy infrastructure.
- Stainless Steel:Austenitic and duplex grades deliver chloride resistance below 0.1 mils per year penetration in potable water systems. EPA Lead and Copper Rule revisions in the United States are forcing wholesale substitution for legacy cast iron installations in municipal pumping stations.
- Cast Iron:Gray and ductile iron formulations retain cost advantage in low-pressure HVAC and drainage applications where corrosion exposure remains minimal. China's Jiangsu province foundries dominate volume production for Asian residential water system OEMs.
- Plastic:Glass-reinforced polypropylene and PVDF housings serve residential water systems and semiconductor chemical delivery where electrochemical inertness outweighs pressure limitations.
- Aluminum:Die-cast alloys address weight-sensitive aerospace fuel transfer and portable dewatering equipment with moderate corrosion exposure.
The dominant share belongs to Stainless Steel, while Plastic is closing the gap fastest.
End User:
End-use concentration determines specification stringency, with sour service oilfield environments and pharmaceutical water systems imposing the most restrictive metallurgical protocols.
- Oil & Gas:Super-duplex and nickel-alloy casings withstand hydrogen sulfide partial pressures exceeding 0.05 psi in sour gas extraction. Saudi Aramco and ADNOC procurement standards mandate third-party witness testing for all high-pressure centrifugal pump housings.
- Water Treatment:Municipal utilities specify 316L stainless steel for potable systems and titanium-clad duplex for seawater reverse osmosis intakes. German water authorities now require REACH-compliant coating chemistries in tender documents.
- Chemical Processing:Hastelloy and Alloy 20 housings resist sulfuric acid concentrations above 90 percent in fertilizer and battery acid manufacturing.
- Marine:Bronze and naval brass casings serve saltwater bilge and ballast applications where galvanic compatibility with hull structures takes priority.
Oil & Gas commands the deepest margin pools, yet Water Treatment is expanding addressable demand most rapidly through regulatory-mandated infrastructure replacement.
Application:
Application architecture dictates wall thickness tolerance, internal pressure rating, and sensor integration capability for predictive maintenance platforms.
- Industrial Pumps:Heavy-walled carbon steel and alloy casings handle process fluids above 200 bar in refinery and petrochemical circulation duty.
- Submersible Pumps:Stainless steel motor housings and double-mechanical seal chambers operate in deep well and wastewater sump installations.
- Centrifugal Pumps:Volute casings with precisely cast internal passages optimize hydraulic efficiency across API 610 oilfield and ISO 5199 chemical process specifications.
- Positive Displacement Pumps:Rigid housings contain reciprocating or rotary element loads in high-viscosity polymer and food processing applications.
Centrifugal designs occupy the largest installed base, though Submersible configurations are gaining share fastest through municipal wastewater infrastructure investment.
Size:
Size classification determines foundry capability requirements, with large-diameter sand castings concentrating in specialized German and Indian production facilities.
- Small Pumps:Investment-cast stainless steel housings below 150 mm discharge diameter serve residential pressure boosting and medical device applications.
- Medium Pumps:Horizontal split-case and vertical inline configurations between 150-400 mm dominate commercial building HVAC and agricultural irrigation procurement.
- Large Pumps:Custom-engineered volutes above 400 mm require dedicated pattern equipment and ASME Section IX qualified welding for critical power generation and flood control installations.
- Specialty Pumps:Cryogenic LNG transfer and molten salt solar thermal systems demand exotic material specifications outside standard product ranges.
Medium Pumps generate the highest unit volume, while Specialty Pumps command the steepest premium escalation per kilogram of finished casing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for pump casing materials diverge sharply by geography. Municipal water utilities in the United States prioritize corrosion-resistant stainless grades under tightening EPA mandates, while oilfield operators in Saudi Arabia specify super-duplex alloys for sour service extraction. Chinese coastal manufacturing clusters drive volume procurement of cast iron and plastic composites for export-oriented pump assembly.
United States
Municipal water authorities are replacing legacy cast iron installations with 316L stainless steel casings. The EPA's Lead and Copper Rule revisions mandate material upgrades for potable water systems, forcing wholesale procurement shifts. Houston-area oilfield service companies anchor demand for high-pressure alloy specifications in Permian Basin extraction operations.
Germany
Industrial pump OEMs specify precision-cast stainless housings for chemical process applications. ECHA restrictions on chromium(VI) surface treatments are disqualifying legacy coating methods from municipal tender documents. Foundries in North Rhine-Westphalia concentrate specialized sand-casting capacity for large-diameter power generation casings.
China
Jiangsu and Zhejiang province manufacturers are consolidating pump assembly capacity, creating localized procurement gravity for regional casing suppliers. The country's dual carbon goals are pressuring foundries to document embodied carbon profiles for EU-bound exports. Qingdao port clusters handle titanium-clad duplex casings for desalination plant re-exports to Middle Eastern markets.
Saudi Arabia
Seawater reverse osmosis expansion is driving demand for super-duplex and titanium-clad casings resistant to chloride attack. Saudi Aramco procurement standards mandate third-party witness testing for all high-pressure centrifugal pump housings. Jubail Industrial City hosts concentrated fabrication capacity for sour service specifications serving Eastern Province oilfields.
India
Agricultural irrigation and municipal wastewater investments are expanding addressable demand for medium-duty cast iron and stainless configurations. BIS certification requirements are tightening material traceability for government-funded infrastructure projects. Gujarat foundry clusters in Rajkot and Ahmedabad supply horizontal split-case casings for South Asian irrigation OEMs.
Pump Casing Materials Market Competitive Landscape
Capability concentration sits with specialized alloy foundries holding ASME Section IX welding certifications; scale advantage sits with integrated pump OEMs with captive casting operations and global service networks. The market structures around three tiers: premium alloy specialists serving oilfield and chemical process specifications; mid-scale stainless steel fabricators supplying municipal water infrastructure; and high-volume cast iron producers for residential and agricultural applications. Dominant competitive moves include backward integration into foundry capacity and geographic expansion through regional service hub establishment.
Within the premium-tier alloy segment, CP Pumpen AG and Sulzer Ltd. occupy positions defined by corrosion-resistant specification expertise. KSB SE & Co. KGaA anchors the integrated OEM tier with global service network coverage. Chinese fabricators including Zibo Qingdong Machinery Manufacturing Co., Ltd. represent the scale-driven export manufacturing archetype serving regional pump assembly clusters.
| Leading Market Players |
|---|
| CP Pumpen AG |
| HMS Group |
| Zibo Qingdong Machinery Manufacturing Co., Ltd |
| KSB SE & Co. KGaA |
| Wilo SE |
| Flowserve Corporation |
| Sulzer Ltd. |
| Grundfos Holding A/S |
| Xylem Inc. |
| Others |
Value Network & Pricing Analysis
Jiangsu province foundry clusters anchor global cast iron casing supply, with capacity utilization swings in Taizhou and Changzhou directly transmitting to spot pricing volatility for municipal water OEMs. Their dominance in medium-duty horizontal split-case production creates asymmetric leverage over buyers lacking alternative sourcing for just-in-time delivery networks.
Pricing Analysis
Long-term offtake contracts dominate procurement for oilfield super-duplex specifications, while spot markets govern cast iron transactions for agricultural irrigation. Price differentiation hinges on ASME Section IX welding certification tiers and nickel alloy grade purity. Cost compression in standard stainless grades is intensifying because Chinese electric-arc furnace capacity is expanding faster than European demand. Municipal utilities exhibit highest price sensitivity due to fixed-budget procurement cycles, whereas Saudi Aramco and ADNOC tolerate premium escalation for sour service compliance.
Supply Chain Analysis
Specialized sand-casting capacity concentrates in German North Rhine-Westphalia operations and Gujarat's Rajkot-Ahmedabad corridor, with both regions feeding global pump OEM assembly lines. Raw material flows draw from Indonesian nickel laterite, South African ferrochrome, and Australian titanium sponge. Single-source vulnerability pervades large-diameter volute production above 400 mm discharge. Distribution runs through captive foundry networks for integrated OEMs and third-party logistics hubs for independent fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration is transforming pump casing procurement into a platform-economics inflection, where sensor-enabled condition monitoring creates recurring revenue attachment points that decouple supplier economics from pure hardware margins.
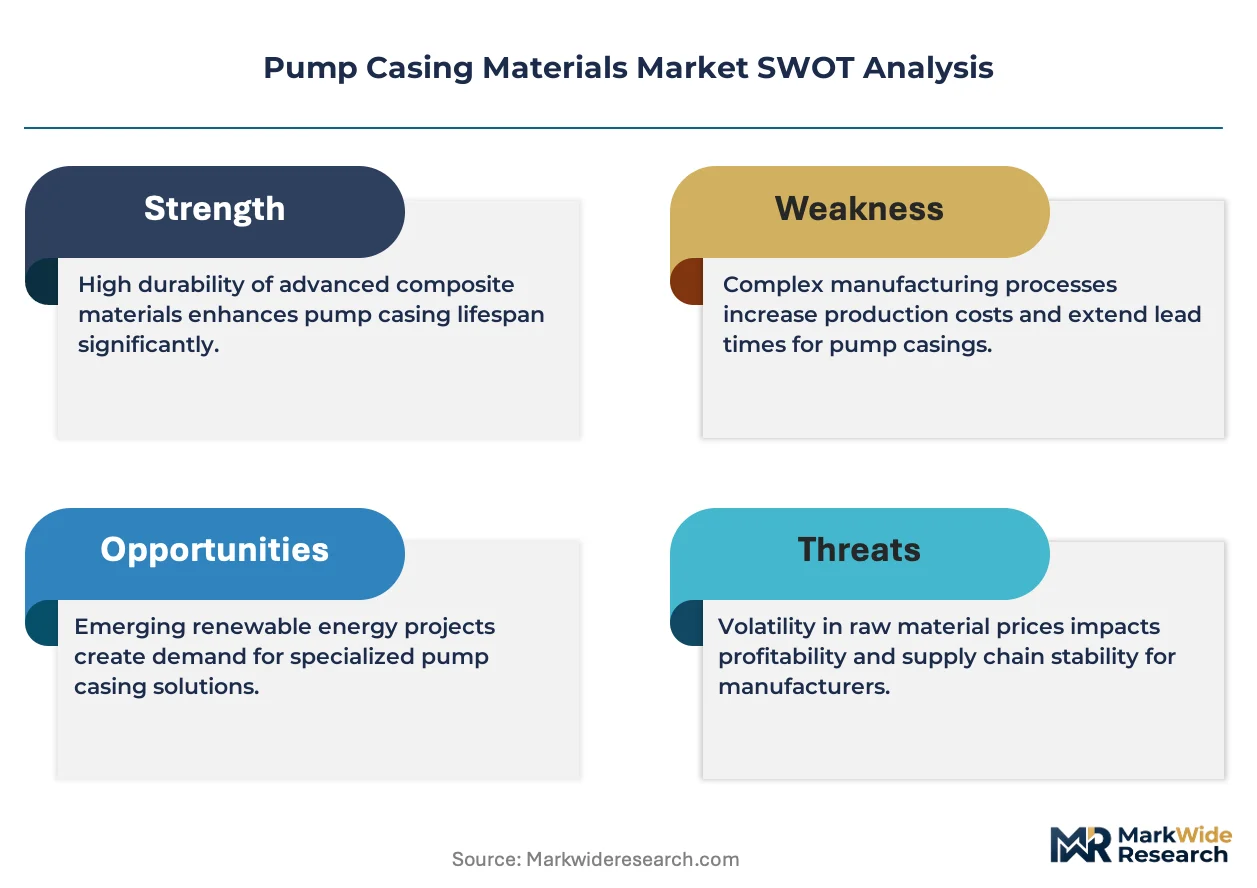
For Market Incumbents: Pre-empt margin erosion from Chinese stainless steel fabricators by securing captive titanium-clad capacity for desalination specifications. Lock in ASME Section IX welding inspector pipelines through community college partnerships in Houston and Jubail. Defend against polymer composite substitution by documenting REACH-compliant coating chemistries ahead of ECHA enforcement timelines. For New Entrants and Emerging Players: Build out additive manufacturing capabilities for nickel-alloy impeller housings with internal cooling channels, targeting chemical process OEMs seeking geometric complexity unavailable to sand-casting. White-space concentration sits in Australian municipal water authorities unbundling installation from procurement. Lead with field engineering partnerships rather than foundry ownership to bypass capital intensity barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA Lead and Copper Rule revisions and EU embodied carbon mandates are structurally expanding addressable demand for certified metallurgical suppliers. Target acquisition archetypes are mid-scale stainless fabricators with existing municipal utility relationships and unexploited service contract potential. Monitor nickel cathode price volatility as the inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Foundry Capacity | Secures super-duplex supply certainty for Permian Basin sour service specifications. |
| Digital Twin Platform Integration | Enables condition-based overhaul contracts extending replacement cycles for Saudi Aramco. |
| REACH-Compliant Coating Chemistry Certification | Qualifies legacy cast iron for German municipal tender documents under ECHA restrictions. |
| Electric-Arc Furnace Carbon Disclosure Verification | Captures EU Green Deal procurement preference for Jiangsu exports to European water utilities. |
| ASME Section IX Welding Inspector Pipeline Development | Resolves certification bottlenecks constraining North American high-pressure alloy lead times. |
Research Methodology
The analysis maps stainless steel grades, cast iron formulations, plastic composites, and super-duplex alloys, each validated through plant managers at foundry operations, procurement leads at pump OEMs, aftermarket service heads, and municipal utility engineering directors. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs trade data, API certification registries, and EPA enforcement databases. Bottom-up capacity assessments triangulated against top-down end-use demand modeling across water treatment, oil and gas, and chemical processing segments.
Assumptions held fixed include regulatory enforcement timelines for EPA Lead and Copper Rule revisions and ECHA PFAS restriction implementation, while nickel price trajectories and Chinese dual carbon policy stringency were varied across sensitivity bands. The projection horizon spans material substitution rates, foundry capacity expansion, and aftermarket service penetration by segment. CAGR derivation incorporated alloy-grade demand elasticity, regional infrastructure investment cycles, and certification compliance cost pass-through. Industry-specific inputs included desalination plant development pipelines and sour service well completion counts.
Stress conditions across nickel cathode price spikes, ECHA coating chemistry bans, and ASME welding inspector supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including foundry capacity concentration in Germany and India, API 610 certification delays, and European plastic casing acceptance uncertainty. Quarterly review of nickel LME pricing, EPA enforcement action filings, and Saudi Aramco procurement standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Silver-Platinum Paste Market
Metals
Zirconium Market
Metals
Metal Powder Market
Metals
Global Mercury Market
Metals
Global Copper Sputtering Target Market
Metals
Global Flat Carbon Steel Market
Metals
Copper Clad Aluminum Wire Market
Metals
Carbotanium Market
Metals
Base Metals Market
Metals
Battery Metals Market
Metals
Stainless Steel Sheet Market
Metals
Niobium Market
Metals
Metal Forging Parts Market
Metals
High Purity Iron Powder Market
Metals
Bismuth Market
Metals
High Purity Pig Iron Market